
 Italy Data Center Construction Market | 2026-2036
Italy Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Construction Market Insights
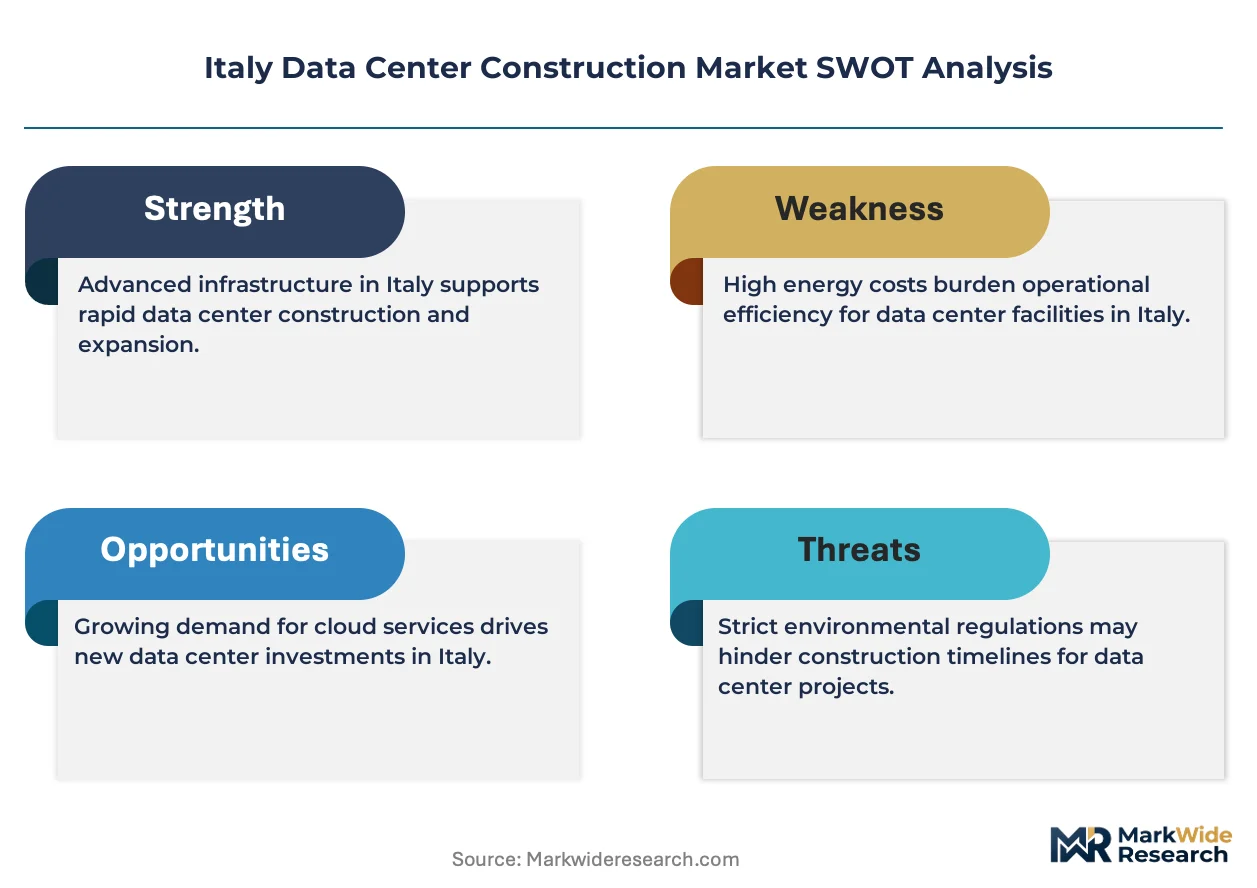
ISO 50001 energy management certification is unwinding the competitive field for data center builders in Italy, raising barriers for contractors without demonstrated energy efficiency credentials. AECOM leverages its integrated design-build capabilities to capture hyperscale contracts across Lombardy. Arup Group Limited anchors its position through advanced thermal engineering for high-density computing environments. Eiffage competes aggressively on civil infrastructure speed, shortening shell-and-core delivery timelines for colocation clients.
Italy data center construction encompasses the full engineering, procurement, and construction of facilities housing servers, storage, and networking equipment, with power densities routinely exceeding 15 kW per rack and precision cooling maintaining temperatures within ±1°C. These facilities serve as critical infrastructure for digital service continuity across financial services, cloud platforms, and public administration. Hyperscale deployments command the largest capital allocations, while edge facilities represent the fastest-expanding footprint as latency-sensitive applications proliferate. Cooling systems absorb disproportionate engineering attention due to Italy's rising ambient temperature profiles and stringent efficiency mandates.
Italy's Agency for National Cybersecurity (ACN) imposes security clearance requirements on data center operators handling sensitive government workloads, directly shaping contractor selection criteria. CE marking and the EU Energy Efficiency Directive constrain equipment specifications and operational performance benchmarks for new builds. Local permitting under Italy's Unified Environmental Authorization (AUA) framework adds procedural complexity that favors established players with regulatory navigation experience. Stakeholders must weigh sovereign cloud commitments against the capital intensity of liquid-cooled infrastructure as workload densities continue climbing.
Market Dynamics
Italy's data center construction sector faces intense pressure from sovereign cloud mandates under the National Recovery and Resilience Plan, which require domestic data residency for public administration workloads. This regulatory pivot is compressing project timelines and favoring contractors with proven hyperscale delivery capabilities.
Growth Catalysts
- EU Energy Efficiency Directive:Stringent operational performance benchmarks are accelerating retrofit demand across Lombardy and Lazio, creating pipeline for efficiency-focused engineering contracts.
- Hyperscale cloud expansion:Low-latency connectivity requirements to continental European networks are concentrating investment in Milan and Rome metro areas.
- Liquid cooling adoption:Power densities exceeding 15 kW per rack are driving precision thermal engineering contracts for high-performance computing environments.
Market Restraints
- Steel and copper volatility:Electrical infrastructure materials face input cost swings that compress fixed-price contract margins for shell-and-core delivery.
- Specialized contractor scarcity:ISO 50001-certified engineering firms concentrate in northern Italy, limiting execution capacity for simultaneous hyperscale deployments.
- Unified Environmental Authorization delays:Italy's AUA permitting framework adds procedural complexity that extends site approval timelines by 8-14 months.
Strategic Opportunities
- Southern Italy edge expansion:Latency-sensitive applications are creating greenfield demand in Sicily and Calabria for distributed computing nodes.
- ACN security clearance specialization:Contractors achieving national cybersecurity agency certification unlock exclusive bidding for sensitive government workloads.
- Immersion cooling convergence:Dielectric fluid systems paired with waste heat recovery are opening municipal district heating partnerships in Turin and Bologna.
Industry Challenges
- Thermal engineering talent scarcity:Italy produces insufficient mechanical engineers with direct liquid cooling expertise for 30+ kW rack densities.
- CE marking compliance timelines:Equipment certification under EU construction product regulations creates procurement bottlenecks for imported precision cooling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Construction Market |
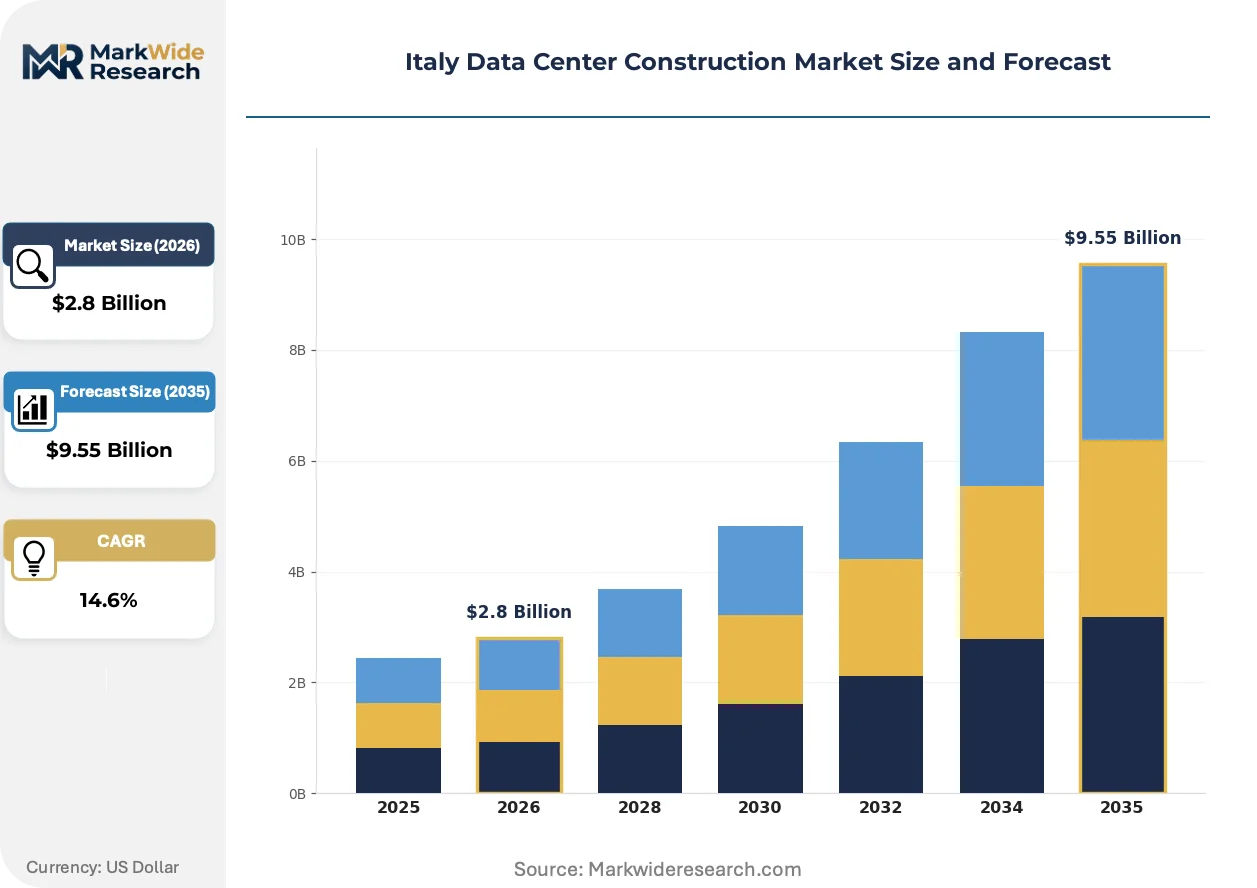
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hyperscale, Colocation, Edge, Modular Technology: Cooling Systems, Power Distribution, Security Infrastructure, Network Equipment End User: Cloud Service Providers, Enterprises, Telecommunications, Government Size: Small, Medium, Large, Enterprise |
| Companies Covered | AECOM, Arup Group Limited, Eiffage, Exyte, Ariatta, DBA PRO, CapIngelec, GSE Group, NORMA Engineering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Construction Market Trends and Innovations
Italian data center construction is pivoting from air-cooled legacy designs toward thermally intensive architectures that align with continental efficiency mandates. This shift is redrawing contractor specializations and equipment procurement patterns.
Direct liquid cooling is supplanting traditional raised-floor air handling in hyperscale facilities across Lombardy. Cloud operators in Milan's Siziano corridor are deploying cold plate systems for GPU-intensive AI training clusters. This technology is supplanting conventional chiller-based architectures and compressing mechanical plant footprints by 40 percent.
Italy's Agency for National Cybersecurity now mandates physical security clearances for personnel accessing sensitive government data halls. This regulatory layer is filtering contractor pools and extending pre-qualification periods. Colocation providers serving public administration clients are absorbing compliance costs through dedicated secure build zones.
Buyers are consolidating procurement under design-build contracts rather than fragmented EPC splits. Hyperscale tenants in Rome's Settebagni district now demand single-source accountability for shell, MEP, and commissioning. This concentration is visible most acutely among financial services tenants requiring accelerated occupancy schedules.
Italy Data Center Construction Market Segmentation
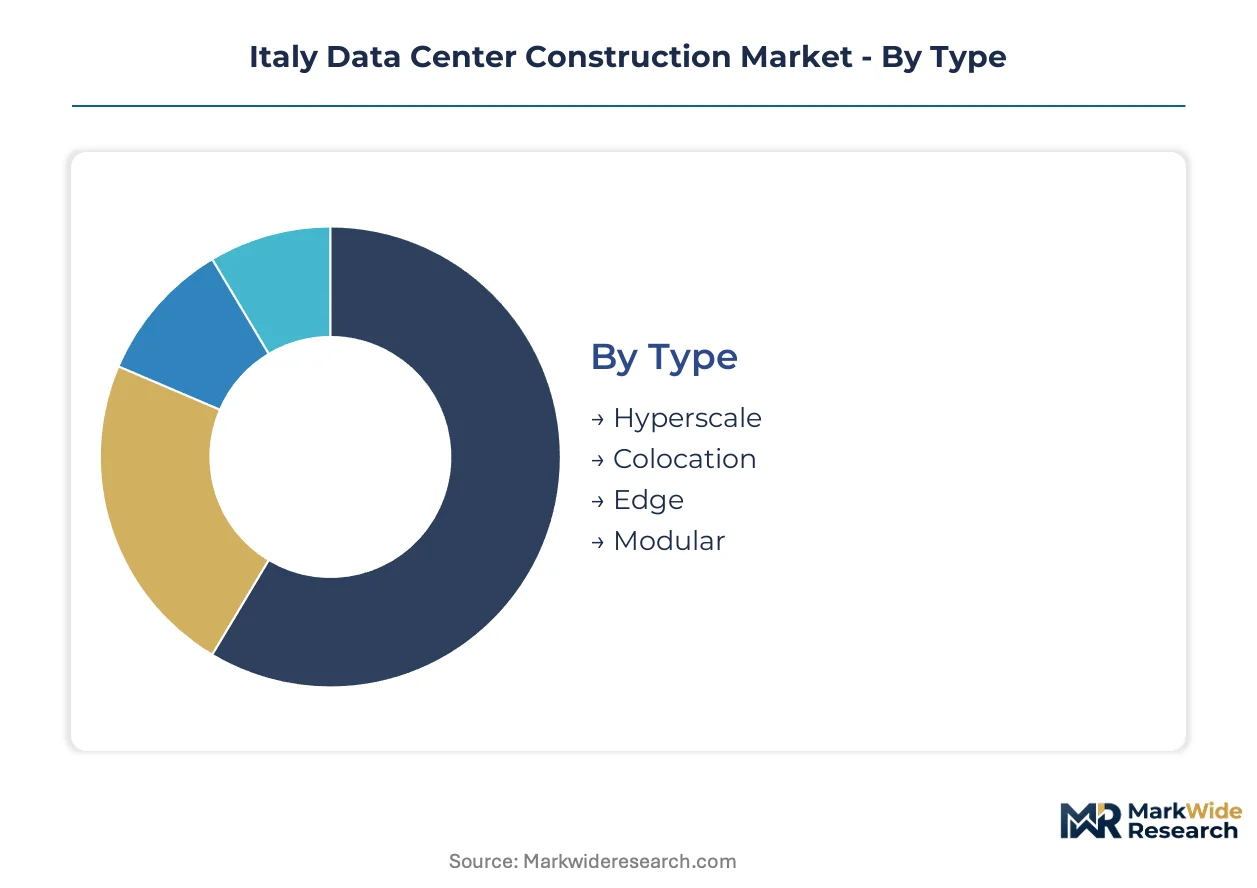
Construction contracts in Italy's data center market fragment sharply across facility scale and technical complexity, with margin concentration shifting toward liquid-cooled hyperscale builds and ACN-certified government installations. Understanding these segment boundaries clarifies where engineering capabilities translate into pricing power.
Type:
Hyperscale deployments command premium engineering margins due to thermal density requirements and compressed delivery schedules, while edge facilities compete on standardized modular replication.
- Hyperscale:Facilities exceeding 10 MW of critical IT load with direct liquid cooling infrastructure for GPU-intensive AI clusters. Milan's Siziano corridor concentrates demand from cloud operators seeking continental European network interconnection points under sovereign data mandates.
- Colocation:Multi-tenant facilities with standardized power densities and shared mechanical plants. Rome's Settebagni district absorbs the bulk of investment as financial services tenants demand accelerated occupancy schedules with single-source design-build accountability.
- Edge:Distributed computing nodes under 1 MW positioned for latency-sensitive applications. Sicily and Calabria attract greenfield development as content delivery networks seek southern European presence.
- Modular:Prefabricated data hall units with factory-integrated power and cooling. Factory acceptance testing under CE marking constrains procurement timelines for imported precision cooling systems.
The dominant share belongs to Hyperscale, while Edge is closing the gap fastest.
Technology:
Cost structures diverge most dramatically between thermal management systems and electrical infrastructure, with cooling technology absorbing disproportionate capital allocation due to Italy's rising ambient temperature profiles.
- Cooling Systems:Precision thermal engineering spanning cold plate direct liquid cooling, immersion dielectric systems, and residual chiller architectures. Turin and Bologna municipalities partner with operators for waste heat recovery into district heating networks.
- Power Distribution:Medium-voltage switchgear, uninterruptible power supplies, and busway distribution rated for 15+ kW rack densities. Steel and copper input cost volatility compresses fixed-price contract margins for electrical contractors.
- Security Infrastructure:Physical access control, perimeter systems, and ACN-mandated secure build zones for government workloads. Italy's Agency for National Cybersecurity filters contractor pools through personnel clearance requirements.
- Network Equipment:Structured cabling, optical distribution frames, and cross-connect infrastructure for continental European connectivity. Low-latency requirements to Frankfurt and Paris peering points shape Milan metro area specifications.
Cooling Systems capture the largest capital share, though Security Infrastructure is gaining share fastest through ACN compliance specialization.
End User:
Procurement authority concentrates with cloud operators consolidating under design-build contracts, while government buyers introduce security clearance premiums that reshape contractor selection criteria.
- Cloud Service Providers:Hyperscale tenants demanding single-source accountability for shell, MEP, and commissioning with sovereign data residency requirements. Italy's National Recovery and Resilience Plan compresses project timelines for public administration workload capacity.
- Enterprises:Corporate captive facilities with customized redundancy tiers and internal security protocols. Financial services tenants in Lombardy drive accelerated delivery schedules through integrated design-build procurement.
- Telecommunications:Carrier-neutral facilities and network edge nodes supporting 5G infrastructure densification. Latency-sensitive applications proliferate across metropolitan markets.
- Government:Public administration workloads requiring ACN security clearances and domestic data residency certification. Sensitive government data halls absorb compliance costs through dedicated secure build zones.
Cloud Service Providers anchor volume commitments, while Government is expanding most quickly through sovereign cloud mandates.
Size:
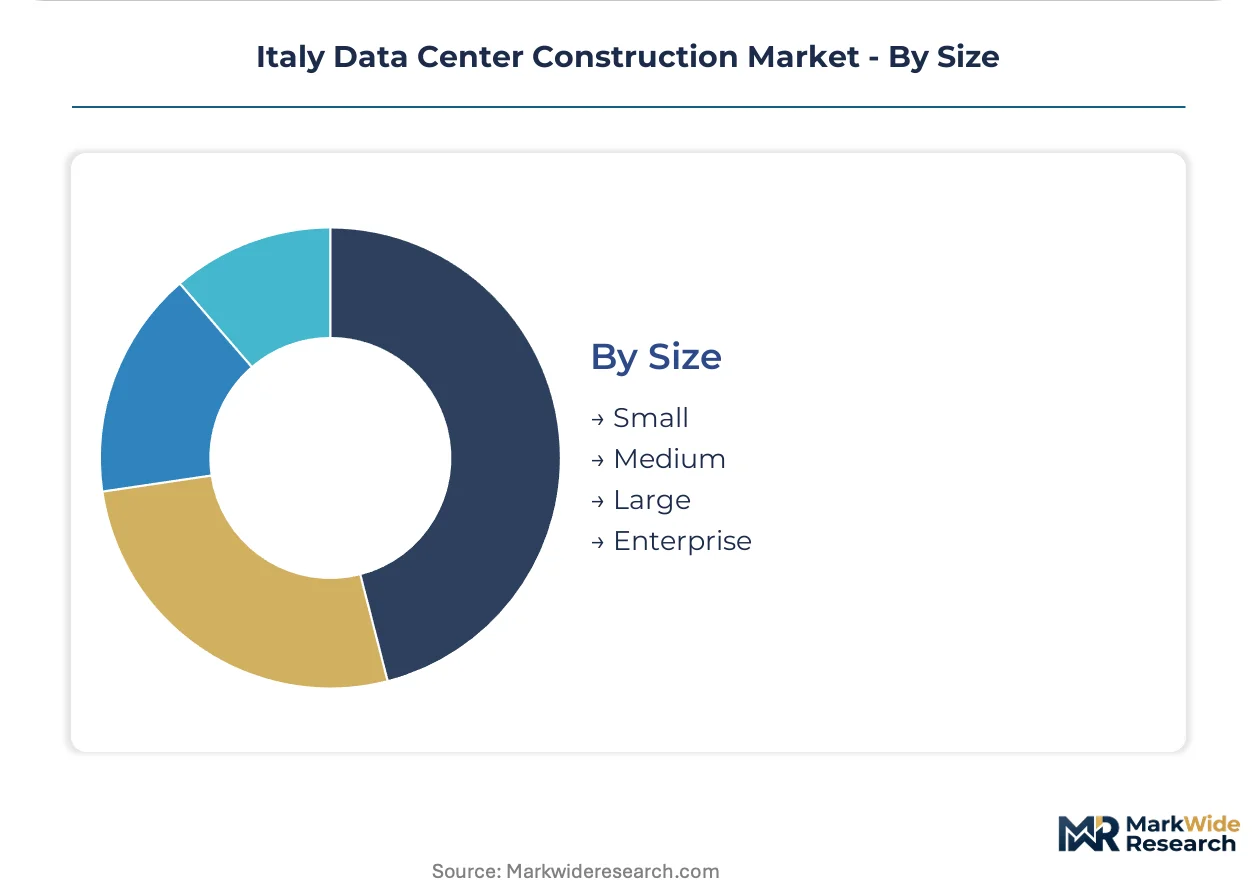
Project scale determines contractor eligibility, with large and enterprise facilities filtering for ISO 50001-certified engineering firms concentrated in northern Italy.
- Small:Facilities under 500 kW serving localized compute requirements with standardized modular approaches. Regional colocation providers favor speed-to-market over custom engineering.
- Medium:500 kW to 2 MW facilities with tiered redundancy and shared infrastructure. Lombardy and Lazio absorb retrofit demand under EU Energy Efficiency Directive operational benchmarks.
- Large:2 MW to 10 MW deployments with dedicated mechanical plants and precision cooling. ISO 50001 energy management certification raises competitive barriers for contractors without demonstrated efficiency credentials.
- Enterprise:Facilities exceeding 10 MW with custom thermal engineering for 30+ kW rack densities. Italy produces insufficient mechanical engineers with direct liquid cooling expertise for this segment's technical requirements.
Enterprise facilities command the highest contract values, though Large facilities are gaining share fastest through hyperscale tenant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's National Recovery and Resilience Plan channels sovereign cloud investment toward domestic data residency, compressing delivery timelines and concentrating hyperscale development in northern industrial corridors.
Lombardy
Milan's Siziano corridor attracts cloud operators seeking continental European network interconnection points under sovereign data mandates. The EU Energy Efficiency Directive imposes operational performance benchmarks that accelerate retrofit demand across the region. ISO 50001-certified engineering firms concentrate here, creating execution bottlenecks for simultaneous hyperscale deployments.
Piedmont
Turin municipalities partner with operators for waste heat recovery into district heating networks, anchoring immersion cooling convergence. CE marking compliance timelines constrain procurement for imported precision cooling systems. The metropolitan area absorbs specialized thermal engineering contracts for GPU-intensive AI training clusters.
Lazio
Rome's Settebagni district hosts financial services tenants demanding accelerated occupancy schedules with single-source design-build accountability. Italy's Agency for National Cybersecurity mandates physical security clearances for personnel accessing sensitive government data halls. The capital region filters contractor pools through extended pre-qualification periods for public administration workloads.
Emilia-Romagna
Bologna explores municipal district heating partnerships with dielectric fluid systems paired with waste heat recovery. The Unified Environmental Authorization framework adds procedural complexity that extends site approval timelines. Regional engineering capacity supports medium-scale colocation facilities with tiered redundancy and shared infrastructure.
Sicily
Latency-sensitive applications drive greenfield demand for distributed computing nodes across the island. Content delivery networks seek southern European presence as edge facilities represent the fastest-expanding footprint. Local permitting challenges favor established players with regulatory navigation experience in Mediterranean climate zones.
Italy Data Center Construction Market Competitive Landscape
Player mix skews toward integrated design-build specialists with demonstrated hyperscale delivery capabilities. The competitive field compresses around contractors possessing ISO 50001 energy management certification and ACN security clearance credentials. Three archetypes dominate: multinational engineering conglomerates with thermal density expertise, regional civil infrastructure speed players, and cybersecurity-cleared specialists for government workloads. Dominant competitive moves include strategic partnerships with cloud operators for sovereign cloud capacity and portfolio diversification into liquid-cooled infrastructure engineering.
Within the multinational tier, AECOM and Arup Group Limited anchor positions through integrated design-build capabilities and advanced thermal engineering for high-density computing environments. Eiffage occupies a position among European infrastructure specialists competing aggressively on civil delivery speed. These three exemplify the certification-heavy competitive structure where energy efficiency credentials and security clearances filter viable bidders for premium contracts.
| Leading Market Players |
|---|
| AECOM |
| Arup Group Limited |
| Eiffage |
| Exyte |
| Ariatta |
| DBA PRO |
| CapIngelec |
| GSE Group |
| NORMA Engineering |
| Others |
Pricing and Supply Chain Analysis
Design-build contracts with embedded capacity reservations lock in steel and copper access for Italian hyperscale projects while freezing electrical infrastructure costs against commodity volatility. This structure binds contractors to northern Italy's ISO 50001-certified engineering firms and insulates cloud operators from input cost swings that compress fixed-price shell-and-core margins.
Pricing Analysis
Certification level creates the primary spread across Italian data center construction bids, with ISO 50001 energy management credentials and ACN security clearances commanding 15-25% premiums over uncertified competitors. Project-based pricing dominates hyperscale deployments, while colocation facilities compete on standardized modular replication with compressed margins. Pricing pressure stems from steel and copper volatility in electrical infrastructure, squeezing fixed-price commitments for shell-and-core delivery. Cloud service providers exhibit lowest price sensitivity due to sovereign data mandates, while regional colocation operators in southern Italy face acute cost consciousness.
Supply Chain Analysis
Port congestion at Genoa and Trieste elevates inbound logistics costs for imported precision cooling systems, extending CE marking compliance timelines by 4-8 weeks. Manufacturing concentrates in Germany, France, and China for medium-voltage switchgear, uninterruptible power supplies, and dielectric fluid systems. Raw material dependencies center on copper busbar, steel enclosure fabrication, and specialized refrigerants. Single-source vulnerability pervades direct liquid cooling components, where German and Austrian suppliers dominate cold plate architectures. Distribution runs through Milan-based mechanical-electrical contractors with hyperscale commissioning experience.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's data center construction market sits at a platform-economics inflection where sovereign cloud interoperability requirements are consolidating procurement authority under design-build integrators. The shift from fragmented EPC splits to single-source accountability restructures competitive moats around certification density and thermal engineering depth.
For Market Incumbents: Shield market position by deepening ISO 50001-certified engineering capacity in Lombardy and accelerating ACN security clearance pipelines for government workload access. The threat of specialized contractor scarcity limits execution bandwidth for simultaneous hyperscale deployments, favoring early certification investment as a capacity-locking lever.
For New Entrants and Emerging Players: Liquid cooling talent gaps in southern Italy present service-layer white space where incumbents under-serve GPU-intensive AI cluster demand. Sicily and Calabria edge facilities offer the most penetrable geography, with latency-sensitive content delivery networks seeking local presence. A go-to-market angle anchored through municipal district heating partnerships in Turin or Bologna bypasses direct competition with established Milan-Rome hyperscale contractors.
For Investors and Strategic Acquirers: Capital is best deployed toward ACN-cleared specialists with demonstrated liquid cooling delivery and existing sovereign cloud tenant relationships. Long-term viability across the 5-10 year window hinges on regulatory compliance depth rather than civil construction speed alone. The signal to watch is ACN pre-qualification timeline compression, which would indicate certification scarcity easing and margin pressure intensifying.
| Strategic Initiative | Industry Significance |
|---|---|
| ACN Security Clearance Acquisition | Unlocks exclusive bidding for Italy's Agency for National Cybersecurity-mandated government data halls. |
| Liquid Cooling Engineering Partnership | Captures GPU-intensive AI cluster contracts as Milan's Siziano corridor power densities exceed 30 kW per rack. |
| Southern Italy Edge Facility Development | Addresses latency-sensitive application demand in Sicily and Calabria with lower land and permitting competition. |
| Municipal Waste Heat Recovery Integration | Creates differentiated positioning through Turin and Bologna district heating network partnerships. |
| ISO 50001 Certification Acceleration | Raises competitive barriers against uncertified contractors under EU Energy Efficiency Directive benchmarks. |
Research Methodology
Cross-validation between primary interviews with data center developers, EPC contractors, and cloud operator procurement leads anchors the qualitative findings against secondary validation from EU Energy Efficiency Directive filings, ACN security clearance registries, and hyperscaler capital expenditure disclosures. Bottom-up project pipeline aggregation triangulates with top-down market sizing across facility type, cooling technology, and end-user segmentation. The analysis draws from construction permit databases, ISO 50001 certification records, and municipal zoning approvals across Lombardy, Lazio, Piedmont, and Sicily.
Sensitivity analysis tests forecast robustness against steel and copper price volatility, ACN clearance timeline variability, and liquid cooling adoption pace across the projection horizon. The analytical framework models hyperscale, colocation, edge, and modular facility types against cooling system technology, power distribution infrastructure, and security compliance tiers. CAGRs derive from installed base expansion, workload density trajectories, and sovereign data mandate enforcement intensity. Industry-specific inputs include GPU cluster deployment schedules, district heating partnership formation rates, and Unified Environmental Authorization approval velocity.
Underlying assumptions cover sustained sovereign cloud investment under Italy's National Recovery and Resilience Plan, with deviation risk concentrated in steel and copper commodity swings and ACN regulatory timeline extensions. Forecasts reflect these conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Global Containerized Data Center Market