
 Switzerland Data Center Power Market | 2026-2036
Switzerland Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Data Center Power Market Insights
The capital-intensity divergence between integrated power infrastructure providers and component assemblers is unwinding competitive dynamics across Swiss data center corridors. Schneider Electric SE leverages its end-to-end electrical distribution portfolio to anchor large-scale projects in the Zurich-West technology cluster. ABB Ltd sustains differentiation through medium-voltage switchgear and digital energy management platforms purpose-built for Alpine climate conditions. Vertiv Group Corp competes on thermal and power infrastructure integration, occupying a specialized position in edge and modular deployments.
Switzerland data center power encompasses the generation, conditioning, distribution, and backup systems that ensure continuous electrical supply to server environments, typically operating at 400/230V three-phase with redundancy tiers from N+1 to 2N+1 architectures. These systems incorporate uninterruptible power supplies, diesel rotary uninterruptible power supplies, and static transfer switches to bridge grid instability and generator startup intervals. Colocation facilities command the largest infrastructure-type revenue pool as Swiss banking and pharmaceutical tenants outsource capacity to meet FINMA audit requirements. Edge data centers represent the fastest-expanding segment, driven by latency-sensitive applications in precision manufacturing and autonomous logistics across Basel and Lausanne corridors. Liquid cooling technology is displacing legacy air systems in facilities above 10 MW, responding to rack densities exceeding 50 kW in AI training clusters.
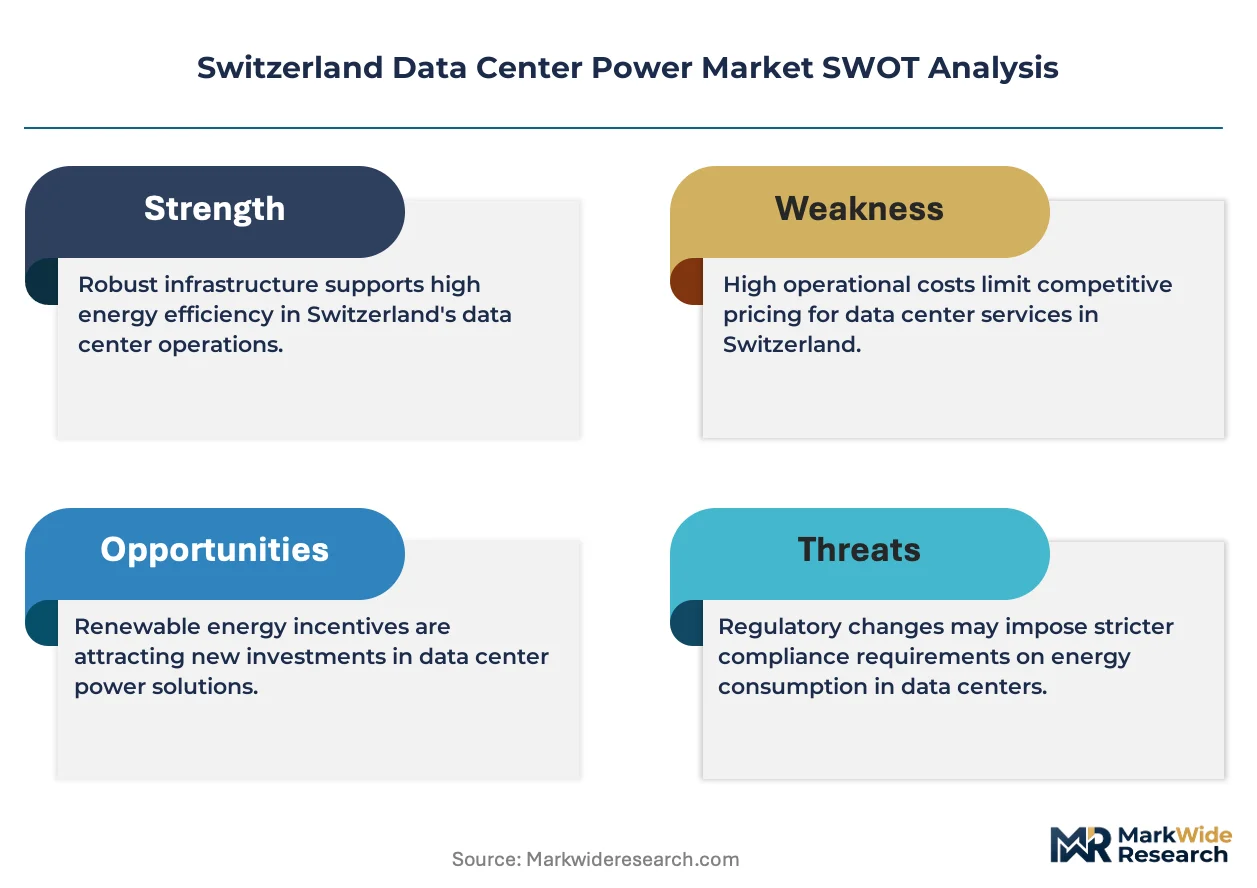
Swissmedic and the Federal Office of Energy enforce efficiency benchmarks and emissions disclosure for critical infrastructure, while FINMA guidelines on operational resilience directly shape data center uptime specifications and backup power redundancy. The Swiss Federal Council's dual carbon goals and building energy codes are forcing operators to source renewable power and retire diesel-dependent designs ahead of compliance deadlines. Stakeholders must monitor how cantonal zoning authorities in Zurich, Vaud, and Basel-Land balance data center load growth against hydroelectric grid capacity and alpine water cooling availability.
Market Dynamics
Liquid cooling infrastructure is decomposing legacy air-based thermal management across Swiss Alpine facilities, forcing power architecture redesigns that accommodate 50+ kW rack densities while preserving hydroelectric grid stability.
Growth Catalysts
- FINMA Operational Resilience Guidelines:Swiss banking regulators mandate backup power redundancy tiers that drive colocation providers toward 2N+1 electrical architectures. Financial services tenants in Zurich and Geneva absorb premium infrastructure costs to satisfy audit requirements.
- Precision Manufacturing Edge Demand:Autonomous logistics and industrial IoT deployments across Basel and Lausanne corridors require sub-10 millisecond latency. Edge data centers proliferate in secondary Swiss cities to serve pharmaceutical and watchmaking automation clusters.
- Federal Renewable Procurement Mandates:The Swiss Federal Council's dual carbon goals compel operators to retire diesel-dependent designs. Hydroelectric sourcing requirements accelerate battery energy storage system adoption for grid bridging.
Market Restraints
- Alpine Water Cooling Scarcity:Cantonal zoning authorities in Vaud and Basel-Land restrict freshwater withdrawals for evaporative cooling. Summer glacial melt variability threatens thermal discharge permits for facilities above 15 MW.
- Medium-Voltage Switchgear Supply Concentration:European electrical component fabrication concentrates in German and Austrian industrial corridors. Swiss project timelines extend 8-14 months for customized 36 kV switchgear assemblies.
- Copper and Rare Earth Magnet Volatility:Generator rotor windings and permanent magnet UPS systems face input cost pressure. Transformer core steel alloying elements exhibit 12-18 month price cyclicality that compresses EPC contractor margins.
Strategic Opportunities
- Ticino Cross-Border Campus Development:The southern canton offers Italian grid interconnection and lower land costs for latency-sensitive Milanese financial services. Hyperscale cloud providers evaluate Lugano corridor sites for Mediterranean market access.
- Waste Heat Recovery District Integration:Zurich-West and Geneva-Aeroport clusters pilot thermal energy export to municipal heating networks. Federal Office of Energy efficiency benchmarks reward operators achieving 40% heat reuse ratios.
- Modular Prefabrication Convergence:Factory-integrated power and cooling skids compress on-site construction from 18 to 6 months. Swiss pharmaceutical tenants favor repeatable 2-4 MW deployments for rapid clinical trial infrastructure scaling.
Industry Challenges
- High-Voltage Technician Certification Bottlenecks:Swiss Federal Inspectorate for Heavy Current Installations administers limited annual examination slots. Cantonal apprenticeship programs produce fewer than 120 qualified medium-voltage specialists yearly against project pipeline demand.
- Legacy Diesel Rotary UPS Integration Complexity:Existing 1990s-era kinetic energy storage systems resist seamless battery energy storage retrofit. Basel pharmaceutical facilities face 24-36 month parallel operation periods during hybrid architecture transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Data Center Power Market |
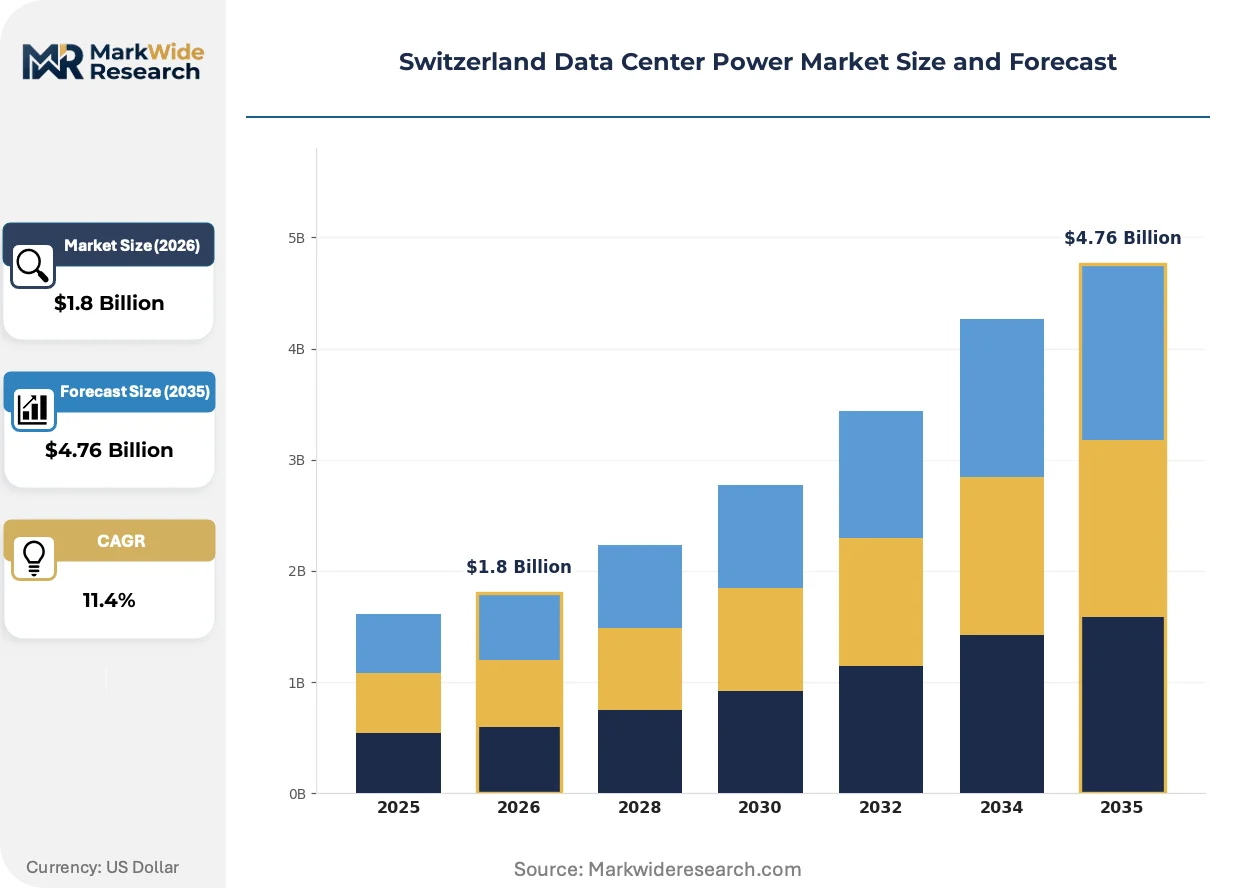
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Diesel Generators, Natural Gas, Grid Power Infrastructure Type: Colocation Facilities, Edge Data Centers, Cloud Providers, Enterprise Data Centers Power Capacity: Below 1 MW, 1-5 MW, 5-10 MW, Above 10 MW Cooling Technology: Air Cooling, Liquid Cooling, Immersion Cooling, Hybrid Cooling |
| Companies Covered | Schneider Electric SE, ABB Ltd, Eaton Corporation, Vertiv Group Corp, Cisco Systems Inc, Fujitsu Ltd, Delta Electronics, Huawei Technologies Co Ltd, Legrand SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Data Center Power Market Trends and Innovations
Power distribution architecture is fragmenting from centralized monolithic designs toward segmented, software-defined topologies that match electrical supply granularity to fluctuating AI workload intensity.
Direct liquid cooling manifolds and cold plate assemblies are decomposing traditional CRAH and chiller-centric thermal strategies. Hyperscale cloud campuses in the Greater Zurich Area deploy single-phase and two-phase immersion systems for GPU training clusters. This technology compression enables 100+ kW rack densities without mechanical refrigeration, reducing power usage effectiveness ratios below 1.15.
Swissmedic and the Federal Office of Energy enforce mandatory energy disclosure and efficiency benchmarking for critical infrastructure operators. Pharmaceutical manufacturing tenants must document Scope 2 emissions for GMP facility certification. Colocation providers respond by procuring Guarantees of Origin from Alpine hydroelectric assets and installing sub-metering at the PDU level.
Financial services procurement teams now unbundle long-term power infrastructure contracts from facility leases. Zurich banking consortia negotiate direct renewable energy supply agreements with Axpo and Alpiq, then contract colocation operators for shell and cooling-only space. This consumption-pattern shift transfers energy price risk to tenant balance sheets while compressing traditional utility markup structures.
Switzerland Data Center Power Market Segmentation
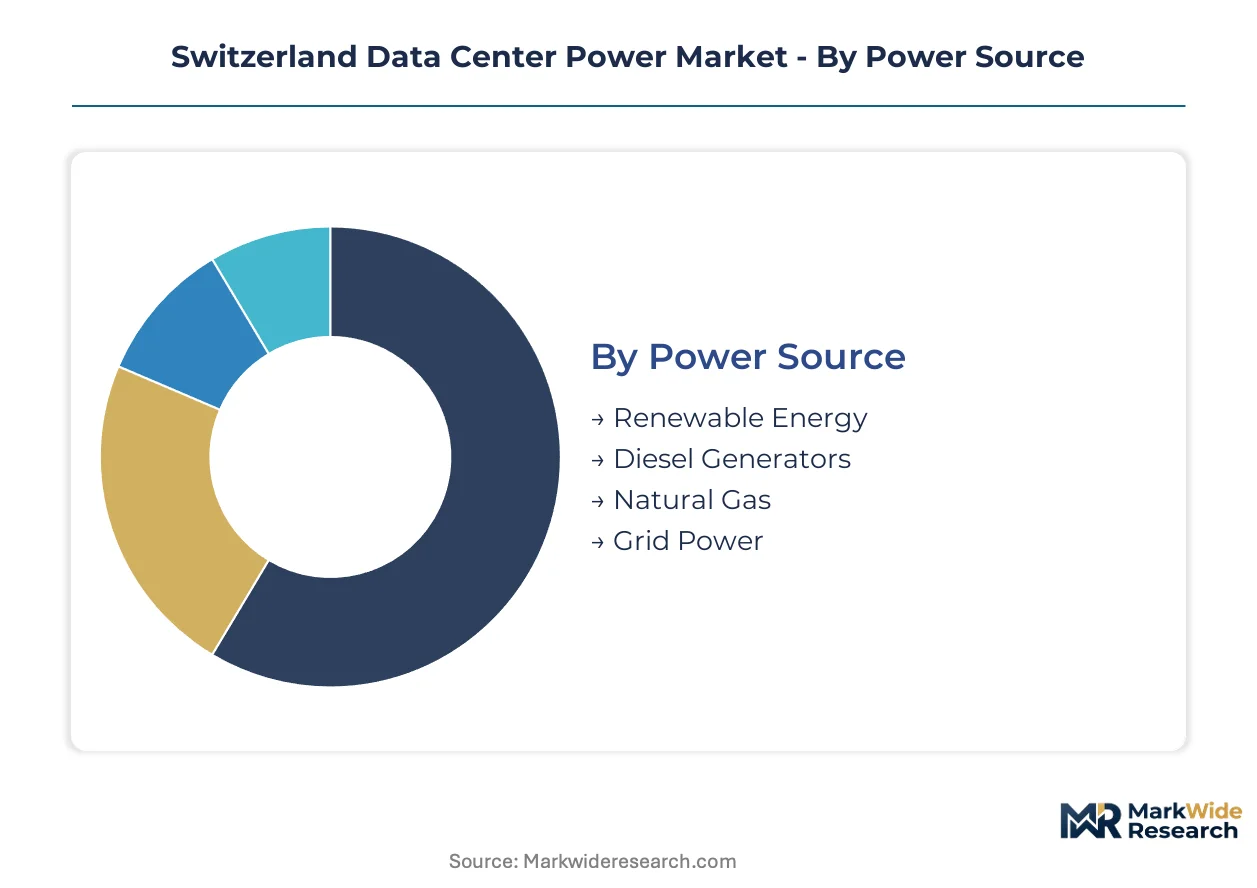
Switzerland data center power segmentation reflects regulatory pressures from Swissmedic efficiency mandates and FINMA resilience requirements. Power architecture choices increasingly hinge on cantonal renewable procurement rules and alpine thermal discharge constraints.
Power Source:
Swiss Federal Council dual carbon goals and hydroelectric grid access differentiate procurement economics across cantonal boundaries.
- Renewable Energy:Guarantees of Origin from Alpine hydroelectric assets satisfy Federal Office of Energy disclosure mandates. Zurich and Geneva financial services tenants absorb premium pricing to meet FINMA audit requirements for Scope 2 emissions documentation.
- Diesel Generators:Legacy rotary and static UPS bridging systems face accelerated retirement timelines under building energy code revisions. Basel pharmaceutical facilities encounter 24-36 month hybrid transition periods during battery energy storage integration.
- Natural Gas:Cogeneration plants serve district heating integration pilots in Zurich-West clusters. Cantonal air quality permits restrict new installations in Vaud and Basel-Land corridors.
- Grid Power:Direct utility agreements with Axpo and Alpiq dominate Greater Zurich Area hyperscale developments. Medium-voltage switchgear lead times of 8-14 months constrain project velocity.
Established volume favors diesel generators; emerging adoption favors renewable energy.
Infrastructure Type:
Latency requirements and audit complexity stratify tenant preferences across Swiss urban corridors.
- Colocation Facilities:Multi-tenant designs absorb 2N+1 electrical architecture costs for FINMA-compliant banking clients. Zurich and Geneva campuses command premium pricing for cross-connected financial services redundancy.
- Edge Data Centers:Sub-10 millisecond latency specifications drive modular 2-4 MW deployments in Basel and Lausanne precision manufacturing zones. Watchmaking and pharmaceutical automation clusters generate concentrated demand.
- Cloud Providers:Hyperscale campuses anchor Greater Zurich Area developments with 100+ kW rack densities. Liquid cooling manifolds displace mechanical refrigeration in GPU training clusters.
- Enterprise Data Centers:Captive facilities persist among Swiss pharmaceutical manufacturers requiring GMP-certified infrastructure control. Swissmedic documentation obligations favor in-house operational sovereignty.
Revenue concentration sits with colocation facilities; steepest expansion trajectory belongs to edge data centers.
Power Capacity:
Scale thresholds determine cooling technology viability and grid interconnection complexity.
- Below 1 MW:Modular prefabricated skids compress deployment timelines for clinical trial infrastructure scaling. Swiss pharmaceutical tenants favor repeatable factory-integrated power and cooling units.
- 1-5 MW:Mid-scale facilities balance air-cooled economics against emerging liquid cooling retrofit pathways. Regional banking data centers cluster in this tier for cost-optimized redundancy.
- 5-10 MW:Hybrid cooling architectures accommodate rack density transitions without full infrastructure replacement. Ticino cross-border developments target this scale for Italian market latency.
- Above 10 MW:Single-phase and two-phase immersion systems enable sub-1.15 PUE ratios without evaporative cooling. Summer glacial melt variability threatens thermal discharge permits for Vaud facilities.
Deployment frequency peaks below 1 MW; technology investment intensity concentrates above 10 MW.
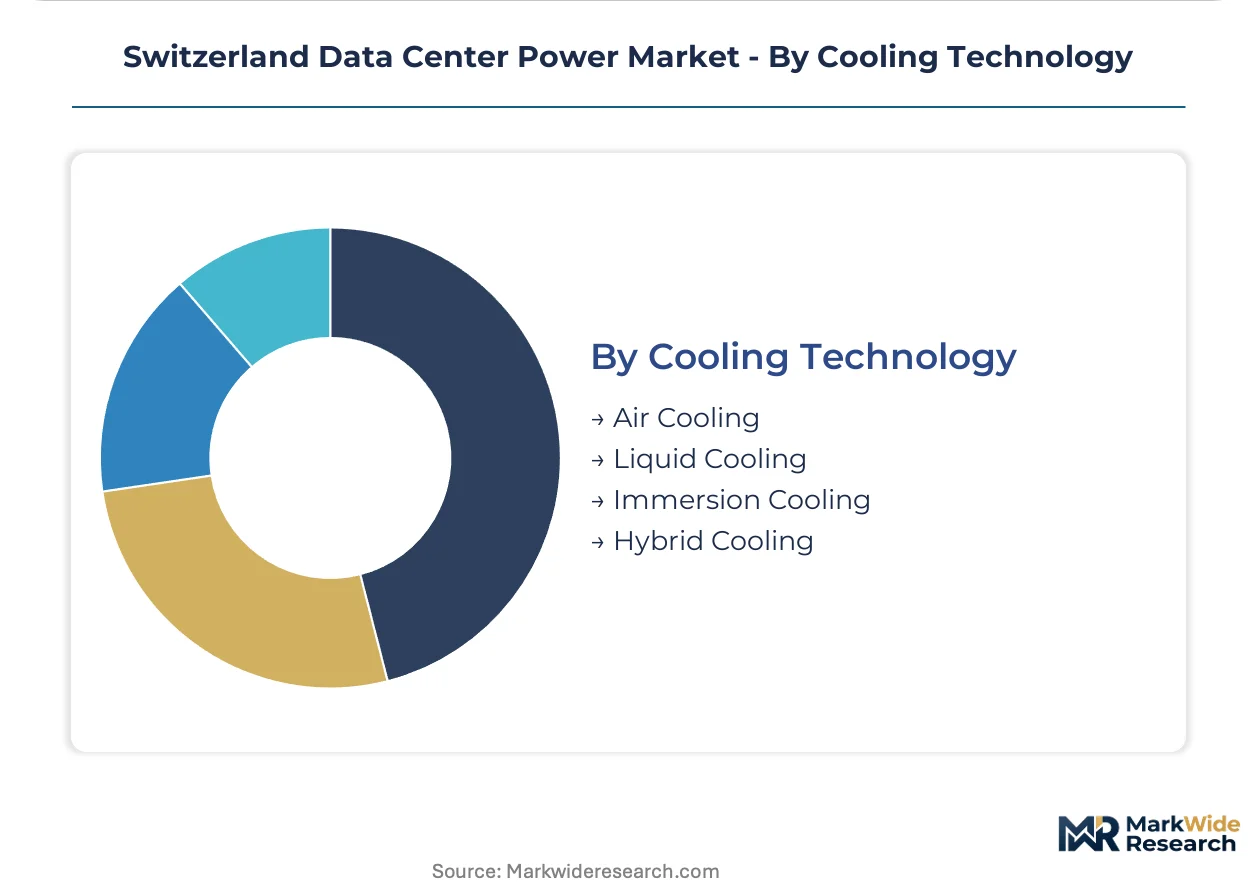
Cooling Technology:
Alpine water availability and rack density trajectories reshape thermal management procurement.
- Air Cooling:Legacy CRAH and chiller-centric designs persist in sub-5 MW facilities with stable workload profiles. Basel-Land cantonal restrictions on freshwater withdrawals accelerate displacement.
- Liquid Cooling:Direct-to-chip manifolds and cold plate assemblies serve 50+ kW AI training racks in Zurich-West hyperscale campuses. Federal Office of Energy efficiency benchmarks reward heat reuse integration.
- Immersion Cooling:Dielectric fluid systems eliminate mechanical refrigeration for 100+ kW GPU clusters. Greater Zurich Area cloud providers pilot two-phase systems for thermal stability.
- Hybrid Cooling:Segmented architectures match air and liquid zones to fluctuating workload intensity. Software-defined thermal management enables granular efficiency optimization.
Installed base remains air-cooled; technology transition favors liquid cooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Zurich Area commands infrastructure premiums 40-60% above Ticino corridor pricing, yet Geneva banking clusters absorb the highest power redundancy costs per MW deployed. This asymmetry reflects cantonal regulatory divergence and hydroelectric grid access stratification across Swiss metropolitan zones.
Greater Zurich Area
Hyperscale cloud campuses anchor demand in Zurich-West and Glattbrugg technology clusters, driven by GPU training workloads exceeding 100 kW per rack. FINMA operational resilience guidelines mandate 2N+1 electrical architectures for financial services tenants. Schneider Electric SE and ABB Ltd dominate switchgear procurement for facilities above 10 MW capacity.
Geneva
Private banking and wealth management institutions drive colocation expansion along the Rhône corridor. Swissmedic efficiency disclosure requirements intersect with cantonal building energy codes to accelerate diesel generator retirement timelines. Lake Geneva water cooling access permits face summer thermal discharge restrictions under Vaud environmental regulations.
Basel
Pharmaceutical manufacturing automation clusters generate concentrated edge data center demand for sub-10 millisecond latency. Novartis and Roche supply chain digitization drives modular 2-4 MW deployments near Basel-Mulhouse-Freiburg tri-border logistics hubs. Cantonal zoning authorities restrict freshwater withdrawals for evaporative cooling above 15 MW facilities.
Lausanne
École polytechnique fédérale de Lausanne research partnerships anchor precision manufacturing IoT deployments across the Lemanic Arc. Watchmaking automation clusters require edge infrastructure for quality control vision systems. Federal Office of Energy efficiency benchmarks reward operators achieving 40% waste heat recovery ratios in district heating integration pilots.
Ticino
The Lugano corridor offers Italian grid interconnection and land cost advantages 25-35% below northern cantons. Milanese financial services latency requirements drive cross-border campus evaluation. Hyperscale cloud providers assess Mediterranean market access against Swiss regulatory compliance benefits for EU data sovereignty requirements.
Switzerland Data Center Power Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Swiss data center corridors. The market structures around three tiers: integrated electrical infrastructure providers commanding premium positioning, component specialists competing on thermal and power integration, and modular system assemblers serving rapid deployment segments. Strategic differentiation concentrates on end-to-end portfolio breadth versus specialized subsystem depth. Competitive moves center on factory-integrated skid offerings and cross-border service network expansion into adjacent European markets.
Among integrated infrastructure providers, Schneider Electric SE and ABB Ltd exemplify the premium-tier archetype through end-to-end electrical distribution and medium-voltage switchgear positioning. Vertiv Group Corp occupies a specialized integration position spanning thermal management and power infrastructure for edge and modular deployment segments. These three anchors represent distinct competitive vectors: full-stack system ownership, heavy electrical equipment specialization, and subsystem integration expertise.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Eaton Corporation |
| Vertiv Group Corp |
| Cisco Systems Inc |
| Fujitsu Ltd |
| Delta Electronics |
| Huawei Technologies Co Ltd |
| Legrand SA |
| Others |
Pricing and Supply Chain Analysis
Battery energy storage system substitution for diesel rotary UPS is redrawing procurement geography and compressing pricing premiums across Swiss data center corridors. This technology shift forces EPC contractors to absorb transformer core steel alloying cost cyclicality while cantonal renewable mandates accelerate premium pricing for hydroelectric-sourced infrastructure.
Pricing Analysis
The customization-premium spread between configured-to-order medium-voltage switchgear and standard modular skids spans project-based contracting structures. Price differentiation rests on FINMA certification tier and alpine climate hardening specifications. Cost compression in sub-5 MW edge deployments is intensifying because pharmaceutical tenants favor repeatable factory-integrated units. Regional banking consortia exhibit lowest price sensitivity; Basel precision manufacturing clusters absorb premium pricing for sub-10 millisecond latency guarantees.
Supply Chain Analysis
European medium-voltage switchgear fabrication chokepoints in German and Austrian industrial corridors tether Swiss project timelines to continental component availability. Copper winding supply draws from Chilean mining operations; rare earth magnet procurement rests on Chinese processing concentration. Single-source vulnerability in 36 kV switchgear assemblies exposes contractors to extended lead time uncertainty. Distribution runs through EPC contractor networks with direct OEM relationships for critical electrical infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against battery energy storage system commoditization threatening legacy diesel rotary UPS service revenues. Incumbents must navigate cantonal efficiency mandates that accelerate technology obsolescence cycles.
For Market Incumbents: Compound defensive positioning through backward integration into medium-voltage switchgear assembly capacity near Zurich-West clusters. Secure captive supply of transformer core steel alloying elements against 12-18 month price cyclicality. Battery energy storage retrofit complexity at Basel pharmaceutical facilities creates sticky service revenue pools worth defending.
For New Entrants and Emerging Players: Differentiate on Ticino cross-border campus development where Italian grid interconnection and land cost advantages undercut northern canton pricing. Target the 2-4 MW modular edge segment serving Lausanne watchmaking automation clusters with rapid deployment factory-integrated skids. FINMA audit complexity creates consultative selling opportunities for compliance-focused entrants.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrical infrastructure specialists holding medium-voltage switchgear fabrication capacity. Long-term viability hinges on hydroelectric grid access stability and cantonal zoning permissiveness for alpine water cooling. Monitor Federal Office of Energy efficiency benchmark tightening as inflection indicator for accelerated diesel generator retirement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Switchgear Assembly | Captive production of 36 kV assemblies compresses lead times against German supply concentration. |
| Waste Heat Recovery District Integration | Zurich-West pilots exporting thermal energy to municipal heating networks satisfy Federal Office of Energy benchmarks. |
| Modular Prefabrication Convergence | Factory-integrated power and cooling skids reduce on-site construction timelines for pharmaceutical clinical trial scaling. |
| Ticino Cross-Border Campus Development | Lugano corridor sites offer Italian grid interconnection for Milanese financial services latency requirements. |
| Battery Energy Storage Retrofit Services | Basel pharmaceutical facilities face 24-36 month hybrid transition periods creating extended service contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center operators, EPC contractors, and cantonal energy planners; and secondary validation through Swiss Federal Office of Energy disclosure filings, FINMA operational resilience guidelines, and Axpo renewable procurement databases. Bottom-up facility-level capacity tracking and top-down cantonal grid interconnection assessments were triangulated against Alpine hydroelectric generation forecasts.
Across the projection horizon, the analytical framework modeled power capacity tiers, infrastructure type segmentation, cooling technology transitions, and cantonal regulatory framework clusters. CAGRs were derived from facility pipeline tracking and tenant absorption rate analysis. Forecast inputs incorporated Swissmedic efficiency mandate compliance timelines and Federal Council dual carbon goal implementation trajectories.
Decision-makers should treat outputs as directional under sustained hydroelectric grid stability and cantonal zoning permissiveness assumptions; material deviation in alpine water cooling availability or medium-voltage switchgear supply concentration would warrant model refresh. Practitioners should keep alternative scenarios live as Federal Office of Energy efficiency benchmark tightening and copper price cyclicality evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
South Africa Data Center Rack Market