
 Mexico Data Center Physical Security Market | 2026-2036
Mexico Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Data Center Physical Security Market Insights
Aftermarket service revenue is reconfiguring margin pools across the Mexico data center physical security landscape. Schneider Electric leverages its integrated power and security platform to capture recurring maintenance contracts. Siemens AG anchors its position through building automation systems that converge physical access with energy management. Genetec specializes in video management software that unifies surveillance across multi-tenant facilities.
Mexico data center physical security encompasses the layered protection of critical infrastructure through perimeter barriers, biometric access control, video surveillance with analytics, and environmental threat detection. Systems typically integrate IP-based cameras operating at 1080p to 4K resolution with access control readers supporting multi-factor authentication across mantrap entries and server cage zones. Surveillance cameras and access control systems represent the dominant technology spend, with monitoring services capturing expanding margin pools as operators outsource round-the-clock threat response. Physical barriers maintain steady demand in greenfield builds, while security personnel faces gradual displacement by software-driven verification workflows.
CONUEE energy efficiency mandates and INAI data protection requirements shape procurement standards for facility operators across Mexican states. CNBV banking regulations impose physical access logging on financial institutions, directly stimulating biometric and audit-trail system upgrades. Stakeholders must weigh the trade-off between capital-intensive on-premise security stacks and managed monitoring services as facility densities rise in Querétaro and Mexico City corridors.
Market Dynamics
Hyperscale cloud operators in Querétaro and Mexico City are compressing procurement cycles for integrated physical security stacks, forcing facility designers to specify unified access control and surveillance platforms rather than point solutions from fragmented vendors.
Growth Catalysts
- INAI data protection mandates:Federal requirements for audit-trail logging and biometric verification at data processing facilities are accelerating replacement of legacy card-reader systems across banking and telecommunications installations.
- Hyperscale facility expansion:Amazon Web Services, Google Cloud, and Microsoft Azure are commissioning multi-megawatt campuses in the Bajío corridor, each requiring perimeter barriers, mantrap entries, and 4K video analytics at scale.
- CNBV banking regulations:Mexico's banking commission mandates physical access logging with biometric capture for all financial data centers, directly stimulating demand for multi-factor authentication infrastructure.
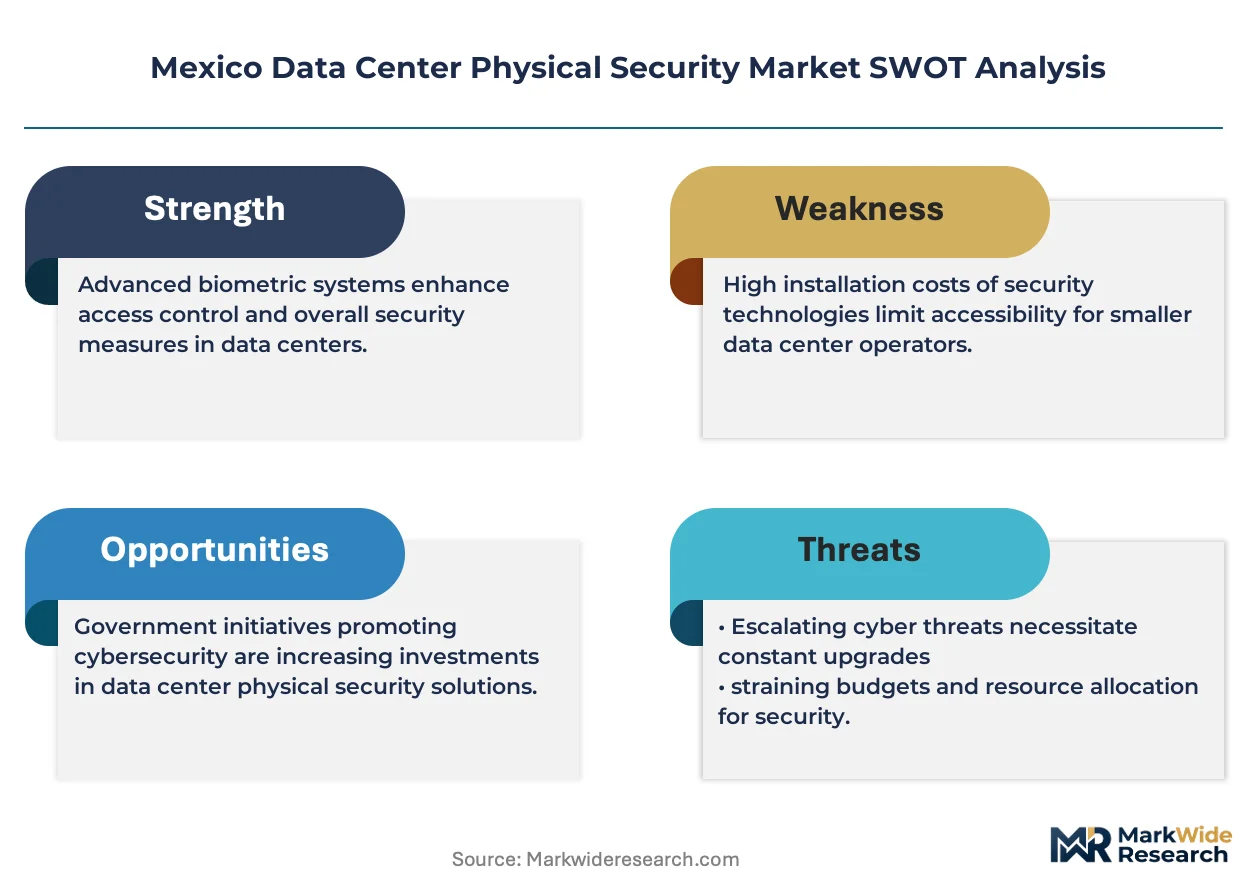
Market Restraints
- Copper and steel input volatility:Perimeter fencing, server cage mesh, and conduit systems face margin pressure from fluctuating commodity prices, squeezing fixed-price construction contracts.
- Specialized integrator concentration:Certified installation capacity clusters in Mexico City and Monterrey, creating bottlenecks for greenfield projects in secondary states like Guanajuato and San Luis Potosí.
- Legacy analog infrastructure:Thousands of existing facilities operate coaxial-based CCTV systems that resist IP migration without complete cabling replacement, delaying upgrade timelines.
Strategic Opportunities
- CONUEE energy efficiency incentives:Federal efficiency standards reward facilities that integrate access control with building management systems, opening cross-sell opportunities for converged platforms.
- Mérida-Cancún corridor:Underdeveloped data center capacity in Yucatán and Quintana Roo offers first-mover positioning for submarine cable landing stations requiring hardened perimeter security.
- AI-powered video analytics:Behavioral recognition and anomaly detection algorithms are penetrating multi-tenant colocation facilities where manual monitoring costs scale with tenant count.
Industry Challenges
- Cyber-physical integration expertise:Facility operators struggle to recruit engineers fluent in both IT network security and physical access control system architecture, delaying unified threat management deployments.
- Multi-vendor interoperability:Proprietary protocols from dominant access control and video management suppliers create integration friction when hyperscale tenants demand open-platform APIs for tenant-facing dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Data Center Physical Security Market |
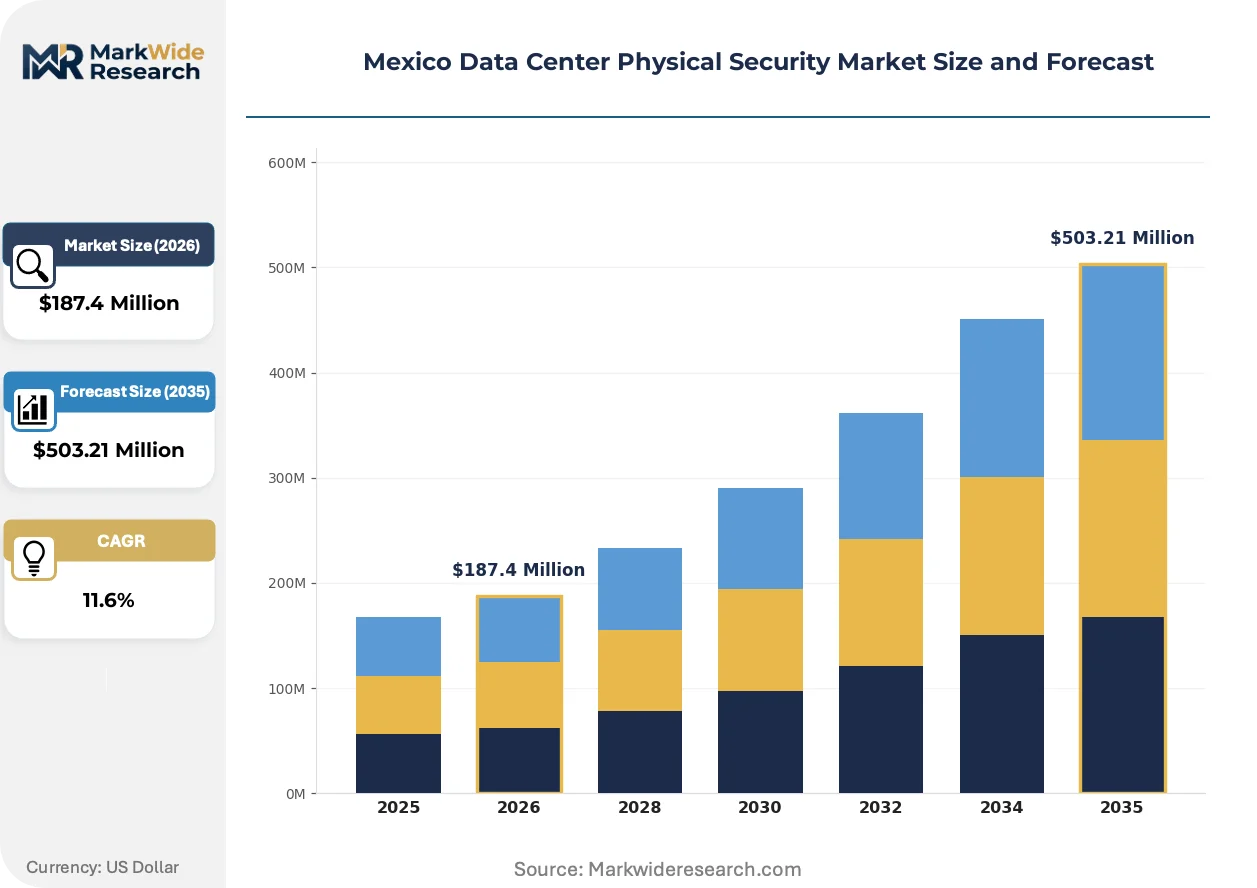
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Cameras, Access Control Systems, Motion Detectors, Fire Alarm Systems Service Type: Consulting Services, Installation Services, Maintenance Services, Monitoring Services End User: Telecommunications Companies, IT Firms, Financial Institutions, Government Agencies Product Type: Physical Barriers, Security Personnel, Monitoring Software, Alarm Systems |
| Companies Covered | Securitas Technology, Genetec, Honeywell International Inc, Siemens AG, Cisco Systems Inc, Johnson Controls, Milestone Systems A/S, Schneider Electric, ABB Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Data Center Physical Security Market Trends and Innovations
Biometric verification workflows and software-defined surveillance architectures are compressing the traditional security personnel count per facility while expanding the data exhaust available for compliance auditing and operational analytics.
Facial recognition and palm-vein authentication systems are rendering obsolete magnetic stripe and proximity card credentials across hyperscale and enterprise colocation facilities. Cloud operators in Querétaro are specifying touchless biometric readers for 100% of mantrap entries, eliminating credential-sharing risks and reducing tailgating incidents. The shift is compressing demand for physical credential production and card management services.
CONUEE efficiency mandates are tightening standby power requirements for security system continuity, forcing integrators to specify UPS-backed access control and edge-recording architectures that maintain operation through grid instability. Facilities must now demonstrate 72-hour autonomous surveillance capability to receive efficiency certifications. Banking and healthcare data centers in Mexico City are absorbing the highest compliance costs as they retrofit legacy electrical infrastructure.
Colocation tenants are unbundling security monitoring from facility base rent, contracting directly with specialized operations centers for round-the-clock threat response rather than accepting landlord-provided guard services. This disintermediation pressures facility operators to open API access for tenant-selected monitoring providers. The pattern is most visible in Guadalajara's emerging tech corridor, where software-as-a-service tenants demand SOC 2-aligned security operations separate from physical plant management.
Mexico Data Center Physical Security Market Segmentation
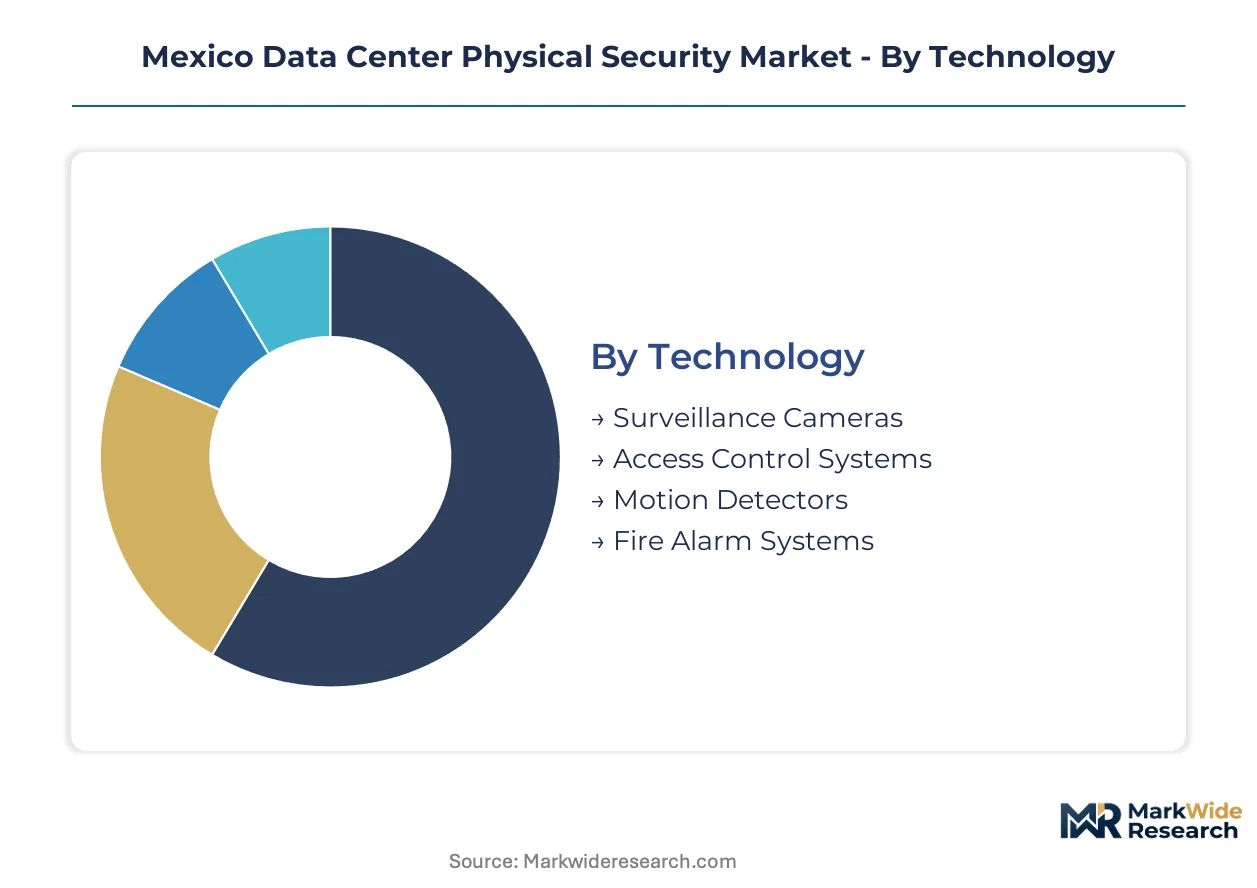
Security procurement in Mexican data centers fragments across technology stacks, service models, and compliance-driven end-user requirements. Each segment exhibits distinct replacement cycles and margin profiles that reshape vendor positioning across Querétaro and Mexico City corridors.
Technology:
Surveillance cameras turn over fastest as resolution upgrades compress refresh cycles, while fire alarm systems persist longest due to regulatory recertification timelines.
- Surveillance Cameras:IP-based units operating at 1080p to 4K resolution dominate new builds, with hyperscale operators in the Bajío corridor specifying edge-analytics capability for real-time threat detection. Banking data centers under CNBV mandates absorb the highest unit volumes for audit-trail compliance.
- Access Control Systems:Biometric readers supporting multi-factor authentication across mantrap entries command premium positioning. Financial institutions replacing legacy card-reader infrastructure drive replacement demand concentrated in Mexico City and Monterrey metropolitan zones.
- Motion Detectors:PIR and microwave sensors integrate with video analytics for perimeter hardening at submarine cable landing stations.
- Fire Alarm Systems:Addressable smoke detection and very early warning aspirating systems maintain decade-long deployment horizons due to CONUEE integration requirements.
Surveillance cameras anchor the volume base while access control systems gain share at the steepest rate.
Service Type:
Cost tiering separates capital-intensive installation from recurring revenue streams that expand with facility density.
- Consulting Services:Risk assessment and compliance gap analysis for INAI data protection mandates. Colocation operators in Guadalajara's tech corridor absorb the highest consulting hours for multi-tenant security architecture.
- Installation Services:Certified integrator capacity clusters in Mexico City and Monterrey, creating bottlenecks for greenfield projects in secondary states.
- Maintenance Services:Recurring contracts for biometric reader calibration and camera lens replacement generate predictable revenue pools.
- Monitoring Services:24/7 threat response outsourcing expands as software-as-a-service tenants demand SOC 2-aligned operations separate from landlord-provided guard services.
Installation services capture the largest one-time contract values while monitoring services climb the fastest as tenants unbundle security from base rent.
End User:
Compliance maturity varies sharply across sectors, with financial institutions facing the most stringent physical access mandates.
- Telecommunications Companies:Carrier-neutral facilities require perimeter hardening for submarine cable landing stations and fiber interconnection points. Telmex and regional carriers drive standardization around unified video and access platforms.
- IT Firms:Hyperscale cloud operators compress procurement cycles for integrated stacks, forcing unified specifications rather than fragmented point solutions.
- Financial Institutions:CNBV regulations mandate biometric capture and audit-trail logging, directly stimulating infrastructure upgrades across banking data centers.
- Government Agencies:Federal and state facilities face INAI data protection requirements with extended procurement timelines.
Financial institutions anchor compliance-driven spending while IT firms expand most quickly through hyperscale facility commissioning.
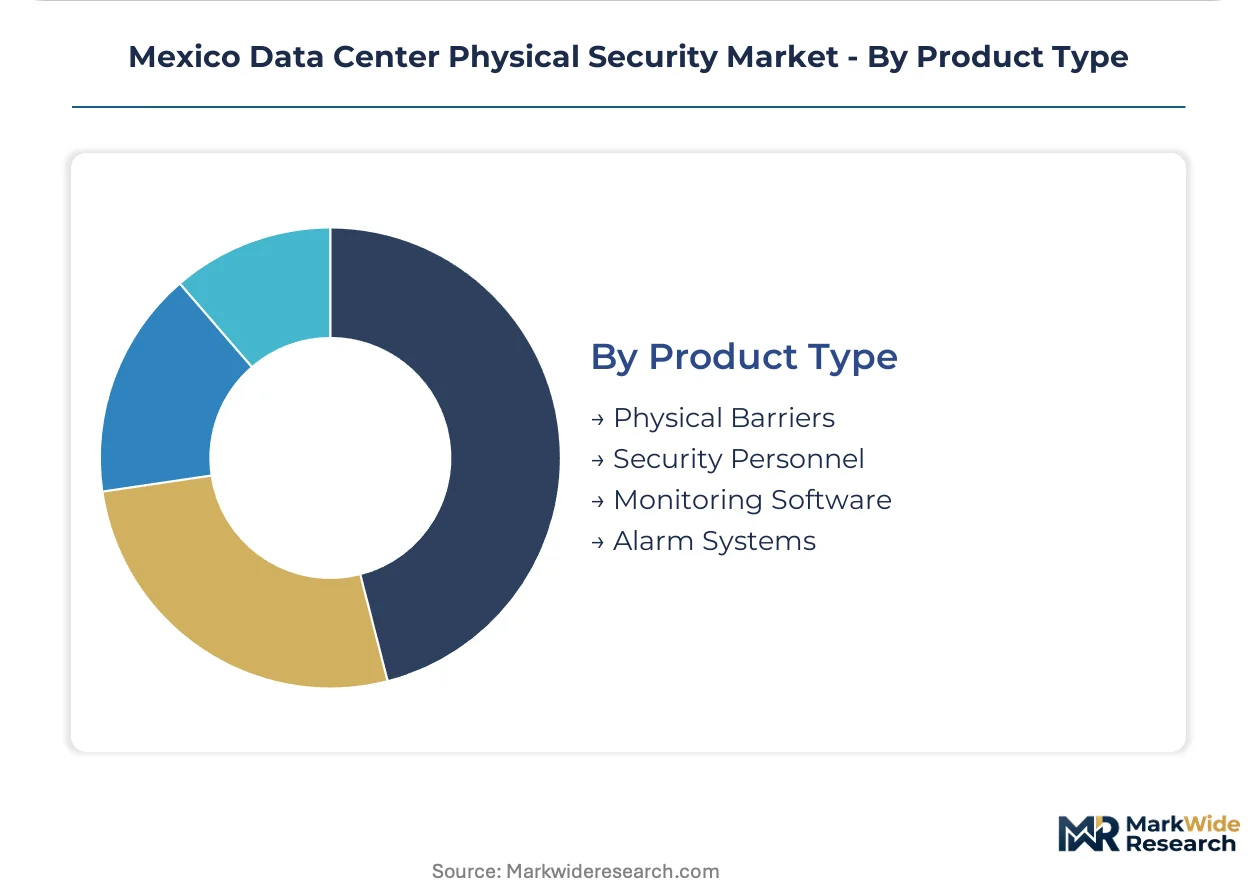
Product Type:
Physical hardware maintains steady demand in greenfield construction as software and personnel face displacement pressure from automation.
- Physical Barriers:Perimeter fencing, server cage mesh, and mantrap entries specified for 72-hour autonomous operation under CONUEE standby power mandates. Copper and steel input volatility squeezes fixed-price construction contracts.
- Security Personnel:Guard counts per facility compress as biometric verification and AI-powered video analytics reduce manual monitoring requirements.
- Monitoring Software:Video management platforms with behavioral recognition algorithms penetrate multi-tenant colocation facilities where tenant count scales monitoring complexity.
- Alarm Systems:Integrated intrusion and environmental threat detection converge with building management systems for efficiency certification.
Physical barriers anchor capital expenditure while monitoring software expands at the steepest trajectory through AI-powered analytics adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility operators in Mexico City absorb the steepest compliance premiums, while Bajío corridor buyers leverage scale economics to compress per-rack security costs. Demand elasticity fractures across sub-regions based on land availability, fiber density, and regulatory enforcement intensity.
Mexico City Metro
Banking data centers under CNBV mandates drive biometric infrastructure density. INAI audit-trail requirements force legacy card-reader replacements across financial institutions. The Santa Fe and Tlalnepantla clusters concentrate premium colocation capacity where compliance costs exceed Bajío benchmarks.
Querétaro and Bajío Corridor
Hyperscale cloud campuses from AWS, Google Cloud, and Microsoft Azure compress procurement cycles for unified access control stacks. CONUEE energy efficiency certifications require 72-hour autonomous surveillance capability at new builds. The El Marqués industrial zone anchors multi-megawatt facility commissioning with standardized perimeter specifications.
Nuevo León
Monterrey's certified integrator concentration creates installation capacity advantages over secondary states. Manufacturing-linked data infrastructure drives demand for environmental threat detection converged with building management. The Apodaca and Santa Catarina sub-markets attract regional bank disaster recovery facilities.
Jalisco
Guadalajara's tech corridor exhibits tenant-driven security unbundling, with SaaS operators contracting directly with specialized monitoring providers. Software-defined surveillance architectures displace landlord-provided guard services. The Zapopan sub-market leads API-enabled platform adoption for multi-tenant facilities.
Yucatán Peninsula
Submarine cable landing stations at Progreso and Cancún create first-mover positioning for hardened perimeter security. Telmex and regional carriers drive standardization around unified video and access platforms. Land availability and lower construction costs attract disaster recovery facilities seeking geographic diversification from central Mexico concentration.
Mexico Data Center Physical Security Market Competitive Landscape
Capability concentration sits with integrated platform specialists; scale advantage sits with global building automation conglomerates. The vendor base stratifies across three tiers: converged power-security platforms, standalone video management software, and certified installation services. Two dominant competitive moves define positioning: cross-selling building management convergence and capturing recurring monitoring contracts through API-enabled platform openness.
Within the integrated platform tier, Schneider Electric and Siemens AG anchor positions through building automation convergence with physical access systems. Genetec occupies a specialist position in video management software for multi-tenant facility unification. These three exemplify the capability-scale trade-off: Schneider and Siemens leverage electrical infrastructure relationships, while Genetec represents pure-play software penetration.
| Leading Market Players |
|---|
| Securitas Technology |
| Genetec |
| Honeywell International Inc |
| Siemens AG |
| Cisco Systems Inc |
| Johnson Controls |
| Milestone Systems A/S |
| Schneider Electric |
| ABB Ltd |
| Others |
Pricing and Supply Chain Analysis
Undercapacity among certified security integrators in Guanajuato and San Luis Potosí is compressing installation timelines and inflating project premiums, forcing buyers toward Mexico City and Monterrey vendors while squeezing margins on fixed-price construction contracts.
Pricing Analysis
Long-term service contracts dominate procurement for hyperscale operators, while project-based pricing persists for greenfield facility builds. Three-tier pricing structure across premium biometric systems, standard IP surveillance, and economy analog retrofits separates banking compliance mandates from cost-sensitive colocation tenants. Pricing pressure stems from copper and steel commodity volatility eroding fixed-margin fencing and cage contracts. SaaS tenants in Guadalajara exhibit the highest price sensitivity as they unbundle monitoring from base rent.
Supply Chain Analysis
Export controls on advanced video analytics chipsets from the United States are constraining edge-computing camera deployments in Mexican hyperscale facilities. Manufacturing concentrates in China for camera assemblies, Taiwan for semiconductor components, and Mexico for perimeter barrier fabrication. The supply chain draws from steel and copper feedstocks subject to commodity price swings, with single-source vulnerability concentrated in biometric sensor modules. Distribution runs through certified integrator networks anchored in Mexico City and Monterrey.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as tenant-driven security unbundling splinters procurement authority away from facility operators toward specialized monitoring providers.
For Market Incumbents: Entrench platform positions by deepening API-enabled openness for tenant-selected monitoring providers and securing CONUEE certification bundling with building management systems. Biometric reader commoditization from Chinese suppliers threatens hardware margins; vertical integration into recurring maintenance contracts defends profitability. For New Entrants and Emerging Players: Build out AI-powered video analytics specialization targeting multi-tenant colocation facilities in Guadalajara's tech corridor where manual monitoring costs scale with tenant count. The Yucatán submarine cable landing station market remains underpenetrated; partner with regional carriers for perimeter hardening specifications. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because security monitoring outsourcing trends align with SaaS tenant growth patterns and compliance audit-trail requirements harden. Target acquisition candidates with SOC 2-aligned operations centers and established CNBV banking relationships. The signal to watch is hyperscale operator consolidation of procurement authority toward unified platform specifications.| Strategic Initiative | Industry Significance |
|---|---|
| API-Enabled Platform Openness | Tenant unbundling demands interoperable access for third-party monitoring providers. |
| CONUEE Certification Bundling | Energy efficiency mandates reward converged building management and security systems. |
| AI Video Analytics Development | Behavioral recognition reduces guard counts while expanding compliance data exhaust. |
| Biometric Infrastructure Retrofit | CNBV mandates force banking data center upgrades from legacy card-reader systems. |
| Yucatán Corridor Expansion | Submarine cable landing stations require hardened perimeter security at underdeveloped sites. |
Research Methodology
Operator-level perspectives from data center facility managers, security system integrators, CNBV compliance officers, and CONUEE certification auditors anchored the qualitative base. Primary interviews combined with secondary validation from INAI regulatory filings, CNBV banking supervision circulars, CONUEE efficiency standard databases, and hyperscaler capital expenditure disclosures. Bottom-up facility counts triangulated against top-down security technology spend estimates.
Scenario-bracketing framed demand projections across the analysis window, modeling technology segmentation by surveillance resolution tiers, access control authentication methods, and service delivery models. End-user splits captured financial institution compliance intensity, hyperscale procurement consolidation, and telecommunications carrier standardization patterns. CAGRs derived from facility commissioning pipelines, replacement cycle compression, and regulatory mandate implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation by global building automation conglomerates would shift outcomes. Material shifts in CNBV physical access logging requirements or CONUEE standby power mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Fault Tolerant Servers Market