
 Chennai Data Center Market | 2026-2036
Chennai Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Chennai Data Center Market Insights
A certified data center engineering workforce shortage is unwinding expansion timelines for several operators in Tamil Nadu. NTT Global Data Centers leverages its hyperscale design playbook to compete for cloud anchor tenants along the OMR corridor. CtrlS Datacenters sustains uptime leadership through its Tier-IV certified facilities, while STT GDC India anchors its South India strategy with carrier-neutral interconnection hubs in Sriperumbudur.
A data center constitutes a purpose-built facility housing servers, storage systems, and network equipment with controlled environmental parameters including power usage effectiveness below 1.5 and ambient temperature maintained within 18-27 degrees Celsius for optimal compute performance. Colocation services command the deepest margin pools as enterprises divest owned infrastructure, while cloud computing segments absorb the fastest capacity additions from SaaS providers and AI training workloads. Disaster recovery services within the service type dimension are gaining traction as BFSI end users mandate geographically separated backup sites under regulatory directives.
India's Ministry of Electronics and Information Technology enforces data localization norms through the Digital Personal Data Protection Act, compelling foreign cloud providers to establish domestic facilities. The Central Electricity Authority mandates dual power feed and diesel generator backup standards for critical IT infrastructure, raising capital intensity for new entrants. Stakeholders must weigh land acquisition costs in Chennai's encroaching industrial zones against the latency advantages of proximity to submarine cable landing stations.
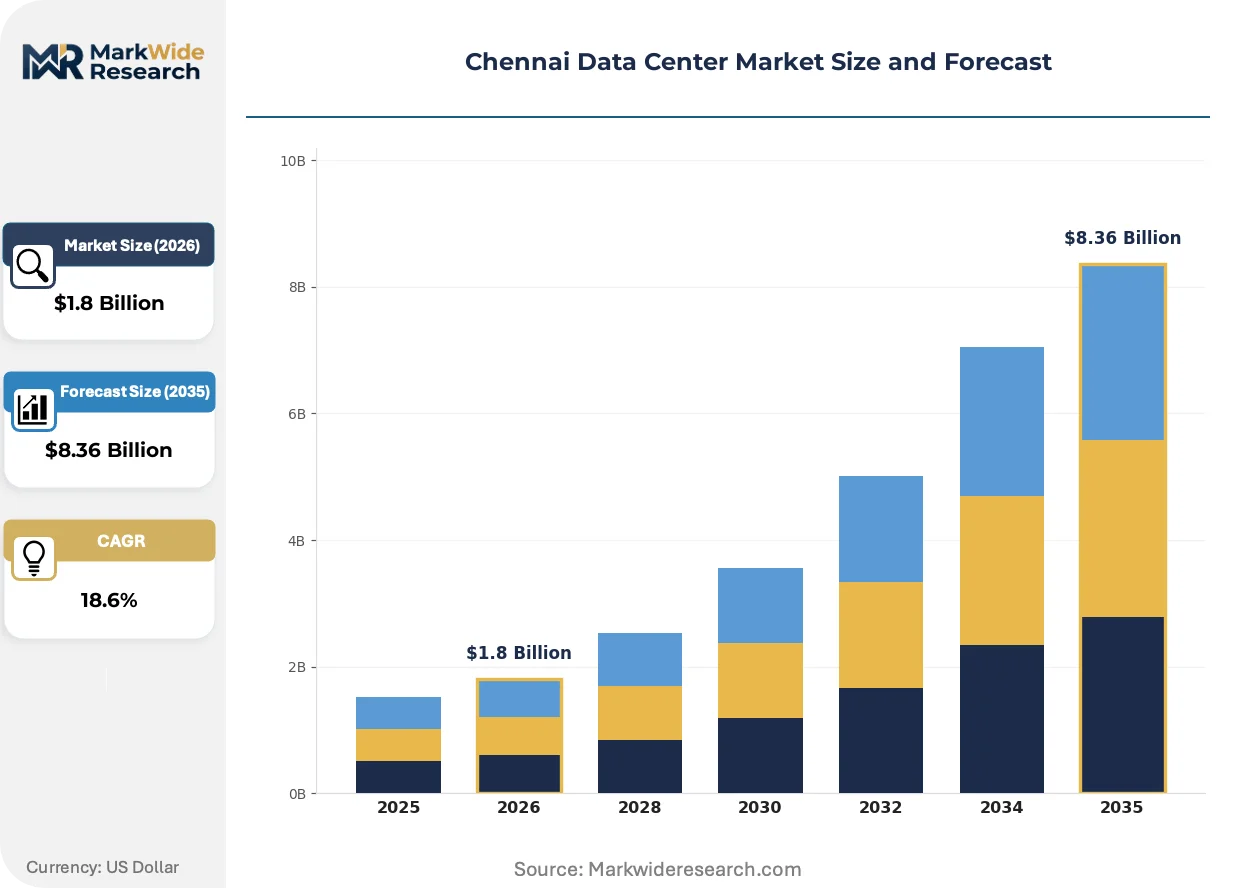
Market Dynamics
The Digital Personal Data Protection Act compels foreign cloud providers to establish domestic facilities, triggering a compliance-driven construction surge along Chennai's OMR corridor and Sriperumbudur industrial belt.
Growth Catalysts
- Data Localization Mandates:India's Digital Personal Data Protection Act requires foreign SaaS providers to store citizen data within national boundaries, forcing hyperscale commitments to Tamil Nadu.
- BFSI Captive Expansion:Banking and insurance institutions are building owned facilities to satisfy RBI guidelines on geographically separated disaster recovery sites.
- Submarine Cable Proximity:Chennai's landing stations for transoceanic fiber links deliver sub-50 millisecond latency to Singapore and Europe, attracting AI training workloads.
Market Restraints
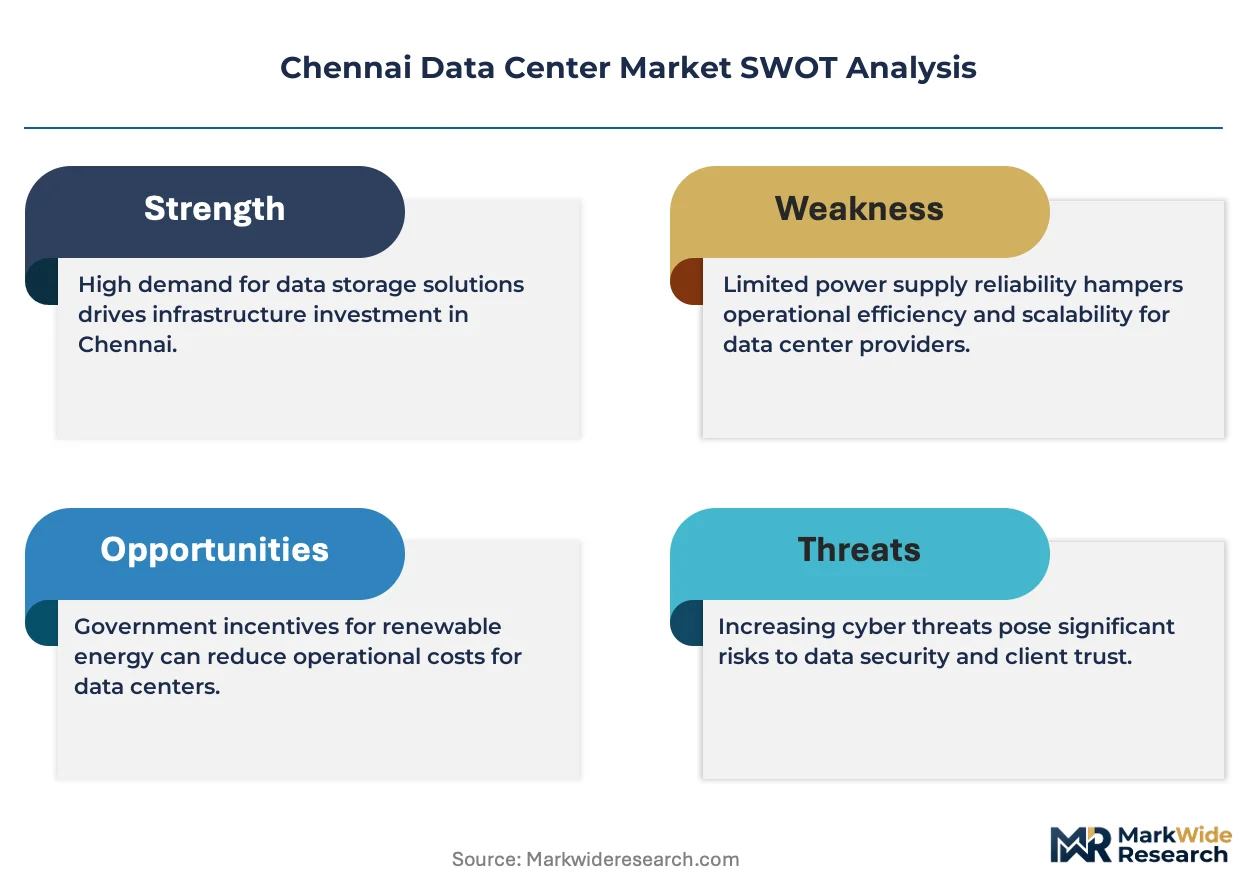
- Land Cost Escalation:Industrial zone encroachment in Sriperumbudur has pushed per-acre acquisition costs beyond viable returns for Tier-II operators.
- Power Infrastructure Bottlenecks:Tamil Nadu Generation and Distribution Corporation's grid reliability forces diesel generator redundancy that raises capital intensity.
- Certified Workforce Scarcity:Uptime Institute-certified engineers command 40 percent wage premiums, stretching operator payroll structures.
Strategic Opportunities
- Edge Computing Nodes:Tamil Nadu's manufacturing clusters in Coimbatore and Hosur present underpenetrated demand for sub-10 megawatt distributed facilities.
- Liquid Cooling Convergence:Direct-to-chip cooling systems combined with AI workload densities enable power usage effectiveness below 1.2 in new builds.
- Green Hydrogen Pilots:The state's renewable energy obligations open pathways for fuel-cell backup systems replacing diesel generators.
Industry Challenges
- Tier-IV Certification Timelines:Uptime Institute's design and construction review processes extend commissioning schedules by 8-14 months.
- Legacy Interconnection Complexity:Enterprises migrating from self-managed server rooms struggle with cross-connect provisioning in carrier-neutral facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chennai Data Center Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Colocation, Managed Hosting, Hybrid Solutions End User: IT & Telecom, BFSI, Retail, Government Service Type: IT Infrastructure, Disaster Recovery, Network Services, Security Services Size: Small, Medium, Large, Enterprise |
| Companies Covered | NTT Global Data Centers, CtrlS Datacenters, STT GDC India, Equinix, AdaniConneX, Sify Technologies, Reliance Data Centers, Tata Communications, Nxtra by Airtel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chennai Data Center Market Trends and Innovations
Hyperscale design principles are penetrating mid-market facilities, while sustainability mandates and AI workload densities are rewiring mechanical and electrical infrastructure specifications across Tamil Nadu.
Modular data center architecture is decomposing traditional monolithic construction in Chennai's OMR corridor. Cloud service providers are specifying factory-integrated power and cooling modules for 12-week deployment cycles. This prefabrication trend is compressing the competitive window for conventional design-build contractors.
The Central Electricity Authority's dual power feed mandate is reshaping electrical topology in new Tamil Nadu facilities. Operators must provision independent grid connections with automatic transfer switching, raising switchgear costs but eliminating single-point-of-failure vulnerabilities. Tier-IV aspirants are responding with 2N transformer configurations that exceed baseline compliance.
Consumption-based power pricing is altering colocation contract structures in Chennai's wholesale market. Enterprises are abandoning flat-rate kilowatt allocations for metered usage tied to actual IT load, transferring operational risk to operators. This shift is most pronounced among BFSI tenants with seasonal compute volatility.
Chennai Data Center Market Segmentation
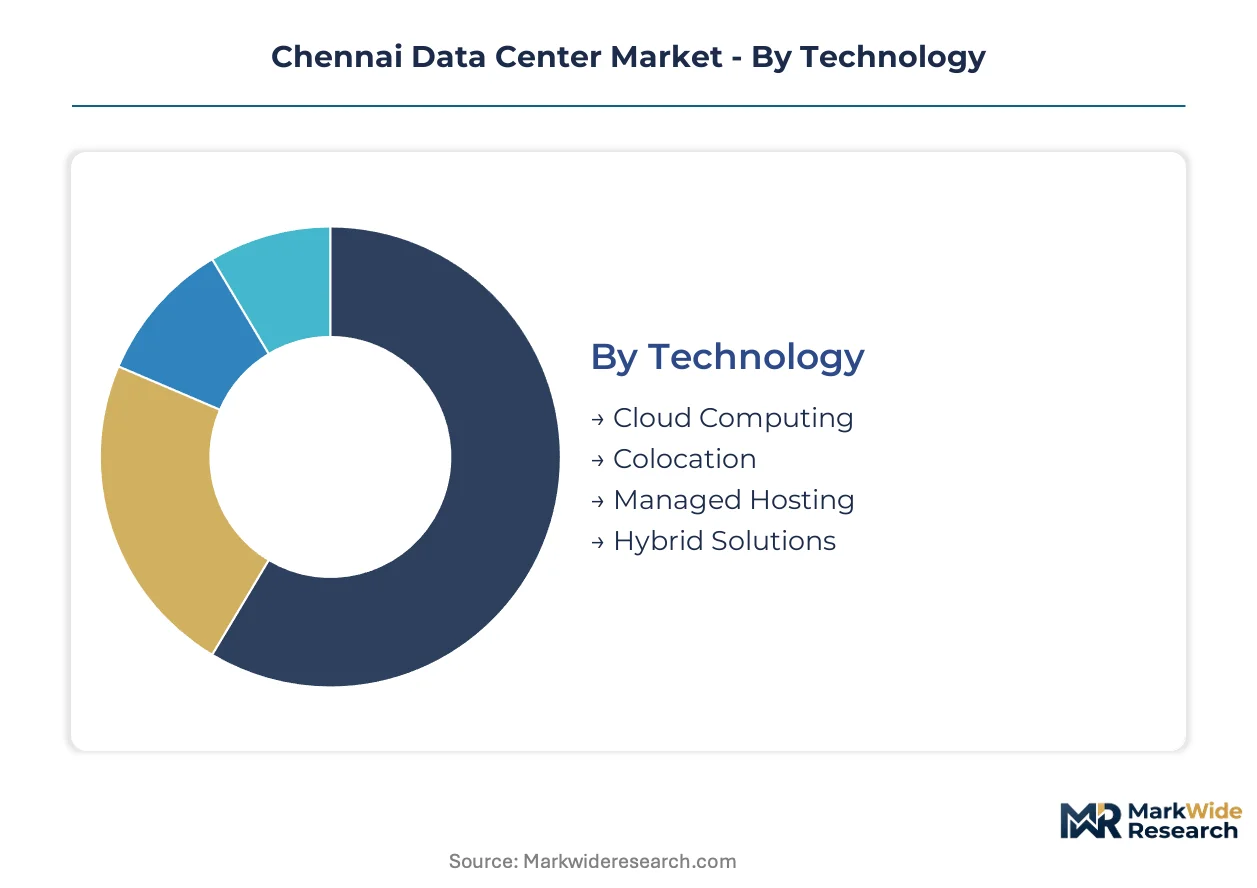
Segmentation in the Chennai data center market reveals how regulatory mandates and workload densities are fragmenting demand across deployment models and customer tiers. Understanding these divisions exposes where capital concentrates and which service lines absorb compliance-driven investments.
Technology:
Domestic demand anchors Colocation and Managed Hosting as enterprises shed owned infrastructure, while Cloud Computing attracts export-linked hyperscale commitments from foreign SaaS providers.
- Colocation:Enterprises lease rack space, power, and cooling in third-party facilities while retaining hardware ownership. BFSI institutions in Chennai's OMR corridor are consolidating self-managed server rooms into Tier-IV certified colocation floors to satisfy RBI disaster recovery mandates.
- Cloud Computing:Hyperscale providers deliver virtualized compute, storage, and networking via subscription models. Foreign cloud operators are building dedicated Chennai regions to comply with India's Digital Personal Data Protection Act data localization requirements.
- Managed Hosting:Operators assume full infrastructure management responsibility including hardware procurement and patch management. Retail chains in Tamil Nadu favor this model for predictable operational expenditure without internal IT specialization.
- Hybrid Solutions:Architectures blend on-premises infrastructure with public cloud bursting for variable workloads. Manufacturing clusters in Coimbatore and Hosur deploy hybrid configurations to keep sensitive production data local while tapping cloud elasticity.
Colocation commands the established base. The steepest expansion runs through Cloud Computing.
End User:
Cost tier differentiation separates captive BFSI facilities from shared infrastructure serving price-sensitive government and retail segments.
- BFSI:Banking, insurance, and financial services institutions operate the most demanding uptime requirements. RBI guidelines mandating geographically separated disaster recovery sites are driving dedicated facility construction in Sriperumbudur.
- IT & Telecom:Technology vendors and telecommunications carriers require dense interconnection and low-latency fiber access. Submarine cable landing stations in Chennai attract these operators for sub-50 millisecond connectivity to Singapore.
- Government:State and central government entities procure through tender processes with heavy weighting on domestic content requirements. Tamil Nadu's state data center consolidation program is absorbing capacity in certified facilities.
- Retail:E-commerce and brick-and-mortar chains demand seasonal capacity scaling for festival-period traffic spikes. Consumption-based pricing models are penetrating this segment fastest.
BFSI absorbs the premium tier. Retail is climbing the fastest.
Service Type:
Volume concentration clusters in foundational infrastructure layers, while margin pools deepen around specialized resilience and security offerings.
- IT Infrastructure:Core compute, storage, and virtualization resources form the baseline service layer. Every Chennai facility regardless of tier provisions this category.
- Disaster Recovery:Geographically separated backup sites with synchronous replication and automated failover. BFSI regulatory directives are accelerating dedicated DR facility construction across Tamil Nadu.
- Network Services:Cross-connects, internet exchange access, and managed WAN optimization. Carrier-neutral facilities in Sriperumbudur compete on interconnection density.
- Security Services:DDoS mitigation, managed firewalls, and compliance auditing. The Digital Personal Data Protection Act is expanding procurement of these add-on services.
IT Infrastructure commands the established base. Disaster Recovery is gaining share fastest.
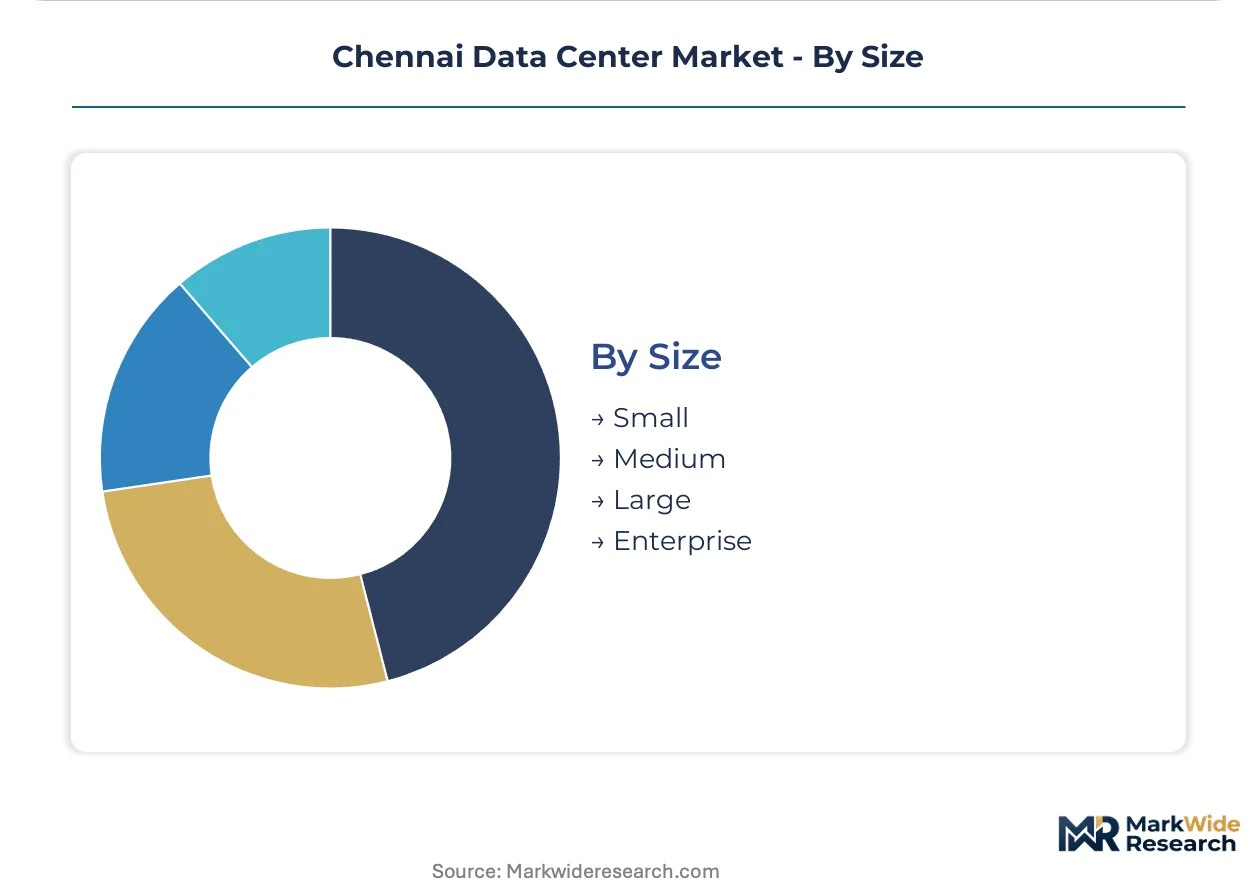
Size:
Customer type and maturity separate self-built enterprise campuses from multi-tenant facilities serving fragmented small and medium demand.
- Enterprise:Dedicated facilities exceeding 10 megawatts designed for single-tenant occupancy. Hyperscale cloud providers and large BFSI institutions are commissioning these builds in Chennai's industrial belt.
- Large:Wholesale colocation contracts spanning full data halls with long-term lease commitments. NTT Global Data Centers and STT GDC India compete aggressively for these anchor tenants.
- Medium:Partial rack or cage deployments with 100-500 kilowatt power commitments. Regional IT services firms and mid-market manufacturers populate this tier.
- Small:Individual rack or fractional rack rentals below 100 kilowatts. Startups and professional services firms in Chennai's OMR corridor cluster here.
Enterprise commands the established base. Medium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Land acquisition premiums in Sriperumbudur now exceed viable returns for Tier-II operators, while the OMR corridor retains pricing power through submarine cable proximity and hyperscale tenant concentration.
OMR Corridor
Cloud service providers and AI training workloads drive demand along this 45-kilometer stretch. The Tamil Nadu government's IT policy incentives accelerate facility approvals for certified data centers. Taramani and Perungudi sub-markets host the densest concentration of carrier-neutral interconnection hubs.
Sriperumbudur Industrial Belt
Banking and insurance institutions commission dedicated disaster recovery campuses to satisfy RBI guidelines on geographic separation. The Central Electricity Authority's dual power feed mandate shapes electrical topology in new builds. Oragadam and Sunguvarchatram industrial zones absorb enterprise-scale commitments exceeding 10 megawatts.
Coimbatore
Manufacturing clusters generate underpenetrated demand for sub-10 megawatt edge computing nodes. State renewable energy obligations open pathways for fuel-cell backup pilots replacing diesel generators. Peelamedu and Sulur industrial estates present distributed facility opportunities with lower land costs than Chennai metro.
Hosur
Automotive and electronics manufacturing supply chains require hybrid cloud architectures keeping sensitive production data local. The Digital Personal Data Protection Act amplifies procurement of security and compliance auditing services. Krishnagiri district's industrial corridors attract medium-scale colocation deployments from regional IT services firms.
Madurai
Government data center consolidation programs absorb capacity in certified facilities serving state administrative functions. Tender processes weight heavily on domestic content requirements and uptime certification grades. Thirumangalam and Kappalur industrial areas host emerging small-scale deployments below 100 kilowatts.
Chennai Data Center Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Tamil Nadu's data center market. Tier-IV certified operators command premium positioning through uptime guarantees, while wholesale colocation specialists compete on speed-to-market and modular deployment cycles. The competitive terrain separates into three strategic archetypes: hyperscale design specialists, carrier-neutral interconnection platforms, and captive infrastructure arms of telecommunications conglomerates. Capacity expansion and certification-driven portfolio upgrades constitute the dominant competitive moves, with operators racing to commission facilities before land cost escalation erodes project returns.
Among Japanese-origin hyperscale specialists, NTT Global Data Centers occupies a position exemplifying the design-playbook approach to cloud anchor tenant acquisition. Indian Tier-IV certified operators CtrlS Datacenters and STT GDC India represent contrasting archetypes within the resilience-focused tier, with the former anchoring uptime leadership and the latter situating carrier-neutral interconnection at the core of South India strategy. These three entities collectively illustrate how foreign capital deployment, domestic certification excellence, and regional interconnection density compete for differentiated positioning along Chennai's OMR corridor and Sriperumbudur industrial belt.
| Leading Market Players |
|---|
| NTT Global Data Centers |
| CtrlS Datacenters |
| STT GDC India |
| Equinix |
| AdaniConneX |
| Sify Technologies |
| Reliance Data Centers |
| Tata Communications |
| Nxtra by Airtel |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with hyperscale cloud providers lock in both switchgear supply access and power cost visibility across Tamil Nadu's OMR corridor. These multi-year commitments insulate Tier-IV operators from spot-market volatility in diesel generator sets and liquid cooling infrastructure.
Pricing Analysis
The customization-premium spread separates configured-to-order Tier-IV certified floors from standard colocation rack space. Pricing stratifies across Tier-IV premium, Tier-III standard, and uncertified economy tiers based on uptime certification grade and power density commitments. Cost compression in the economy tier is intensifying because hyperscale providers are absorbing wholesale capacity at scale. Retail chains and professional services firms exhibit the highest price sensitivity, while BFSI institutions prioritize certification grade over unit economics.
Supply Chain Analysis
Inbound logistics costs through Chennai Port congestion and container availability constraints on Asia-Pacific trade lanes elevate switchgear and precision cooling equipment lead times. Supply concentrates in China for electrical switchgear, Germany for precision cooling systems, and South Korea for semiconductor-grade power components. Raw material dependencies span copper busbars, lithium-ion battery cells for UPS systems, and specialized refrigerants for direct-to-chip cooling. Single-source vulnerability runs through Chinese electrical equipment suppliers subject to India's BIS quality certification mandates. Distribution runs through EPC contractors and specialized data center infrastructure integrators serving the OMR corridor and Sriperumbudur industrial belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chennai data center market operates as a defensive-moat story anchored in regulatory entrenchment. India's Digital Personal Data Protection Act and RBI disaster recovery mandates create high switching costs for certified facility tenants.
For Market Incumbents: Consolidate carrier-neutral interconnection density in Sriperumbudur to defend against emerging hyperscale build-to-suit competitors. Acquire land reserves in Coimbatore and Hosur before industrial zone encroachment erodes project returns. Vertical integration into renewable energy procurement secures power cost advantages under Tamil Nadu's green hydrogen pilot programs. For New Entrants and Emerging Players: Anchor in edge computing nodes below 10 megawatts serving Coimbatore's manufacturing clusters and Hosur's automotive supply chains. The medium-scale colocation tier presents the most penetrable white space, with regional IT services firms demanding certified facilities outside Chennai metro pricing zones. A modular deployment go-to-market angle compresses commissioning schedules against incumbent construction timelines. For Investors and Strategic Acquirers: Carrier-neutral platform operators with existing submarine cable landing station access represent the priority acquisition archetype. Long-term viability hinges on land bank depth and power purchase agreement structures across the projection horizon. Watch for inflection when hyperscale providers shift from leased colocation to owned campus development in Tamil Nadu.| Strategic Initiative | Industry Significance |
|---|---|
| Tier-IV Certification Investment | Uptime Institute design review validates premium pricing power for BFSI disaster recovery mandates. |
| Modular Deployment Architecture | Factory-integrated power modules compress 12-week commissioning cycles against conventional construction. |
| Carrier-Neutral Interconnection Expansion | Cross-connect density in Sriperumbudur attracts IT and Telecom tenants seeking sub-50 millisecond Singapore latency. |
| Green Hydrogen Backup Pilot | Tamil Nadu renewable energy obligations open fuel-cell pathways replacing diesel generator redundancy. |
| Land Bank Acquisition in Secondary Markets | Coimbatore and Hosur industrial estates offer lower acquisition costs than Chennai metro encroachment zones. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with data center facility directors, cloud procurement officers at hyperscale tenants, Tamil Nadu electricity board planning engineers, and Uptime Institute certification auditors. Secondary validation drew from Central Electricity Authority grid reliability reports, TRAI telecom infrastructure disclosures, RBI circulars on disaster recovery compliance, and customs data on electrical equipment imports. Bottom-up capacity installation tracking and top-down BFSI IT spend analysis were triangulated against hyperscale cloud provider capex disclosures.
Across the analysis window, the forecasting framework modeled technology deployment mode, end-user vertical, facility size tier, and service type complexity alongside geographic cluster adoption patterns. CAGRs were derived from installed base growth rates and average selling price trajectories by certification grade. Industry-specific inputs included Tamil Nadu Generation and Distribution Corporation reliability statistics and submarine cable landing station capacity expansion timelines.
Underlying assumptions cover sustained data localization enforcement, grid stability within Central Electricity Authority dual-feed mandates, and hyperscale cloud provider commitment continuity, with deviation risk concentrated in land acquisition cost escalation and certified engineer wage inflation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Switzerland Data Center Construction Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Japan Data Center Power Market