
 US Data Center Rack Market | 2026-2036
US Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
US Data Center Rack Market Insights
Managed power and cooling subscription services is recalibrating how rack vendors monetize physical infrastructure. Schneider Electric leverages its integrated software-defined power management platform to anchor recurring revenue streams alongside hardware sales. Vertiv competes through thermal management specialization that sustains premium positioning in high-density deployments. Dell Technologies differentiates via factory-integrated rack systems that compress deployment timelines for enterprise buyers.
Data center racks are standardized steel or aluminum enclosure frameworks designed to mount servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D specifications for width and vertical rack unit spacing. Their primary purpose is to organize IT hardware into scalable, serviceable rows that optimize airflow, cable management, and physical security within conditioned white spaces. Open frame configurations lead unit volume due to cost efficiency and unrestricted airflow for low-density workloads, while liquid cooling rack segments capture expanding margin pools as thermal loads exceed 30 kilowatts per cabinet. Enclosed racks maintain steady demand from government and financial end users prioritizing physical security compliance, whereas wall-mounted variants occupy niche edge computing installations with severe floor space constraints.
ASHRAE publishes thermal guidelines that directly shape rack airflow engineering and materials selection for US-manufactured products. OSHA workplace safety standards and NFPA electrical codes govern installation practices and grounding requirements in domestic facilities. NIST cybersecurity frameworks increasingly influence rack-level access control and monitoring specifications for federal contracts. Stakeholders must monitor how state-level clean energy mandates in Virginia, Texas, and Arizona reshape power density requirements and cooling technology choices in new construction.
Market Dynamics
Hyperscale cloud providers are compressing deployment cycles for liquid-ready rack architectures across Virginia and Texas campuses, forcing incumbent vendors to reconfigure factory integration workflows and thermal engineering capabilities to match 30+ kilowatt density thresholds.
Growth Catalysts
- NIST Cybersecurity Frameworks:Federal contractors now mandate rack-level access logging and biometric authentication, expanding specification requirements for enclosed cabinet segments serving government end users.
- ASHRAE Thermal Guidelines:Updated liquid cooling compatibility standards are accelerating retrofit demand in legacy enterprise colocation facilities across Northern Virginia's Data Center Alley cluster.
- Texas Clean Energy Mandates:State-level renewable power requirements in Dallas-Fort Worth and Austin metro areas are driving rack purchases with integrated power monitoring for carbon accounting compliance.
Market Restraints
- Steel Input Volatility:Cold-rolled steel price fluctuations compress margin pools for open-frame rack manufacturers serving cost-sensitive wholesale colocation operators.
- Regional Supply Concentration:Domestic cabinet fabrication capacity concentrates in southeastern states, creating logistics bottlenecks for rapid-turn hyperscale deployments in western markets.
- NFPA Electrical Code Friction:Evolving grounding and arc-fault requirements extend site certification timelines, delaying revenue recognition for rack-plus-power integrated shipments.
Strategic Opportunities
- Edge Computing Wall-Mount Expansion:5G network densification in secondary US metros creates demand for compact, NEMA-rated enclosures with integrated thermal management for outdoor telecommunications huts.
- Subscription Service Models:Power and cooling monitoring as recurring revenue streams allows vendors to capture lifetime value beyond initial hardware transactions in enterprise accounts.
- OSHA-Compliant Installation Services:Workplace safety training and certified rigging programs address liability concerns in multi-tenant facilities with frequent equipment swaps.
Industry Challenges
- Liquid Cooling Plumbing Integration:Factory-installed coolant distribution units demand specialized technician skills scarce in traditional electrical contracting workforces serving data center construction.
- Multi-Vendor Interoperability Testing:Hyperscale buyers require pre-validated rack-power-cooling bundles, forcing coordination across previously independent supplier tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Data Center Rack Market |
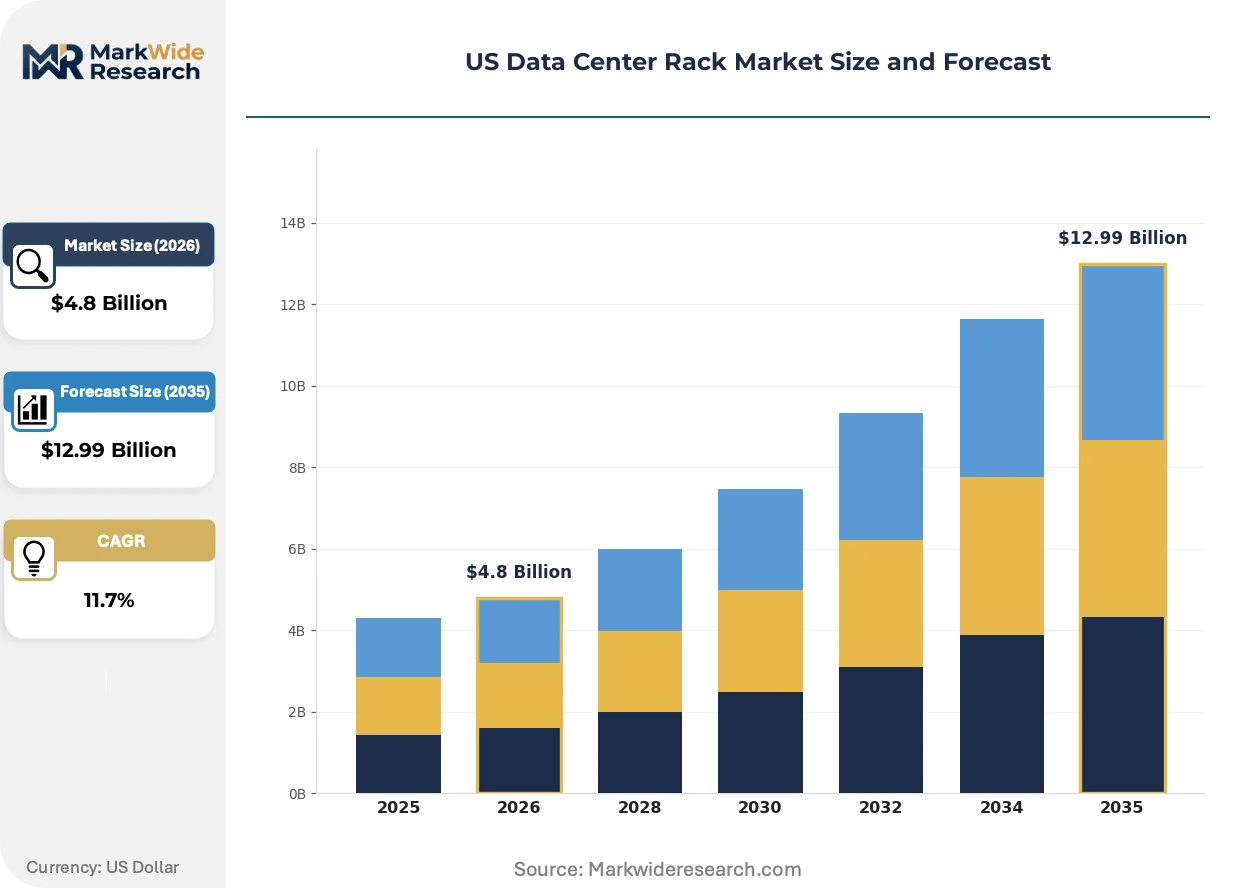
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Racks, Wall-Mounted Racks, Rack Accessories Cooling Technology: Air Cooling, Liquid Cooling, Hybrid Cooling, Immersion Cooling End User: Enterprises, Colocation Providers, Government, Cloud Service Providers Installation Type: On-premise, Pre-fabricated, Modular, Custom-built |
| Companies Covered | Rittal, Dell Technologies, Schneider Electric, Black Box Corporation, IBM, Hewlett Packard Enterprise, Vertiv, Panduit, Eaton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Data Center Rack Market Trends and Innovations
Rack architecture is converging around thermal and power management as unified design variables rather than separate specification threads. Vendors now engineer for density headroom that exceeds current deployment needs by 40-50% to accommodate generational server upgrades without structural replacement.
Immersion cooling tank systems are consolidating secondary containment and heat rejection infrastructure into single-footprint modules. Hyperscale operators in Phoenix and Las Vegas are adopting these configurations for AI training clusters exceeding 50 kilowatts per rack. Factory integration of dielectric fluid reservoirs and dry cooler connections is compressing field installation from weeks to days.
FERC Order 2222 implementation is reshaping how rack-level power distribution units communicate with grid operators. Battery-backed cabinet architectures in Texas ERCOT territory now participate in frequency regulation markets, requiring UL 1973-certified energy storage integration. Colocation providers are re-specifying PDUs with bidirectional power flow capabilities to capture demand response revenue streams.
Enterprise procurement teams are unbundling rack hardware from installation and commissioning services. Direct sourcing through manufacturer digital platforms displaces traditional distribution channels for standardized open-frame configurations. Financial services buyers in New York and Chicago metro markets now specify factory witness testing and pre-shipment validation to compress site acceptance protocols.
US Data Center Rack Market Segmentation
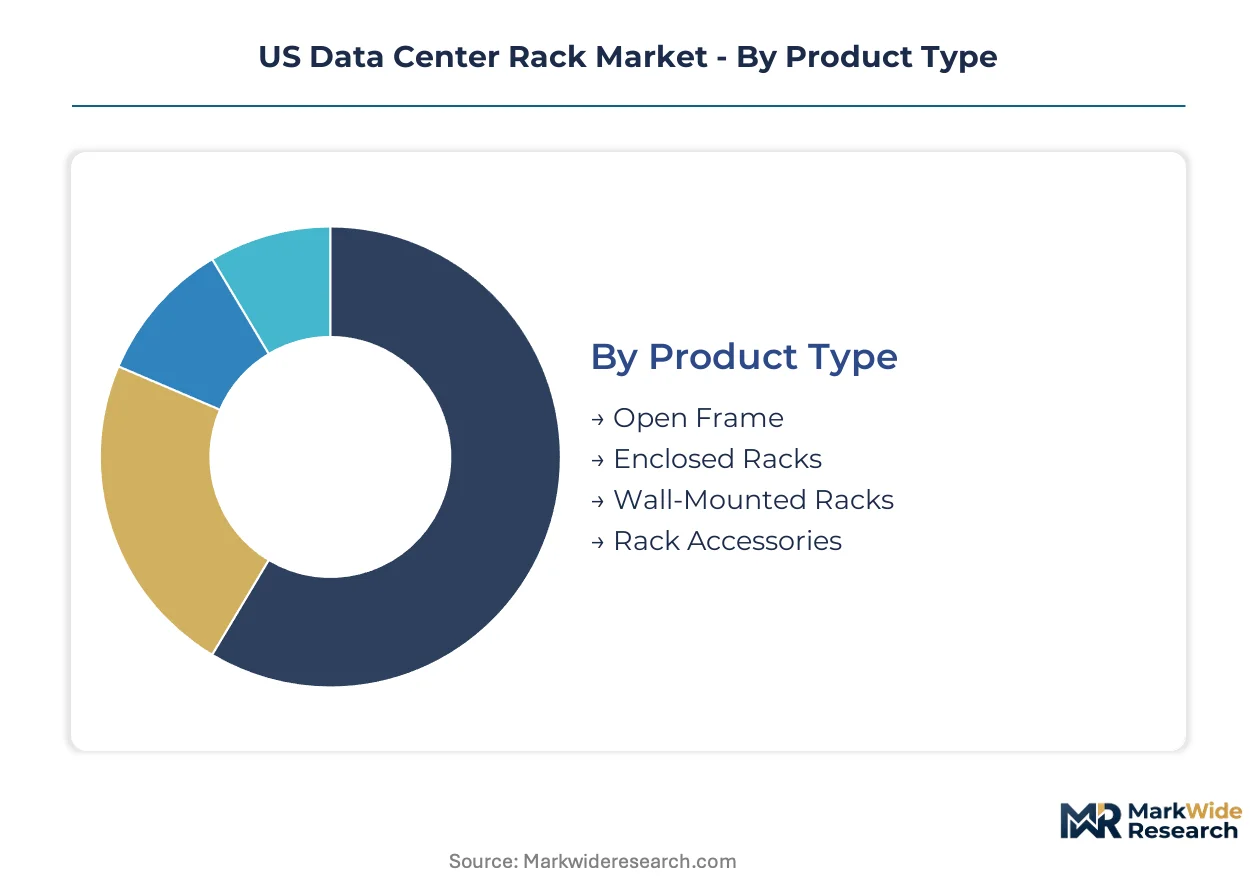
Segmentation reveals how certification burdens and thermal specifications fragment procurement patterns across federal, enterprise, and hyperscale buyer pools. Rack architecture choices cascade through cooling infrastructure decisions, installation timelines, and long-term upgrade pathways.
Product Type:
NIST cybersecurity frameworks mandate biometric access logging for enclosed cabinets serving federal contracts, while OSHA rigging standards govern open-frame installations in multi-tenant facilities.
- Open Frame:Unenclosed steel or aluminum structures maximize airflow for sub-30 kilowatt densities. Wholesale colocation operators in Dallas-Fort Worth specify these configurations to minimize capital expenditure per rack position while maintaining ASHRAE thermal compliance.
- Enclosed Racks:Lockable cabinets with integrated side panels and front/rear doors satisfy NIST 800-53 physical access controls. Government end users in Northern Virginia's Data Center Alley cluster require these specifications for classified workload containment, extending procurement cycles by 60-90 days for security validation.
- Wall-Mounted Racks:Compact NEMA-rated enclosures serve 5G telecommunications huts with severe floor space constraints. Secondary US metros including Indianapolis and Nashville drive demand for integrated thermal management in these configurations.
- Rack Accessories:Cable management arms, blanking panels, and vertical PDU mounting brackets complete airflow optimization. These components carry lower regulatory burden than primary cabinet structures.
Leading the category by volume: Open Frame. Growing fastest: Enclosed Racks.
Cooling Technology:
Cost tiers separate legacy air-cooled infrastructure from liquid-ready architectures commanding 40-60% capital premiums.
- Air Cooling:Conventional raised-floor perimeter cooling dominates legacy enterprise facilities. These systems face retrofit pressure as server power densities climb past 15 kilowatts per cabinet in Phoenix and Las Vegas campuses.
- Liquid Cooling:Direct-to-chip cold plates and rear-door heat exchangers capture expanding margin pools. Hyperscale operators in Texas and Virginia now specify liquid-ready rack architectures for AI training clusters exceeding 30 kilowatt density thresholds.
- Hybrid Cooling:Combined air and liquid infrastructure preserves optionality for mixed-density deployments. Colocation providers favor this approach to accommodate diverse tenant requirements without full infrastructure replacement.
- Immersion Cooling:Dielectric fluid tank systems consolidate secondary containment and heat rejection into single-footprint modules. Factory integration compresses field installation timelines from weeks to days for extreme-density AI workloads.
Volume concentration: Air Cooling. Steepest expansion trajectory: Liquid Cooling.
End User:
Procurement authority fragments across capital expenditure budgets, operating expenditure models, and federal appropriations cycles.
- Enterprises:Financial services and healthcare buyers in New York and Chicago metros specify factory witness testing and pre-shipment validation. These requirements compress site acceptance protocols but extend procurement lead times.
- Colocation Providers:Multi-tenant operators balance standardization against customization demands. Their procurement emphasizes rapid-turn deployment capability and modular power density headroom.
- Government:Federal contracts mandate NIST-compliant rack-level access control and biometric authentication. Security validation extends sales cycles but locks in multi-year maintenance revenue streams.
- Cloud Service Providers:Hyperscale buyers compress deployment cycles through pre-validated rack-power-cooling bundles. Their factory integration requirements force coordination across previously independent supplier tiers.
Dominant volume: Colocation Providers. Fastest share gain: Cloud Service Providers.
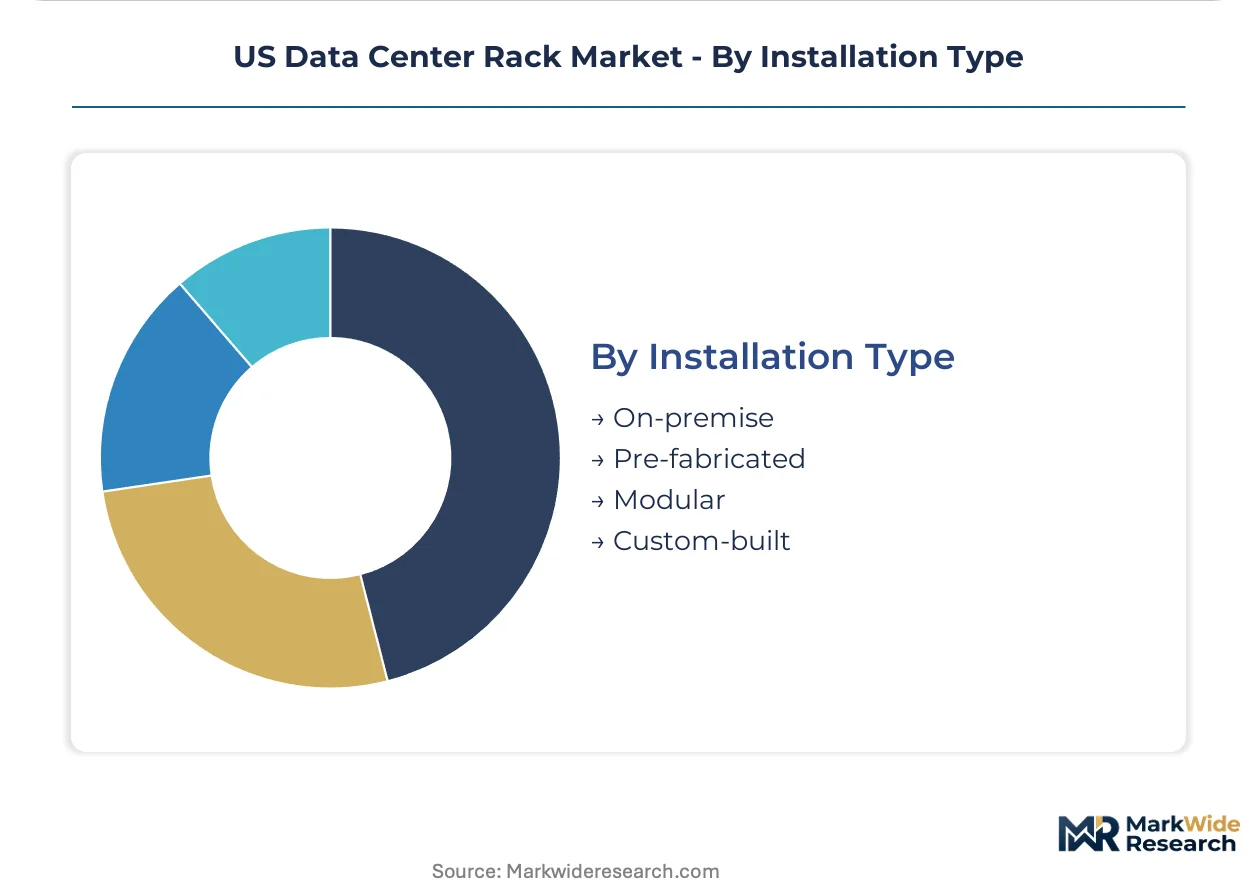
Installation Type:
Geographic concentration of fabrication capacity in southeastern states creates logistics arbitrage between domestic manufacturing and field assembly models.
- On-premise:Traditional stick-built construction allows maximum customization for specialized workloads. These projects face extended timelines due to NFPA electrical code grounding and arc-fault certification requirements.
- Pre-fabricated:Factory-integrated rack systems compress deployment timelines for enterprise buyers. Dell Technologies and Schneider Electric anchor recurring revenue streams through pre-configured power and cooling bundles.
- Modular:Standardized pod architectures enable rapid capacity expansion in land-constrained markets. These configurations align with Texas clean energy mandates through integrated power monitoring for carbon accounting compliance.
- Custom-built:Purpose-engineered structures address unique physical constraints or extreme density requirements. Liquid cooling plumbing integration demands specialized technician skills scarce in traditional electrical contracting workforces.
Highest deployment count: On-premise. Climbing the fastest: Pre-fabricated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's Data Center Alley anchors domestic rack deployment activity, with Loudoun County alone hosting over one hundred operational facilities. This concentration shapes supplier logistics, installation workforce deployment, and regulatory compliance patterns across the national market.
Virginia
Hyperscale cloud providers compress deployment cycles for liquid-ready architectures across Loudoun and Prince William counties. NIST cybersecurity frameworks mandate rack-level access logging for federal contractors operating near DC intelligence corridors. Data Center Alley clusters drive specification requirements that cascade to vendor engineering teams nationwide.
Texas
Dallas-Fort Worth and Austin metro areas absorb expanding hyperscale campus investments from cloud service providers. ERCOT grid participation rules under FERC Order 2222 reshape power distribution unit specifications for frequency regulation markets. Rack purchases integrate carbon accounting monitoring to satisfy state-level clean energy procurement mandates.
Arizona
Phoenix and Las Vegas desert campuses adopt immersion cooling tank systems for AI training clusters exceeding fifty kilowatt densities. ASHRAE thermal guidelines accelerate retrofit demand as legacy air-cooled infrastructure faces density pressure. Factory-integrated dielectric fluid reservoirs compress field installation timelines from weeks to days.
Illinois
Chicago financial services buyers specify factory witness testing and pre-shipment validation protocols for enterprise rack procurement. NFPA electrical code grounding requirements extend site certification timelines for integrated rack-plus-power shipments. The metro's colocation density sustains demand for rapid-turn deployment capabilities.
California
Bay Area hyperscale operators and Los Angeles media streaming facilities drive high-density rack specifications. OSHA workplace safety standards govern installation practices in multi-tenant facilities with frequent equipment swaps. State energy efficiency regulations influence thermal management technology selection for new construction.
US Data Center Rack Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the rack manufacturing value chain. The vendor base separates between integrated infrastructure conglomerates and specialized thermal engineering houses. Three archetypes dominate: diversified electrical equipment conglomerates with captive rack fabrication, pure-play thermal management specialists, and server OEMs with factory-integrated cabinet offerings. Competitive moves concentrate on pre-validated bundle partnerships and liquid cooling engineering acquisitions.
Within the diversified infrastructure tier, Schneider Electric and Eaton occupy positions spanning power distribution through thermal management. Vertiv exemplifies the thermal specialization archetype with focused engineering depth in high-density cooling applications. Dell Technologies represents server OEM vertical integration into rack systems, compressing deployment timelines through factory pre-configuration. These three anchors illustrate how competitive positioning fragments across integration depth rather than geographic coverage.
| Leading Market Players |
|---|
| Rittal |
| Dell Technologies |
| Schneider Electric |
| Black Box Corporation |
| IBM |
| Hewlett Packard Enterprise |
| Vertiv |
| Panduit |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
Liquid-ready rack architecture migration simultaneously compresses cost economics for high-density deployments and concentrates supply relationships around specialized thermal engineering partners. Factory integration of coolant distribution units and dielectric fluid reservoirs shifts value capture toward vendors with captive fabrication capabilities, while open-frame manufacturers serving wholesale colocation face margin compression from steel input volatility.
Pricing Analysis
Uptime guarantees and thermal performance outcomes anchor value-based pricing for liquid-cooled rack systems serving hyperscale cloud operators. Three-tier pricing structure across liquid-ready premium, air-cooled standard, and open-frame economy levels reflects certification grade and factory integration depth. Cost compression in economy tiers is intensifying because cold-rolled steel price volatility squeezes margin pools for unenclosed configurations. Wholesale colocation operators exhibit highest price sensitivity, while federal contractors prioritize NIST-compliant enclosed cabinets with biometric access logging regardless of capital premium.
Supply Chain Analysis
Single-source vulnerability sits with southeastern US fabrication clusters where domestic cabinet manufacturing concentrates for rapid-turn hyperscale fulfillment. Cold-rolled steel draws from domestic mills and Canadian imports, while specialized coolant distribution components rest on limited qualified supplier pools. Tariff exposure on aluminum extrusions and electrical-grade steel creates margin pressure for integrated rack-plus-power shipments. Distribution runs through direct manufacturer platforms displacing traditional channel partners for standardized configurations, with factory-integrated systems commanding dedicated logistics protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over liquid cooling engineering and factory pre-configuration determines competitive durability. Players are pursuing downstream service bundling to capture lifetime value beyond initial hardware transactions.
For Market Incumbents: To counter hyperscale buyers compressing deployment cycles through pre-validated rack-power-cooling bundles, Schneider Electric and Vertiv should deepen captive thermal engineering capabilities via specialized technician training programs. Securing UL 1973-certified energy storage integration for Texas ERCOT frequency regulation markets locks in multi-year maintenance revenue streams that offset hardware margin pressure.
For New Entrants and Emerging Players: The forty-to-sixty percent capital premium between liquid-ready and legacy air-cooled architectures creates entry space for hybrid cooling specialists addressing mixed-density colocation requirements. Edge computing wall-mount configurations in Indianapolis and Nashville telecommunications huts represent the most penetrable white-space, with NEMA-rated outdoor enclosures and integrated thermal management as the specific go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with thermal engineering specialists given FERC Order 2222 implementation reshaping rack-level power distribution specifications. Long-term viability over a multi-year horizon favors vendors with bidirectional power flow capabilities and carbon accounting integration. Acquisition targets should demonstrate factory integration workflows compressing field installation timelines. The signal to watch is hyperscale procurement teams unbundling installation services from hardware, indicating preference for vertically integrated platform vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Engineering Acquisition | Captures scarce technician capabilities for factory-installed coolant distribution units serving Virginia and Texas hyperscale campuses. |
| Pre-validated Bundle Partnership | Coordinates previously independent rack-power-cooling supplier tiers to match compressed deployment cycles demanded by cloud service providers. |
| Subscription Service Model Launch | Converts power and cooling monitoring into recurring revenue streams extending lifetime value beyond initial hardware transactions. |
| OSHA-Compliant Installation Program | Addresses liability concerns in multi-tenant facilities with frequent equipment swaps across Northern Virginia's Data Center Alley cluster. |
| ERCOT Grid Participation Certification | Enables battery-backed cabinet architectures to capture demand response revenue streams under FERC Order 2222 implementation. |
Research Methodology
Multi-period observation of hyperscale deployment cycles, thermal density thresholds, and state-level clean energy procurement patterns anchored the trend analysis, supplemented by interviews with data center facility managers, colocation procurement directors, electrical contracting supervisors, and hyperscale supply chain planners. Secondary validation drew from SEC filings of publicly traded infrastructure vendors, EIA electricity consumption data, FERC Order 2222 implementation records, and ASHRAE thermal guideline publications. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment forecasts to establish market sizing boundaries.
Input-output matrices mapped rack unit shipments across cooling technology tiers, installation type categories, and end-user procurement authority segments throughout the projection horizon. CAGRs were derived from regression analysis of historical deployment velocity against server power density trajectories and state-level data center incentive programs. Industry-specific forecast inputs included hyperscaler capex disclosure patterns and NIST cybersecurity framework adoption timelines for federal contracting pools.
Underlying measurement precision varies by segment; liquid cooling and immersion cooling configurations carry tighter precision than legacy air-cooled infrastructure due to visible hyperscale procurement pipelines. Forecasts reflect documented assumptions regarding server power density evolution and state clean energy mandate enforcement intensity. Deviation in steel input cost volatility or NFPA electrical code revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market