
 Chile Data Center Market | 2026-2036
Chile Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Data Center Market Insights
Financial services demand is shifting toward hybrid infrastructure models across Chile's data center landscape. ODATA anchors its position through captive energy sourcing and Santiago metro dominance. Ascenty competes via cross-border fiber integration with São Paulo and Buenos Aires corridors. Microsoft Corporation differentiates through sovereign cloud architecture aligned to local data residency requirements.
A data center constitutes a purpose-built facility housing servers, storage systems, and network equipment with controlled temperature bands between 18°C and 27°C, redundant power architectures, and latency thresholds under 20 milliseconds for financial trading applications. Colocation retains the largest revenue share as enterprises exit owned facilities, while hyperscale deployments accelerate as Amazon Web Services and Google expand campus-style developments in Quilicura and Cerrillos. Edge computing remains nascent but concentrates in mining corridors from Antofagasta to Copiapó where real-time processing reduces satellite backhaul dependency.
Chile's Ministry of Energy enforces renewable power quotas for facilities above 500 kW contracted load, while the Undersecretariat of Telecommunications certifies data center interoperability for government cloud procurement. These frameworks compel operators to secure long-term power purchase agreements with solar and wind developers in the Atacama region. Stakeholders must monitor transmission grid congestion at the SIC-SING interconnection and assess whether submarine cable landings at Valparaíso reshape latency arbitrage against Brazilian and Colombian alternatives.
Market Dynamics
Chile's data center market is being fundamentally restructured by the Central Bank of Chile's operational resilience mandates for payment system operators, which force financial institutions to migrate critical workloads from on-premise facilities to certified colocation infrastructure with redundant power and sub-20 millisecond latency guarantees.
Growth Catalysts
- Submarine cable landings:New fiber optic systems at Valparaíso are reducing latency to São Paulo by 40 percent, attracting regional cloud providers to establish Chilean points of presence.
- Financial sector compliance:The Central Bank of Chile's tightened operational resilience standards for payment systems mandate disaster recovery site separation, driving colocation demand from banks and fintech operators.
- Renewable energy quotas:The Ministry of Energy's 500 kW threshold for renewable power procurement pushes developers toward solar and wind contracts in the Atacama region, lowering long-term operational costs.
Market Restraints
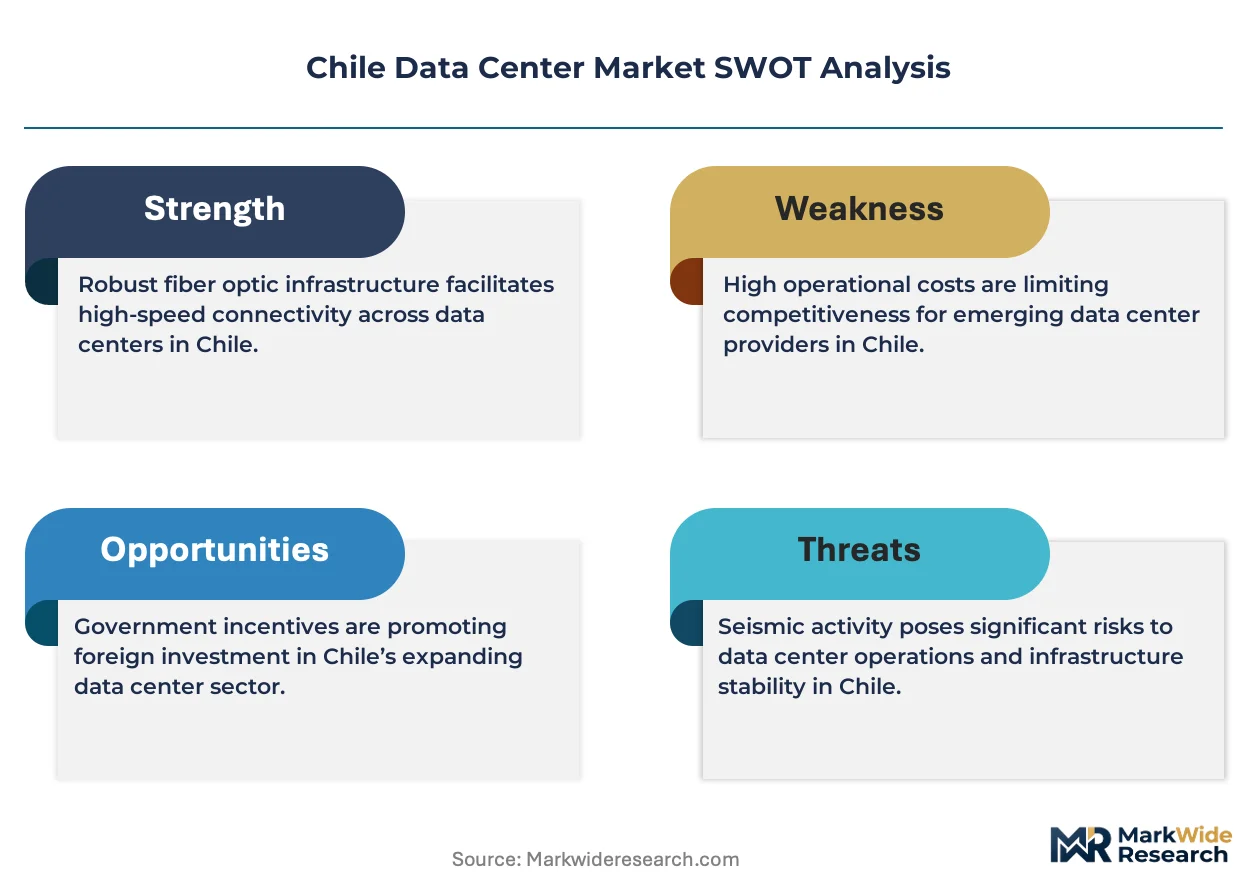
- Transmission grid congestion:The SIC-SING interconnection bottleneck limits power delivery to Santiago's metropolitan zone, constraining facility expansion in the primary demand cluster.
- Lithium supply concentration:Battery energy storage systems depend on Chilean lithium carbonate output, creating input cost volatility as battery manufacturers compete for domestic supply.
- Submarine cable dependency:International connectivity relies on three primary cable systems landing at Valparaíso; any physical disruption isolates the national digital infrastructure from global networks.
Strategic Opportunities
- Antofagasta mining corridor:Copper and lithium extraction operations in the Atacasta region require real-time processing for autonomous haulage and predictive maintenance, creating edge computing demand currently served by satellite backhaul.
- Government cloud procurement:The Undersecretariat of Telecommunications' interoperability certification opens public sector contracts for certified operators, with sovereign cloud requirements favoring local facility investment.
- Liquid cooling convergence:Integration of direct-to-chip cooling with high-density GPU deployments for AI training workloads allows operators to capture premium pricing from hyperscale tenants.
Industry Challenges
- Electrical engineering talent scarcity:Chile produces fewer than 200 specialized data center power systems engineers annually, forcing operators to recruit from Spanish and Mexican labor markets.
- Seismic certification timelines:Facilities must demonstrate compliance with NCh2361 structural standards for earthquake resistance, extending commissioning cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Data Center Market |
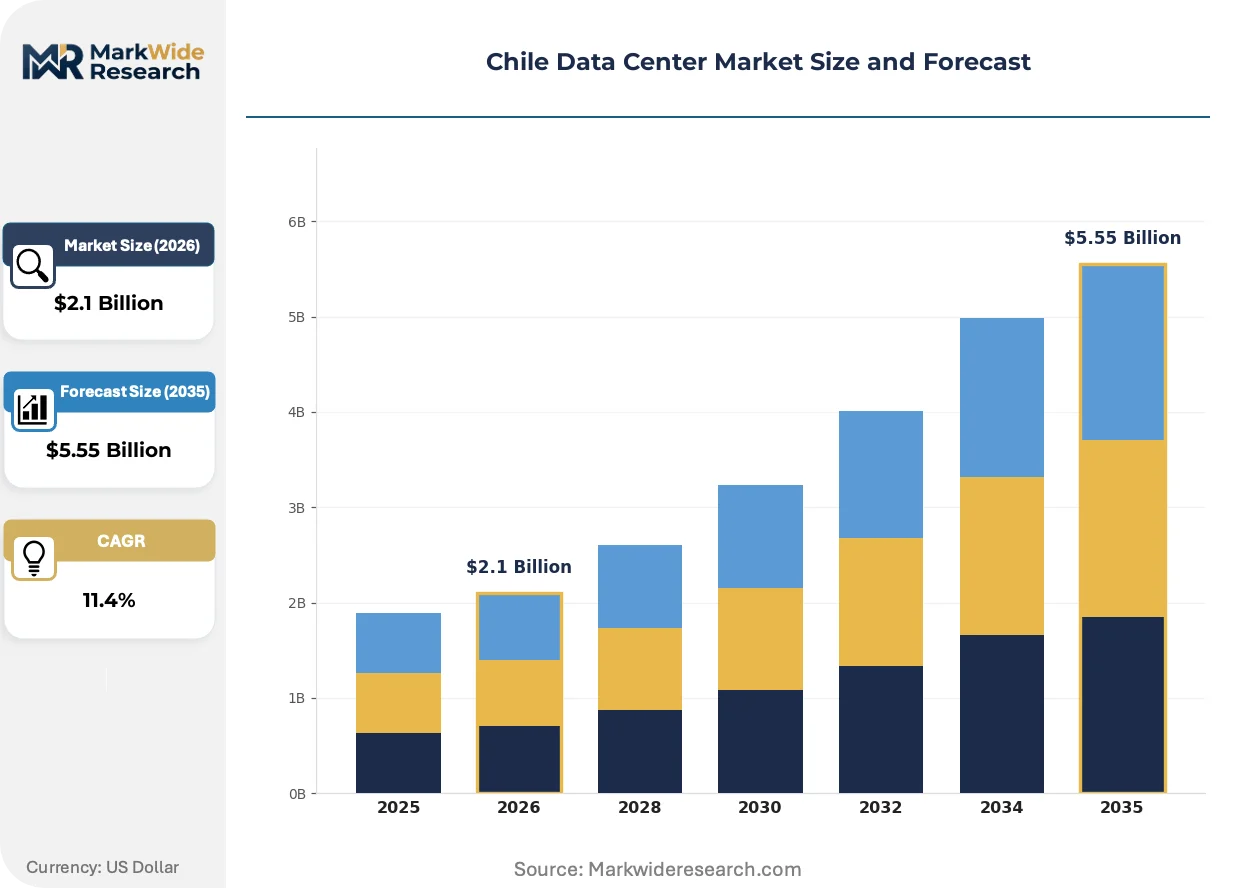
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Hyperscale, Edge Computing, Managed Services End User: Telecommunications, Financial Services, Healthcare, Government Service Type: Infrastructure as a Service, Platform as a Service, Data Backup, Disaster Recovery Technology: Virtualization, Internet of Things, Artificial Intelligence, Cloud Computing |
| Companies Covered | Equinix, ODATA, Ascenty, Amazon Web Services, Google, Microsoft Corporation, EdgeConneX, SONDA, Entel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Data Center Market Trends and Innovations
Direct liquid cooling systems are penetrating Chilean facilities at unprecedented speed, driven by GPU density requirements for generative AI training clusters. This thermal architecture shift is compressing traditional air-cooled designs and forcing infrastructure retrofit decisions.
Immersion cooling using dielectric fluids is electrifying facility design conversations among hyperscale operators evaluating Santiago deployments. Mining sector data centers in the Atacama are piloting single-phase immersion for dust-heavy environments. This technology is electrifying competitive differentiation as operators seek to market PUE ratios below 1.15 against regional competitors.
The Ministry of Energy's renewable power quotas for facilities above 500 kW contracted load are mandating long-term power purchase agreements with solar and wind developers. Industrial consequence includes 15-year contract structures that lock in energy costs but constrain operational flexibility. Hyperscale campus developments in Quilicura and Cerrillos are most affected, with Amazon Web Services and Google negotiating directly with Atacama solar farms to secure bundled renewable certificates.
Financial services procurement is fragmenting across hybrid infrastructure models rather than consolidating with single providers. Banks are unbundling primary and disaster recovery site contracts, awarding compute to hyperscale clouds and physical security to specialized colocation operators. This pattern is most visible in Santiago's metropolitan zone, where Banco de Chile and Banco Santander Chile operate multi-vendor architectures.
Chile Data Center Market Segmentation
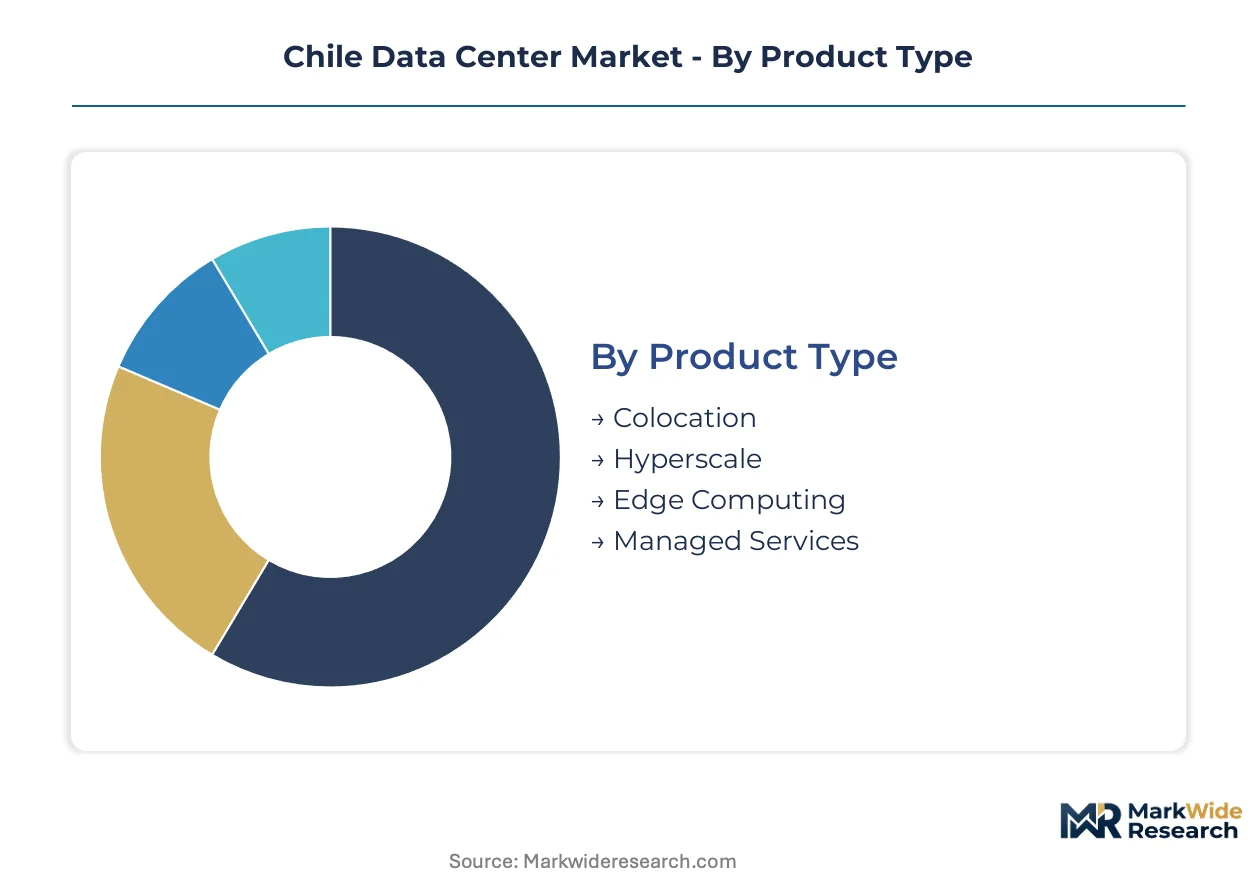
Segmentation in Chile's data center market reveals how regulatory pressure and infrastructure maturity create divergent certification burdens across deployment models. Understanding these divides helps operators align capital allocation with compliance exposure and customer procurement patterns.
Product Type:
Certification requirements intensify with facility scale, as the Ministry of Energy's renewable quotas and the Undersecretariat of Telecommunications' interoperability standards apply differentially across deployment architectures.
- Colocation:Multi-tenant facilities with standardized rack densities and shared cooling infrastructure. Financial services procurement concentrates here as banks unbundle primary and disaster recovery sites to meet Central Bank of Chile operational resilience mandates. The segment carries the heaviest certification load for seismic compliance under NCh2361 standards.
- Hyperscale:Campus-style developments exceeding 10 MW per facility with dedicated substations and direct renewable power purchase agreements. Amazon Web Services and Google negotiate 15-year solar contracts in the Atacama region to satisfy Ministry of Energy quotas for loads above 500 kW.
- Edge Computing:Distributed nodes positioned for sub-10 millisecond latency in mining corridors from Antofagasta to Copiapó. These compact deployments face lighter regulatory scrutiny but depend on satellite backhaul where fiber remains absent.
- Managed Services:Operator-delivered remote hands, monitoring, and infrastructure management layered atop physical colocation or customer-owned facilities.
Colocation sits at the top of the volume ranking, with Edge Computing climbing the fastest as mining automation demands real-time processing.
End User:
Procurement sophistication varies sharply across verticals, with regulated industries demanding audited compliance trails that informal sectors rarely require.
- Telecommunications:Carriers deploying 5G core networks and content delivery infrastructure. These operators drive cross-border fiber integration through Valparaíso submarine cable landings to reduce São Paulo latency.
- Financial Services:Banks, fintech operators, and payment system providers subject to Central Bank of Chile disaster recovery site separation rules. Banco de Chile and Banco Santander Chile operate multi-vendor hybrid architectures splitting compute between hyperscale clouds and specialized colocation operators.
- Healthcare:Hospital systems and telemedicine platforms with moderate compliance requirements around patient data residency.
- Government:Public sector entities procuring through the Undersecretariat of Telecommunications' certified interoperability framework. Sovereign cloud requirements favor local facility investment over foreign hyperscale alternatives.
Financial Services commands the premium pricing tier, while Government procurement is expanding most quickly as digital transformation mandates accelerate.
Service Type:
Margin structures diverge based on whether offerings bundle physical infrastructure with software layers or remain pure hardware rentals.
- Infrastructure as a Service:Compute, storage, and networking resources delivered on demand with metered billing. Hyperscale operators capture this demand through direct sales relationships with enterprise customers.
- Platform as a Service:Development environments and middleware abstracting underlying infrastructure management. Microsoft Corporation's sovereign cloud architecture targets this layer for customers requiring local data residency.
- Data Backup:Off-site replication services with defined recovery point objectives. Financial institutions specify these contracts separately from primary infrastructure to satisfy operational resilience audits.
- Disaster Recovery:Hot and warm standby sites with automated failover orchestration. The Central Bank of Chile's tightened standards mandate geographic separation between primary and recovery facilities, driving dual-contract procurement patterns.
Infrastructure as a Service dominates current revenue, with Platform as a Service gaining share fastest as application modernization accelerates.
Technology:
Thermal and computational architectures determine facility design investments and operational cost trajectories across deployment types.
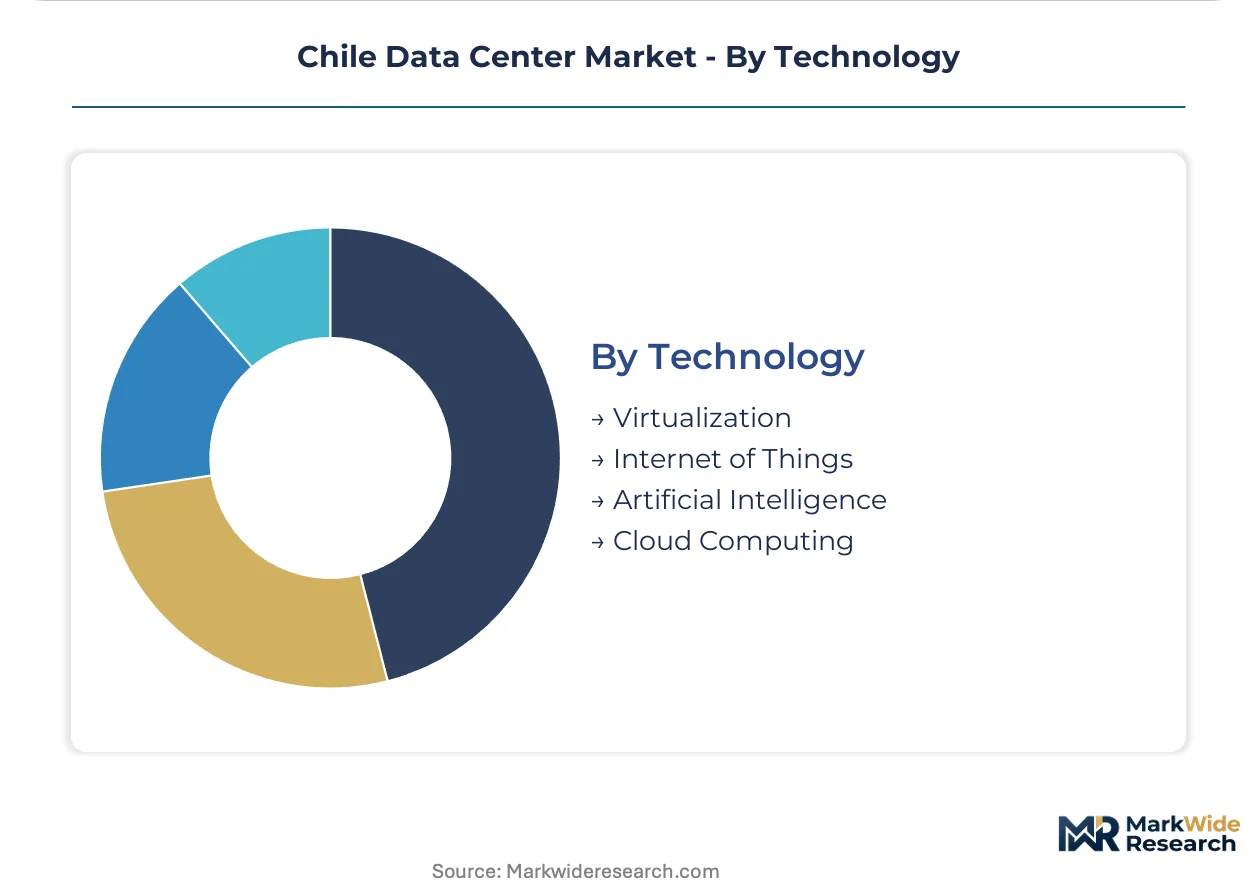
- Virtualization:Server abstraction enabling multi-tenant resource pooling and rapid workload migration. This foundational layer underpins colocation economics but offers limited differentiation.
- Internet of Things:Sensor networks and connected device management driving edge computing demand in mining and logistics corridors. Antofagasta copper operations deploy these systems for autonomous haulage and predictive maintenance.
- Artificial Intelligence:GPU-intensive training and inference workloads requiring direct liquid cooling and power densities exceeding 50 kW per rack. This technology is compressing traditional air-cooled designs and forcing infrastructure retrofit decisions.
- Cloud Computing:Distributed resource orchestration spanning on-premise, colocation, and hyperscale environments. Financial services procurement fragments across hybrid models rather than consolidating with single providers.
Cloud Computing anchors current deployment volumes, with Artificial Intelligence expanding most steeply as generative AI training clusters penetrate Chilean facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping data center deployment across Latin America as operators seek jurisdictions with renewable energy frameworks that reduce long-term power costs. Chile's Ministry of Energy quotas and Central Bank of Chile operational resilience mandates create distinct compliance cost profiles compared to regional alternatives.
Brazil
Financial services demand from São Paulo's banking corridor drives colocation expansion as Banco Central do Brasil enforces payment system continuity rules. ANATEL's telecommunications licensing framework shapes fiber connectivity investments. Hyperscale campuses cluster in Campinas and São Paulo metro zones where Ascenty anchors cross-border integration with Chilean corridors.
Mexico
Nearshoring manufacturing and fintech growth propel edge computing demand across northern industrial states. IFT interoperability standards for government cloud procurement create certification pathways for foreign operators. Querétaro and Monterrey absorb the bulk of new capacity as submarine cable landings at Veracruz reduce latency to US markets.
Colombia
Bogotá's financial district generates disaster recovery site demand as Banco de la República tightens operational resilience for payment infrastructure. MinTIC's data center interoperability certification opens public sector contracts. Medellín's fiber-rich metropolitan zone attracts regional cloud provider points of presence seeking Andean connectivity.
Argentina
Currency volatility constrains hyperscale investment despite Buenos Aires' substantial enterprise demand. Banco Central de la República Argentina's payment system regulations lag regional peers in mandating external colocation. Córdoba and Rosario industrial corridors show nascent edge computing traction for agribusiness IoT deployments.
Chile Data Center Market Competitive Landscape
Capacity expansion dominates the current landscape as operators race to secure Santiago metropolitan zone real estate and renewable power purchase agreements. The market structure concentrates around three tiers: global hyperscale clouds with sovereign cloud architectures, regional colocation specialists with cross-border fiber integration, and domestic operators with captive energy sourcing. Strategic archetypes include renewable-anchored developers securing long-term solar contracts, seismic-certified facility operators extending commissioning cycles for NCh2361 compliance, and edge computing specialists targeting mining corridor automation demand. M&A activity and direct renewable power procurement represent the dominant competitive vectors.
Among global hyperscale clouds, Amazon Web Services and Google occupy positions defined by campus-scale developments in Quilicura and Cerrillos with direct Atacama solar contracting. ODATA exemplifies the regional colocation archetype through Santiago metro dominance and captive energy sourcing strategies. Ascenty represents cross-border integration specialists with fiber corridors linking São Paulo and Buenos Aires. Microsoft Corporation anchors the sovereign cloud tier through architecture aligned to local data residency requirements.
| Leading Market Players |
|---|
| Equinix |
| ODATA |
| Ascenty |
| Amazon Web Services |
| Microsoft Corporation |
| EdgeConneX |
| SONDA |
| Entel |
| Others |
Pricing and Supply Chain Analysis
Atacama solar power purchase agreements flow through Santiago metropolitan facilities as the dominant cost anchor, compressing operational expenditure differentials between hyperscale campus developments and colocation operators while locking both tiers into fifteen-year contract structures that constrain pricing flexibility.
Pricing Analysis
Direct-to-enterprise sales relationships bypass traditional channel-margin layers entirely, with hyperscale operators negotiating bundled renewable certificates alongside compute capacity. Certification grade under NCh2361 seismic standards and Ministry of Energy renewable compliance tiers create sharp price differentiation between certified and uncertified facilities. Cost compression in edge computing deployments intensifies as satellite backhaul dependency forces operational expenditure trade-offs against fiber-connected alternatives. Mining sector buyers in Antofagasta demonstrate highest price sensitivity due to remote location penalties, while financial services procurement in Santiago shows lowest sensitivity given regulatory mandate urgency.
Supply Chain Analysis
Electrical engineering talent scarcity in Chilean manufacturing geographies forces recruitment from Spanish and Mexican labor markets, extending commissioning cycles and inflating labor cost components. Critical equipment sourcing concentrates in China, Germany, and the United States for switchgear, cooling systems, and power distribution units. Lithium carbonate supply from domestic Atacama salares feeds battery energy storage systems, creating single-source vulnerability as battery manufacturers compete for constrained output. Distribution runs through direct manufacturer relationships with EPC contractors rather than distributor networks, with Valparaíso port handling submarine cable landings as the primary international connectivity chokepoint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's data center market functions as a geographic-arbitrage play against Brazilian and Colombian alternatives, with Atacama solar cost differentials and Central Bank of Chile regulatory stringency creating distinct competitive positioning for operators able to secure renewable power purchase agreements ahead of regional peers.
For Market Incumbents: Hedge against transmission grid congestion at the SIC-SING interconnection by securing substation capacity in advance of demand surges, while deepening captive energy sourcing through direct solar farm equity positions to defend margin structure against renewable certificate price volatility. Reinforce seismic certification timelines as a competitive moat, extending NCh2361 compliance documentation as a barrier against faster-moving but less capitalized entrants. For New Entrants and Emerging Players: Cloud marketplace routes offer lowest-friction customer acquisition for platform-as-a-service layers, bypassing capital-intensive facility construction. The Antofagasta mining corridor represents the most penetrable white-space target, with autonomous haulage and predictive maintenance demand currently served by high-latency satellite backhaul. Position through edge computing nodes with direct fiber integration to copper and lithium extraction operations, leveraging real-time processing requirements as the go-to-market wedge against incumbent colocation providers. For Investors and Strategic Acquirers: Consolidation pressure builds where electrical engineering talent scarcity meets renewable power contract fragmentation across sub-scale operators. Five-to-ten year viability hinges on securing long-dated solar purchase agreements before Atacama development sites exhaust. Target acquisition archetype: regional colocation specialists with existing NCh2361 certification and stranded renewable contract capacity. The signal to watch is Ministry of Energy quota threshold adjustments above 500 kW, which would accelerate competitive exit among non-compliant facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Deployment | Captures premium GPU-density tenants as AI training clusters penetrate Chilean facilities. |
| Atacama Solar Power Purchase Agreement | Locks in fifteen-year operational cost advantage against grid-tied competitors. |
| Cross-Border Fiber Integration | Reduces São Paulo latency by forty percent through Valparaíso submarine cable landings. |
| NCh2361 Seismic Certification Investment | Creates eight-to-fourteen month regulatory moat against faster but uncertified entrants. |
| Edge Computing Node Deployment | Addresses mining corridor automation demand currently dependent on satellite backhaul. |
Research Methodology
Bottom-up financial services and mining sector modeling reconciled against top-down hyperscale capacity tracking forms the analytical core of this study. Primary interviews with data center operators, Central Bank of Chile compliance officers, Atacama solar developers, and submarine cable consortium representatives combined with secondary validation from SEC filings, SUBTEL interoperability certifications, Ministry of Energy renewable quota registrations, and SIC-SING grid operator disclosures. Triangulation across demand-side procurement patterns and supply-side power contracting activity ensures segment-level consistency.
Input-output matrices map facility capacity additions against renewable power availability, cross-border fiber latency improvements, and regulatory compliance cost burdens across the projection horizon. Segmentation dimensions include deployment architecture, end-use vertical, service tier, and thermal technology type. CAGRs derive from facility commissioning timelines, power purchase agreement contract structures, and enterprise workload migration velocity. Forecast inputs incorporate GPU density trajectories for AI training clusters and seismic certification approval rates.
The model assumes a particular technology adoption path; alternative pathways for immersion cooling or solid-state battery storage would alter the outlook for power density and backup power architecture. Forecasts reflect documented assumptions regarding renewable energy quota enforcement, submarine cable landing schedules, and central bank operational resilience mandate implementation timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Middle East Data Center Market