
 Automotive Dealer Management Systems (DMS) Market | 2026-2036
Automotive Dealer Management Systems (DMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Dealer Management Systems (DMS) Market Outlook
Buyer concentration among large dealership groups is shifting procurement power toward multi-location operators seeking unified platforms. Apriorit leverages deep automotive software expertise to serve tier-one dealer groups with custom integration layers. Chetu anchors its position through offshore delivery centers that reduce deployment costs for mid-market dealerships. Intellias competes by embedding AI-driven analytics into core DMS workflows for European automotive clients.
Automotive Dealer Management Systems encompass integrated software platforms that coordinate vehicle inventory, customer relationship management, service scheduling, and financial reporting across dealership operations. These systems typically run on centralized databases with real-time synchronization between showroom floors, service bays, and back-office accounting functions. Cloud-based deployment now leads new implementations as dealerships abandon aging server infrastructure, while CRM modules capture the fastest expansion as customer data platforms merge with sales automation tools. Inventory management remains the most mature segment, though margin pools increasingly concentrate in hybrid deployment models that bridge legacy on-premises investments with cloud scalability.
FCC guidelines on consumer data protection shape how DMS vendors architect customer information storage and telematics integration in the United States. EPA reporting requirements for fleet emissions filter into service scheduling modules that track vehicle maintenance histories for regulatory compliance. GDPR and state-level privacy statutes force cross-border vendors to implement jurisdictional data partitioning. Stakeholders must weigh the pace of OEM-mandated system standardization against the flexibility that independent dealer groups still demand from open-architecture platforms.
Market Dynamics
Cloud migration and API-first architectures are dismantling legacy on-premises DMS installations across North American and Western European dealer networks, forcing vendors to rebuild core platforms for distributed, multi-location operations.
Growth Catalysts
- GDPR-mandated data partitioning:European privacy statutes compel DMS vendors to engineer jurisdictional data controls, creating upgrade cycles for compliance-ready platforms.
- Telematics integration:Connected vehicle data streams are pulling real-time maintenance histories into service scheduling modules, expanding platform utility.
- Large dealership group consolidation:Multi-franchise operators in the United States are standardizing on unified platforms to centralize inventory visibility across dozens of locations.
Market Restraints
- Legacy server infrastructure:Aging on-premises investments at independent dealerships create technical debt that slows cloud migration timelines.
- Input cost volatility:Semiconductor shortages and cloud compute pricing fluctuations strain vendor margins on hardware-dependent deployment packages.
- OEM-mandated standardization:Manufacturer-imposed system requirements limit vendor flexibility and compress differentiation in captive dealer networks.
Strategic Opportunities
- AI-driven analytics convergence:Machine learning modules embedded in CRM and inventory forecasting represent unpenetrated white space for workflow automation.
- Mid-market dealership penetration:Cloud-native, lower-touch deployment models can capture independent dealers currently priced out of enterprise-tier platforms.
- IRA clean vehicle incentives:United States federal tax credits for electric vehicle sales are expanding dealer technology budgets for customer qualification and reporting tools.
Industry Challenges
- Integration complexity:Bridging legacy DMS databases with modern cloud APIs requires specialized engineering talent scarce in automotive software.
- Certification timeline compression:Multiple overlapping privacy regimes demand continuous compliance auditing that stretches vendor QA resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Dealer Management Systems (DMS) Market |
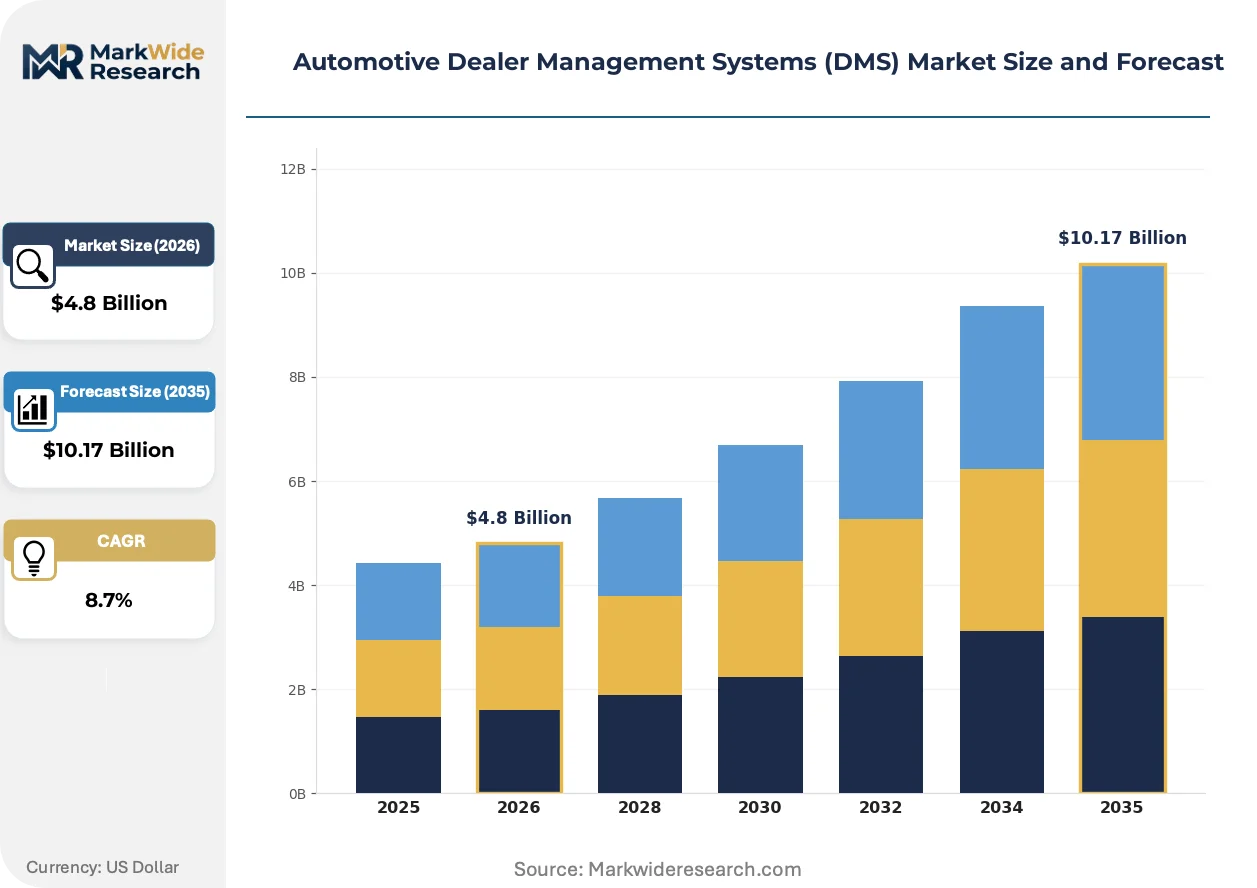
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM, Inventory Management, Sales Reporting, Service Scheduling End User: Dealerships, Fleet Managers, Automotive OEMs, Aftermarket Providers Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Service Type: Consulting, Support, Maintenance, Training |
| Companies Covered | Apriorit, Chetu, Inoxoft, Intellias, N-iX, CXCS Technology, Innowise, LeverX, Saritasa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Dealer Management Systems (DMS) Market Strategic Shifts
Microservices architectures are fragmenting monolithic DMS platforms into composable components, letting dealer groups swap modules without forklift upgrades. This architectural pivot is redrawing competitive boundaries between full-suite vendors and specialized workflow providers.
Containerized deployment is modularizing core DMS functions into independently scalable units. Tier-one dealer groups in the United States are piloting container-based inventory and CRM modules that deploy in hours rather than months. This modularity is compressing vendor lock-in periods and enabling best-of-breed procurement strategies.
EPA fleet emissions reporting requirements are filtering into service bay modules that track maintenance histories for regulatory compliance. Vendors must architect data retention and audit trails that satisfy both federal reporting and state-level inspection regimes. Service scheduling segments in California and Texas are experiencing the earliest compliance-driven upgrade cycles.
Subscription pricing models are displacing perpetual licenses as dealer groups prioritize operational expenditure over capital deployment. Large multi-franchise operators are negotiating enterprise SaaS contracts that bundle training, support, and continuous feature updates. This shift is most visible among publicly traded dealership groups seeking predictable technology cost structures.
Automotive Dealer Management Systems (DMS) Market Segmentation
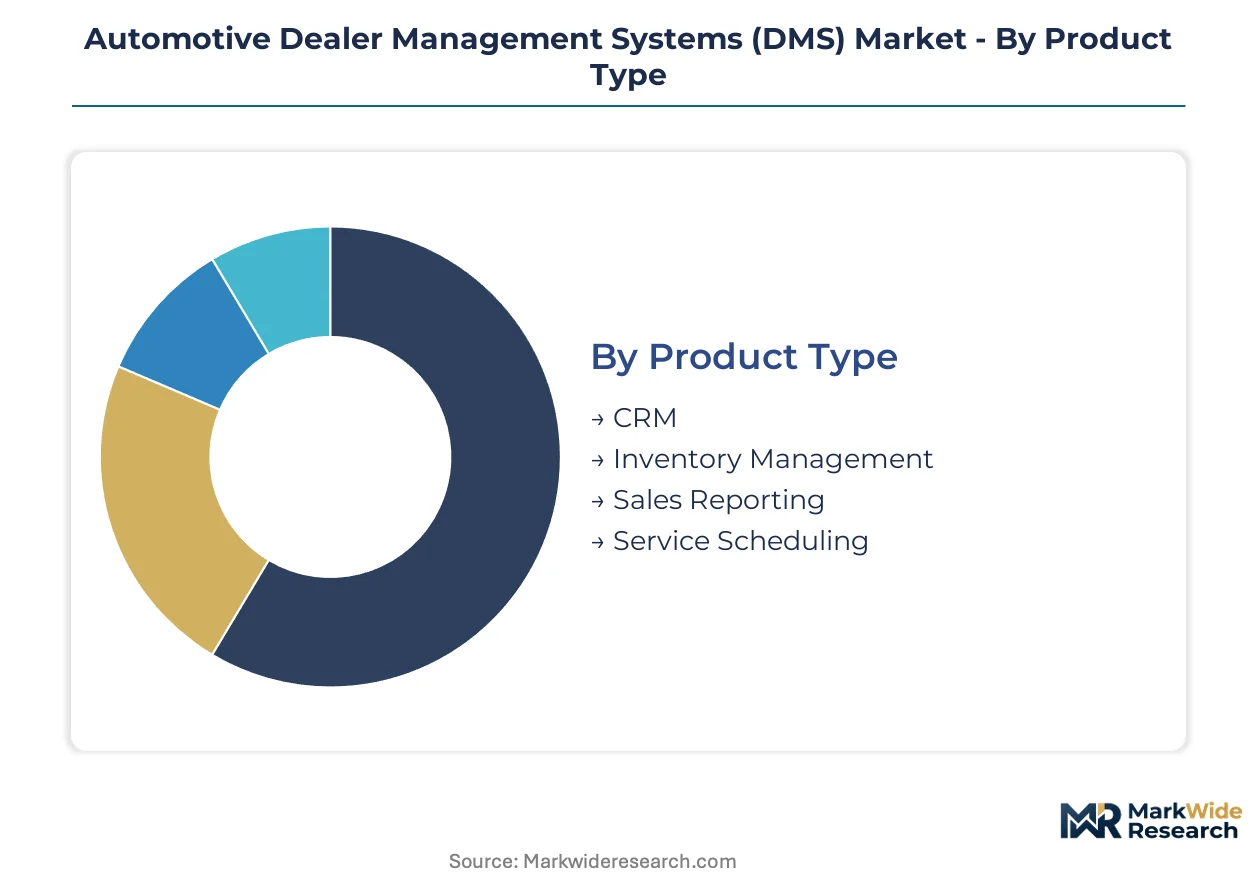
DMS procurement patterns diverge sharply between integrated platform buyers and modular component adopters. Understanding where each segment sits on this integration spectrum reveals upgrade priorities and vendor positioning strategies.
Product Type:
CRM and inventory modules anchor most deployments as embedded functions, while sales reporting and service scheduling often launch as standalone pilots before platform consolidation.
- CRM:Customer data platforms now merge with sales automation and telematics ingestion, creating unified prospect-to-service histories. Large US dealer groups standardize on CRM-first architectures before expanding to adjacent modules.
- Inventory Management:Real-time synchronization across showroom floors, wholesale auctions, and OEM allocation systems defines this mature segment. Margin pools concentrate in hybrid deployment models bridging legacy investments with cloud scalability.
- Sales Reporting:Dashboards aggregate transaction data for multi-location visibility and lender compliance documentation.
- Service Scheduling:Connected vehicle data streams pull real-time maintenance histories into bay allocation systems, expanding platform utility for fixed operations.
Volume placements concentrate in Inventory Management; the faster expansion belongs to CRM.
End User:
Dealerships dominate absolute deployment counts, yet fleet managers and OEMs are driving specification standards that reshape vendor roadmaps.
- Dealerships:Independent single-points favor modular entry points; multi-franchise groups demand unified platforms across dozens of locations. IRA clean vehicle incentives are expanding technology budgets for customer qualification tools.
- Automotive OEMs:Manufacturer-mandated system requirements limit vendor flexibility in captive dealer networks, compressing differentiation.
- Fleet Managers:EPA emissions reporting requirements filter into maintenance tracking modules for regulatory compliance.
- Aftermarket Providers:Parts distributors and independent service chains adopt DMS-lite configurations for inventory and customer management.
Dealerships retain the deepest installed base; fleet managers are gaining share fastest.
Deployment:
Cost tier structures separate capital-intensive on-premises investments from operational expenditure cloud models, with hybrid bridging strategies capturing mid-market transitions.
- Cloud-Based:Subscription pricing displaces perpetual licenses as publicly traded dealer groups seek predictable cost structures. Containerized deployment compresses vendor lock-in periods.
- Hybrid:Bridges legacy server infrastructure with cloud scalability, capturing dealerships with technical debt constraints.
- On-Premises:Aging installations at independent dealerships create upgrade cycles for compliance-ready platforms.
- Mobile:Field sales and service advisors access core functions through native applications, extending platform reach beyond fixed workstations.
Cloud-based deployments lead new implementations; hybrid models show the steepest expansion trajectory.
Service Type:
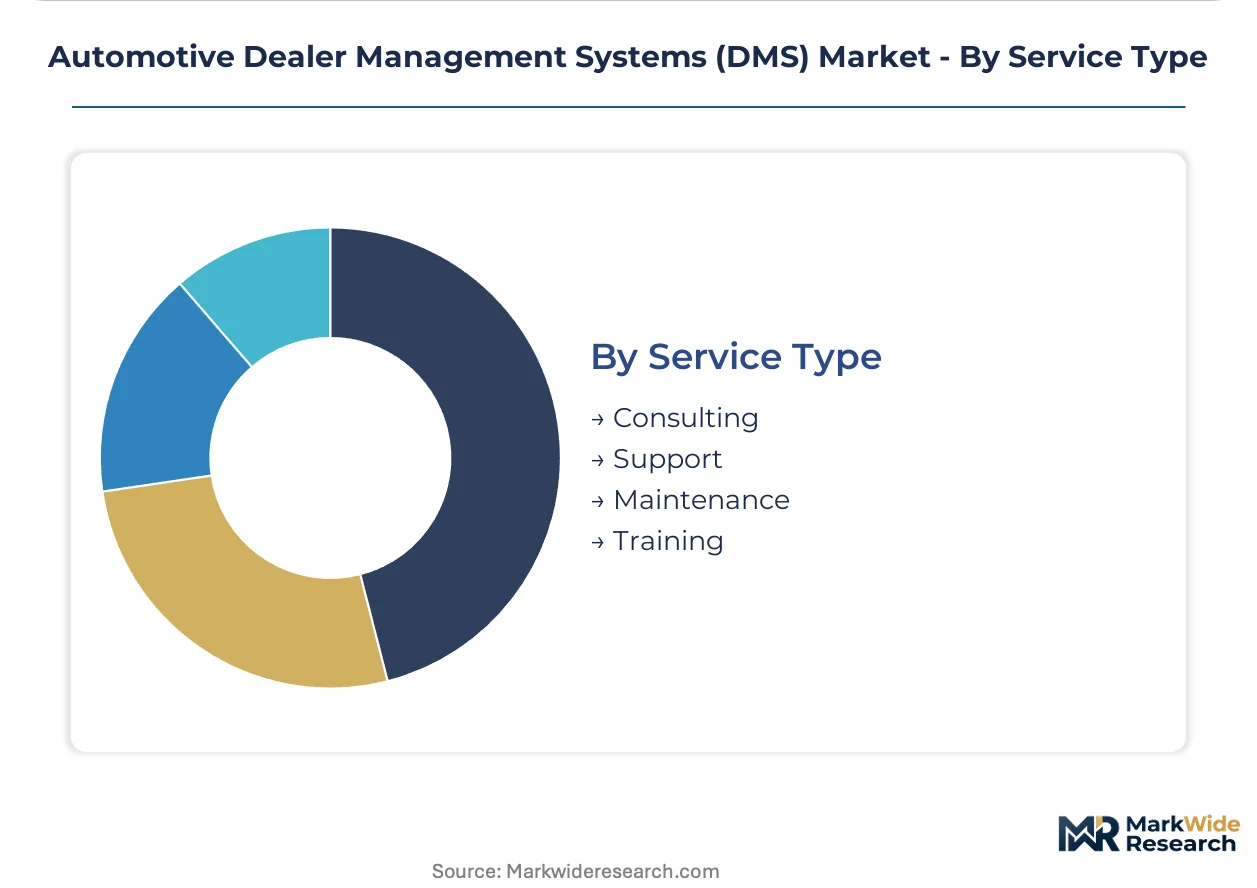
Margin concentration follows the shift from perpetual license margins to recurring service revenue streams.
- Support:24/7 operational assistance commands premium pricing for multi-location dealer groups with zero-downtime requirements.
- Consulting:System integration and workflow redesign services address the scarcity of specialized automotive software engineering talent.
- Training:Continuous education contracts bundle with enterprise SaaS agreements as feature velocity accelerates.
- Maintenance:Compliance auditing and security patching services stretch vendor QA resources across overlapping privacy regimes.
Support contracts generate the most recurring revenue; consulting engagements are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large dealership groups in the United States concentrate procurement power and drive platform standardization across multi-franchise operations. Cloud migration accelerates in Western Europe as GDPR compliance mandates data partitioning architectures. Emerging markets in Asia-Pacific show rising adoption of mobile-first DMS configurations.
United States
Multi-franchise dealer groups spanning Texas, California, and the Southeast dominate technology procurement for unified inventory visibility. IRA clean vehicle incentives expand dealer budgets for customer qualification and reporting tools. The Dallas-Fort Worth metroplex anchors concentrated deployment of enterprise-tier SaaS contracts among publicly traded dealership groups.
Germany
KBA vehicle registration requirements and emissions compliance drive service scheduling module upgrades across Baden-Württemberg and Bavaria. GDPR-mandated data partitioning compels vendors to engineer jurisdictional controls for cross-border dealer networks. Stuttgart's automotive engineering cluster incubates specialized DMS integration providers serving OEM-mandated standardization programs.
United Kingdom
Large dealer groups in London and the Midlands prioritize CRM-first architectures before expanding to adjacent modules. FCA consumer protection guidelines shape customer data storage architectures and telematics integration protocols. Manchester's technology corridor hosts cloud-native DMS pilots compressing deployment timelines from months to hours.
Canada
Provincial privacy statutes in Ontario and British Columbia parallel GDPR requirements for customer information management. Environment and Climate Change Canada emissions reporting filters into fleet maintenance tracking for regulatory compliance. Toronto's financial services cluster drives subscription pricing adoption among dealer groups seeking predictable operational expenditure structures.
India
Rising vehicle sales in Maharashtra and Karnataka expand addressable market for cloud-native DMS targeting mid-market dealerships. BIS data localization requirements influence vendor decisions on server infrastructure placement. Bangalore's software development ecosystem supplies specialized engineering talent for API-first platform architectures bridging legacy systems.
Automotive Dealer Management Systems (DMS) Market Competitive Environment
United States-based technology providers anchor the enterprise tier; Eastern European development specialists hold cost-advantaged positions in integration services. Market structure shows moderate consolidation around full-suite vendors competing with modular component providers. Two strategic archetypes dominate: cloud-native platform builders and legacy system integration specialists. Competitive moves concentrate on API ecosystem partnerships and vertical feature expansion into telematics and AI-driven analytics.
Within the custom integration tier, Apriorit and Chetu exemplify contrasting geographic positioning strategies. Apriorit leverages automotive software expertise to serve tier-one dealer groups requiring specialized engineering layers. Chetu anchors its market presence through offshore delivery centers that reduce deployment costs for mid-market dealership segments. Intellias occupies a position embedding analytics capabilities into core workflows for European automotive clients.
| Leading Market Players |
|---|
| Apriorit |
| Chetu |
| Inoxoft |
| Intellias |
| N-iX |
| CXCS Technology |
| Innowise |
| LeverX |
| Saritasa |
| Others |
Value Chain & Pricing Dynamics
Cloud compute pricing indices cascade through DMS vendor margins, compressing subscription tiers as infrastructure costs concentrate among hyperscaler providers. This input cost volatility feeds into deployment package pricing, forcing tier-one dealers toward enterprise SaaS contracts that absorb volatility through volume commitments.
Pricing Analysis
Volume placements in inventory management modules generate thinner margins than CRM and AI-driven analytics segments where differentiation commands premium pricing. Three-tier pricing structure across enterprise, mid-market, and independent dealership levels reflects customization depth and integration complexity. Pricing pressure stems from semiconductor cost fluctuations and cloud infrastructure pricing cycles. Independent single-point dealerships exhibit highest price sensitivity; multi-franchise groups absorb premium tiers for unified platform standardization.
Supply Chain Analysis
Reverse-logistics flows for legacy server hardware and on-premises equipment refurbishment create secondary supply channels for cost-constrained independent dealerships. Core engineering talent concentrates in Ukraine, Poland, and India, with Bangalore and Lviv anchoring specialized automotive software development. Platform architectures draw from open-source frameworks, proprietary OEM APIs, and hyperscaler infrastructure services. Single-source vulnerability sits with cloud infrastructure dependencies on AWS, Azure, and Google Cloud. Distribution runs through direct enterprise sales for tier-one dealer groups and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized automotive software engineering capacity constraints prop vendor pricing power, as API-first platform rebuilds outstrip qualified development pipeline output.
For Market Incumbents: Extend API ecosystem partnerships to lock in dealership workflow integration before modular competitors fragment platform coherence. Acquire specialized integration firms in Eastern European talent clusters to defend engineering capacity. OEM-mandated standardization programs threaten differentiation; counter through vertical feature expansion into telematics and AI-driven analytics.
For New Entrants and Emerging Players: Cloud-native deployment specialists represent the most penetrable channel partner type for mid-market dealership segments. Target independent dealer groups in Texas and California with containerized modules that deploy in hours rather than months. Lead with subscription pricing models that displace perpetual license incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor custom integration specialists with automotive software expertise in Ukraine and Poland. Long-term viability hinges on platform consolidation around API-first architectures over legacy system maintenance. Watch for IRA clean vehicle incentive program expansion as inflection signal for customer qualification tool demand.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Rebuild | Enables real-time telematics ingestion for EPA compliance tracking across multi-location dealer networks. |
| Containerized Module Deployment | Compresses vendor lock-in periods and accelerates CRM-first adoption among publicly traded dealership groups. |
| GDPR-Ready Data Partitioning | Opens upgrade cycles for European dealer networks facing jurisdictional privacy mandate enforcement. |
| AI-Driven Analytics Convergence | Captures unpenetrated white space in inventory forecasting and service bay optimization workflows. |
| Mid-Market Cloud-Native Entry | Targets independent dealerships priced out of enterprise-tier platforms with lower-touch deployment models. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dealership operations directors, DMS vendor product managers, automotive OEM platform engineers, and cloud infrastructure procurement officers combined with secondary validation from NADA membership databases, SEC 10-K filings of publicly traded dealer groups, and hyperscaler capex disclosures. Bottom-up deployment counts triangulated against top-down technology spend estimates from dealership financial statements.
Granularity-level modeling segmented the market by deployment architecture, dealership scale tier, module type, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to cloud migration timelines and compliance-driven upgrade cycles. Forecast inputs included IRA incentive program expansion trajectories and GDPR enforcement intensity indices.
Caveats apply where semiconductor supply normalization or hyperscaler pricing renegotiations could materially shift vendor margin structures and deployment timelines. Practitioners should monitor EPA fleet emissions reporting rule expansion and state-level privacy statute proliferation for early signals of compliance-driven upgrade demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Licensing Market
Software & Services
Tenant Billing System Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
Production Optimization Software Market
Software & Services
Global Programming Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Embedded Hypervisor Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
Collaborative Applications Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Cloud Business Process Management (BPM) Software Market