
 Data Center Virtualization Market | 2026-2036
Data Center Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Virtualization Market Analysis
Multi-source infrastructure procurement is recalibrating how enterprises balance cloud-native and on-premises virtualization assets. VMware anchors enterprise hybrid deployments through its established hypervisor ecosystem. Red Hat leverages open-source Kubernetes platforms to compete in container orchestration. Microsoft extends Azure Stack integration to sustain channel control across distributed environments.
Data center virtualization abstracts compute, storage, and network resources from physical hardware through software-defined layers, enabling dynamic resource pooling with sub-millisecond latency targets for workload migration. Server virtualization remains the foundational layer, though network virtualization is expanding fastest as SD-WAN and NFV deployments accelerate. Desktop virtualization occupies narrower margin pools, concentrated in regulated industries requiring centralized endpoint control. Storage virtualization dominates capital allocation where enterprises consolidate siloed arrays into unified fabrics.
The EU AI Act and GDPR constrain how European operators process training data within virtualized boundaries, forcing architectural redesigns. The US FCC and NIST frameworks shape cybersecurity baselines for federal cloud migrations, directly filtering vendor qualification. India's BIS and MeitY guidelines mandate data localization that privileges domestic private cloud buildouts. Stakeholders must weigh sovereignty requirements against hyperscaler interoperability before committing to long-term virtualization contracts.
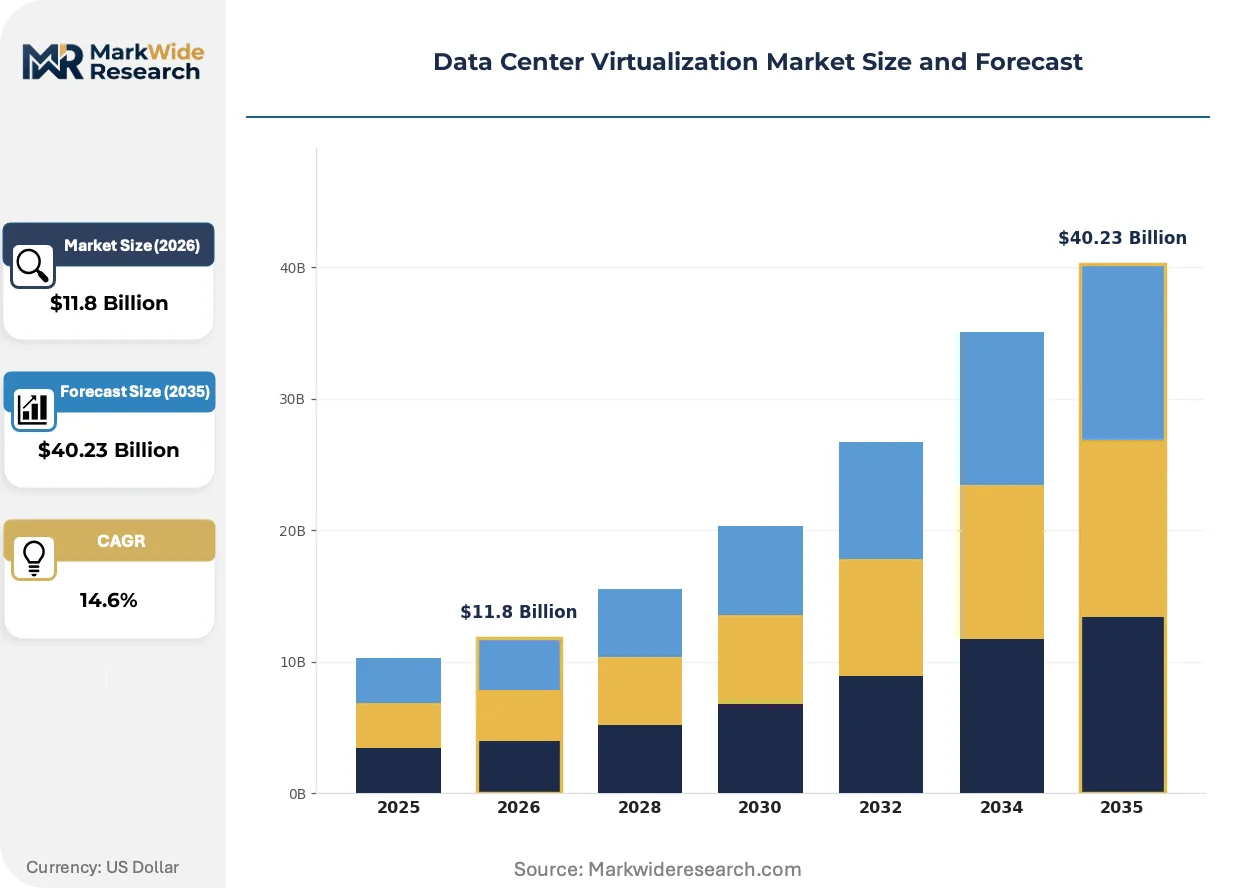
Market Dynamics
Financial services firms are recalibrating virtualization architectures to absorb real-time risk analytics workloads, while the EU AI Act forces European operators to rebuild data governance frameworks around sovereignty requirements.
Growth Catalysts
- EU AI Act compliance mandates:European operators must redesign virtualized boundaries for AI training data processing, accelerating investment in sovereign cloud infrastructure and compliant orchestration layers.
- Hyperscaler corridor concentration:Frankfurt's cloud corridor in Germany attracts sustained capital deployment, concentrating demand for enterprise-grade virtualization platforms with sub-millisecond latency guarantees.
- NFV acceleration in telecom:Network function virtualization replaces proprietary hardware at mobile operators, driving software-defined infrastructure procurement for 5G core deployments.
Market Restraints
- Specialized engineering talent scarcity:Kubernetes and SD-WAN expertise commands premium compensation, constraining deployment velocity for mid-market enterprises without captive training programs.
- Hyperscaler dependency concentration:Three cloud providers control the majority of bare-metal supply, creating negotiation leverage asymmetry for virtualization software vendors seeking hardware optimization.
- GDPR-EU AI Act friction:Overlapping compliance obligations force redundant architectural safeguards, extending deployment timelines and inflating professional services attach rates.
Strategic Opportunities
- India's data localization mandates:BIS and MeitY guidelines privilege domestic private cloud buildouts, opening white space for localized virtualization stacks outside hyperscaler dominance.
- Edge-container convergence:Kubernetes orchestration at distributed cell towers and factory floors creates demand for lightweight hypervisors optimized for constrained compute environments.
- US federal cloud migration tailwinds:NIST cybersecurity frameworks and FCC guidelines filter vendor qualification, creating preferential access lanes for compliant virtualization platforms.
Industry Challenges
- Legacy mainframe integration complexity:Financial services virtualization projects stall on COBOL workload migration, requiring expensive emulation layers and extended parallel operation periods.
- Multi-cloud certification timelines:Vendor-neutral interoperability standards remain immature, forcing buyers into premature architectural lock-in decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Virtualization Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Solution Type: Server Virtualization, Storage Virtualization, Network Virtualization, Desktop Virtualization End User: Enterprise, Service Provider, Government, Academic Application: Disaster Recovery, Load Balancing, Cloud Management, Testing & Development |
| Companies Covered | Nutanix, Red Hat, VMware, Parallels, Scale Computing, Microsoft, Oracle, Broadcom, Citrix Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Virtualization Market Emerging Trajectories
Container-native virtualization is dissolving the boundary between hypervisor and orchestrator layers, compressing procurement decisions around unified platforms rather than discrete infrastructure components.
Confidential computing hardware extensions are electrifying security architectures for multi-tenant environments. Financial services deploy these capabilities for risk analytics isolation. The technology is electrifying competitive positioning around zero-trust virtualization stacks.
The EU AI Act's training data governance requirements are forcing architectural redesigns across European deployments. Operators must implement verifiable data lineage within virtualized boundaries. German cloud corridor investments now prioritize compliant orchestration layers over raw compute density.
Enterprise sourcing patterns are consolidating around outcome-guaranteed service contracts. Infrastructure teams now procure guaranteed latency and availability metrics rather than discrete server licenses. This compression is most visible in US federal and German financial services procurement.
Data Center Virtualization Market Segmentation
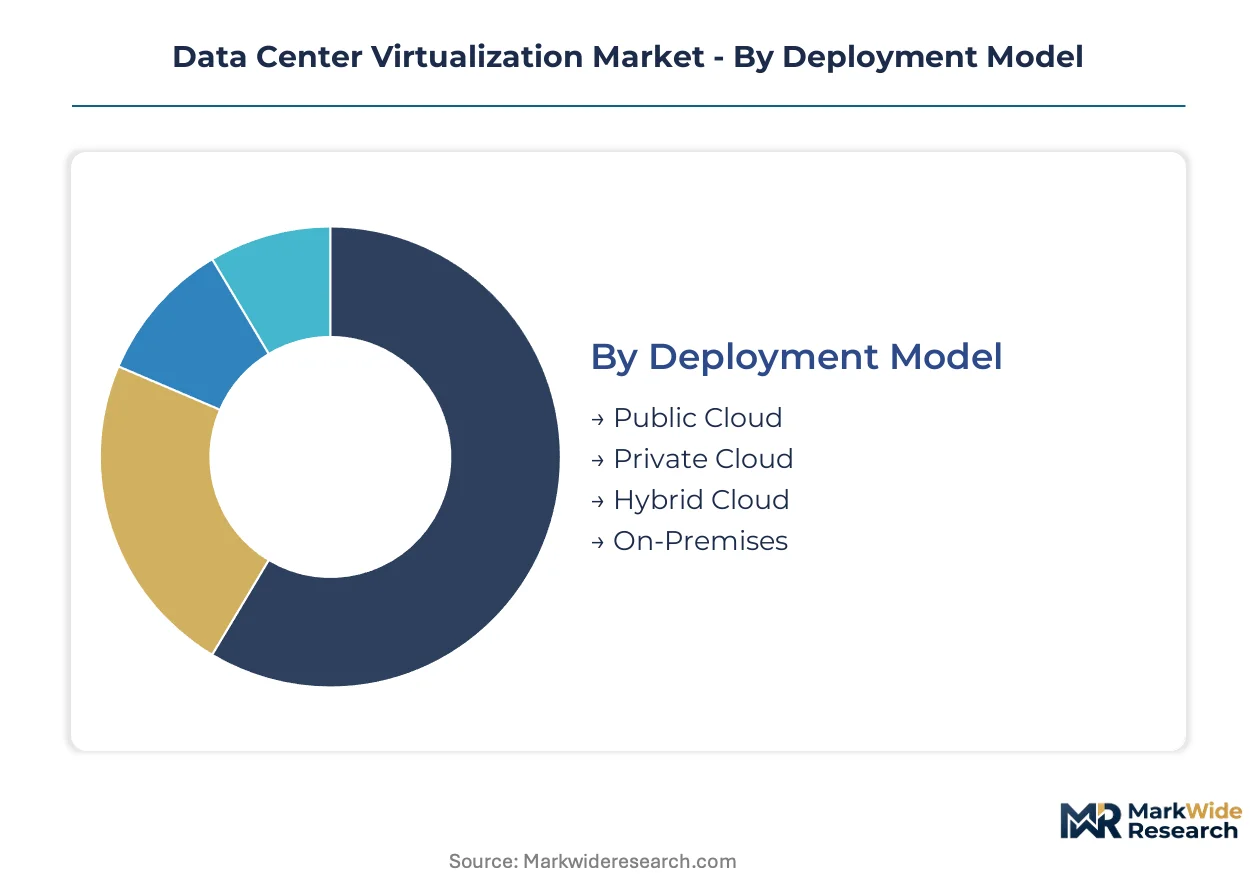
Virtualization procurement splits across deployment sovereignty requirements and workload isolation needs. Certification burdens from GDPR, EU AI Act, and NIST frameworks filter vendor eligibility differently across each segment boundary.
Deployment Model:
GDPR and EU AI Act compliance obligations concentrate heaviest in private and hybrid configurations, while NIST cybersecurity frameworks shape federal eligibility for on-premises deployments.
- Public Cloud:Multi-tenant infrastructure delivers elastic compute pools through hyperscaler-managed hypervisors. Financial services firms in Frankfurt's cloud corridor favor this model for risk analytics burst capacity, though EU AI Act data lineage requirements constrain workload placement.
- Private Cloud:Dedicated virtualized environments isolate tenant resources on single-organization hardware. India's BIS and MeitY localization mandates privilege domestic private cloud buildouts, opening white space outside hyperscaler dominance.
- Hybrid Cloud:Unified orchestration spans on-premises and off-premises virtualized assets. Enterprises balance sovereignty requirements against elasticity needs through consistent Kubernetes control planes.
- On-Premises:Fully captive infrastructure maintains physical boundary control for classified workloads. US federal agencies prioritize this model under NIST 800-53 and FedRAMP baselines.
Leading the category by volume: Private Cloud. Expanding most quickly: Hybrid Cloud.
Solution Type:
Capital allocation intensity varies sharply—storage virtualization commands the largest infrastructure budgets, while network virtualization climbs fastest on 5G core and SD-WAN replacement cycles.
- Server Virtualization:Hypervisor abstraction partitions physical compute into isolated virtual machines. VMware's vSphere ecosystem anchors enterprise hybrid deployments, though container-native alternatives erode licensing attach rates.
- Storage Virtualization:Software-defined layers consolidate siloed arrays into unified addressable fabrics. Financial services allocate disproportionate capital here to support real-time risk analytics throughput requirements.
- Network Virtualization:SD-WAN and NFV deployments displace proprietary hardware at mobile operators. Telecom 5G core buildouts accelerate software-defined infrastructure procurement across European and Indian markets.
- Desktop Virtualization:Centralized endpoint control serves regulated industries with strict data residency mandates. Narrower margin pools concentrate in healthcare and government sectors requiring centralized endpoint governance.
Storage virtualization captures the largest capital share. Network virtualization posts the steepest expansion trajectory.
End User:
Procurement sophistication stratifies sharply—enterprises negotiate outcome-guaranteed service contracts, while government buyers filter through certification gates that disqualify non-compliant vendors.
- Enterprise:Large organizations procure guaranteed latency and availability metrics rather than discrete server licenses. German financial services firms exemplify this shift toward outcome-based infrastructure contracting.
- Service Provider:Multi-tenant operators aggregate demand across downstream customers. Hyperscaler corridor concentration in Frankfurt privileges vendors with sub-millisecond latency guarantees.
- Government:Public sector procurement runs through NIST, FedRAMP, and EU cybersecurity certification frameworks. Vendor qualification timelines extend deployment cycles but create preferential access lanes for compliant platforms.
- Academic:Research institutions virtualize HPC and AI training workloads with limited budget elasticity. EU AI Act governance requirements complicate cross-border collaboration architectures.
Enterprise segment dominates absolute spend. Government vertical climbs fastest on federal cloud migration tailwinds.
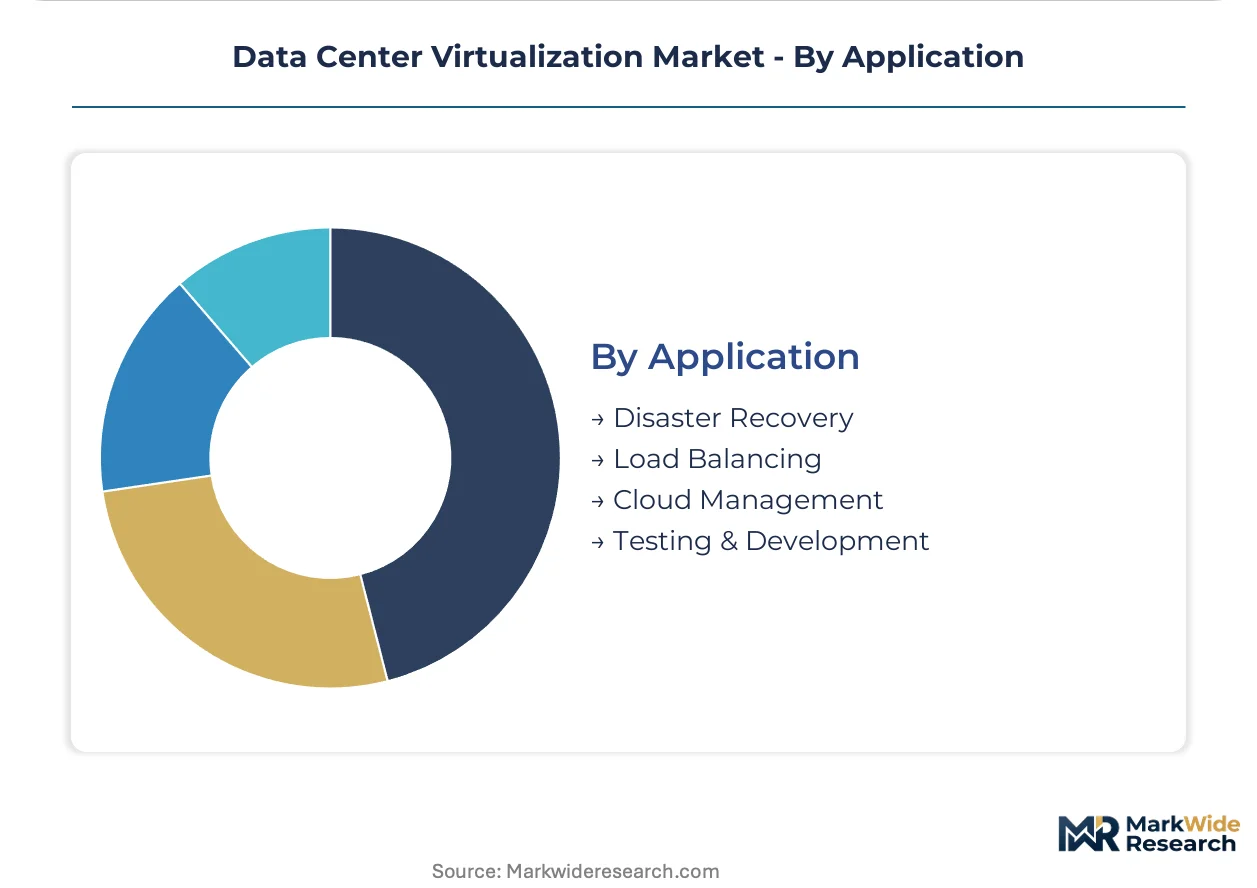
Application:
Workload criticality determines virtualization architecture—disaster recovery and load balancing demand sub-millisecond failover guarantees, while testing environments tolerate higher latency tolerance.
- Disaster Recovery:Synchronous replication between virtualized sites enforces aggressive RPO targets. Financial services mandate near-zero data loss for trading system continuity.
- Load Balancing:Traffic distribution across virtualized compute pools maintains application responsiveness. E-commerce and digital banking platforms drive demand for intelligent traffic steering.
- Cloud Management:Unified control planes orchestrate multi-cloud virtualized resources. Kubernetes-native tooling displaces legacy proprietary management stacks.
- Testing & Development:Ephemeral virtualized environments accelerate software release cycles. Lower criticality permits container-native virtualization without full hypervisor overhead.
Disaster recovery leads by infrastructure commitment. Cloud management gains share fastest on multi-cloud complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in Taiwan and South Korea anchor Asia-Pacific virtualization hardware supply chains. Frankfurt's cloud corridor and Northern Virginia's data center alley concentrate software-defined infrastructure demand. Regulatory fragmentation across GDPR, EU AI Act, and NIST frameworks reshapes procurement geography.
United States
Financial services in New York and Chicago drive real-time risk analytics virtualization. NIST cybersecurity frameworks and FedRAMP baselines filter federal cloud vendor qualification. Northern Virginia's data center alley sustains hyperscaler expansion for government and enterprise workloads.
Germany
Frankfurt's cloud corridor attracts hyperscaler investment for EU AI Act-compliant sovereign infrastructure. The EU AI Act and GDPR force architectural redesigns for AI training data governance. Bavaria's automotive and industrial automation clusters deploy edge virtualization for factory floor orchestration.
India
BIS and MeitY localization mandates privilege domestic private cloud buildouts outside hyperscaler dominance. Mumbai and Bangalore financial services firms expand virtualized risk analytics capacity. Telangana's Hyderabad corridor concentrates data center construction for sovereign cloud requirements.
United Kingdom
London's financial services sector procures outcome-guaranteed virtualization contracts with sub-millisecond latency targets. The UK Information Commissioner's Office enforces GDPR-aligned data residency for cross-border workloads. Slough and Docklands data center clusters sustain enterprise hybrid deployments.
Japan
Tokyo and Osaka financial institutions virtualize mainframe-dependent core banking systems. METI guidelines shape domestic cloud interoperability standards. Kansai manufacturing corridors deploy edge-container convergence for distributed factory orchestration.
Data Center Virtualization Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors seek Kubernetes-hypervisor convergence. The market structures around three tiers: hyperscaler-integrated platforms, enterprise hybrid specialists, and open-source container-native challengers. Two archetypes anchor positioning: established hypervisor incumbents defending licensing attach rates, and cloud-native entrants dissolving hardware abstraction boundaries. M&A activity and technology licensing agreements concentrate competitive momentum around unified orchestration stacks.
Within the enterprise hybrid tier, VMware and Nutanix exemplify divergent architectural bets on hypervisor-centric versus hyperconverged infrastructure models. Red Hat occupies a position bridging open-source Kubernetes standardization with enterprise support monetization. Microsoft anchors the hyperscaler-integrated vector through Azure Stack distribution across regulated verticals.
| Leading Market Players |
|---|
| Nutanix |
| Red Hat |
| VMware |
| Parallels |
| Scale Computing |
| Microsoft |
| Oracle |
| Broadcom |
| Citrix Systems |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up virtualization specialists anchor supply behavior through aggressive licensing consolidation, while sovereign-backed cloud infrastructure in Germany and India enforces pricing discipline through compliance-mandated procurement thresholds. This ownership fragmentation creates divergent cost structures across enterprise hybrid deployments and hyperscaler-integrated stacks.
Pricing Analysis
Warranty and professional services bundling separates premium virtualization platforms from unbundled open-source alternatives with community-only support. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade against NIST and EU AI Act frameworks, plus volume scale for hyperscaler corridor commitments. Pricing pressure stems from container-native alternatives eroding traditional hypervisor attach rates. Mid-market enterprises exhibit highest price sensitivity due to scarce Kubernetes engineering talent.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea wafer fabrication clusters tighten silicon supply for virtualization hardware, while Indian software engineering pools expand orchestration layer development. Server and storage component supply draws from Taiwan, South Korea, and China manufacturing bases. Single-source vulnerability concentrates in specialized confidential computing hardware extensions. Distribution runs through hyperscaler direct procurement channels and value-added reseller networks serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase where Kubernetes-native orchestration displaces legacy hypervisor-centric architectures, compressing procurement decisions around unified platforms.
For Market Incumbents: Cement hybrid cloud positioning through deeper Azure Stack and VMware vSphere integration to defend against container-native erosion. Prioritize certification investment for NIST 800-53 and EU AI Act compliance to maintain federal and European financial services access. Channel control through outcome-guaranteed service contracts locks in enterprise procurement relationships.
For New Entrants and Emerging Players: Capture India's domestic private cloud buildouts driven by BIS and MeitY localization mandates outside hyperscaler dominance. Target edge-container convergence at factory floors and cell towers with lightweight hypervisor offerings. Go-to-market through telecom NFV procurement channels accelerates 5G core deployment traction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor open-source container-native specialists with enterprise support monetization in European sovereign cloud corridors. Long-term viability hinges on orchestration layer standardization rather than hardware abstraction lock-in. Watch confidential computing hardware extension adoption as inflection indicator for security-premium pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Kubernetes-hypervisor convergence compresses procurement around unified orchestration stacks for hybrid deployments. |
| Acquisition of Specialist Firm | Container-native virtualization challengers extend reach into financial services risk analytics workloads. |
| Strategic Partnership | Hyperscaler alliances with telecom operators accelerate NFV deployment for 5G core buildouts. |
| Geographic Expansion | Frankfurt cloud corridor investments prioritize EU AI Act-compliant sovereign infrastructure over raw compute density. |
| Product Launch | Confidential computing extensions electrify competitive positioning around zero-trust multi-tenant architectures. |
Methodological Framework
Independent corroboration across hyperscaler capex disclosures, SEC infrastructure software filings, and telecom operator procurement records underwrites the qualitative findings. Primary interviews with data center engineering directors, IT procurement officers, platform integration specialists, and channel partner account managers combined with secondary validation from NIST cybersecurity framework documentation, EU AI Act regulatory texts, and BIS localization guidelines. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Rate-of-change decomposition across deployment model, solution type, end user vertical, and application workload criticality dimensions structured the analytical framework. CAGRs derived from segment-level elasticity modeling against infrastructure investment cycles and regulatory compliance timelines. Confidential computing hardware penetration and Kubernetes adoption curves served as technology-transition inputs throughout the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement severity and hyperscaler bare-metal supply concentration. Assumptions reflect sovereign data localization mandate expansion and legacy mainframe emulation cost trajectories. Material deviation in confidential computing standardization or federal cloud migration velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Spain Data Center Rack Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Data Processing and Hosting Services Market