
 Metal Fabrication Robots Market | 2026-2036
Metal Fabrication Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Fabrication Robots Market Foresight
Software-defined predictive maintenance subscriptions is rebalancing revenue models away from pure hardware sales. FANUC Corporation leverages its global service network to sustain long-term customer relationships. KUKA AG anchors European automotive automation through deep manufacturing scale. Yaskawa Electric Corporation differentiates via specialized motion control architectures for high-precision welding tasks.
Metal fabrication robots are programmable multi-axis manipulators designed to execute cutting, welding, stamping, and assembly operations with repeatability tolerances typically below 0.1 millimeter. These systems integrate servo motors, force sensors, and real-time path planning to replace manual labor in hazardous or precision-critical production environments. Articulated robots occupy the dominant position due to six-degree-of-freedom flexibility in complex weld geometries. Collaborative robots represent the fastest-expanding category as fenceless deployment reduces floor space requirements and retooling downtime. The welding application segment commands the largest margin pool because arc welding integration demands specialized torches, seam tracking, and process control software that lock in aftermarket service revenue.
ISO 10218 safety standards and OSHA workplace robotics guidelines shape product design by mandating protective stops, speed separation monitoring, and collaborative force limits. The EU Machinery Directive and CE marking framework restrict market access for non-compliant systems, compelling manufacturers to certify control architectures before European deployment. Stakeholders must monitor how EPA emissions rules for metal cutting processes and evolving NHTSA automotive quality standards redirect R&D investment toward cleaner, more traceable fabrication automation.
Market Dynamics
Automotive OEMs in Germany, Japan, and the United States are consolidating welding robot procurement around single-source suppliers capable of certifying full production lines under ISO 10218 and CE marking requirements, compressing vendor diversity and locking in long-term service contracts.
Growth Catalysts
- EU Machinery Directive compliance mandates:European OEMs must deploy CE-certified robotic systems for market access, forcing replacement cycles and standardizing control architectures across automotive and aerospace fabrication lines.
- Automotive welding automation:Arc welding integration with seam tracking and real-time path planning is displacing manual labor in hazardous environments across Detroit, Stuttgart, and Toyota City production clusters.
- Collaborative robot fenceless deployment:Force-limited cobots reduce floor space requirements and retooling downtime, accelerating adoption in small-batch metal fabrication shops.
Market Restraints
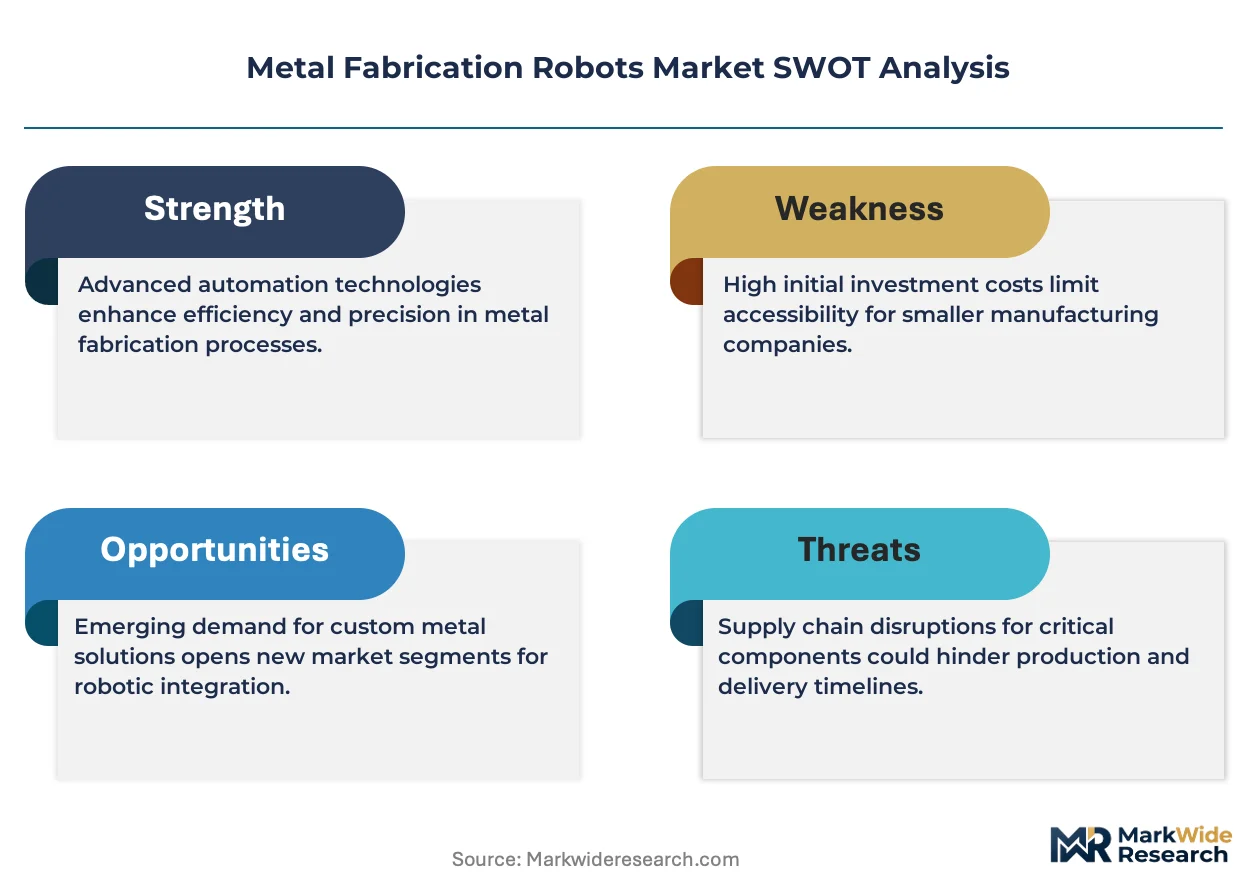
- Servo motor supply concentration:Precision motion control components originate from concentrated East Asian suppliers, exposing European and North American integrators to input volatility and extended lead times.
- OSHA and ISO 10218 certification friction:Multi-jurisdictional safety compliance adds six to twelve months to product launch timelines, delaying revenue recognition for non-specialized vendors.
- Manual welding substitution economics:Low-wage metal fabrication in emerging manufacturing economies retains cost advantage for simple geometries, capping robot penetration in price-sensitive segments.
Strategic Opportunities
- India PLI scheme for manufacturing automation:Production-linked incentives for capital goods are redirecting automotive supplier investment toward certified robotic welding cells in Pune and Chennai industrial corridors.
- EPA emissions rules for metal cutting:Cleaner fabrication mandates are compelling US job shops to automate thermal cutting processes, creating aftermarket retrofit demand for fume-extraction-integrated robot systems.
- AI-driven predictive maintenance convergence:Machine learning overlay on servo motor diagnostics is enabling subscription revenue models that decouple vendor economics from hardware shipment cycles.
Industry Challenges
- Certified robotics technician scarcity:ISO 10218 compliance auditing and collaborative robot force calibration require specialized training pipelines that German and Japanese technical institutes have not scaled to match deployment velocity.
- Legacy PLC integration complexity:Brownfield automotive plants in the US Midwest and UK Midlands face protocol incompatibility between twenty-year-old control systems and modern Ethernet-based robot architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Fabrication Robots Market |
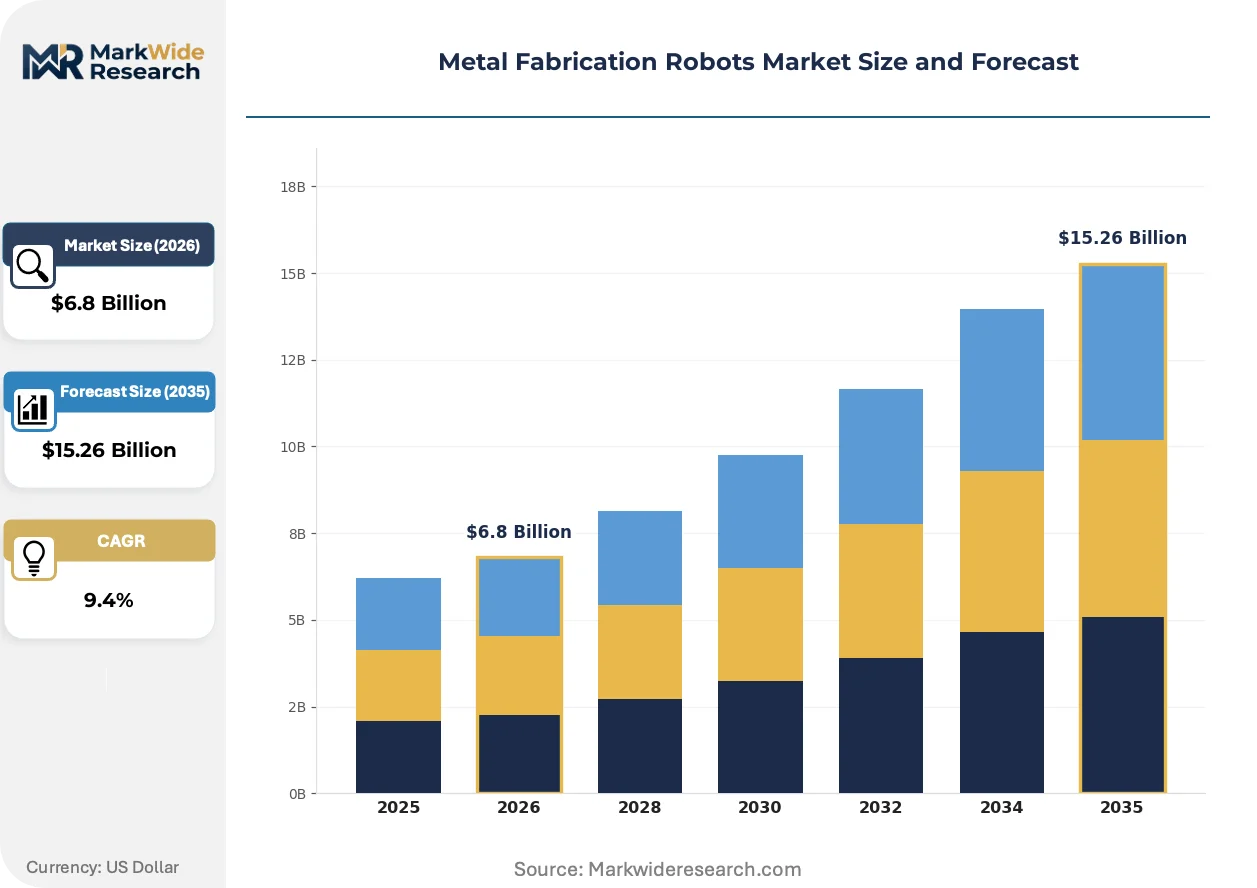
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Articulated Robots, SCARA Robots, Cartesian Robots, Collaborative Robots End User: Aerospace, Automotive Manufacturers, Marine Industry, Heavy Equipment Application: Welding, Cutting, Stamping, Assembly Technology: Plasma Cutting, Laser Cutting, Waterjet Cutting, Robotic Welding |
| Companies Covered | ABB, FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, Kawasaki Heavy Industries, DENSO Robotics, Panasonic Corporation, Stäubli International AG, Universal Robots, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Fabrication Robots Market Shifts & Advancements
Edge-computing architectures are relocating path planning and force feedback processing from centralized controllers to robot-mounted units, compressing latency and enabling real-time adaptive welding in dynamic joint conditions.
Sensor fusion is decentralizing quality assurance by embedding seam tracking, arc monitoring, and bead geometry inspection directly into welding torch assemblies. Tier-one automotive suppliers in Germany and Japan are deploying these integrated heads at scale, eliminating offline inspection stations and compressing throughput time in high-mix battery tray fabrication.
REACH and RoHS substance restrictions are reshaping robot component specifications across European deployment. Cable insulation, servo motor coatings, and controller housings must now certify absence of restricted phthalates and heavy metals, forcing redesign cycles and supplier qualification delays that favor incumbents with established compliance laboratories.
Service unbundling is fragmenting traditional robot procurement in North American job shops. Buyers now separate hardware acquisition from programming, maintenance, and software licensing, compressing upfront capital requirements while elongating vendor relationships. This pattern is most visible in Texas and Ohio metal fabrication clusters where private equity-backed consolidators standardize multi-site robot fleets through centralized service contracts rather than per-location capex approval.
Metal Fabrication Robots Market Segmentation
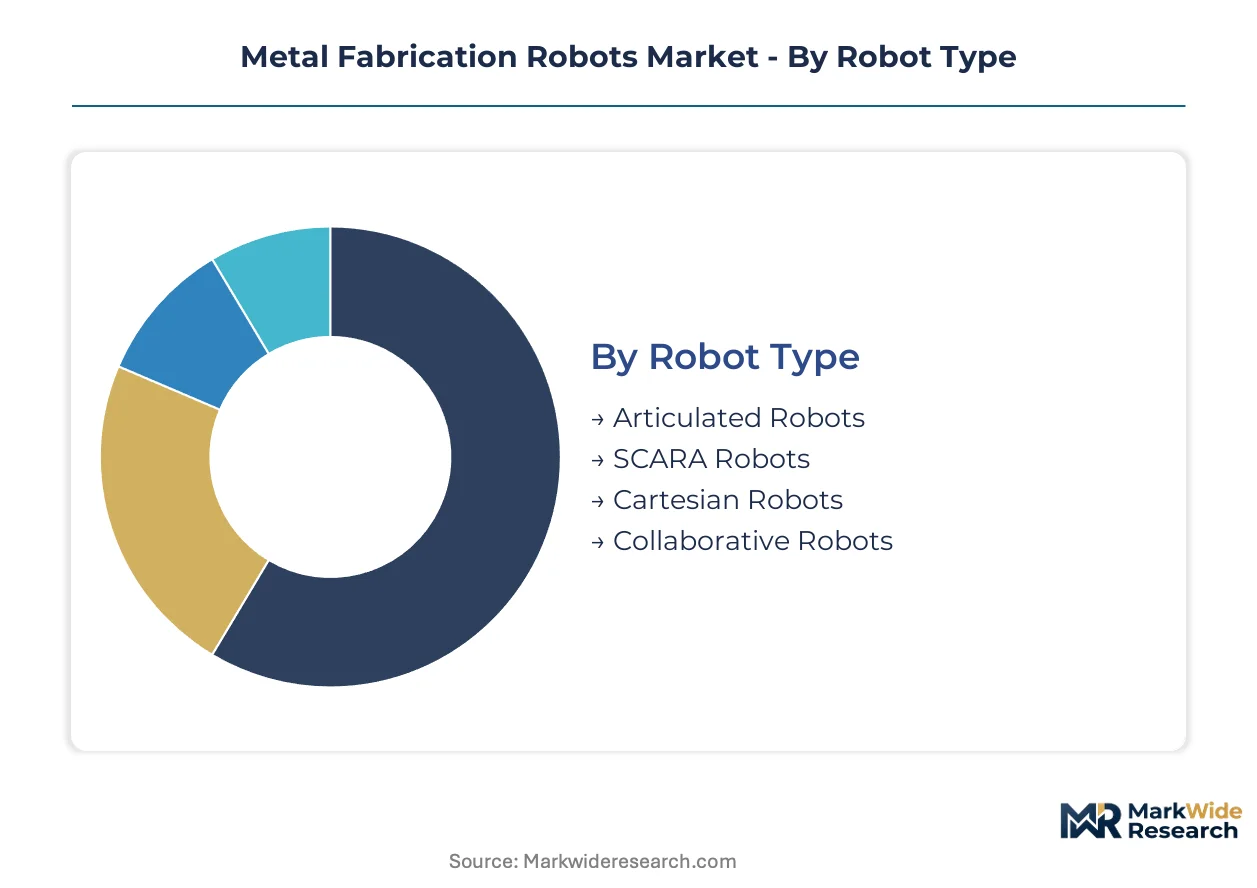
Robot type and application segmentation determines capital allocation patterns across automotive and aerospace fabrication clusters. End-user concentration in Germany, Japan, and the United States drives divergent procurement specifications for welding precision and throughput requirements.
Robot Type:
Six-axis articulated systems demand the highest upfront capital outlay due to servo motor density and control architecture complexity.
- Articulated Robots:Six-degree-of-freedom manipulators with rotary joints enable complex weld geometries in automotive underbody assembly. German OEMs in Stuttgart anchor procurement volume for high-payload arc welding cells.
- Collaborative Robots:Force-limited cobots with fenceless safety certification reduce floor space requirements and retooling downtime. Small-batch metal fabrication shops in Texas and Ohio are accelerating deployment for mixed-model production.
- SCARA Robots:Selective compliance assembly robots excel in planar stamping operations with high repeatability.
- Cartesian Robots:Linear-motion gantry systems dominate large-format plasma cutting in heavy equipment fabrication.
Articulated robots absorb the bulk of installed capacity; collaborative robots are expanding most quickly.
End User:
Automotive manufacturers concentrate procurement volume through single-source supplier contracts that certify full production lines.
- Automotive Manufacturers:Tier-one suppliers deploy robotic welding cells for battery tray fabrication and chassis assembly. Toyota City and Detroit production clusters drive specification standardization under ISO 10218 compliance mandates.
- Aerospace:Airframe fabricators require sub-millimeter repeatability for titanium and aluminum alloy joining. Boeing and Airbus supplier networks in Wichita and Toulouse anchor demand for specialized seam-tracking systems.
- Heavy Equipment:Caterpillar and Komatsu suppliers automate thick-plate welding for excavator boom fabrication.
- Marine Industry:Shipyards in South Korea and Japan deploy gantry-mounted robots for hull section assembly.
Automotive manufacturers command the dominant share of annual robot procurement; aerospace is gaining share fastest on precision requirements.
Application:
Welding applications lock in the highest aftermarket service revenue through specialized torch integration and process control software.
- Welding:Arc welding with real-time seam tracking and adaptive path planning displaces manual labor in hazardous environments. EPA emissions rules for metal cutting processes are redirecting investment toward fume-extraction-integrated systems in US job shops.
- Cutting:Thermal and mechanical cutting operations demand precision motion control for kerf width consistency. Laser cutting cells in German automotive supplier parks achieve throughput rates that justify premium servo motor specifications.
- Stamping:High-speed press tending requires synchronized robot-to-press communication protocols.
- Assembly:Nut-running and fastening operations concentrate in collaborative robot deployments for ergonomic relief.
Welding commands the largest installed base; cutting is climbing the fastest on cleaner fabrication mandates.
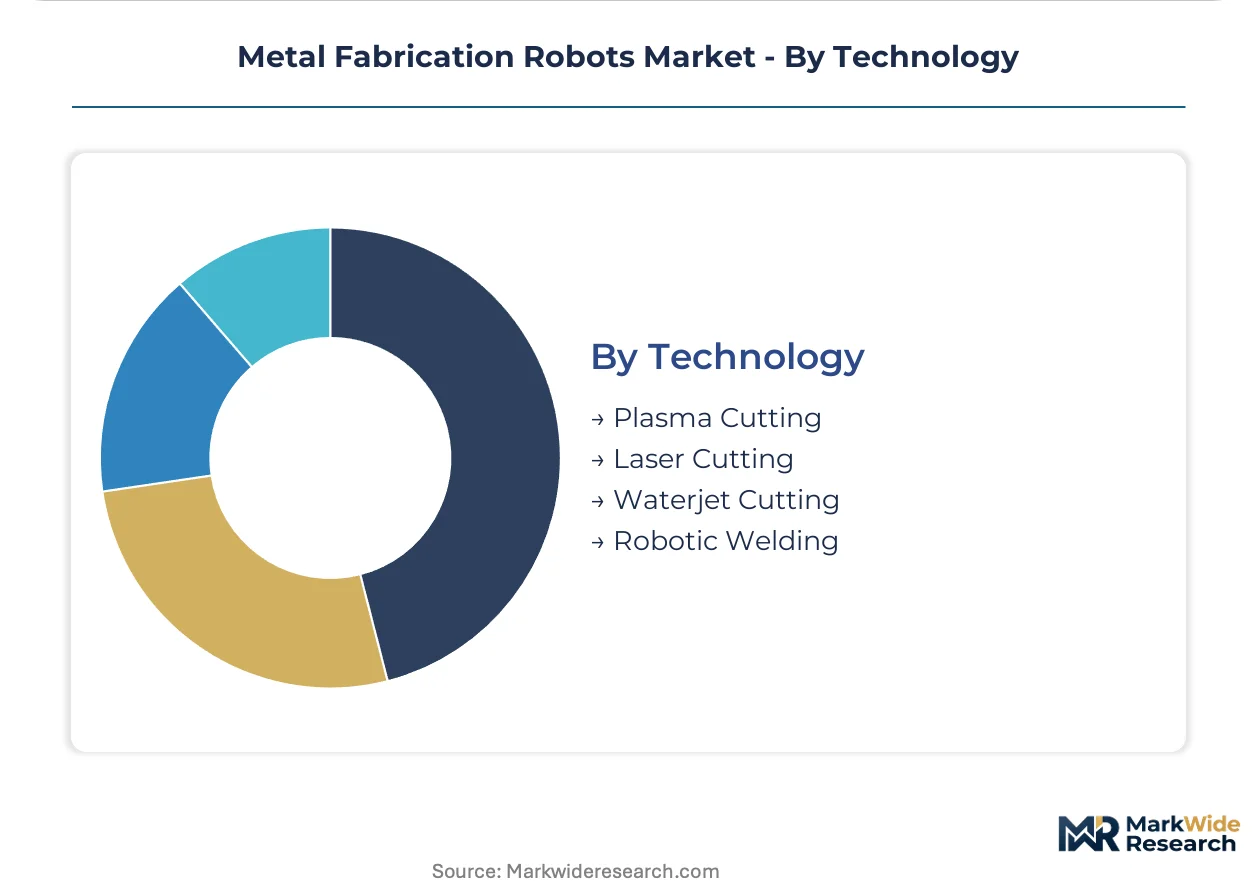
Technology:
Laser cutting systems require the most sophisticated motion control architectures due to beam delivery precision requirements.
- Robotic Welding:Integrated torch assemblies with embedded arc monitoring and bead geometry inspection eliminate offline quality stations. FANUC and KUKA service networks sustain long-term revenue through predictive maintenance subscriptions.
- Laser Cutting:Fiber laser integration with robotic beam delivery enables high-speed processing of reflective metals. Automotive battery tray fabricators in Japan specify these systems for copper and aluminum joining.
- Plasma Cutting:High-velocity thermal cutting dominates thick-plate applications in heavy equipment.
- Waterjet Cutting:Abrasive jet systems serve specialty applications requiring no heat-affected zone.
Robotic welding retains the dominant technology position; laser cutting shows the steepest expansion trajectory on precision demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian component foundries while consumption gravitates toward German, Japanese, and US automotive assembly corridors. This geographic split shapes capital flow patterns and certification requirements across the value chain.
United States
Automotive OEMs in Detroit and battery fabricators across the Midwest are consolidating welding robot procurement under EPA emissions compliance mandates. OSHA workplace robotics guidelines enforce ISO 10218 safety standards for fenceless collaborative deployments. Texas and Ohio metal fabrication clusters are unbundling service contracts from hardware acquisition to compress upfront capital requirements.
Germany
Stuttgart automotive suppliers anchor European demand for high-payload arc welding cells with sub-millimeter repeatability specifications. The EU Machinery Directive and CE marking framework restrict market access to certified control architectures, forcing replacement cycles across brownfield plants. Bavaria and Baden-Württemberg production corridors standardize on single-source supplier contracts that lock in long-term predictive maintenance subscriptions.
Japan
Toyota City and Nagoya production clusters drive specification standardization for battery tray fabrication and chassis assembly automation. METI industrial policy reinforces domestic robot deployment through supply chain security incentives. Kanto and Kansai manufacturing belts concentrate precision motion control R&D for seam-tracking integration in high-mix production environments.
China
MIIT industrial upgrading directives accelerate robot substitution in Yangtze River Delta metal fabrication shops facing wage pressure. GB standards and SAMR certification requirements reshape control architecture specifications for domestic market access. Pearl River Delta export manufacturers are retrofitting thermal cutting cells with fume-extraction-integrated systems to meet tightening environmental enforcement.
India
The PLI scheme for manufacturing automation redirects automotive supplier investment toward certified robotic welding cells in Pune and Chennai industrial corridors. BIS standards alignment with ISO 10218 is compressing vendor qualification timelines for European and Japanese OEMs. Maharashtra and Tamil Nadu fabrication clusters represent the fastest-expanding adoption frontier for fenceless collaborative robot deployment in small-batch production.
Metal Fabrication Robots Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the robot architecture stack, creating a tiered vendor ecosystem where servo motor foundries and control software houses occupy distinct margin pools. The market structure consolidates around full-line integrators capable of certifying complete production lines under multi-jurisdictional safety frameworks. Three archetypes dominate: Japanese precision-motion specialists, European automotive-centric system integrators, and Danish collaborative robot pure-plays. Competitive dynamics center on strategic partnerships for sensor fusion integration and geographic expansion through localized service network buildout.
Among Japanese precision-motion specialists, FANUC Corporation and Yaskawa Electric Corporation exemplify the archetype of vertically integrated control architecture providers. KUKA AG anchors the European system integrator tier with deep manufacturing scale and automotive line certification capabilities. Universal Robots occupies the collaborative robot pure-play position, representing the asset-light design philosophy that reduces floor space requirements through force-limited fenceless deployment.
| Leading Market Players |
|---|
| ABB |
| FANUC Corporation |
| KUKA AG |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries |
| DENSO Robotics |
| Panasonic Corporation |
| Stäubli International AG |
| Universal Robots |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up metal fabrication specialists in Texas and Ohio are consolidating multi-site robot fleets through centralized service contracts, compressing vendor diversity while anchoring pricing discipline through volume aggregation and standardized maintenance subscriptions.
Pricing Analysis
Cost-down pressure on mid-tier articulated systems accelerates because automotive OEMs in Detroit and Stuttgart are consolidating procurement around single-source suppliers capable of certifying full production lines under ISO 10218 and CE marking requirements. Three-tier pricing structure across premium, standard, and economy levels separates FANUC and KUKA's predictive maintenance-bundled offerings from entry-level Chinese systems. Price differentiation hinges on certification grade and after-sales service intensity, with European automotive buyers least price-sensitive due to compliance mandates and small-batch job shops most sensitive to upfront capital outlay.
Supply Chain Analysis
Refurbishment flows for servo motors and force sensors are creating secondary supply channels that buffer lead time volatility for North American integrators facing extended procurement cycles. Precision motion control components draw from concentrated East Asian supply bases in Japan, South Korea, and Taiwan, with harmonic drive gears and high-resolution encoders anchoring robot arm production. Single-source vulnerability around rare-earth magnet supply for servo motors exposes European and North American assemblers to input volatility. Distribution runs through certified system integrators who bundle hardware, programming, and compliance auditing for automotive end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified robotics technician scarcity is constraining deployment velocity, propping pricing for predictive maintenance subscriptions as buyers trade upfront hardware discounts for elongated service lock-in.
For Market Incumbents: Anticipate margin compression in standard articulated robot hardware as Chinese manufacturers achieve CE marking compliance for European market access. Defend position by deepening backward integration into servo motor production and expanding certified service network density in Germany's Baden-Württemberg corridor. Prioritize AI-driven predictive maintenance R&D to decouple revenue from hardware shipment cycles and lock in long-term automotive customer relationships. For New Entrants and Emerging Players: The premium-to-economy price gap in collaborative robot deployments creates white-space opportunity for fenceless systems targeting small-batch metal fabrication shops in India's Pune and Chennai industrial corridors. Target automotive supplier parks seeking ISO 10218-compliant welding cells under PLI scheme incentives. Pursue unbundled service contracting models that separate hardware acquisition from programming and maintenance to compress buyer capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor European system integrators with established CE marking laboratories and automotive line certification capabilities in Germany and Eastern Europe. Long-term viability rests on predictive maintenance subscription attach rates and software-defined control architecture ownership. Monitor EPA emissions rule enforcement intensity for metal cutting processes as inflection indicator for aftermarket retrofit demand in US job shops.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription Buildout | FANUC and KUKA service networks sustain recurring revenue decoupled from hardware cycles. |
| CE Marking Laboratory Investment | EU Machinery Directive compliance mandates restrict market access to certified control architectures. |
| Collaborative Robot Force Calibration Certification | OSHA fenceless deployment guidelines create technician scarcity premium for qualified service providers. |
| Edge-Computing Path Planning Integration | Real-time adaptive welding in dynamic joint conditions compresses latency for automotive battery tray fabrication. |
| India PLI Scheme Localization Partnership | Production-linked incentives redirect automotive supplier investment toward Pune and Chennai robotic welding cells. |
Research Methodology
Independent corroboration across plant engineers at Tier 1 automotive suppliers, procurement leads at German OEMs, and aftermarket service heads at robot integrators underwrites the qualitative findings. Secondary validation drew from SEC 10-K filings, EU Machinery Directive certification databases, and customs trade data for servo motor and harmonic drive imports. Bottom-up unit deployment estimates triangulated against top-down automotive production capacity projections across the analysis window.
Rate-of-change decomposition across robot type, application, end-use industry, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth trajectories weighted by installed base and replacement cycle timing. Forecast inputs incorporated EPA emissions rule enforcement schedules, MIIT industrial upgrading directives for Chinese fabricators, and BIS standards alignment timelines for Indian market access.
Inputs from OEM procurement teams and certified system integrators were available through the study window; gaps in small-batch job shop deployment data introduce uncertainty bands around collaborative robot adoption velocity. Forecasts reflect documented assumptions regarding compliance timeline adherence and technician training pipeline scaling. Practitioners should monitor ISO 10218 auditor certification rates and REACH substance restriction enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Inspection Robots Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Asia-Pacific AUV Market