
 South Korea Data Center Physical Security Market | 2026-2036
South Korea Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Physical Security Market Insights
ISO 27001 certification for physical security management is redrawing vendor eligibility in South Korea's data center procurement pipeline. Schneider Electric leverages its integrated power and security platform to anchor large hyperscale contracts. Hanwha Vision Co., Ltd. dominates domestic camera supply through localized manufacturing and government project relationships. Bosch Sicherheitssysteme GmbH competes on German-engineered fire detection integration with access control architectures.
South Korea data center physical security encompasses perimeter hardening, biometric identity verification, video surveillance with edge analytics, and environmental threat mitigation for mission-critical IT infrastructure. Systems typically deploy IP67-rated outdoor cameras, multi-factor biometric readers, and VESDA-class early smoke detection to maintain sub-15-minute emergency response windows. Access Control Systems and Surveillance Cameras command the largest installed base, though Video Analytics within the Technology dimension shows the fastest structural expansion as AI-enabled behavior recognition replaces passive monitoring. Managed Services across the Service Type dimension captures expanding margin pools as facilities outsource 24/7 security operations center staffing.
MFDS guidelines on pharmaceutical data integrity and KISA critical infrastructure protection standards shape product certification requirements and facility audit cycles. The Personal Information Protection Commission enforces biometric data handling protocols that constrain vendor system architectures. Stakeholders must monitor evolving NIS2-equivalent domestic legislation and its interaction with cloud provider security obligation frameworks.
Market Dynamics
Cloud service providers are expanding hyperscale footprints across Seoul and Busan, compressing procurement cycles and elevating ISO 27001 certification from preference to mandatory vendor eligibility criterion. This concentration of buyer power is restructuring supplier relationships and technical specifications simultaneously.
Growth Catalysts
- MFDS cybersecurity convergence mandate:Pharmaceutical data integrity requirements are mandating integrated physical-digital security architectures, creating specification pull for unified platform vendors.
- Hyperscale facility construction:Cloud providers are commissioning multi-megawatt facilities in the Seoul metropolitan cluster, generating concentrated demand for perimeter hardening and biometric access systems.
- Edge analytics capability maturation:AI-enabled behavior recognition is replacing passive video monitoring, expanding addressable service revenue pools for security operations center outsourcing.
Market Restraints
- Biometric data handling compliance:Personal Information Protection Commission protocols constrain system architectures, adding certification layers that extend deployment timelines.
- Specialized component supply concentration:VESDA-class early smoke detection modules and IP67-rated outdoor camera enclosures depend on limited domestic manufacturing capacity.
- Technical integration complexity:Multi-factor biometric readers must interface with legacy access control infrastructure, creating interoperability friction during facility retrofits.
Strategic Opportunities
- Busan digital port zone expansion:Maritime logistics data center construction is accelerating, creating geographic diversification beyond Seoul saturation.
- KISA critical infrastructure protection alignment:Evolving NIS2-equivalent domestic legislation is tightening audit cycles, expanding recurring managed services contracts.
- Video analytics-environmental monitoring convergence:Edge AI and early smoke detection integration is enabling predictive threat response platforms that command premium pricing.
Industry Challenges
- Cyber-physical security skill synthesis:Facilities require personnel fluent in both biometric system administration and network security protocols, a combination scarce in regional labor markets.
- Multi-certification timeline compression:Vendors must simultaneously achieve ISO 27001, KISA, and MFDS approvals to qualify for hyperscale procurement, straining quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Physical Security Market |
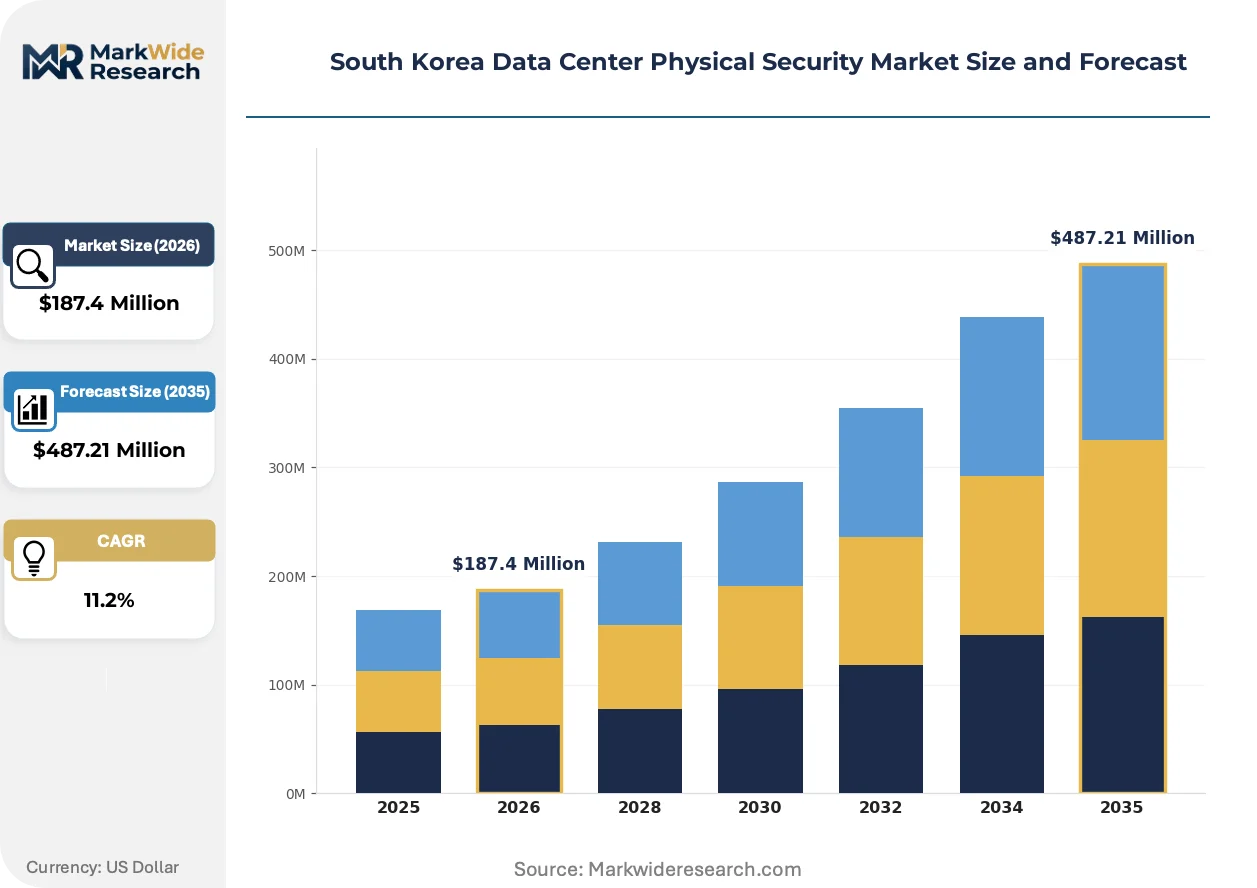
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Access Control Systems, Surveillance Cameras, Intrusion Detection Systems, Fire Detection Systems Technology: Biometrics, RFID, Alarm Systems, Video Analytics End User: Telecom Operators, Cloud Service Providers, Enterprises, Government Agencies Service Type: Consulting, Installation, Maintenance, Managed Services |
| Companies Covered | Hangzhou Hikvision Digital Technology Co Ltd, Schneider Electric, Axis Communications AB, ASSA ABLOY, ABB Ltd, Honeywell International Inc, Hanwha Vision Co., Ltd., Bosch Sicherheitssysteme GmbH, Johnson Controls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Physical Security Market Trends and Innovations
Physical security systems are transitioning from standalone perimeter protection to integrated cyber-physical platforms that unify biometric identity, environmental threat detection, and real-time video analytics under centralized management architectures.
AI-enabled behavior recognition is supplanting rule-based motion detection in video surveillance deployments. Hyperscale operators are specifying edge-analytics cameras that process object classification and anomaly flagging locally, reducing bandwidth consumption and enabling sub-15-minute emergency response windows. This compression of detection-to-response latency is redefining competitive differentiation among system integrators.
KISA critical infrastructure protection standards are mandating hardened facility designs with redundant authentication pathways. Data center operators must demonstrate biometric access logging, environmental monitoring continuity, and physical breach simulation testing to maintain operational licenses. The compliance burden falls heaviest on colocation providers serving financial services and healthcare verticals.
Security operations center staffing is migrating from in-house teams to specialized managed services providers. Colocation and enterprise facility operators are unbundling 24/7 monitoring from hardware procurement, preferring outcome-based contracts that tie vendor compensation to incident response metrics. This preference shift is most pronounced in Seoul's hyperscale corridor, where labor costs and round-the-clock coverage requirements favor outsourcing economics.
South Korea Data Center Physical Security Market Segmentation
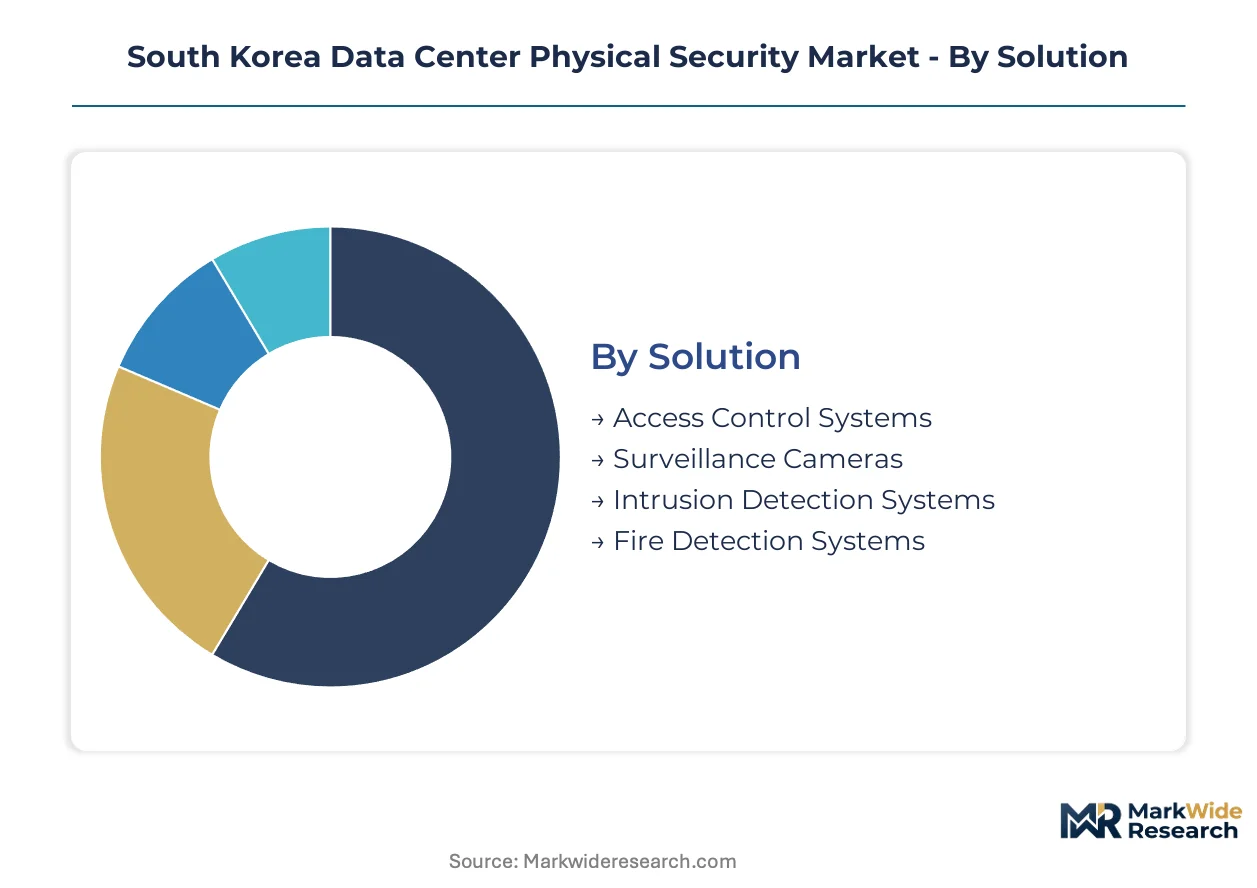
Segmentation in South Korea's data center physical security market reveals how procurement priorities diverge between hyperscale cloud builds and legacy enterprise retrofits. Margin concentration shifts toward integrated platforms that bundle hardware with compliance-certification services.
Solution:
Margin pools concentrate in systems that unify multiple threat vectors under single management architectures, reducing integration friction for facility operators.
- Access Control Systems:Multi-factor biometric readers and card-based credentialing form the perimeter authentication layer. Demand concentrates in Seoul's hyperscale corridor where cloud providers mandate ISO 27001-certified installations with redundant authentication pathways.
- Surveillance Cameras:IP67-rated outdoor enclosures and edge-analytics-enabled devices process object classification locally. Busan digital port zone construction is driving specification pull for marine-hardened housings with sub-15-minute emergency response integration.
- Intrusion Detection Systems:Perimeter sensors and volumetric detection arrays protect facility boundaries.
- Fire Detection Systems:VESDA-class early smoke detection modules address mission-critical IT infrastructure environmental threats.
Surveillance Cameras holds installed capacity. Video Analytics is rotating up the share rankings.
Technology:
Technology selection tracks the MFDS cybersecurity convergence mandate, which favors architectures that bridge physical identity verification with digital audit trails.
- Video Analytics:AI-enabled behavior recognition processes anomaly flagging at the edge, reducing bandwidth consumption. Seoul metropolitan cluster hyperscale operators specify these capabilities to compress detection-to-response latency windows.
- Biometrics:Fingerprint, iris, and facial recognition modalities enforce identity verification at facility entry points. Personal Information Protection Commission protocols constrain system architectures, extending deployment timelines for vendors seeking KISA certification.
- RFID:Contactless credentialing supports high-throughput access scenarios.
- Alarm Systems:Centralized notification architectures integrate sensor networks with security operations center dashboards.
Biometrics dominates current procurement volumes. Video Analytics is climbing the fastest.
End User:
Customer type determines contract structure, with cloud providers demanding outcome-based managed services while government agencies prioritize domestic manufacturing content.
- Cloud Service Providers:Hyperscale operators commission multi-megawatt facilities with compressed procurement cycles. These buyers mandate integrated physical-digital security platforms that satisfy both ISO 27001 and KISA critical infrastructure protection standards.
- Government Agencies:Public sector facilities emphasize localized supply chains and MFDS pharmaceutical data integrity alignment. National security classifications require hardened facility designs with redundant authentication pathways and documented breach simulation testing.
- Telecom Operators:Legacy facility retrofits drive replacement demand for perimeter hardening systems.
- Enterprises:Colocation tenants and private data center operators balance capital constraints with compliance requirements.
Cloud Service Providers command the largest contract values. Government Agencies is gaining share fastest.
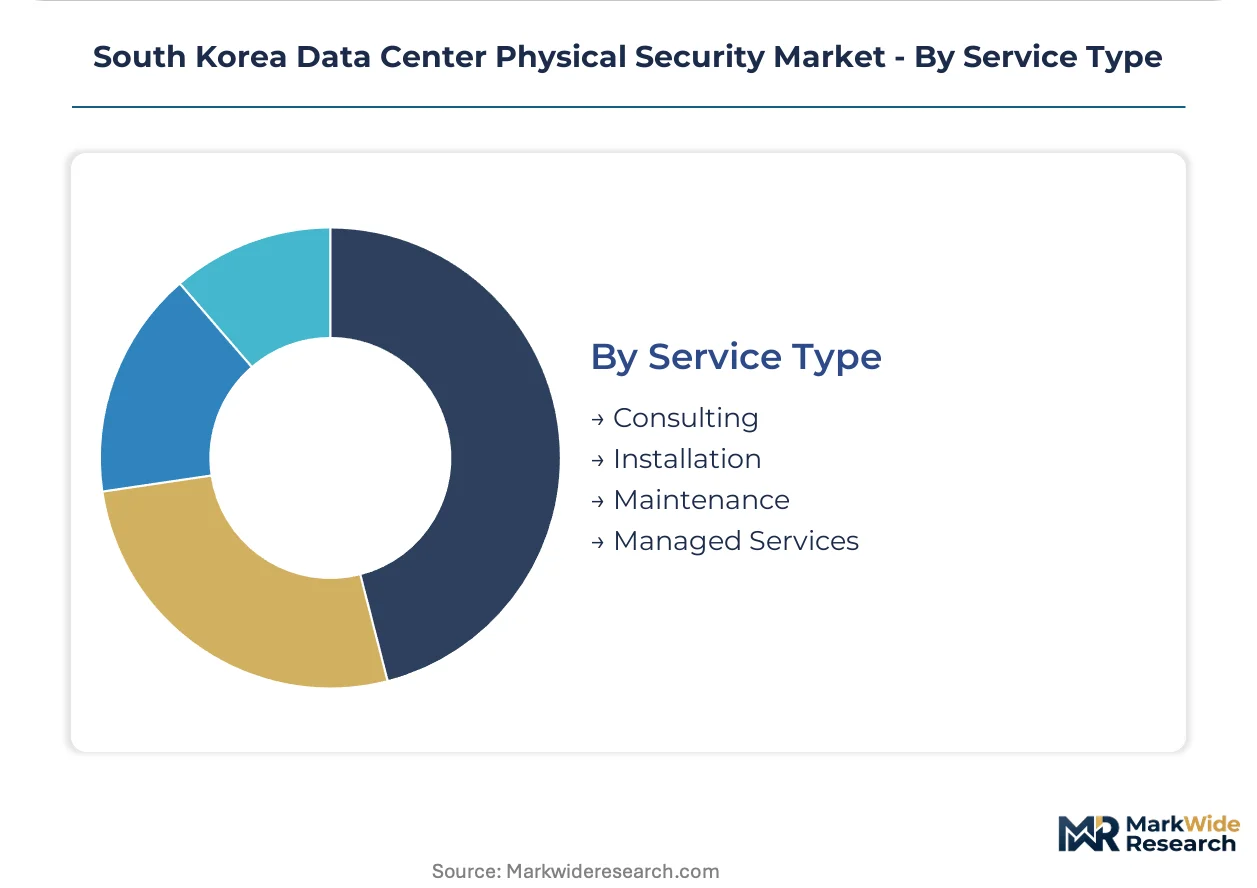
Service Type:
Service revenue expansion correlates with labor cost pressures in Seoul's 24/7 operations environment, where outsourcing economics favor specialized providers.
- Managed Services:Security operations center staffing and 24/7 monitoring unbundle from hardware procurement under outcome-based contracts. Seoul hyperscale corridor operators prefer these arrangements to address round-the-clock coverage requirements without direct employment overhead.
- Consulting:Compliance navigation and certification pathway design support vendor qualification. MFDS, KISA, and ISO 27001 simultaneous approval requirements strain quality assurance bandwidth, creating demand for specialized advisory.
- Installation:System deployment and integration with legacy access control infrastructure.
- Maintenance:Recurring service contracts for sensor calibration and firmware updates.
Installation holds current service revenue volume. Managed Services is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators concentrate procurement power in Seoul's metropolitan corridor, compressing vendor qualification timelines and elevating certification requirements across all sub-regions. The Busan digital port zone is emerging as a secondary demand anchor for maritime logistics data center construction.
Seoul Capital Area
Multi-megawatt hyperscale facilities drive demand for integrated physical-digital security platforms. KISA critical infrastructure protection standards mandate redundant authentication pathways and documented breach simulation testing. Pangyo Techno Valley and Sangam Digital Media City host concentrated colocation construction requiring ISO 27001-certified vendor pools.
Busan-Ulsan
Maritime logistics data center construction accelerates specification pull for marine-hardened camera housings and sub-15-minute emergency response integration. The country's national port authority oversees digital port zone security compliance. Busan's new container terminal data hub commands specialized perimeter hardening systems.
Daegu-Gyeongbuk
Telecom operator facility retrofits generate replacement demand for legacy access control infrastructure. Regional industrial complex regulations require hardened facility designs for manufacturing-adjacent data processing. Gumi's electronics cluster hosts enterprise data center expansion with biometric integration requirements.
Daejeon-Sejong
Government agency data center construction emphasizes localized supply chains and MFDS pharmaceutical data integrity alignment. National security classifications require redundant authentication pathways. Sejong's administrative city hosts public sector facility hardening under strict audit cycles.
Gwangju-Honam
Enterprise colocation demand balances capital constraints with compliance requirements for financial services tenants. Regional data protection protocols constrain biometric system architectures. Gwangju's AI-focused industrial zone drives modest facility construction with edge analytics specifications.
South Korea Data Center Physical Security Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with security divisions alongside specialized surveillance technology developers. Market structure shows moderate concentration around integrated platform providers capable of unified power-security offerings. Two strategic archetypes dominate: multinational technology conglomerates leveraging global certification portfolios, and domestic champions exploiting government project relationships. Competitive moves center on hyperscale contract anchoring and compliance service bundling.
Among Korea-based specialists, Hanwha Vision Co., Ltd. exemplifies the domestic champion archetype through localized manufacturing scale. Schneider Electric and Bosch Sicherheitssysteme GmbH represent multinational platform integrators competing on unified physical-digital security architectures. These three anchors illustrate the tension between domestic procurement preferences and global technology standards in hyperscale qualification processes.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co Ltd |
| Schneider Electric |
| Axis Communications AB |
| ASSA ABLOY |
| ABB Ltd |
| Honeywell International Inc |
| Hanwha Vision Co., Ltd. |
| Bosch Sicherheitssysteme GmbH |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for VESDA-class early smoke detection modules concentrate procurement leverage with hyperscale cloud operators in Seoul, compressing vendor margins while elevating ISO 27001 certification premiums. This inventory tightness feeds directly into pricing power asymmetries across South Korea's data center security supply base.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate hyperscale procurement, where cloud providers mandate three-tier pricing structure across premium, standard, and economy certification levels. Price differentiation centers on KISA compliance tier and after-sales service bundling. Cost compression in standard-tier biometric readers is intensifying because domestic manufacturing capacity constraints force reliance on imported sensor modules. Cloud service providers show least price sensitivity, while regional enterprise colocation operators in Gwangju-Honam exhibit highest elasticity.
Supply Chain Analysis
Inventory buffers for IP67-rated outdoor camera enclosures run lean, with 45-day stock cycles exposing facilities to marine-hardened component shortages. Supply concentrates in South Korea, China, and Germany for edge-analytics chipsets, biometric sensor arrays, and fire detection modules respectively. The chain draws from specialized semiconductor foundries, precision optics manufacturers, and rare-earth magnet suppliers. Single-source vulnerability around AI inference processors creates procurement risk. Distribution runs through system integrators with KISA certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's data center physical security market sits in early-cycle expansion, with MFDS pharmaceutical data integrity mandates and NIS2-aligned hardening rules accelerating platform replacement across legacy facilities. This regulatory tailwind supports penetration growth beyond hyperscale greenfield construction.
For Market Incumbents: Compound platform integration advantages by embedding managed services into hardware contracts, addressing the threat of specialized AI analytics startups displacing passive surveillance vendors. Prioritize backward integration into edge-computing chipsets to defend margin position against component cost volatility. Expand ISO 27001 certification services to capture compliance-navigation revenue from mid-tier colocation operators. For New Entrants and Emerging Players: 24/7 security operations center staffing gaps in Busan digital port zone offer immediate white-space access, where incumbent coverage networks remain underdeveloped. Target maritime logistics data center operators with marine-hardened camera housing specialization and sub-15-minute response guarantees. Pursue KISA certification fast-track partnerships with established system integrators to bypass multi-year qualification barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized security divisions, particularly those holding dormant government project relationships. Long-term viability hinges on cyber-physical convergence capability synthesis. Monitor MFDS enforcement intensity as inflection signal—accelerated audit cycles would compress vendor consolidation timelines and elevate recurring services multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies biometric, video, and environmental monitoring under single KISA-compliant architecture. |
| Managed Services Expansion | Captures 24/7 SOC outsourcing demand from Seoul hyperscale corridor labor cost pressures. |
| Edge Analytics Capability Buildout | Enables sub-15-minute emergency response windows specified by cloud providers. |
| Certification Fast-Track Investment | Compresses ISO 27001, KISA, and MFDS simultaneous approval timelines for hyperscale qualification. |
| Geographic Diversification | Establishes Busan digital port zone presence ahead of maritime logistics data center construction. |
Research Methodology
The analysis maps access control systems, surveillance cameras, intrusion detection, and fire detection segments, each validated through facility security directors, system integrator project managers, and cloud provider procurement leads. Primary fieldwork with data center operators, KISA compliance auditors, and biometric technology vendors combined with secondary validation against KISA infrastructure protection standards, MFDS pharmaceutical guidelines, and hyperscaler capex disclosures. Bottom-up installation base enumeration and top-down market sizing triangulate volume estimates.
Consistency checks against hyperscale construction pipeline data and government facility hardening budgets validated projection outputs across the modeling period. Segmentation dimensions include solution type, technology modality, end-user vertical, service tier, and regional cluster. CAGRs derive from facility construction run-rates, compliance-driven replacement cycles, and managed services penetration curves. Edge AI deployment timelines and biometric reader installation densities inform technology-specific trajectories.
Forecasts assume regulatory continuity in MFDS pharmaceutical oversight and KISA critical infrastructure regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Poland Data Center Market