
 White Box Server Market | 2026-2036
White Box Server Market Size, Share, and Industry Trends Forecast 2026-2036
White Box Server Market Intelligence
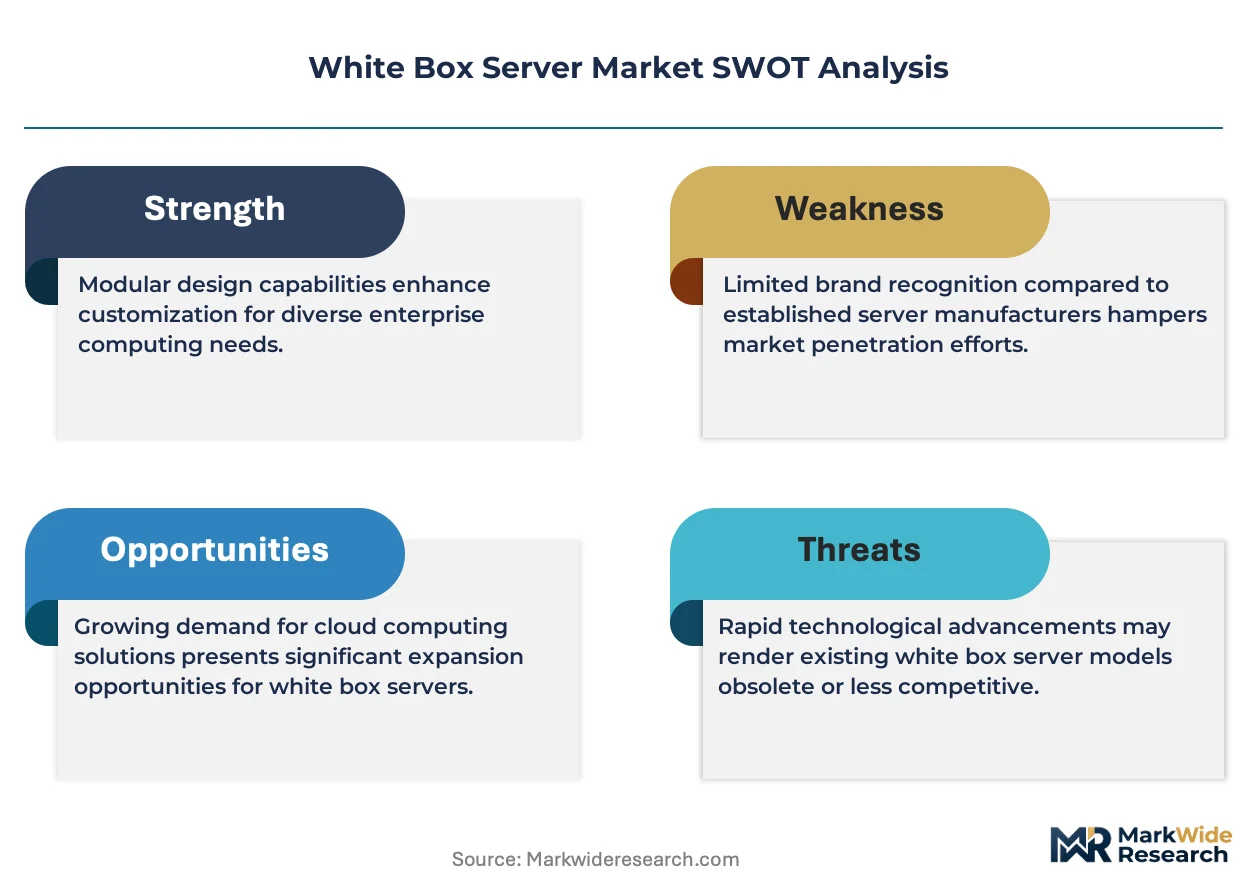
CE marking for IT equipment is collapsing the competitive field as smaller assemblers struggle with electromagnetic compatibility and safety documentation. Quanta Computer leverages its ODM scale to dominate hyperscale contracts across North America and Asia. Super Micro Computer anchors its position through in-house motherboard design and Silicon Valley-adjacent manufacturing. Wistron competes on cost-engineered blade and rack platforms for cloud providers seeking supply diversification.
A white box server denotes an unbranded or custom-configured compute unit built from standardized x86 components, typically supporting multi-socket Intel or AMD processors with PCIe expansion and redundant power supplies, assembled to buyer specifications rather than sold as a finished product. Its primary purpose is to deliver flexible, cost-optimized infrastructure for data centers that prioritize total cost of ownership over vendor-integrated support ecosystems. Rack servers hold the dominant volume position given their density and compatibility with standard 19-inch data center cabinets, while edge computing deployments represent the fastest structural expansion as latency-sensitive workloads push compute away from centralized facilities. Hyperscaler end users command the deepest margin pools through direct ODM relationships that bypass traditional channel markups entirely.
The EPA Energy Star program and the EU Ecodesign Directive shape product roadmaps by mandating minimum efficiency thresholds that disqualify legacy power supply architectures. China's GB standards for electronic product safety and India's BIS registration requirements add compliance layers for suppliers targeting those procurement markets. Procurement teams must monitor how tightening carbon disclosure rules under the EU CSRD alter supplier qualification criteria ahead of the next server refresh cycle.
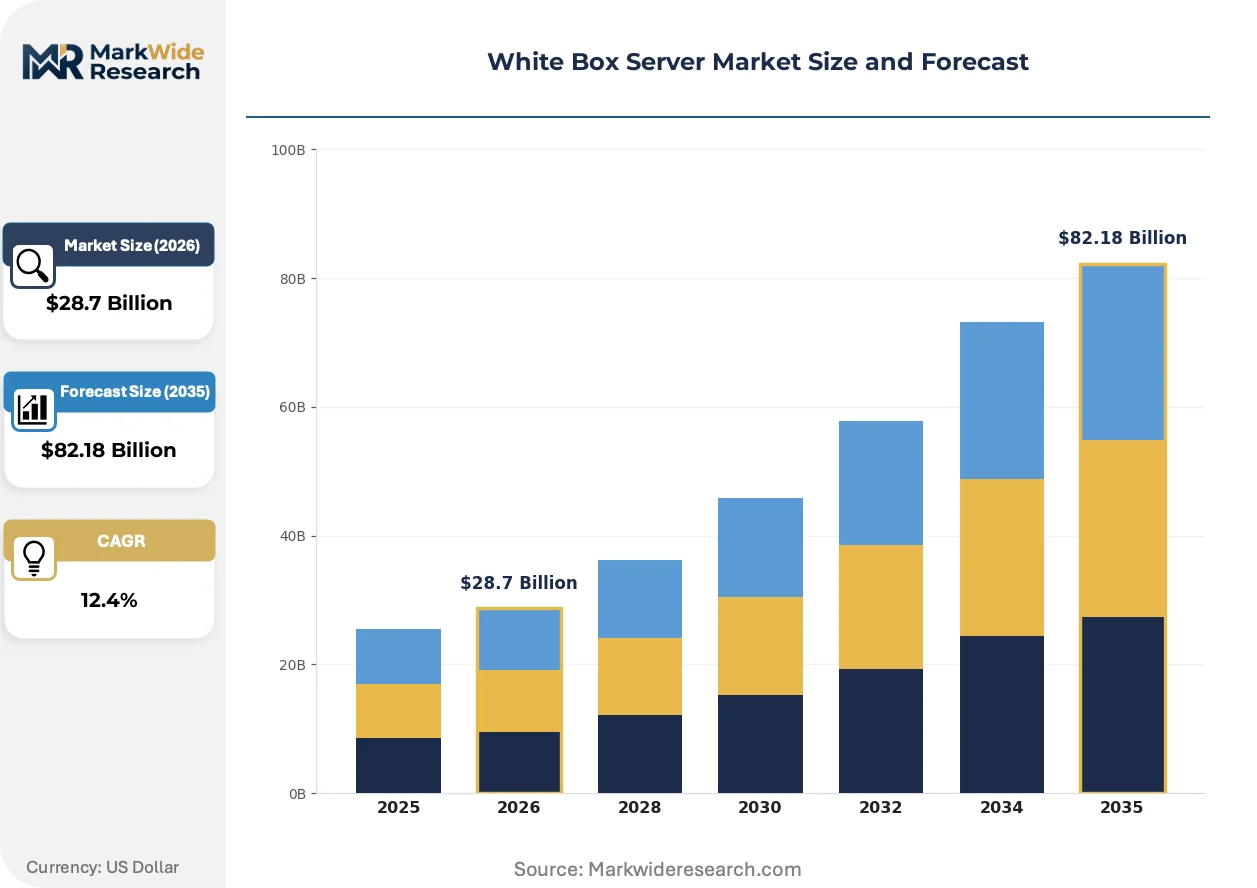
Market Dynamics
Hyperscaler procurement concentration is restructuring supplier relationships as direct ODM engagements displace traditional distribution channels and compress channel margins across the server value chain.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbon refrigerants are accelerating liquid-cooled server deployments in European data centers.
- Hyperscaler cloud infrastructure buildouts:Amazon Web Services, Microsoft Azure, and Google Cloud are expanding bare-metal capacity through direct ODM sourcing.
- Edge computing latency requirements:Distributed AI inference and autonomous systems are pulling compute resources toward metropolitan edge facilities.
Market Restraints
- Memory and GPU supply concentration:NVIDIA H100 allocation constraints and HBM3 supply bottlenecks limit white box configurability for AI training workloads.
- CE marking compliance costs:Electromagnetic compatibility testing and safety documentation requirements exclude smaller regional assemblers from European procurement.
- Power density thermal limits:Air-cooled rack designs face hard ceilings above 30-40kW per cabinet, forcing costly infrastructure retrofits.
Strategic Opportunities
- India BIS registration pathway:Local assembly incentives and domestic data localization mandates are opening captive production opportunities for cloud providers.
- Direct liquid cooling convergence:Integration of cold plate and immersion technologies with high-temperature processors enables 100kW+ rack densities.
- EU CSRD carbon disclosure rules:Scope 3 emissions tracking requirements favor suppliers with verified supply chain transparency and renewable energy sourcing.
Industry Challenges
- Electromechanical design talent scarcity:Shortage of thermal engineers and power distribution specialists capable of 48V direct-current and liquid-cooled integration.
- EPA Energy Star certification timelines:Extended validation cycles for emerging high-efficiency power supply architectures delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Box Server Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $82.18 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Microservers Deployment: On-Premises, Hybrid, Cloud-Based, Edge Computing End User: Data Centers, Enterprises, Telecom Providers, Hyperscalers Service Type: Maintenance, Support, Consulting, Integration |
| Companies Covered | Quanta Computer Inc., Super Micro Computer, Inc., Wistron Corporation, Celestica Inc., Inventec Corporation, Penguin Computing, Hyve Solutions, ZT Systems, Hon Hai Precision Industry Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Box Server Market Strategic Shifts & Innovations
Liquid cooling architectures and disaggregated compute fabrics are rewriting server design paradigms as thermal and economic pressures force departures from legacy air-cooled monolithic systems.
Direct liquid cooling using cold plates and dielectric immersion fluids is displacing conventional air-cooled designs in hyperscale facilities. Microsoft and Google are deploying immersion tanks for AI training clusters exceeding 100kW per rack. This thermal approach is compressing data center real estate requirements and enabling processor power envelopes above 700W.
The EU Ecodesign Directive is mandating minimum efficiency thresholds for server power supplies and idle state consumption. These requirements are disqualifying legacy 80 PLUS Bronze architectures from European procurement. Hyperscalers are responding by specifying titanium-rated power supplies and 48V rack-level distribution to minimize conversion losses.
Direct ODM relationships are unbundling traditional value-added reseller channels as hyperscalers negotiate bare-metal configurations with Quanta, Wistron, and Foxconn. This disintermediation is collapsing channel margins and forcing distributors to pivot toward mid-market enterprise and colocation segments. The shift is most visible in Virginia and Texas data center clusters where AWS, Meta, and Google operate million-square-foot facilities.
White Box Server Market Segmentation
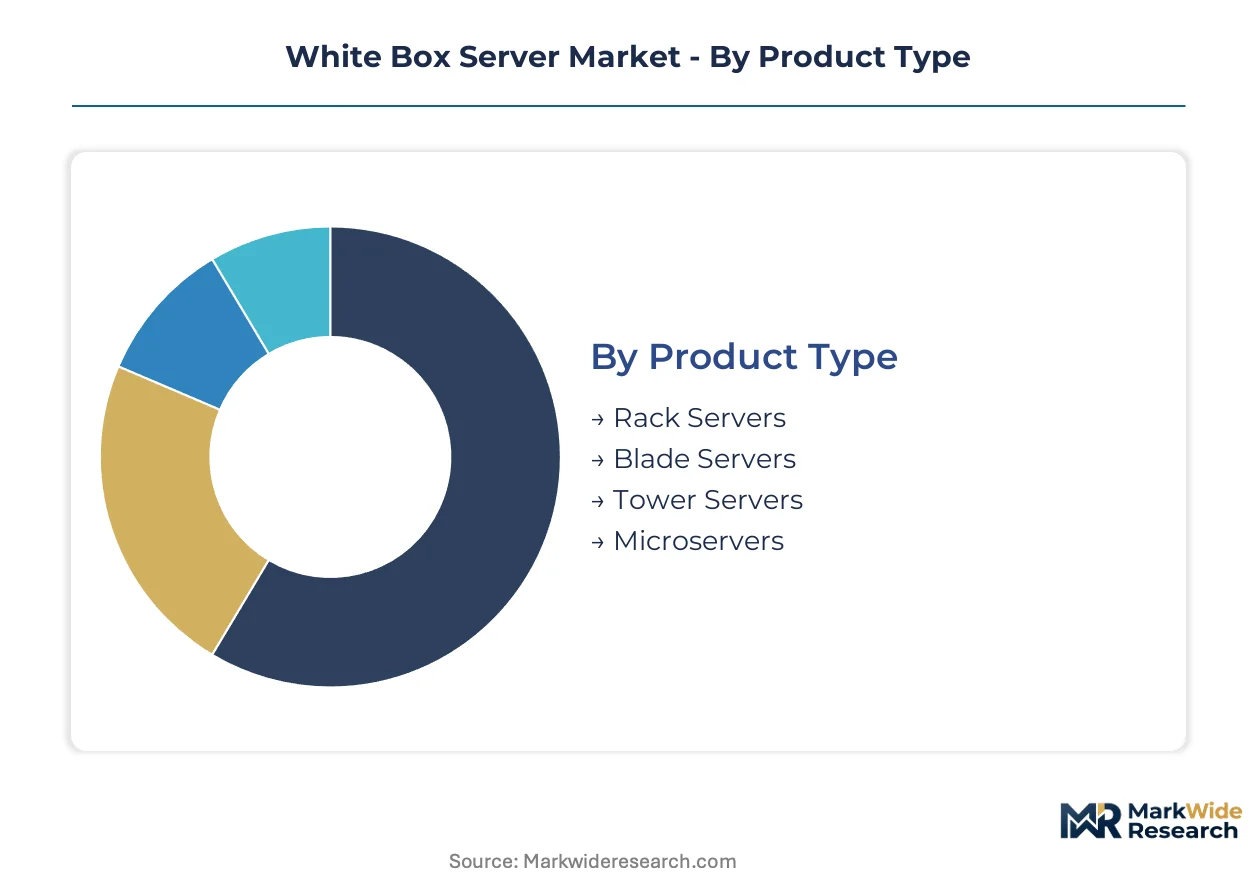
White box server procurement patterns diverge sharply across deployment contexts, with hyperscaler direct sourcing, enterprise refresh cycles, and edge latency requirements creating distinct specification demands. Understanding these segment boundaries clarifies where ODMs can bypass channel markups and where systems integrators retain pricing power.
Product Type:
Margin pools concentrate in high-density rack configurations that hyperscalers procure through direct ODM relationships, while blade platforms serve enterprises seeking vendor-managed infrastructure.
- Rack Servers:Standard 19-inch form factors support multi-socket Intel and AMD configurations with PCIe expansion slots and redundant power supplies. Texas and Virginia data center clusters absorb the largest shipment volumes as AWS, Meta, and Google expand bare-metal capacity. The EPA Energy Star program and EU Ecodesign Directive are disqualifying legacy 80 PLUS Bronze power supply architectures from procurement.
- Blade Servers:Modular chassis designs enable shared power and cooling infrastructure across multiple compute nodes. Wistron competes aggressively on cost-engineered blade platforms for cloud providers pursuing supply diversification. Air-cooled rack designs face thermal ceilings above 30-40kW per cabinet, forcing infrastructure retrofits.
- Tower Servers:Standalone vertical enclosures suit remote office and small business deployments with limited rack infrastructure.
- Microservers:Low-power dense nodes target lightweight web serving and cold storage workloads.
The dominant share belongs to Rack Servers, while Edge Computing deployments in the Deployment category are closing the gap fastest.
Deployment:
Cost tier separation is pronounced between capex-heavy on-premises installations and opex-structured cloud arrangements, with hybrid deployments commanding premium integration fees.
- On-Premises:Enterprise-owned facilities with dedicated power, cooling, and physical security infrastructure. India's BIS registration requirements and domestic data localization mandates are opening captive production opportunities for cloud providers establishing local assembly.
- Hybrid:Workload portability between private infrastructure and public cloud resources with unified orchestration layers. Microsoft's Azure Stack and Google's Anthos are validating white box hardware for these distributed configurations. Procurement teams monitor tightening carbon disclosure rules under the EU CSRD.
- Cloud-Based:Hyperscaler-operated facilities with tenant abstraction from underlying hardware.
- Edge Computing:Metropolitan and near-premises facilities serving latency-sensitive AI inference and autonomous systems. Distributed workloads are pulling compute resources away from centralized facilities with the steepest expansion trajectory.
Cloud-Based deployments hold the dominant share, while Edge Computing is gaining share fastest.
End User:
Customer type determines whether procurement flows through distribution channels or bypasses them entirely via direct ODM negotiation.
- Hyperscalers:Amazon Web Services, Microsoft Azure, and Google Cloud negotiate bare-metal configurations directly with Quanta, Wistron, and Foxconn. This disintermediation collapses channel margins and forces distributors toward mid-market enterprise segments. Direct ODM engagements compress channel margins across the server value chain.
- Data Centers:Colocation and wholesale facilities providing neutral-host infrastructure for enterprise tenants. CE marking compliance costs for electromagnetic compatibility testing exclude smaller regional assemblers from European procurement.
- Enterprises:Corporate IT departments with refresh cycles tied to depreciation schedules and support contract renewals.
- Telecom Providers:5G core and radio access network virtualization driving edge server deployments.
The dominant share belongs to Hyperscalers, while Telecom Providers are expanding most quickly.
Service Type:
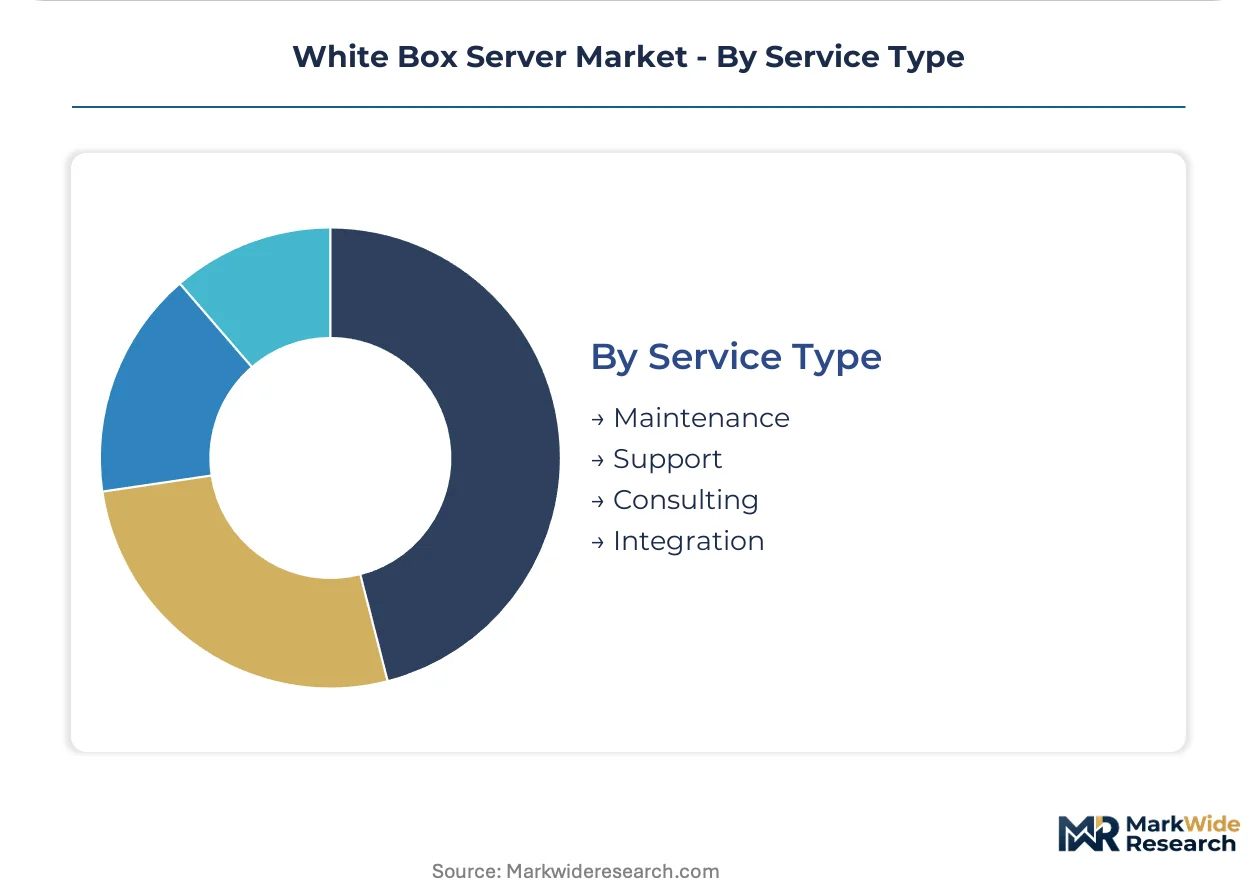
Supply concentration sits with maintenance and support contracts that ODMs are extending to capture recurring revenue from direct hardware relationships.
- Maintenance:Hardware replacement and preventive servicing agreements. Super Micro Computer anchors market position through in-house motherboard design and Silicon Valley-adjacent manufacturing capabilities that shorten repair turnaround.
- Support:Technical assistance and troubleshooting services. Quanta Computer leverages ODM scale to dominate hyperscale contracts across North America and Asia with integrated support offerings.
- Consulting:Infrastructure design and workload optimization advisory.
- Integration:System assembly, software stack deployment, and rack-level configuration services.
Maintenance commands the dominant share, while Integration is climbing the fastest as edge deployments proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The subsea cable landing stations at Virginia Beach and the Pacific Light Cable Network interconnect at Los Angeles anchor North American data center gravity. These fiber backbones concentrate hyperscaler procurement volumes where latency arbitrage meets renewable energy access.
United States
Texas and Virginia data center clusters absorb the largest share of white box server shipments as AWS, Meta, and Google operate million-square-foot facilities. The EPA Energy Star program mandates minimum efficiency thresholds that disqualify legacy power supply architectures from federal procurement. Northern Virginia's Loudoun County maintains the densest concentration of cloud infrastructure worldwide.
Germany
Frankfurt's DE-CIX internet exchange drives demand for low-latency compute infrastructure serving European financial services. The EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants accelerate liquid-cooled server deployments. Bavarian data centers near Munich are retrofitting immersion cooling systems to meet thermal density requirements.
China
Beijing-Tianjin-Hebei and Yangtze River Delta clusters scale domestic cloud infrastructure for Alibaba Cloud and Tencent. GB standards for electronic product safety add compliance layers for suppliers targeting state-owned enterprise procurement. Inner Mongolia's wind-powered facilities supply hyperscale campuses with renewable-aligned server refresh cycles.
India
Mumbai and Chennai data center markets expand under domestic data localization mandates and BIS registration requirements for local assembly. The country's PLI scheme incentivizes captive production for cloud providers establishing regional manufacturing. Telangana's Hyderabad cluster attracts Microsoft and Google facility investments with land and power subsidies.
United Kingdom
London's Docklands cable landing stations and Slough data center corridor serve financial services latency requirements. The EU CSRD carbon disclosure rules, retained in UK sustainability frameworks, favor suppliers with verified Scope 3 emissions tracking. Manchester and Leeds edge facilities distribute AI inference workloads toward northern industrial centers.
White Box Server Market Key Industry Players
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions. The supplier base concentrates around original design manufacturers with direct hyperscaler relationships, compressing traditional channel margins. Three archetypes dominate: ODM scale players with captive manufacturing, vertically integrated motherboard designers, and cost-engineered blade specialists. Competitive moves center on direct liquid cooling convergence and 48V power distribution integration.
Within the ODM tier, Quanta Computer exemplifies scale-driven contract manufacturing across North American and Asian hyperscale deployments. Super Micro Computer anchors the vertically integrated archetype through in-house motherboard design capabilities. Wistron occupies a position within cost-optimized blade and rack platforms, representing supply diversification strategies for cloud providers seeking vendor multiplicity.
| Leading Market Players |
|---|
| Quanta Computer Inc. |
| Super Micro Computer, Inc. |
| Wistron Corporation |
| Celestica Inc. |
| Inventec Corporation |
| Penguin Computing |
| Hyve Solutions |
| ZT Systems |
| Hon Hai Precision Industry Company Ltd. |
| Others |
Cost & Logistics Intelligence
ODM manufacturing scale at Quanta and Foxconn facilities compresses unit economics and establishes price floors that smaller assemblers cannot match. Texas and Virginia data center clusters concentrate procurement volumes, amplifying buyer leverage and squeezing channel margins across the server value chain.
Pricing Analysis
Certification level creates the primary spread, with CE-marked and Energy Star-validated configurations commanding premiums over uncertified alternatives. Contract-based long-term offtake dominates hyperscaler procurement, while spot purchasing persists for mid-market enterprise refreshes. Price differentiation hinges on liquid-cooling integration and titanium-rated power supply inclusion. Cost compression in air-cooled rack tiers is intensifying because NVIDIA H100 allocation constraints force buyers toward GPU-optimized configurations. Hyperscalers exhibit lowest price sensitivity due to direct ODM relationships, while regional colocation operators face acute margin pressure.
Supply Chain Analysis
Memory module inventory cycles and 12-16 week lead times for high-temperature processors constrain build schedules for AI-optimized servers. Taiwan, China, and South Korea anchor component supply, with HBM3 memory and advanced packaging capacity concentrated at SK Hynix and Samsung facilities. Raw material dependencies center on copper for cold plates, dielectric fluids for immersion systems, and rare earth elements for power supply magnetics. Single-source vulnerability sits with NVIDIA GPU allocation protocols. Distribution runs through direct ODM engagements for hyperscalers and value-added resellers for enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct ODM relationships function as a defensive moat by locking in hyperscaler procurement flows and excluding channel-dependent competitors. Switching costs escalate as liquid-cooled rack designs require customized thermal engineering and 48V power distribution integration.
For Market Incumbents: Shield market position by deepening captive manufacturing in Texas and Virginia corridors to secure proximity to AWS, Meta, and Google facilities. Accelerate certification investment for EU Ecodesign Directive compliance before the next refresh cycle locks out legacy architectures. Vertical integration into cold plate and immersion cooling component supply mitigates thermal engineer scarcity and protects margins against emerging liquid-cooling specialists. For New Entrants and Emerging Players: Anchor in India's BIS-registered assembly corridor, where PLI incentives and data localization mandates create procurement preference for locally manufactured servers. Target edge computing deployments in metropolitan AI inference facilities, where latency requirements outstrip hyperscaler supply attention and integration service premiums remain available. A direct liquid cooling convergence go-to-market angle exploits thermal density ceilings that incumbent air-cooled designs cannot address. For Investors and Strategic Acquirers: Motherboard-design-capable mid-tier ODMs with established hyperscaler relationships offer the most defensible acquisition profile for the projection horizon. Long-term viability rests on thermal engineering talent pipelines and renewable energy sourcing verification under tightening EU CSRD carbon disclosure rules. The signal to watch is NVIDIA GPU allocation expansion timelines, which determine whether AI training-optimized white box configurations achieve production scale or remain supply-constrained.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Integration | Enables 100kW+ rack densities for Microsoft and Google AI training clusters. |
| EU Ecodesign Directive Compliance | Qualifies titanium-rated power supplies for Frankfurt financial services procurement. |
| India BIS Registration Pathway | Opens captive production for cloud providers under domestic data localization mandates. |
| 48V Power Distribution Adoption | Minimizes conversion losses for hyperscaler bare-metal configurations in Texas facilities. |
| Scope 3 Emissions Verification | Satisfies EU CSRD supplier qualification criteria ahead of server refresh cycles. |
Research Approach
Desk research of hyperscaler capex disclosures, ODM financial filings, and EPA Energy Star certification databases preceded structured interviews with data center procurement directors, thermal engineering leads, and ODM account managers. Primary fieldwork captured direct ODM negotiation practices and liquid-cooling deployment timelines. Secondary validation drew from EU regulatory filings, BIS registration records, and trade data for server component flows. Bottom-up shipment estimates triangulated against top-down infrastructure investment tracking.
Variance decomposition across product type, deployment model, end user category, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level shipment trajectories and average selling price trends. Forecast inputs incorporated NVIDIA GPU allocation schedules, F-Gas Regulation phase-down timelines, and hyperscaler facility construction pipelines.
Material uncertainties — memory supply bottlenecks, tariff exposure on Chinese components, and thermal engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about direct ODM relationship stability and liquid-cooling technology maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
Philippines Data Center Physical Security Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Malaysia Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Server Operating Environments Market