
 China Data Center Cooling Market | 2026-2036
China Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Cooling Market Outlook
GB 50174 data center design certification is unwinding competitive access as operators race to meet Tier III and Tier IV uptime standards. Huawei Technologies Co. Ltd. leverages its integrated power and thermal portfolio to dominate turnkey deployments for state-backed cloud infrastructure. Vertiv Group Corp. sustains technology leadership in precision cooling through its Liebert thermal controls franchise. Hangzhou Envicool Technology Co. Ltd. anchors domestic supply chains with localized chiller production and rapid service response across eastern provinces.
China data center cooling encompasses engineered thermal management systems that maintain IT equipment within operational temperature bands, typically delivering supply air at 18-27°C while targeting power usage effectiveness below 1.3 for new hyperscale builds. Liquid cooling submerges or directly contacts server components with dielectric fluids or water-glycol mixtures, enabling heat dissipation densities above 50 kW per rack that air systems cannot match. Air cooling retains cost advantages in legacy facilities and smaller edge nodes where retrofit capital constraints limit infrastructure overhaul. Cloud service providers concentrate procurement volume as their megawatt-scale campuses drive specification standards and supplier qualification cycles.
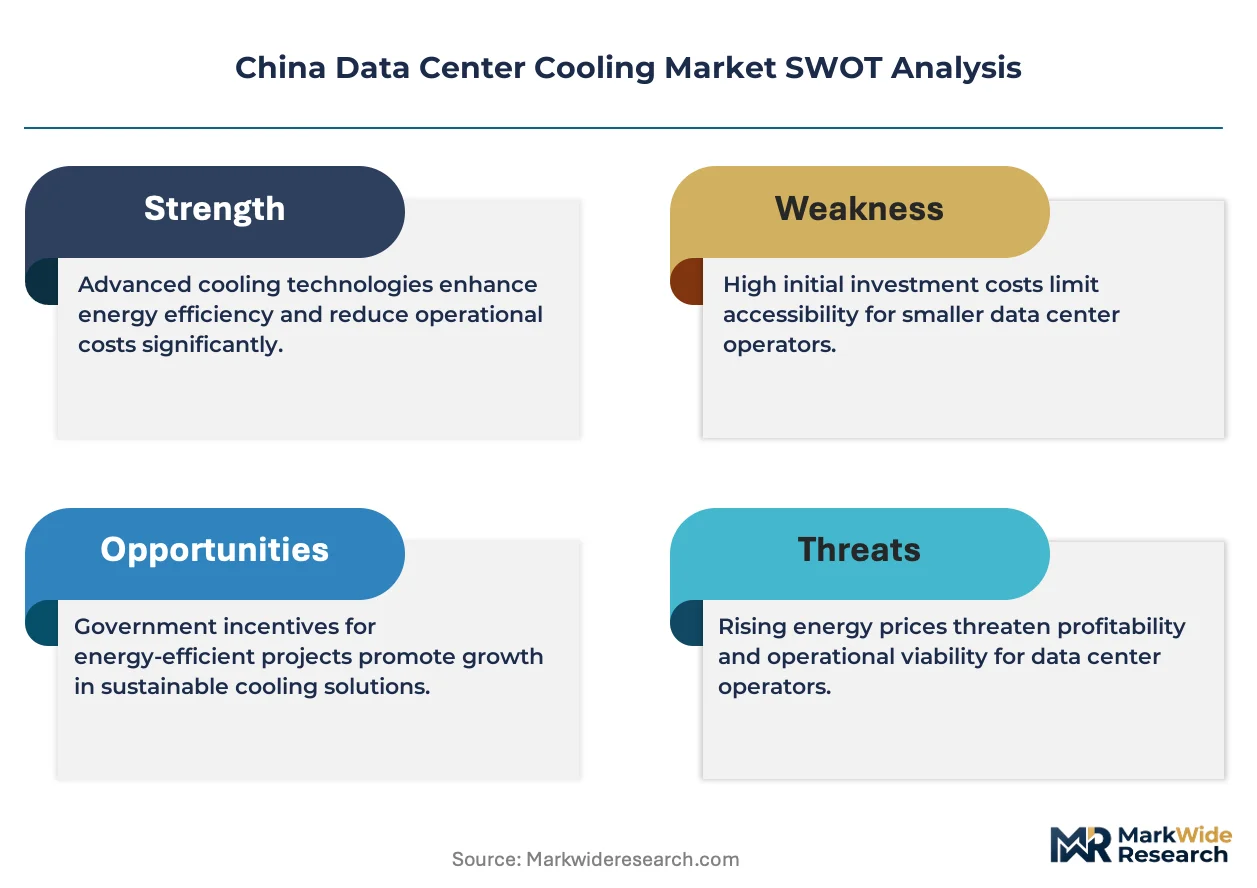
MEE enforces dual carbon intensity targets that cascade into provincial PUE ceilings, while GB standards mandate thermal redundancy and energy efficiency metrics for all new facilities. MIIT promotes green data center ratings that directly influence state-owned enterprise vendor selection and subsidy eligibility. Stakeholders must monitor how provincial carbon trading schemes reshape operating cost structures and whether liquid cooling standardization accelerates beyond hyperscale into enterprise and edge deployments.
Market Dynamics
China's dual carbon mandates from MEE are compressing PUE thresholds below 1.3 for new hyperscale facilities, forcing operators to abandon legacy air-cooled architectures before natural replacement cycles conclude. This regulatory compression is bifurcating procurement specifications between retrofit-constrained edge nodes and greenfield liquid-cooled campuses.
Growth Catalysts
- MEE Provincial PUE Ceilings:Provincial carbon intensity targets cascade into operating license conditions that disqualify air-cooled facilities above 1.5 PUE, redirecting capital toward liquid cooling retrofits and new builds.
- Hyperscale Cloud Procurement:State-backed cloud operators anchor volume specifications that upstream suppliers must qualify against, consolidating supply chains around dielectric fluid and water-glycol direct-to-chip architectures.
- Greater Bay Area Cluster Density:Shenzhen, Guangzhou, and Dongguan concentrate over half of national data center construction permits, creating localized demand gravity for cooling system deployment and service infrastructure.
Market Restraints
- Dielectric Fluid Supply Concentration:Three domestic chemical producers control fluorinated fluid formulations essential for immersion cooling, exposing operators to input cost volatility and allocation rationing during capacity expansions.
- Legacy Facility Stranded Asset Risk:GB 50174 Tier III certification requirements render pre-2020 air-cooled data centers economically unviable for state-owned enterprise tenancy, compressing residual value recovery windows.
- Technical Talent Scarcity:Liquid cooling system design and maintenance competencies remain concentrated among equipment OEMs and their authorized service networks, constraining operator insourcing options.
Strategic Opportunities
- Western Province Greenfield Development:Inner Mongolia and Guizhou offer renewable energy surpluses and cooler ambient temperatures that reduce mechanical cooling load, attracting hyperscale operators seeking PUE compliance at lower operating cost.
- MIIT Green Data Center Ratings:Subsidy eligibility and state procurement preference tied to official efficiency ratings create competitive differentiation for operators achieving advanced certification tiers.
- Edge Computing Thermal Architecture:Micro data centers and 5G base station enclosures require compact, ambient-tolerant cooling solutions that domestic chiller manufacturers are adapting from industrial process heritage.
Industry Challenges
- GB 50174 Certification Timeline Compression:Tier IV uptime documentation requires 12-18 months of continuous operational testing, delaying revenue recognition for new facilities amid tightening permit windows.
- Air-to-Liquid Retrofit Integration Complexity:Existing raised-floor facilities face structural load limits, fluid containment retrofit costs, and fire suppression system incompatibility that constrain upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Cooling Market |
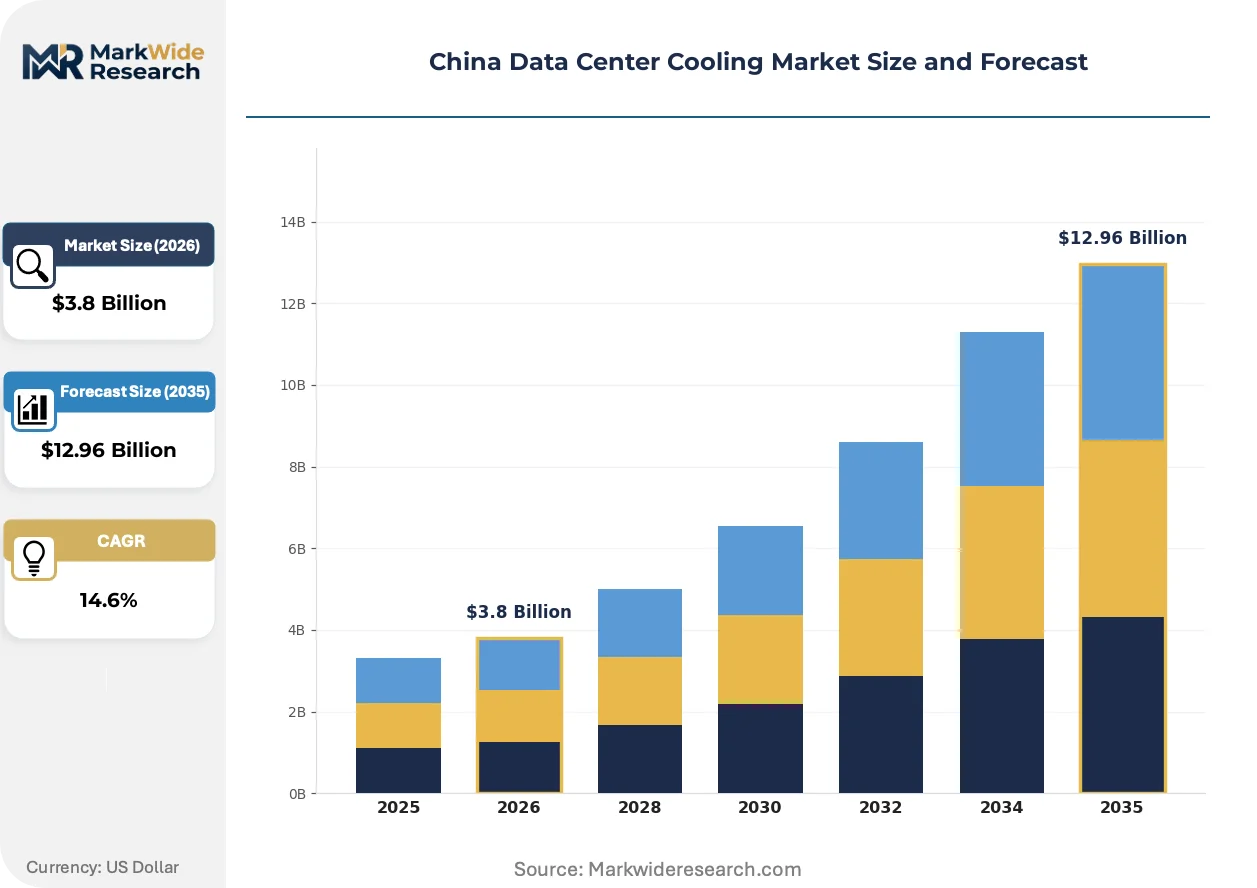
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Liquid Cooling, Air Cooling, Hybrid Cooling, Direct Expansion End User: Cloud Service Providers, Colocation Providers, Enterprises, Government Agencies Component: Chillers, CRAC Units, Cooling Towers, Air Handling Units Deployment Type: On-Premises, Off-Premises, Modular Data Centers, Edge Computing |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., Johnson Controls International plc, Huawei Technologies Co. Ltd., Carrier Global Corporation, Daikin Industries Ltd, STULZ GmbH, Hangzhou Envicool Technology Co. Ltd., GIGA-BYTE Technology Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Cooling Market Strategic Shifts
Thermal management architectures are diverging sharply between legacy air-cooled retrofits and liquid-cooled greenfield designs, with regulatory pressure compressing the transition timeline. Innovation concentrates on fluid chemistry, system modularity, and service model restructuring.
Direct-to-chip liquid cooling is bifurcating deployment patterns across the operator base. Water-glycol cold plates and dielectric fluid immersion systems dissipate heat densities exceeding 50 kW per rack that air handlers cannot address. Hyperscale cloud providers mandate liquid-cooled specifications for new procurement, while enterprise colocation operators face stranded asset risk in facilities engineered for 10-15 kW rack densities. This technology split is compressing supplier qualification cycles and fragmenting service competency requirements.
MEE enforcement of dual carbon intensity targets tightens provincial PUE ceilings annually, with non-compliant facilities facing operating license suspension. GB standards now mandate thermal redundancy documentation and real-time efficiency metering for all new construction permits. State-owned enterprise tenancy contracts require Tier III or Tier IV certification, forcing operators to front-load capital for redundant cooling loops and emergency power integration.
Specification authority is consolidating within hyperscale procurement teams that dictate supplier qualification standards and service level terms. Equipment vendors now compete through turnkey performance contracts rather than unit sales, absorbing operational risk for PUE guarantees. This model is displacing traditional distributor channels in the Greater Bay Area, where direct manufacturer deployment teams manage installation and commissioning for megawatt-scale campuses.
China Data Center Cooling Market Segmentation
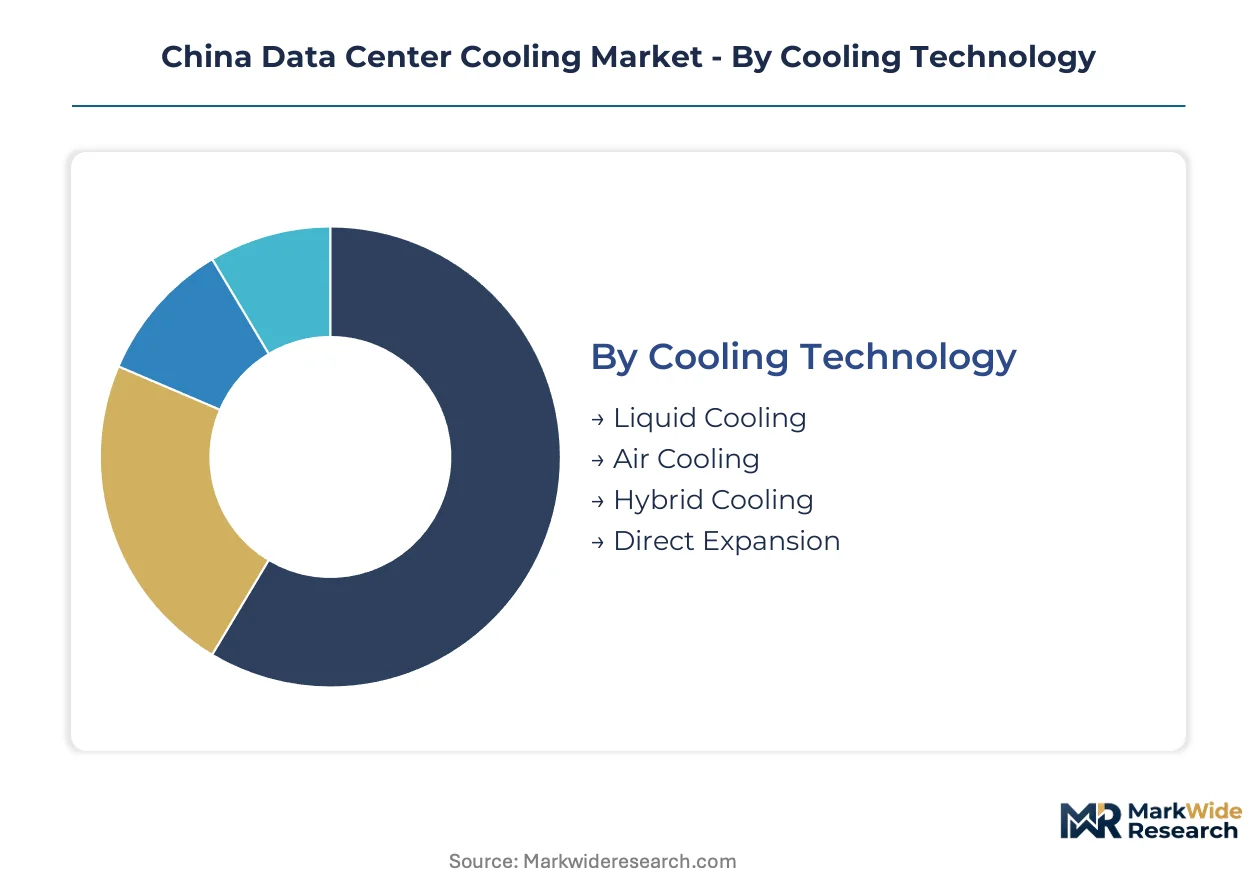
China's data center cooling market fragments across technology architectures shaped by MEE carbon mandates and procurement specifications driven by hyperscale operators. Each segmentation dimension reveals distinct competitive dynamics between legacy infrastructure and next-generation thermal systems.
Cooling Technology:
MEE provincial PUE ceilings below 1.3 bifurcate procurement between compliant liquid systems and legacy air architectures facing license risk.
- Liquid Cooling:Direct-to-chip cold plates and dielectric fluid immersion systems dissipate heat densities exceeding 50 kW per rack. Cloud service providers in the Greater Bay Area mandate liquid specifications for new megawatt-scale campuses, consolidating supplier qualification around water-glycol and fluorinated fluid formulations.
- Air Cooling:Raised-floor precision air handlers and perimeter CRAC units retain installed base dominance in pre-2020 facilities. Stranded asset risk intensifies as GB 50174 Tier III certification requirements disqualify air-cooled deployments above 1.5 PUE from state-owned enterprise tenancy contracts.
- Hybrid Cooling:Combined architectures deploy liquid loops for high-density compute zones while maintaining air distribution for storage and networking racks.
- Direct Expansion:Refrigerant-based split systems serve smaller edge nodes and retrofit-constrained facilities where chiller plant expansion proves capital-prohibitive.
Established volume favors Air Cooling; emerging adoption favors Liquid Cooling.
End User:
Procurement concentration varies sharply by capital scale and regulatory exposure across operator categories.
- Cloud Service Providers:State-backed hyperscale operators anchor national procurement volume through megawatt-scale campus developments. Their specification authority dictates supplier qualification standards and compresses deployment timelines for liquid-cooled infrastructure.
- Colocation Providers:Multi-tenant facility operators face divergent tenant demands between legacy air-cooled halls and premium liquid-cooled suites. MIIT green data center ratings determine subsidy eligibility and competitive positioning for state enterprise contracts.
- Enterprises:Private data center operators prioritize retrofit economics over PUE optimization, constraining liquid cooling penetration outside financial services and high-frequency trading verticals.
- Government Agencies:State procurement frameworks mandate Tier III or Tier IV uptime certification, directing capital toward redundant cooling architectures and thermal monitoring systems.
Procurement authority concentrates with Cloud Service Providers; facility count dominance sits with Enterprises.
Component:
Supply chain localization pressures reshape component sourcing strategies across eastern manufacturing clusters.
- Chillers:Centrifugal and screw compressor systems deliver chilled water to CRAH units and liquid cooling heat exchangers. Domestic manufacturers in Jiangsu and Zhejiang provinces capture service response advantages for hyperscale deployments in the Greater Bay Area.
- CRAC Units:Computer room air conditioners provide precision temperature and humidity control for raised-floor environments. Demand concentrates in Tier II and Tier III city edge nodes where legacy architecture retention persists.
- Cooling Towers:Evaporative heat rejection systems enable water-cooled chiller efficiency in western provinces with cooler ambient temperatures and renewable energy surpluses.
- Air Handling Units:Centralized air distribution equipment serves large-scale facilities with uniform rack density profiles and conventional hot aisle containment.
Localization momentum favors Chillers; retrofit dependency sustains CRAC Units.
Deployment Type:
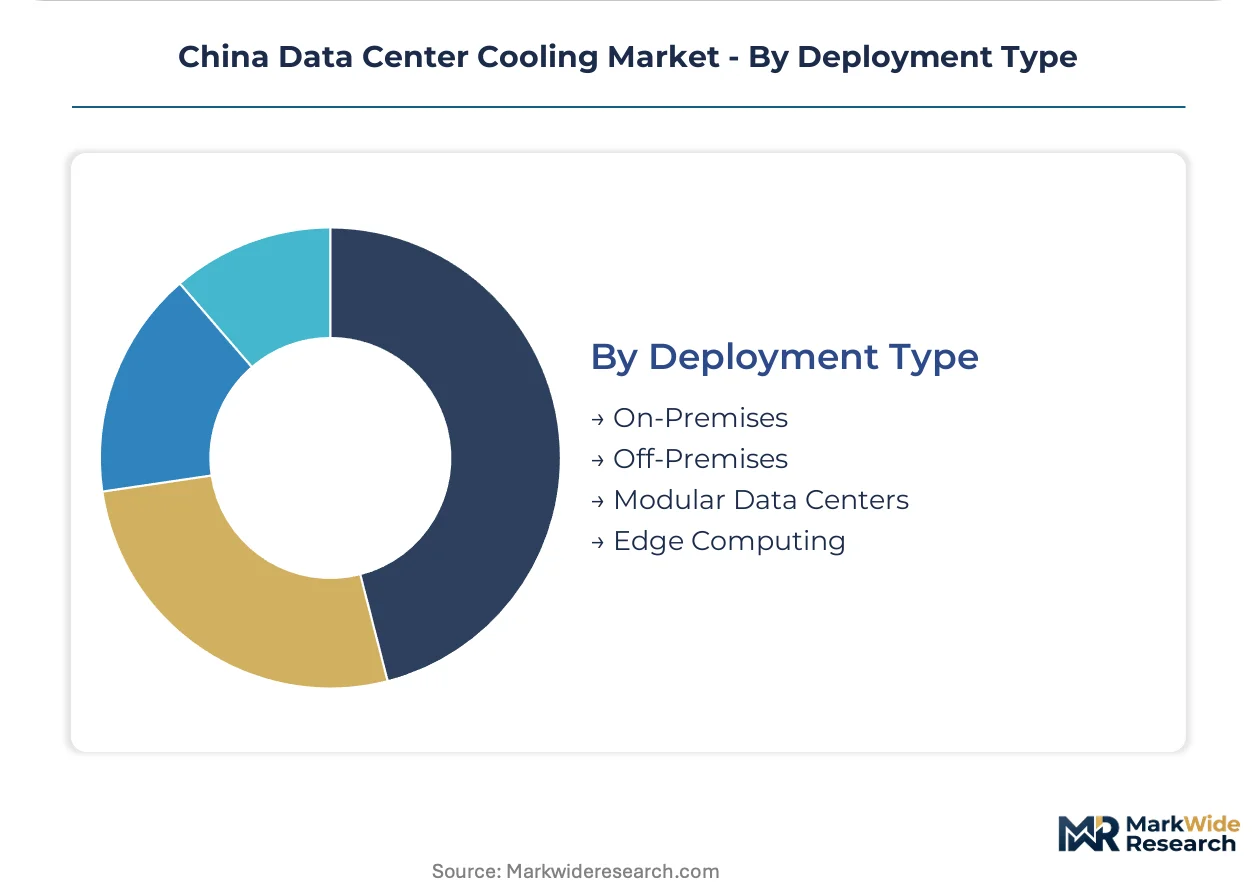
Physical infrastructure models diverge between centralized hyperscale campuses and distributed edge architectures.
- On-Premises:Enterprise-owned facilities retain operational control over thermal management but face capital constraints limiting liquid cooling adoption. GB 50174 certification requirements drive redundant cooling loop investments for new construction permits.
- Off-Premises:Colocation and cloud tenancy shifts thermal infrastructure risk to facility operators. PUE guarantee clauses in service contracts transfer operational efficiency accountability to cooling system vendors.
- Modular Data Centers:Factory-integrated enclosures with pre-engineered cooling systems accelerate deployment timelines for western province greenfield developments. Standardized thermal architectures reduce commissioning complexity in Inner Mongolia and Guizhou renewable energy zones.
- Edge Computing:Micro data centers and 5G base station enclosures demand compact, ambient-tolerant cooling solutions. Domestic manufacturers adapt industrial process chiller heritage for harsh environment reliability requirements.
Capital efficiency favors Off-Premises; latency requirements drive Edge Computing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The national ultra-high-voltage direct current transmission grid underwrites China's data center cooling demand geography, channeling renewable generation from western provinces to eastern load centers and enabling PUE-compliant facility placement far from traditional coastal clusters.
Greater Bay Area
Shenzhen, Guangzhou, and Dongguan concentrate over half of national data center construction permits issued by MIIT. MEE provincial PUE ceilings below 1.3 force liquid cooling adoption for new hyperscale campuses. Tencent and Huawei anchor megawatt-scale procurement specifications that upstream cooling suppliers must qualify against.
Beijing-Tianjin-Hebei
State-backed cloud operators drive thermal infrastructure investment in this northern corridor. GB 50174 Tier III certification requirements disqualify legacy air-cooled facilities from government tenancy contracts. Zhangjiakou's renewable energy surplus attracts hyperscale operators seeking carbon compliance without western province latency penalties.
Yangtze River Delta
Shanghai's financial services verticals sustain demand for low-latency colocation with redundant cooling architectures. MIIT green data center ratings determine subsidy eligibility for facilities in Jiangsu and Zhejiang provinces. Hangzhou Envicool anchors domestic chiller supply chains with rapid service response across eastern manufacturing clusters.
Western Provinces
Inner Mongolia and Guizhou offer cooler ambient temperatures that reduce mechanical cooling load for hyperscale campuses. Provincial carbon trading schemes reshape operating cost structures for operators locating near renewable generation assets. Modular data center deployments accelerate in these regions to bypass eastern land scarcity constraints.
Sichuan-Chongqing
Hydropower surpluses during wet seasons attract seasonal data center migration from coal-dependent eastern grids. Chongqing's rising status as a western logistics hub supports edge computing node deployment with compact cooling requirements. Local governments compete through tax incentives for thermal infrastructure investment.
China Data Center Cooling Market Competitive Environment
Listed leaders compete with private specialists across technology integration depth, with publicly traded multinationals facing off against domestic unlisted champions in turnkey deployment contests. Market structure bifurcates between consolidated hyperscale procurement channels and fragmented edge node supply chains. Three archetypes dominate: integrated infrastructure conglomerates, precision cooling specialists, and localized service providers. Competitive moves concentrate on vertical integration into power distribution and thermal management bundles, plus geographic expansion through western province greenfield partnerships.
Within the integrated infrastructure tier, Huawei Technologies Co. Ltd. and Vertiv Group Corp. occupy positions defined by turnkey performance contracting models. Hangzhou Envicool Technology Co. Ltd. exemplifies the localized service archetype, anchoring domestic supply chains with rapid response capabilities across eastern provinces. These three entities represent the competitive spectrum from state-backed scale to regional agility.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| Johnson Controls International plc |
| Huawei Technologies Co. Ltd. |
| Carrier Global Corporation |
| Daikin Industries Ltd |
| STULZ GmbH |
| Hangzhou Envicool Technology Co. Ltd. |
| GIGA-BYTE Technology Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term performance contracts with PUE guarantees lock in hyperscale procurement volume while anchoring price visibility for cooling system vendors across the Greater Bay Area. These arrangements transfer operational risk from cloud operators to equipment suppliers, compressing margin buffers for participants unable to meet MEE carbon intensity thresholds.
Pricing Analysis
Three-tier pricing structure across premium liquid-cooled, standard hybrid, and economy air-cooled configurations separates procurement tiers by certification grade and volume scale. Price differentiation centers on GB 50174 Tier IV uptime documentation and after-sales service bundling, with hyperscale buyers commanding steepest discounts. Pricing pressure stems from dielectric fluid supply concentration among three domestic chemical producers. Enterprise colocation operators exhibit highest price sensitivity due to retrofit capital constraints, while state-backed cloud providers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of fluorinated fluids and water-glycol formulations dominates inventory strategy as operators buffer against allocation rationing during hyperscale capacity expansions. Manufacturing concentrates in Jiangsu and Zhejiang provinces for chillers, with dielectric fluid production anchored in domestic chemical clusters. Raw material dependencies span rare earth heat transfer additives, precision-machined cold plates, and semiconductor-grade fluid formulations. Single-source vulnerability runs through fluorinated fluid supply chains. Distribution runs through direct manufacturer deployment teams that displace traditional distributor channels for megawatt-scale campus projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics around liquid cooling standardization are reshaping vendor interoperability, with MIIT green data center ratings functioning as the coordination mechanism that locks in ecosystem winners.
For Market Incumbents: Consolidate service network density in the Greater Bay Area to defend against modular data center manufacturers expanding from western provinces. Capture backward integration into power distribution equipment to bundle thermal and electrical infrastructure under single performance contracts. MEE provincial PUE ceiling enforcement compresses qualification windows for new suppliers. For New Entrants and Emerging Players: Differentiate on rapid commissioning capabilities for edge computing nodes in Chongqing and Sichuan, where 5G base station enclosures demand compact ambient-tolerant cooling. Target western province greenfield developments in Inner Mongolia and Guizhou as the most penetrable geography, given land scarcity constraints in eastern clusters. Pursue MIIT green data center certification as the primary go-to-market credential for state enterprise procurement eligibility. For Investors and Strategic Acquirers: Capital is best deployed toward domestic chiller manufacturers with established service response networks across eastern provinces, given the long-term viability of localized supply chains under carbon trading scheme expansion. Monitor provincial carbon trading scheme liquidity as the signal to watch for operating cost structure inflection that would reshape facility location economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Distribution | Huawei and Vertiv bundle electrical and thermal infrastructure under unified performance guarantees. |
| Western Province Greenfield Partnership | Inner Mongolia and Guizhou renewable zones attract hyperscale operators seeking PUE compliance. |
| MIIT Green Data Center Certification | Official efficiency ratings determine subsidy eligibility and state procurement preference. |
| Dielectric Fluid Supply Agreement | Long-term offtake contracts with domestic chemical producers buffer against allocation rationing. |
| Direct Deployment Team Expansion | Manufacturer-controlled installation displaces distributor channels in megawatt-scale campus projects. |
Study Parameters
A standing panel of data center facility directors, thermal infrastructure procurement managers, MIIT certification auditors, and cloud operator engineering leads provided ongoing calibration against operational realities. Primary interviews combined with secondary validation from GB standards documentation, MIIT green data center rating disclosures, provincial carbon trading scheme filings, and hyperscaler capex announcements. Bottom-up installation tracking and top-down market sizing triangulated volume estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon, with analytical frameworks modeling cooling technology architecture, end-user procurement authority, component supply chain localization, and deployment type physical infrastructure. CAGRs derived from segmented growth trajectory analysis incorporating MEE regulatory enforcement timelines, hyperscale campus construction permits, and dielectric fluid production capacity expansion.
The analysis sits within stated boundaries; outcomes outside sustained MEE PUE ceiling enforcement or dielectric fluid supply expansion would require recalibration. Forecasts reflect assumptions regarding provincial carbon trading scheme implementation and GB 50174 certification timeline adherence. Revision becomes warranted when liquid cooling standardization adoption crosses hyperscale boundaries into enterprise and edge deployments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market