
 Global Software Defined Infrastructure (SDI) Market | 2026-2036
Global Software Defined Infrastructure (SDI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Software Defined Infrastructure (SDI) Market Foresight
Enterprise-grade SDI certification is bifurcating the competitive landscape into validated and non-validated supplier tiers. VMware sustains technology leadership through its vSphere virtualization stack and deep channel partnerships. Cisco Systems dominates network virtualization with its Application Centric Infrastructure platform and extensive enterprise relationships. Hewlett Packard Enterprise navigates the hardware-software boundary with its composable infrastructure offerings and GreenLake as-a-service model.
Software Defined Infrastructure refers to IT infrastructure where compute, storage, and networking resources are abstracted from physical hardware and managed through software controllers, typically using APIs and policy-driven automation to enable dynamic resource allocation across heterogeneous environments. Its primary purpose is to replace static, manually configured data centers with programmable, elastic systems that respond to workload demands in real time. Hybrid cloud deployment now captures the dominant share of enterprise spending as organizations seek to balance sovereignty requirements with scalability. Network virtualization represents the fastest-expanding solution type as 5G rollouts and edge computing architectures demand programmable connectivity. Orchestration software commands the highest margin pool due to vendor stickiness and the complexity of multi-vendor integration.
The U.S. Federal Risk and Authorization Management Program shapes demand by mandating standardized security assessments for cloud products sold to government agencies. The EU Cybersecurity Act and NIS2 Directive are forcing European infrastructure operators toward certified, auditable software-defined systems. China's GB standards for cloud computing and data security impose localization requirements on foreign SDI vendors operating in that market. Stakeholders must monitor how divergent sovereignty frameworks fragment procurement standards across major economies.
Market Dynamics
The SDI market is being fundamentally restructured by the collision between hyperscale cloud buildouts and sovereignty mandates that fragment procurement standards across major economies. This tension forces infrastructure buyers to architect for portability while satisfying divergent compliance regimes.
Growth Catalysts
- Hyperscale cloud expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are deploying software-defined architectures across multi-region footprints, creating pull-through demand for orchestration and network virtualization layers.
- Federal modernization mandates:The U.S. Federal Risk and Authorization Management Program requires standardized security assessments, accelerating FedRAMP-authorized SDI procurement across civilian and defense agencies.
- EU AI Act compliance pressure:European enterprises are retrofitting infrastructure to satisfy auditability and data governance requirements, driving replacement cycles for non-compliant legacy systems.
Market Restraints
- Semiconductor supply concentration:Advanced networking silicon from TSMC and Samsung foundries faces allocation constraints, extending lead times for high-performance SDI hardware.
- Specialized talent scarcity:Kubernetes, Terraform, and infrastructure-as-code expertise commands premium compensation, inflating implementation costs for mid-market adopters.
- China GB standard localization:Mandatory data residency and security certification requirements create operational friction for foreign SDI vendors seeking market access.
Strategic Opportunities
- Edge computing architectures:5G network rollouts and industrial IoT deployments in Germany, Japan, and South Korea are creating demand for distributed, software-defined edge infrastructure.
- Composable infrastructure convergence:The integration of software-defined storage with disaggregated compute pools enables dynamic resource pooling for high-frequency trading platforms.
- India PLI scheme incentives:Production-linked incentives for electronics manufacturing are attracting hyperscale data center investments that embed SDI as foundational architecture.
Industry Challenges
- Multi-vendor integration complexity:Enterprises struggle to harmonize VMware, Cisco ACI, and open-source orchestration layers into unified policy domains.
- Certification timeline compression:FedRAMP, ISO 27001, and SOC 2 audits require 12-18 month cycles that delay revenue recognition for new SDI deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Software Defined Infrastructure (SDI) Market |
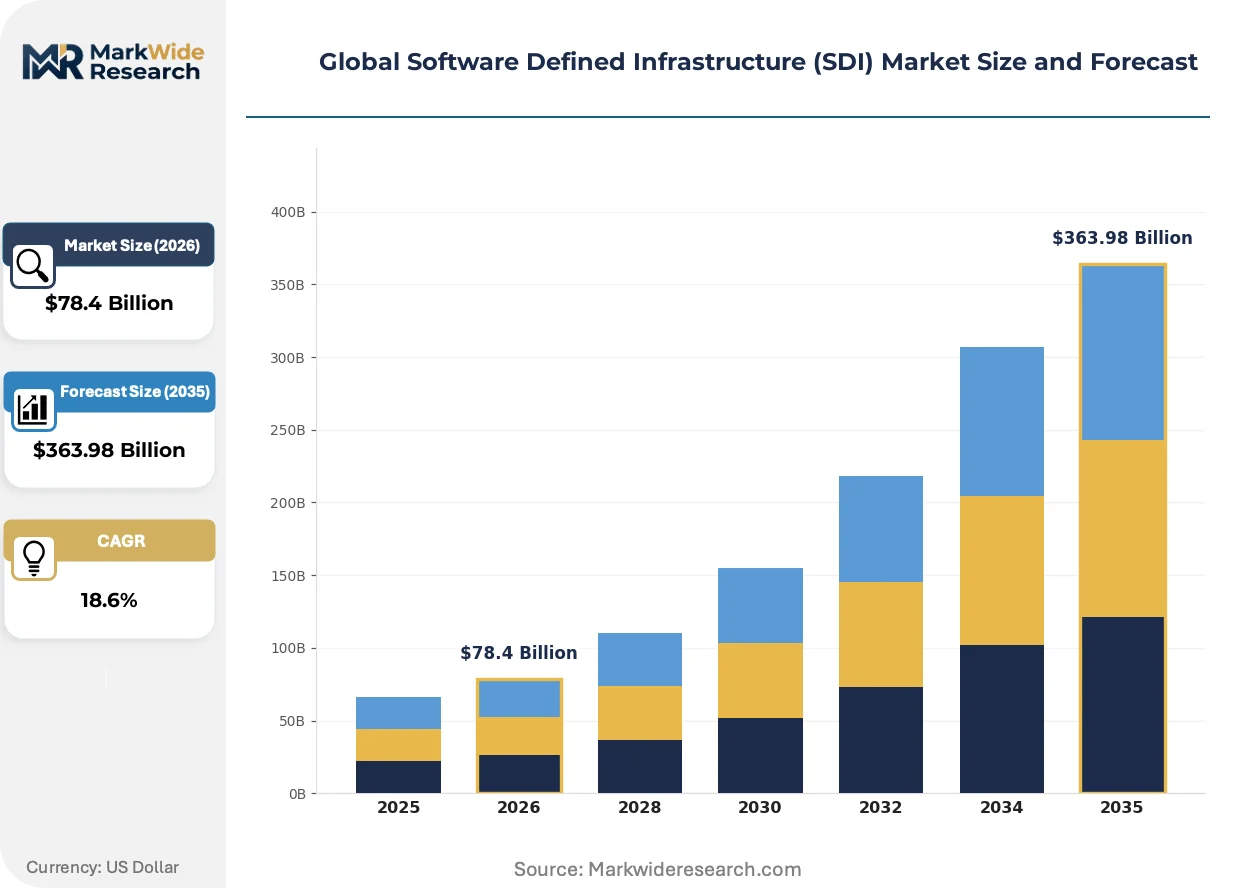
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $363.98 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises Solution Type: Compute Virtualization, Network Virtualization, Storage Virtualization, Orchestration Software Use Case: Data Center Automation, Disaster Recovery, Application Optimization, Multi-Cloud Management End User Industry: Telecommunications, Government Agencies, Financial Services, Educational Institutions, Technology Providers |
| Companies Covered | VMware, Cisco Systems, Microsoft, Dell Technologies, Hewlett Packard Enterprise, IBM, Oracle, Nutanix, Red Hat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Software Defined Infrastructure (SDI) Market Shifts & Advancements
Container-native infrastructure is displacing virtual-machine-centric architectures as the default abstraction layer, compressing deployment cycles and redefining vendor competitive moats.
SmartNIC technology is miniaturizing network function virtualization directly onto server motherboards. Financial services firms in London and Singapore are deploying these offloads for sub-microsecond latency trading. This compression is eliminating standalone network appliance categories and shifting margin pools to semiconductor-integrated solutions.
The EU Cybersecurity Act and NIS2 Directive are mandating certified, auditable software-defined systems for critical infrastructure operators. European energy and transport utilities must now document supply chain provenance and vulnerability management in their SDI procurement. German and French system integrators are building compliance-as-a-service wrappers around standard orchestration platforms.
Consumption-based infrastructure procurement is displacing perpetual licensing in enterprise data center refresh cycles. Hewlett Packard Enterprise's GreenLake and Dell Apex models are capturing Fortune 500 workloads previously reserved for capital purchases. This shift is most visible in U.S. healthcare and federal sectors where operating-expense treatment aligns with budget constraints.
Global Software Defined Infrastructure (SDI) Market Segmentation
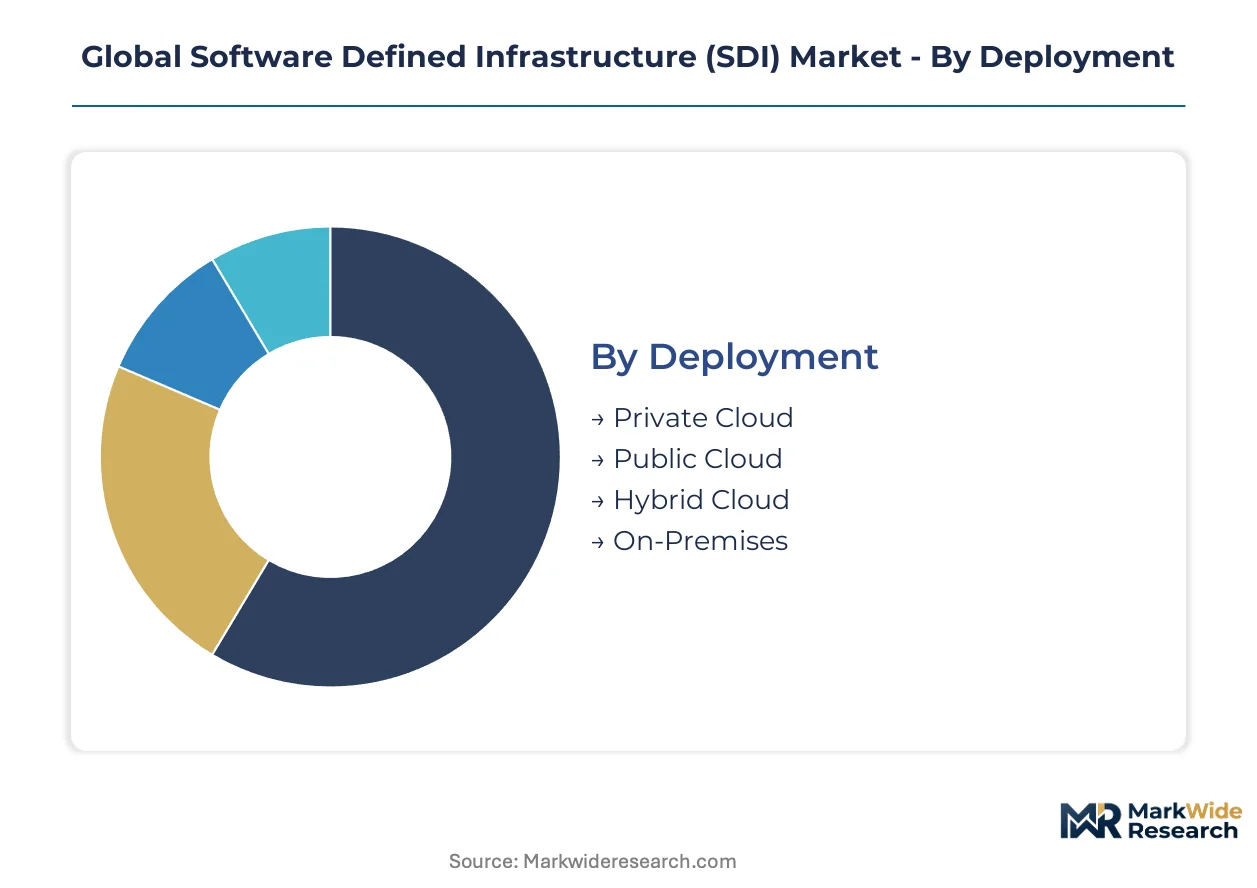
SDI procurement patterns diverge sharply across deployment models and solution types, with regulatory frameworks in the United States, Germany, and China forcing distinct certification requirements that reshape vendor selection criteria.
Deployment:
FedRAMP authorization in the United States, EU Cybersecurity Act certification, and China's GB standards create divergent compliance pathways that fragment procurement decisions across multinational enterprises.
- Hybrid Cloud:Combines on-premises control with public cloud elasticity through unified orchestration layers. Financial services firms in New York and London deploy hybrid configurations to satisfy data sovereignty mandates while accessing burst capacity for trading analytics workloads.
- Private Cloud:Delivers dedicated infrastructure with tenant-isolated resource pools managed through proprietary software controllers. German automotive manufacturers and Japanese pharmaceutical companies favor private deployments to satisfy ISO 27001 and local data residency requirements.
- Public Cloud:Shared multi-tenant infrastructure operated by hyperscale providers with API-driven resource provisioning.
- On-Premises:Fully captive data center assets with software-defined abstraction layers installed over owned hardware.
Hybrid Cloud handles the majority of throughput; Private Cloud is expanding most quickly among regulated industries.
Solution Type:
Margin concentration follows orchestration software due to integration complexity, while hardware-adjacent virtualization layers compete on price.
- Orchestration Software:Policy engines and automation frameworks that coordinate multi-vendor infrastructure through declarative APIs. Kubernetes-based platforms from Rancher Labs and Red Hat OpenShift dominate enterprise evaluations in Singapore and Sydney financial districts.
- Network Virtualization:Decouples control plane from physical switching hardware to enable programmable traffic management. 5G core network buildouts by Deutsche Telekom and NTT Docomo are accelerating segment expansion across European and Asian telecom infrastructure.
- Compute Virtualization:Hypervisor-based abstraction of server resources enabling workload portability across hardware generations.
- Storage Virtualization:Software-defined pooling of heterogeneous storage media through unified namespace presentation.
Orchestration Software commands the highest margin pool; Network Virtualization is climbing the fastest on share.
Use Case:
Operational maturity determines adoption sequencing, with automation-first deployments preceding complex multi-cloud governance implementations.
- Data Center Automation:Eliminates manual provisioning through infrastructure-as-code pipelines and self-service portals. U.S. federal agencies under Cloud Smart mandates and NHS Trusts in England are standardizing on automated provisioning to compress deployment cycles.
- Multi-Cloud Management:Unified governance across AWS, Azure, and GCP environments with cost optimization and compliance monitoring. Australian mining conglomerates and Canadian energy utilities deploy these tools to prevent vendor lock-in while maintaining centralized policy enforcement.
- Disaster Recovery:Software-defined replication and failover orchestration for business continuity objectives.
- Application Optimization:Dynamic resource allocation tuned to workload performance requirements.
Data Center Automation handles the majority of throughput; Multi-Cloud Management is gaining share fastest.
End User Industry:
Security clearance requirements and transaction latency tolerances create distinct procurement patterns across verticals.
- Financial Services:Real-time trading infrastructure and regulatory reporting systems demanding sub-millisecond latency. Investment banks in London's Square Mile and Singapore's Marina Bay district deploy composable infrastructure for high-frequency trading platforms.
- Government Agencies:Classified and unclassified workloads subject to national security frameworks. U.S. Department of Defense JWCC contracts and UK Government Digital Service standards mandate FedRAMP and NCSC-certified SDI architectures.
- Telecommunications:5G core and edge virtualization for network function disaggregation.
- Technology Providers:Cloud-native SaaS platforms built on software-defined foundations.
- Educational Institutions:Research computing and campus IT modernization through software-defined consolidation.
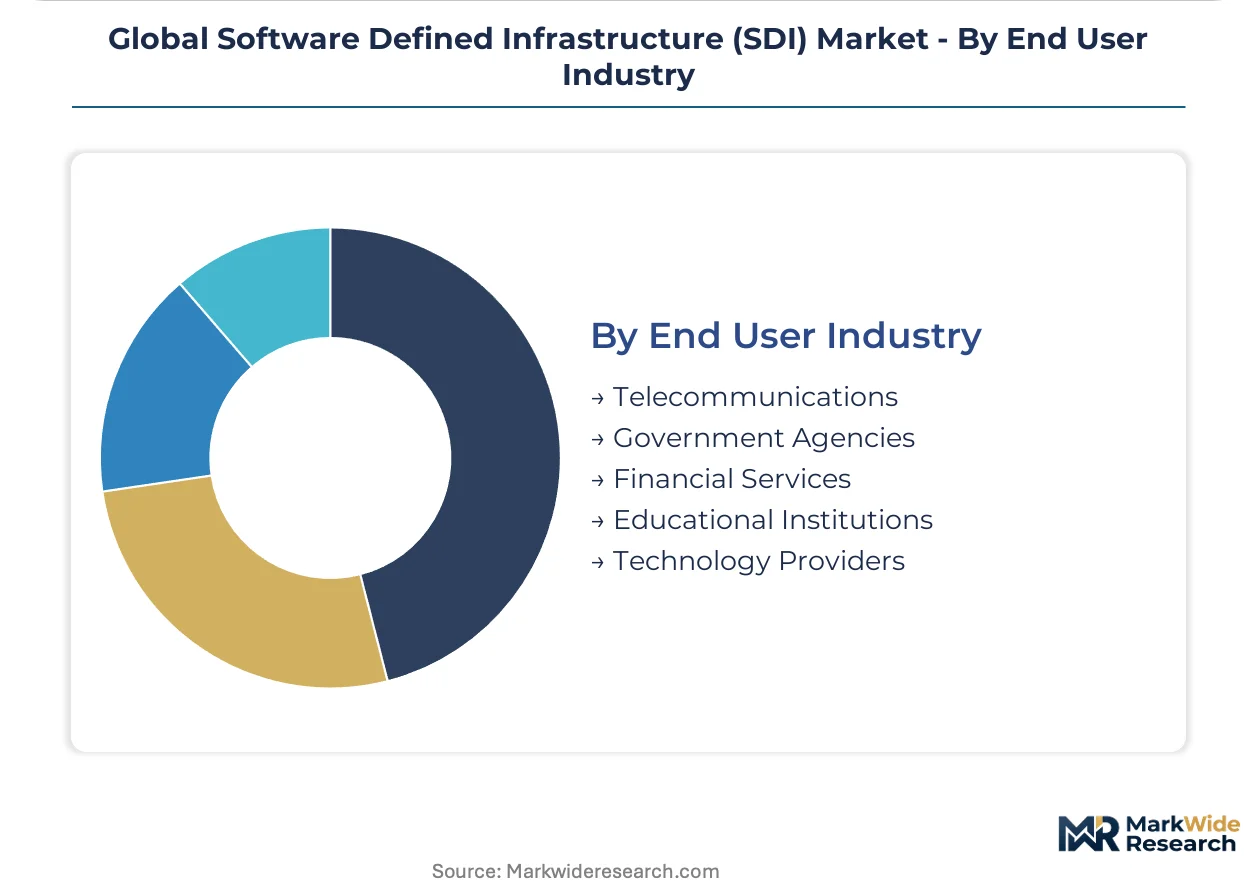
Financial Services handles the majority of throughput; Government Agencies is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced networking silicon from TSMC and Samsung foundries concentrates supply-side capacity in East Asian manufacturing clusters. This concentration creates allocation constraints that extend lead times for high-performance SDI hardware across all major demand centers. Procurement patterns fragment as divergent sovereignty frameworks reshape certification requirements.
United States
Hyperscale cloud buildouts by Amazon Web Services and Microsoft Azure drive demand for orchestration layers. The Federal Risk and Authorization Management Program mandates FedRAMP certification for government procurement. Silicon Valley and Northern Virginia data center clusters absorb the majority of domestic SDI deployment.
Germany
Automotive manufacturers and industrial conglomerates require ISO 27001-compliant private cloud infrastructure. The EU Cybersecurity Act and NIS2 Directive mandate certified, auditable software-defined systems for critical infrastructure operators. Munich and Stuttgart industrial corridors host concentrated deployment of composable infrastructure for manufacturing workloads.
China
Domestic cloud providers expand software-defined architectures under GB standards for cloud computing and data security. Mandatory data residency and security certification requirements create operational friction for foreign vendors. Beijing and Shanghai metropolitan clusters lead localization of SDI supply chains.
Japan
NTT Docomo and KDDI deploy network virtualization for 5G core buildouts. METI industrial policy encourages software-defined manufacturing infrastructure under Society 5.0 initiatives. Tokyo and Osaka financial districts demand sub-microsecond latency trading infrastructure.
India
Production-linked incentives for electronics manufacturing attract hyperscale data center investments embedding SDI architecture. RBI guidelines on data localization push financial institutions toward compliant software-defined storage. Mumbai and Bengaluru technology corridors concentrate enterprise adoption.
Global Software Defined Infrastructure (SDI) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the SDI market. The vendor base separates into three distinct tiers: hyperscale cloud providers with integrated stacks, legacy hardware vendors transitioning to software-centric models, and pure-play orchestration specialists. Strategic moves concentrate on M&A for Kubernetes expertise and capacity expansion through as-a-service consumption models.
Within the legacy hardware transition tier, VMware and Cisco Systems exemplify vendors navigating the software-hardware boundary. Hewlett Packard Enterprise occupies a position representing composable infrastructure convergence. These three anchors demonstrate how established technology vendors reposition around software-defined abstraction layers rather than physical equipment sales.
| Leading Market Players |
|---|
| VMware |
| Cisco Systems |
| Microsoft |
| Dell Technologies |
| Hewlett Packard Enterprise |
| IBM |
| Oracle |
| Nutanix |
| Red Hat |
| Others |
Supply & Pricing Matrix
SmartNIC substitution for discrete network appliances is redrawing procurement geography toward semiconductor-integrated solutions while compressing hardware margins and elevating orchestration software premiums across enterprise data centers.
Pricing Analysis
FedRAMP authorization dictates the pricing tier structure across the U.S. federal procurement channel, separating validated suppliers from uncertified competitors. Three-tier pricing stratifies across premium FedRAMP High, standard FedRAMP Moderate, and economy self-attested levels. Cost compression in hardware virtualization layers is intensifying because SmartNIC integration eliminates standalone appliance categories. Mid-market adopters exhibit highest price sensitivity due to Kubernetes talent scarcity inflating total cost of ownership.
Supply Chain Analysis
TSMC and Samsung foundry capacity in Taiwan and South Korea constitutes the critical chokepoint for advanced networking silicon deployment. SDI hardware draws from 5nm/7nm networking chips, high-bandwidth memory modules, and programmable FPGA substrates. Single-source vulnerability concentrates in East Asian semiconductor fabrication. Distribution runs through direct OEM relationships with hyperscale cloud providers and certified systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined infrastructure operates as a defensive-moat market where regulatory certification entrenchment creates switching costs that lock enterprise buyers into validated supplier ecosystems for multi-year refresh cycles.
For Market Incumbents: Compound certification investments across FedRAMP, EU Cybersecurity Act, and China's GB standards to widen the compliance gap with emerging competitors. Deepen channel control through systems integrator exclusivity arrangements in Germany and Japan. Kubernetes-native orchestration expertise represents the critical capability scarcity threatening hardware-centric vendors. For New Entrants and Emerging Players: FedRAMP Fast Track authorization offers the most penetrable entry vector into the U.S. federal segment previously reserved for established suppliers. Target Indian financial institutions under RBI data localization mandates where compliance-native architectures outcompete retrofit incumbents. Lead with consumption-based pricing models aligned to GreenLake and Apex procurement patterns in healthcare and federal sectors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed orchestration specialists holding Kubernetes distribution partnerships but lacking hardware-software convergence capabilities. Five-to-ten year viability hinges on multi-cloud governance platform consolidation. Monitor hyperscaler capex disclosure inflections as demand signal for underlying SDI component suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks U.S. Department of Defense JWCC contract eligibility and civilian agency procurement pipelines. |
| SmartNIC Platform Integration | Captures sub-microsecond latency trading workloads in London and Singapore financial districts. |
| EU Cybersecurity Act Certification | Mandates auditable supply chain provenance for German energy and French transport infrastructure operators. |
| Kubernetes Distribution Partnership | Secures channel access to Rancher Labs and Red Hat OpenShift enterprise evaluations in Asia-Pacific. |
| Consumption Model Transition | Aligns with HPE GreenLake and Dell Apex procurement shifts in U.S. healthcare and federal sectors. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs, IT procurement officers, platform engineers, and channel partners and refined through secondary validation against SEC filings, hyperscaler capex disclosures, App Annie infrastructure spend data, and FedRAMP authorization databases. Bottom-up deployment sizing across hybrid cloud, private cloud, and on-premises configurations triangulated with top-down vendor revenue attribution.
Variance decomposition across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro infrastructure spend indicators. Forecast inputs incorporated 5G core network buildout timelines and sovereign cloud localization mandates.
Decision-makers should treat outputs as directional under sustained hyperscale expansion and regulatory fragmentation assumptions; material deviation in semiconductor supply availability would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and China GB standard implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Spain Data Center Rack Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Bengaluru Data Center Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Paris Data Center Market