
 Ireland Data Center Market | 2026-2036
Ireland Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Data Center Market Outlook
Ireland's renewable energy planning conditions is rebalancing where developers secure land and power. Google leverages its long-term power purchase agreements with Irish wind farms to sustain expansion at its Dublin-adjacent facilities. Microsoft anchors its European cloud infrastructure with deep investments in hyperscale campuses west of the capital. Amazon Web Services competes through aggressive land banking in counties with available grid capacity and planning flexibility.
Data centers are mission-critical facilities housing servers, storage systems, and networking infrastructure within controlled environments maintaining temperatures between 18°C and 27°C and relative humidity at 40–60%. These facilities process, store, and distribute digital information for enterprises, governments, and consumers. Colocation operators dominate the installed base in Ireland, while hyperscale builds capture the majority of new capital deployment as cloud providers seek owned capacity. Edge computing remains nascent but positions for latency-sensitive workloads in financial services and autonomous systems.
The Commission for Regulation of Utilities enforces grid connection standards that require data centers to demonstrate firm demand response capability or on-site generation. Ireland's Environmental Protection Agency implements emissions licensing that shapes cooling technology selection and refrigerant choices. BSI standards for energy management and ISO 27001 for information security govern operational certification. Stakeholders must monitor planning appeals, grid constraint maps, and corporate renewable energy procurement trajectories to anticipate where permitted capacity will materialize.
Market Dynamics
An Bord Pleanála's renewable energy planning conditions are forcing data center developers to relocate from the Greater Dublin Area to western counties with wind farm access. This spatial reconfiguration is redistributing capital deployment across Ireland's regional grid infrastructure.
Growth Catalysts
- Hyperscale Cloud Expansion:Global cloud providers are securing multi-hundred-megawatt land positions in County Kildare and Cork to anchor European infrastructure capacity.
- Wind Energy Integration:Developers with long-term power purchase agreements from Irish wind farms satisfy An Bord Pleanála's grid stability and carbon intensity requirements for planning approval.
- Latency-Sensitive Financial Workloads:Dublin's proximity to London and Frankfurt makes Irish facilities attractive for high-frequency trading and real-time risk processing applications.
Market Restraints
- Grid Connection Queues:The Commission for Regulation of Utilities maintains firm demand response requirements that extend connection timelines for facilities without on-site generation or battery storage.
- Land Scarcity in Eastern Corridor:Available sites with adequate transmission capacity within 50 kilometers of Dublin have been largely absorbed by earlier entrants.
- Refrigerant Phase-Down:Ireland's implementation of the EU F-Gas Regulation restricts high-GWP cooling agents, forcing capital-intensive chiller replacements or alternative thermal architecture investments.
Strategic Opportunities
- Western Corridor Development:Counties Galway and Mayo offer untapped grid capacity from onshore wind integration, attracting developers with lower land costs and streamlined county council planning processes.
- Liquid Cooling Convergence:Direct-to-chip and immersion cooling technologies enable higher rack densities for artificial intelligence training clusters, differentiating Irish facilities against air-cooled continental alternatives.
- Corporate Renewable Procurement:Ireland's streamlined renewable energy guarantee of origin framework allows colocation tenants to claim verified carbon-free electricity matching for ESG reporting.
Industry Challenges
- Specialized Electrical Trades Shortage:Medium-voltage switchgear commissioning and high-voltage cable termination skills are concentrated among a small contractor base, extending construction schedules.
- ISO 27001 Certification Burden:Financial services tenants require current information security management certification, creating compliance overhead for smaller colocation operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Data Center Market |
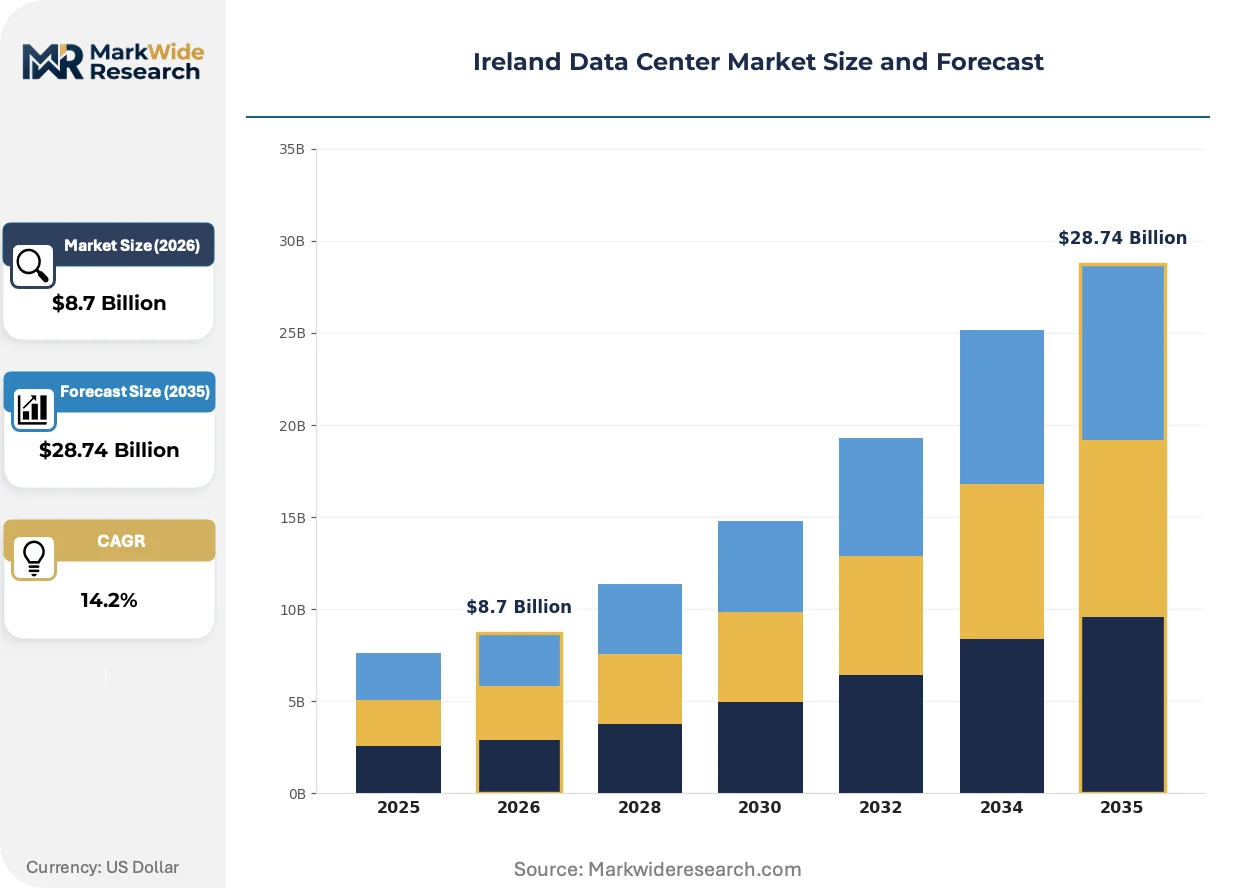
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Hyperscale, Edge Computing, Managed Hosting Technology: Cooling Solutions, Power Distribution, Networking Equipment, Security Systems End User: Telecommunications, IT Services, Financial Services, Cloud Providers Installation: On-premises, Remote, Hybrid, Modular |
| Companies Covered | Google, K2 Data Centres, Digital Realty, Vantage Data Centers, Echelon Data Centres, Equinix, Microsoft, BT Communications Limited, Amazon Web Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Data Center Market Strategic Shifts
Cooling technology selection is becoming the primary competitive differentiator as rack densities climb past 30 kilowatts per unit. Irish operators are racing to deploy thermal architectures that satisfy both EPA emissions licensing and hyperscale reliability requirements.
Immersion cooling using synthetic dielectric fluids is overtaking traditional raised-floor air handling for artificial intelligence training deployments. Hyperscale operators with dedicated Dublin-adjacent campuses are retrofitting white space for tank-based systems. This transition is compressing mechanical infrastructure footprints and enabling 50% higher compute density per square meter.
An Bord Pleanála's updated planning guidelines require demonstrable grid stability contributions from new data center projects. Developers must now incorporate battery storage or synchronous condensers to receive development consent in the Greater Dublin Area. Facilities without firm demand response capability are redirecting toward western counties with available transmission headroom.
Enterprise procurement of colocation services now prioritizes verified renewable energy matching over traditional location and connectivity metrics. Financial services buyers in Dublin require granular carbon accounting tied to hourly generation data. This behavioral shift is elevating operators with direct wind farm power purchase agreements above competitors relying on grid-average green tariffs.
Ireland Data Center Market Segmentation
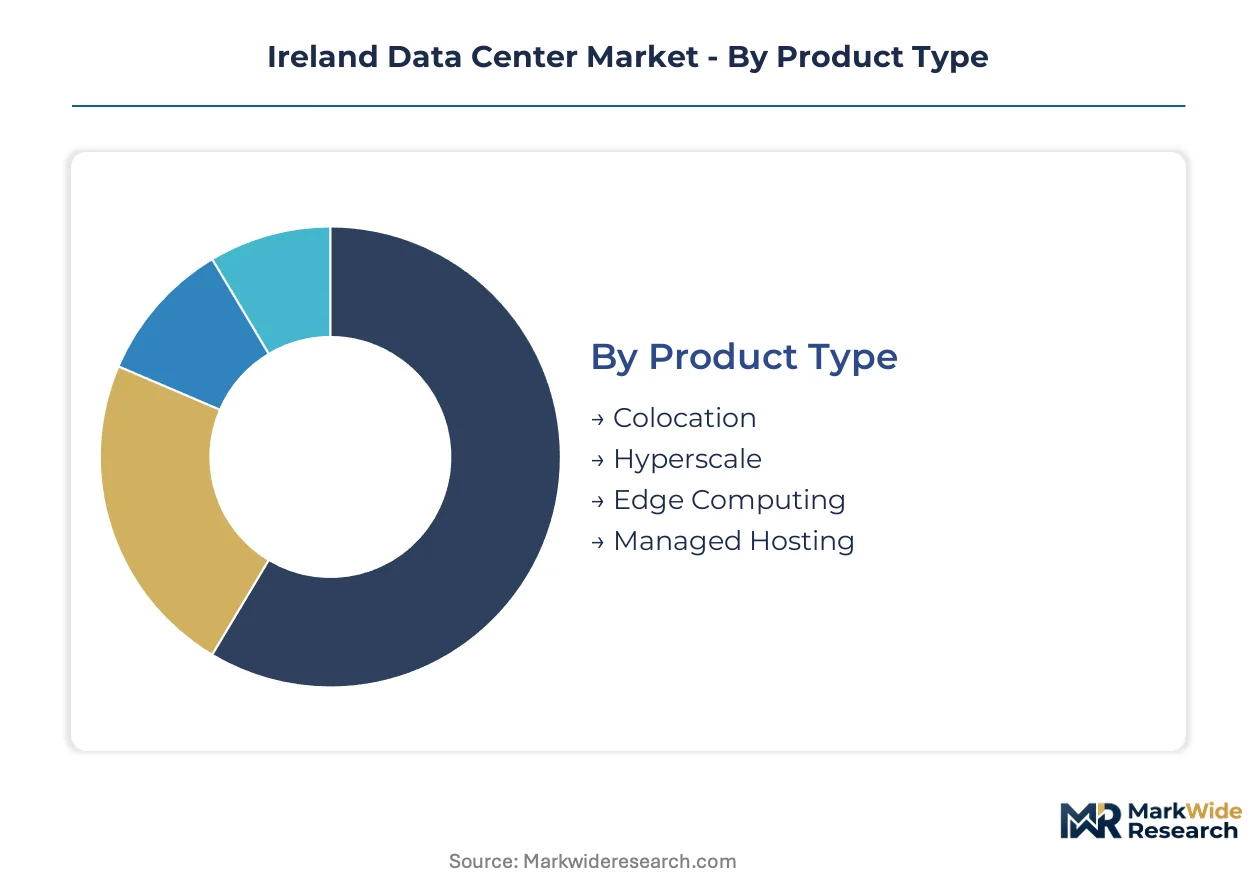
Ireland's data center segmentation reflects the tension between established colocation infrastructure and hyperscale cloud expansion. Understanding facility type, technology stack, and end-user concentration reveals where An Bord Pleanála's planning constraints redirect capital deployment across the island.
Product Type:
Supply concentration in hyperscale campuses is redrawing Ireland's facility map as cloud providers bypass constrained Dublin corridors.
- Colocation:Multi-tenant facilities lease rack space and power to enterprises lacking capital for owned infrastructure. Demand clusters among Dublin-based financial services firms requiring proximity to submarine cable landing stations for sub-10-millisecond London latency.
- Hyperscale:Single-tenant campuses exceeding 50 megawatts serve cloud providers with dedicated mechanical and electrical infrastructure. Google, Microsoft, and Amazon Web Services dominate land positions in County Kildare and western counties where wind power purchase agreements satisfy planning conditions.
- Edge Computing:Distributed micro-facilities under 500 kilowatts position for autonomous vehicle data processing and industrial IoT latency requirements.
- Managed Hosting:Service providers operate customer-owned equipment under long-term contracts, declining as enterprises shift toward cloud-native architectures.
Colocation absorbs the bulk of installed capacity; hyperscale is expanding most quickly as cloud providers execute multi-hundred-megawatt commitments.
Technology:
Cost tier differentiation in thermal and power infrastructure separates premium facilities from commodity competitors as rack densities climb past 30 kilowatts.
- Cooling Solutions:Chilled water, direct expansion, and emerging immersion systems maintain 18°C to 27°C operating ranges. Liquid cooling deployments concentrate in hyperscale artificial intelligence training clusters where dielectric fluid immersion enables 50% higher compute density per square meter.
- Power Distribution:Medium-voltage switchgear, uninterruptible power supplies, and busway systems deliver conditioned electricity to server racks. Commissioning delays from specialized electrical contractor scarcity extend construction timelines for facilities without pre-qualified installation partners.
- Networking Equipment:Core switches, edge routers, and optical transport infrastructure interconnect compute nodes.
- Security Systems:Biometric access control, video surveillance, and intrusion detection protect physical infrastructure.
Cooling solutions command the largest capital allocation; power distribution faces the steepest expansion trajectory as grid connection requirements tighten under Commission for Regulation of Utilities standards.
End User:
Customer type concentration in financial services and cloud providers is reshaping facility design specifications across Ireland's eastern corridor.
- Telecommunications:Mobile network operators and fixed-line carriers deploy edge infrastructure for 5G core network functions and content delivery caching.
- IT Services:Systems integrators and managed service providers resell colocation capacity to enterprise clients with fragmented geographic requirements.
- Financial Services:Investment banks, insurance carriers, and payment processors demand ISO 27001 certification and sub-millisecond connectivity to London and Frankfurt trading venues. Dublin's submarine cable proximity makes Irish facilities attractive for high-frequency trading infrastructure.
- Cloud Providers:Hyperscale operators including Google, Microsoft, and Amazon Web Services anchor European capacity in counties with available grid headroom and streamlined planning processes.
Cloud providers absorb the bulk of new capital deployment; financial services maintains the most stringent certification and latency requirements.
Installation:
Geography of deployment is shifting from established on-premises Dublin campuses toward modular western corridor builds as planning constraints tighten.
- On-premises:Enterprise-owned facilities within corporate real estate portfolios face stranded asset risk as cloud migration accelerates.
- Remote:Off-site dedicated facilities in secondary locations offer disaster recovery capacity with lower land costs than capital-region alternatives.
- Hybrid:Architectures combining owned infrastructure with cloud burst capacity dominate enterprise procurement patterns.
- Modular:Prefabricated data center components enable rapid deployment in counties Galway and Mayo where grid capacity from onshore wind integration attracts developers with lower land costs and streamlined county council planning processes.
On-premises retains legacy installed base; modular is gaining share fastest as developers seek speed-to-market in unconstrained western counties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dublin anchors Ireland's data center concentration, with hyperscale campuses clustering in County Kildare and emerging western corridors redirecting capital as planning constraints tighten across the Greater Dublin Area.
Greater Dublin Area
Financial services demand and submarine cable proximity drive facility concentration in Dublin and adjacent counties. An Bord Pleanála's renewable energy planning conditions now restrict approvals unless projects demonstrate grid stability contributions and wind power purchase agreements. Hyperscale operators maintain existing campuses while new entrants redirect toward unconstrained western locations.
County Kildare
Available transmission capacity and proximity to Dublin make Kildare the primary expansion corridor for cloud providers with established land positions. The Commission for Regulation of Utilities enforces firm demand response requirements that favor operators with battery storage or on-site generation. Microsoft and Google anchor multi-hundred-megawatt commitments across several Kildare sites.
County Cork
Southern Ireland's second-largest urban center attracts developers seeking planning flexibility outside the capital region. County council processes in Cork offer streamlined timelines compared to An Bord Pleanála's direct jurisdiction over Greater Dublin projects. Amazon Web Services competes through aggressive land banking in Cork's industrial zones.
Western Corridor
Counties Galway and Mayo offer untapped grid capacity from onshore wind integration with lower land costs than eastern alternatives. Developers with renewable energy self-sufficiency models satisfy planning conditions that block Dublin-adjacent projects. Modular prefabricated deployments accelerate speed-to-market in these unconstrained markets.
Northern Region
Strategic positioning for UK latency requirements attracts edge computing investments in border-adjacent counties. BT Communications Limited leverages existing telecommunications infrastructure for distributed facility deployment. Grid interconnection with Northern Ireland's network provides additional transmission pathway diversity.
Ireland Data Center Market Competitive Environment
The competitive structure tilts toward hyperscale cloud operators with renewable energy procurement capabilities. Tiered concentration separates global technology platforms with dedicated campuses from multi-tenant colocation specialists serving financial services tenants. Two strategic archetypes dominate: vertically integrated cloud providers with captive power agreements, and independent developers with planning expertise in constrained jurisdictions. Capacity expansion and strategic land banking constitute the dominant competitive moves as operators race to secure positions before grid constraints harden.
Within the hyperscale tier, Google and Microsoft exemplify operators with established Irish wind farm power purchase agreements that satisfy An Bord Pleanála's renewable energy requirements. Among independent developers, K2 Data Centres occupies a position representing specialized planning navigation capabilities in constrained eastern corridors. These three anchors illustrate how renewable energy procurement sophistication and jurisdictional expertise separate viable expansion candidates from blocked projects.
| Leading Market Players |
|---|
| K2 Data Centres |
| Digital Realty |
| Vantage Data Centers |
| Echelon Data Centres |
| Equinix |
| Microsoft |
| BT Communications Limited |
| Amazon Web Services |
| Others |
Value Chain & Pricing Dynamics
Financial services procurement teams now mandate hourly carbon-free energy matching for ESG reporting, forcing colocation operators to secure wind farm power purchase agreements or absorb renewable energy premiums that compress margins on standard rack contracts.
Pricing Analysis
Uptime Institute certification tiers anchor value-based pricing across Irish facilities, with Tier III and Tier IV designs commanding substantial premiums over uncertified alternatives. Price differentiation rests on renewable energy guarantee of origin verification and liquid cooling readiness for artificial intelligence workloads. Cost compression in standard colocation runs through aggressive land banking competition in County Kildare. Cloud providers exhibit lowest price sensitivity given captive infrastructure requirements, while mid-market enterprises negotiate aggressively on per-kilowatt rates.
Supply Chain Analysis
Reverse logistics for server decommissioning and component refurbishment flow through specialized IT asset disposition providers in the Netherlands and Germany, reducing raw material demand for new equipment. Primary manufacturing concentrates in China, Taiwan, and Malaysia for switchgear, servers, and cooling components. Supply chain risk centers on single-source dependency for medium-voltage switchgear from German specialists. Distribution runs through Dublin Port for eastern corridor projects and Cork Harbour for southern deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
An Bord Pleanála's renewable energy planning conditions erect a formidable compliance barrier that rewards operators with established wind power purchase agreements while excluding undercapitalized entrants from the Greater Dublin Area.
For Market Incumbents: Extend renewable energy procurement capabilities through long-term Irish wind farm contracts to defend planning approval access against western corridor competitors. Secure battery storage partnerships to satisfy Commission for Regulation of Utilities demand response requirements. Deepen vertical integration into synchronous condenser installation to accelerate grid connection timelines. For New Entrants and Emerging Players: Enter via modular prefabricated deployments in counties Galway and Mayo where county council planning processes offer faster approval timelines than An Bord Pleanála jurisdiction. Target hyperscale cloud providers seeking secondary European capacity outside constrained Dublin corridors. Lead with liquid cooling specialization to differentiate against legacy air-cooled competitors. For Investors and Strategic Acquirers: Re-rating potential sits with developers holding secured grid connection agreements in western counties given An Bord Pleanála's eastern corridor restrictions. Long-term viability favors operators with demonstrated renewable energy self-sufficiency models. Monitor Commission for Regulation of Utilities queue progression for early signals of permitted capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Power Purchase Agreement | Wind farm contracts satisfy An Bord Pleanála planning conditions for grid stability contributions. |
| Liquid Cooling Infrastructure Deployment | Immersion systems enable artificial intelligence training densities that differentiate Irish facilities. |
| Western Corridor Land Banking | County Galway and Mayo sites offer unconstrained grid capacity with streamlined planning processes. |
| Battery Storage Integration | On-site generation assets accelerate Commission for Regulation of Utilities connection approvals. |
| ISO 27001 Certification Investment | Information security management credentials unlock financial services tenant procurement budgets. |
Study Parameters
Document review covered utility interconnection filings, An Bord Pleanála planning decisions, and corporate renewable energy disclosures, complemented by interviews with data center development executives, utility planning officers, colocation procurement managers, and wind farm project developers. Secondary sources included Commission for Regulation of Utilities grid constraint maps, Environmental Protection Agency emissions licensing records, and hyperscaler capital expenditure reports. Bottom-up facility-level capacity assessments triangulated against top-down market sizing from power demand forecasts.
Segmentation outputs reflect facility type, cooling technology tier, and end-user concentration across the projection horizon. CAGRs derived from power demand elasticity models incorporating cloud provider expansion commitments and planning approval velocity assumptions. Industry-specific inputs included wind farm capacity factor data and specialized electrical contractor availability indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated An Bord Pleanála restriction scenarios or grid interconnection delays. Forecasts reflect documented assumptions regarding renewable energy procurement cost trajectories and western corridor transmission buildout schedules. Practitioners should monitor Commission for Regulation of Utilities queue updates and county council planning approval velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Bengaluru Data Center Market
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Spain Data Center Rack Market
Data Center Infrastructure
Japan Data Center Construction Market