
 Managed Data Center Services Market | 2026-2036
Managed Data Center Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Data Center Services Market Outlook
The EU Energy Efficiency Directive is realigning procurement criteria for data center capacity across European enterprise buyers. Equinix leverages its interconnection platform density to sustain premium positioning in sustainability-conscious markets. Digital Realty anchors its competitive stance through in-house renewable energy contracting and LEED-certified facility expansion. NTT DATA competes on integrated network-services bundling across Asia-Pacific metro clusters.
Managed data center services encompass the outsourcing of facility infrastructure operations, including power distribution, cooling systems, physical security, and remote hands support, typically governed by service level agreements specifying uptime thresholds of 99.99% or higher and mean time to repair commitments. Colocation and hybrid deployment models dominate current revenue contribution, reflecting enterprise reluctance to fully exit owned infrastructure. Edge computing represents the fastest-growing deployment category as latency-sensitive applications in manufacturing and autonomous systems require geographically distributed processing nodes closer to data origination points.
EPA ENERGY STAR certification requirements and EU Code of Conduct for Data Centre Energy Efficiency establish baseline operational standards that filter market access for smaller facility operators unable to fund efficiency retrofits. FERC interconnection rules and state-level renewable portfolio standards in the United States further shape site selection and power procurement strategies for hyperscale deployments. Stakeholders must evaluate carbon intensity metrics alongside traditional cost-per-kilowatt benchmarks when selecting long-term colocation partnerships.
Market Dynamics
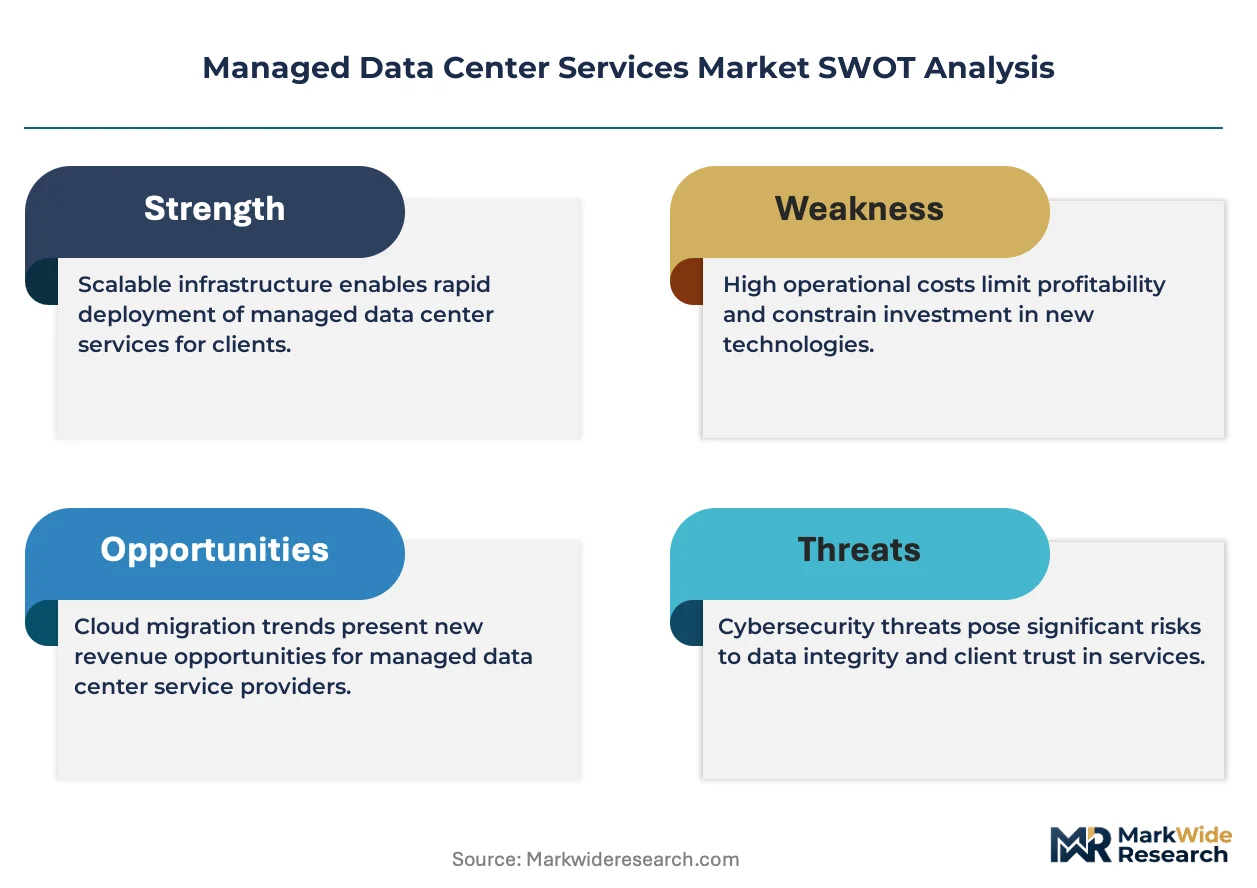
Enterprise workload migration to third-party facilities is compressing capital deployment cycles while the EU Energy Efficiency Directive mandates power usage effectiveness thresholds that filter operator viability.
Growth Catalysts
- EU Energy Efficiency Directive:The directive mandates facility power usage effectiveness reporting, compelling enterprise buyers to favor certified operators and accelerating contract flows toward compliant providers.
- Financial services outsourcing:Banks and insurance carriers are migrating core infrastructure workloads to managed facilities, reducing owned real estate exposure while preserving operational control.
- Edge computing deployment:Latency-sensitive manufacturing and autonomous systems applications require geographically distributed processing nodes, expanding addressable facility demand beyond traditional hub markets.
Market Restraints
- Power cost volatility:Electricity input costs fluctuate with regional grid pricing and renewable energy certificate markets, compressing margin predictability for operators without captive generation.
- Site concentration risk:Hyperscale demand concentrates in Germany, Singapore, and the United States, limiting diversification options and inflating land acquisition premiums in these clusters.
- Liquid cooling retrofit limitations:Legacy air-cooled facilities face technical barriers to supporting high-density GPU deployments, constraining their addressable share of AI training workloads.
Strategic Opportunities
- India data center expansion:The country's digital infrastructure buildout and local data residency requirements create underpenetrated capacity demand from domestic enterprises and multinational subsidiaries.
- Leased renewable energy contracting:Long-term power purchase agreements with solar and wind developers enable carbon-neutral positioning that differentiates operators in sustainability-conscious procurement.
- AI workload hybridization:Convergence of training clusters in hyperscale facilities with inference nodes at edge locations creates bundled service opportunities spanning both deployment categories.
Industry Challenges
- Critical facilities engineering talent:Shortages of technicians qualified in electrical distribution, thermal management, and network operations constrain expansion velocity and elevate labor costs.
- EPA ENERGY STAR certification timelines:The verification process for facility energy performance benchmarking extends deployment schedules and delays revenue recognition for new builds.
- Interconnection complexity:Integrating legacy enterprise networks with cloud on-ramps and carrier-neutral exchange fabrics requires specialized engineering that extends implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Data Center Services Market |
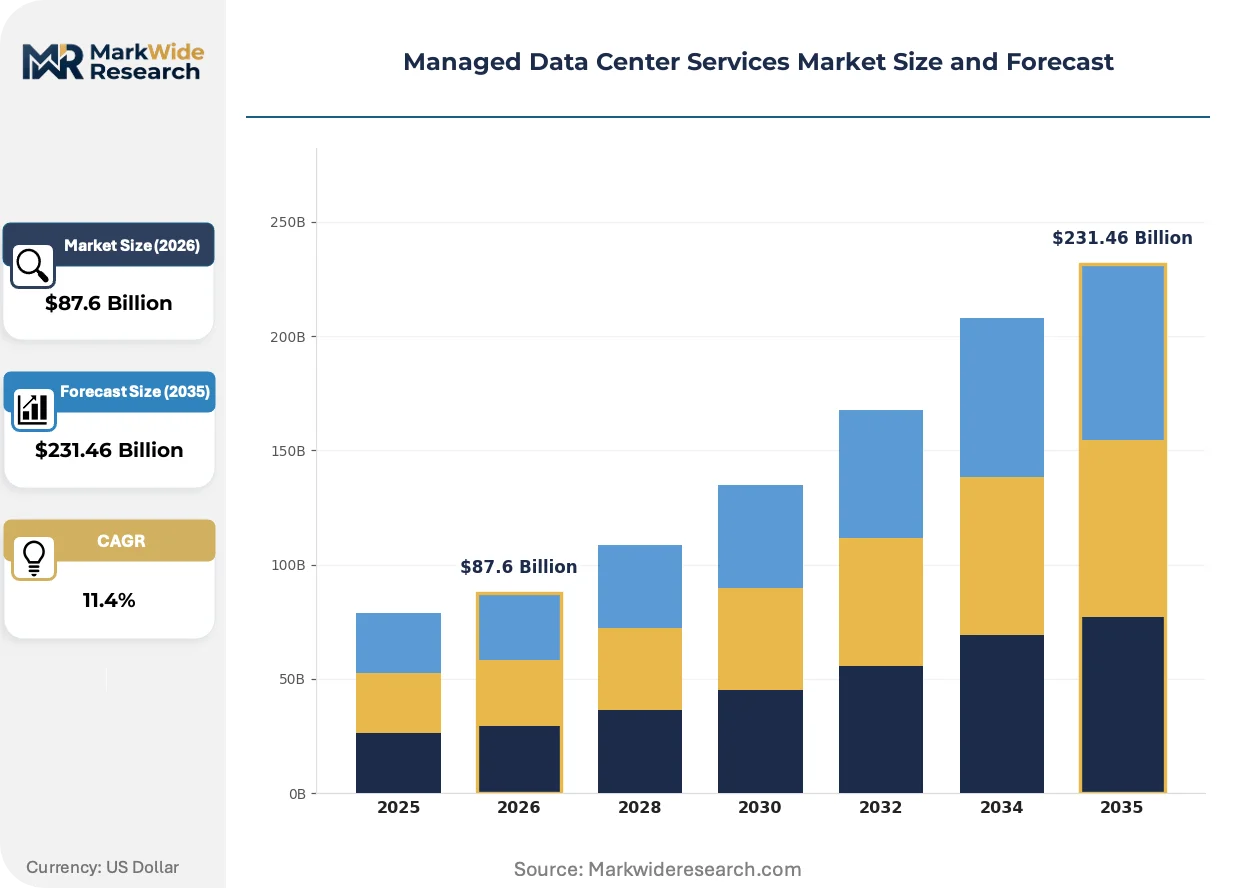
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Dedicated Hosting, Managed Hosting, Disaster Recovery Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Small Enterprises, Large Enterprises, Government, Healthcare Technology: Virtualization, Automation, Security, Networking |
| Companies Covered | Equinix, Digital Realty, NTT DATA, IBM Corporation, Rackspace Technology, Kyndryl, Dell Inc., Hewlett Packard Enterprise, DXC Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Data Center Services Market Strategic Shifts
Liquid cooling architectures and AI-optimized facility designs are compressing traditional infrastructure planning horizons while sustainability-linked procurement criteria reshape competitive positioning.
Direct liquid cooling is overtaking conventional air-handling units in high-density deployments. Hyperscale operators and AI training facilities are adopting cold plate and immersion systems at accelerated rates. This thermal architecture is overtaking legacy designs by enabling rack densities above 50 kilowatts, compressing facility footprints and power distribution costs.
The EU Code of Conduct for Data Centre Energy Efficiency has tightened operational disclosure requirements. Facility operators must now report granular power usage effectiveness and water utilization metrics to retain enterprise contract eligibility. German and Dutch markets exhibit the most stringent enforcement, with procurement teams embedding these standards into request-for-proposal scoring matrices.
Enterprise buyers are consolidating vendor relationships around integrated platform providers. Single-source contracts spanning colocation, interconnection, and managed network services are displacing multi-vendor arrangements. This concentration pattern is most pronounced in financial services and healthcare verticals, where compliance integration costs favor unified operational accountability.
Managed Data Center Services Market Segmentation
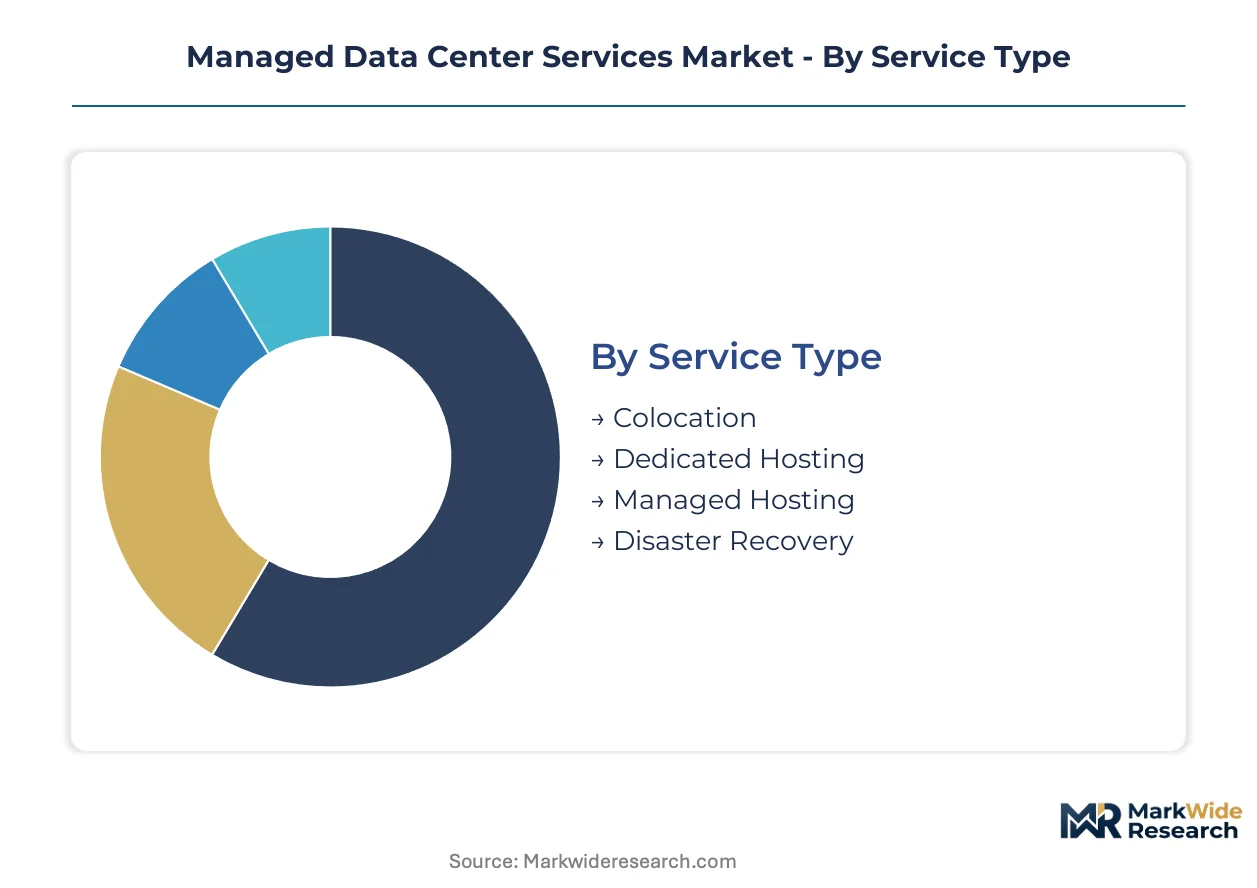
Segmentation in managed data center services reveals how procurement criteria diverge across buyer sophistication levels and workload criticality. Understanding these fault lines enables operators to align facility investments with contract structures that match customer risk tolerance and compliance obligations.
Service Type:
Buyers differentiate primarily by how much operational control they retain versus delegate to third-party operators.
- Colocation:Customers lease physical rack space, power, and cooling while maintaining full control over server hardware and software stacks. Financial services firms in Frankfurt and Singapore concentrate demand here to satisfy data residency requirements without owning real estate.
- Dedicated Hosting:Single-tenant server environments provisioned and maintained by the operator deliver predictable performance for compliance-sensitive workloads. Healthcare systems in Germany favor this model for patient data isolation under GDPR and national health privacy frameworks.
- Managed Hosting:Full-stack infrastructure outsourcing including OS patching, security monitoring, and backup management appeals to mid-market enterprises lacking in-house platform engineering teams.
- Disaster Recovery:Secondary site replication and failover orchestration services command premium pricing based on recovery time objective guarantees and geographic separation mandates.
Colocation leads volumes today; edge-enabled hybrid configurations are gaining share fastest.
Deployment Model:
Latency requirements and data sovereignty rules determine where processing capacity physically resides relative to enterprise networks.
- Hybrid:Interconnected on-premises and third-party environments enable workload portability between owned infrastructure and colocated capacity. Manufacturing firms deploying predictive maintenance systems drive demand across German industrial clusters.
- Edge Computing:Micro-facilities positioned within 10 milliseconds of data origination support autonomous systems and real-time analytics. Singapore's port automation and US manufacturing corridors exhibit the steepest facility deployment trajectories.
- Cloud-Based:Fully abstracted infrastructure consumed as operational expenditure suits development teams prioritizing speed over hardware control.
- On-Premises:Enterprise-owned facilities persist in defense and classified government segments where physical access controls outweigh outsourcing economics.
Hybrid architectures dominate current procurement; edge computing is climbing the fastest as latency-sensitive applications multiply.
End User:
Regulatory exposure and capital availability split the buyer base into fundamentally different contract negotiation postures.
- Large Enterprises:Multi-megawatt deployments with customized space, power, and interconnection specifications command dedicated facility wings and long-term lease structures. US hyperscale cloud providers anchor demand in Northern Virginia and Dallas-Fort Worth corridors.
- Government:FedRAMP, ITAR, and comparable national security certification requirements filter vendor eligibility to operators with cleared personnel and physically segregated infrastructure zones.
- Small Enterprises:Standardized rack units and remote hands services purchased through monthly contracts minimize upfront commitment and technical staffing needs.
- Healthcare:HIPAA in the United States and national health data frameworks in Germany and Singapore impose audit trails and access logging that shape facility selection scoring.
Large enterprises anchor contract values; government segments show the steepest expansion trajectory as digital sovereignty policies tighten.
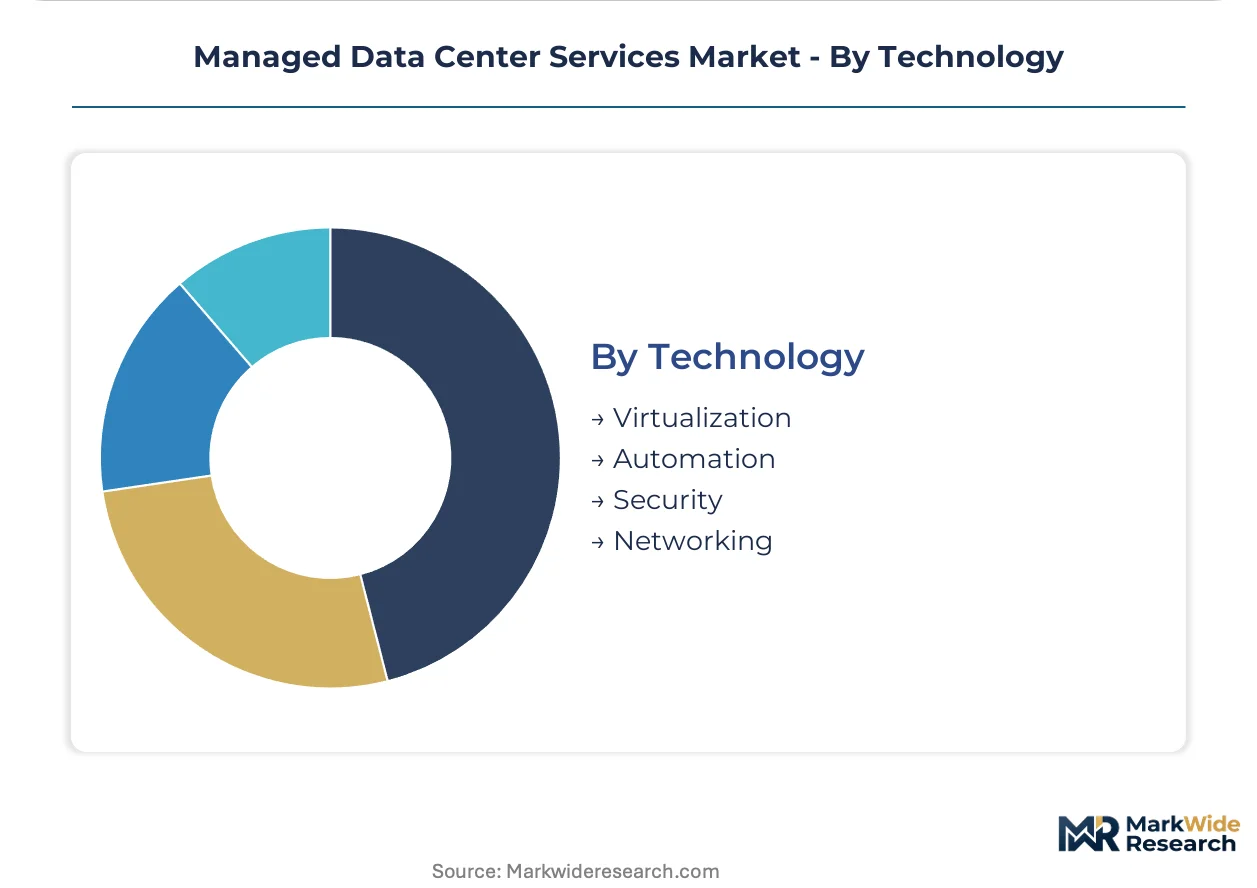
Technology:
Operational efficiency and security posture increasingly determine vendor selection beyond raw space and power metrics.
- Automation:Infrastructure-as-code provisioning and AI-driven predictive maintenance reduce mean time to repair and enable self-service capacity scaling. Operators in Singapore and Germany compete aggressively on platform orchestration capabilities.
- Security:Zero-trust network architectures, biometric physical access controls, and 24/7 security operations center integration address financial services and government threat models.
- Virtualization:Software-defined compute, storage, and networking abstraction layers maximize hardware utilization rates across multi-tenant environments.
- Networking:Carrier-neutral exchange fabrics and direct cloud on-ramps determine interconnection value for hybrid workload architectures.
Automation platforms differentiate operator margins today; security-integrated service bundles are expanding most quickly in regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified data center engineers cluster in Northern Virginia, Frankfurt, and Singapore, anchoring facility operations for hyperscale deployments. These talent concentrations determine where operators can reliably staff 24/7 critical infrastructure operations.
United States
Hyperscale cloud providers drive multi-megawatt absorption in Northern Virginia and Dallas-Fort Worth corridors. FERC interconnection rules and state renewable portfolio standards shape power procurement strategies for new builds. Ashburn, Virginia hosts the densest fiber interconnection ecosystem globally, with operators competing on latency to major cloud regions.
Germany
Financial services firms in Frankfurt demand certified facilities for core banking infrastructure under GDPR data residency mandates. The EU Energy Efficiency Directive enforces granular power usage effectiveness reporting that filters operator eligibility. Berlin and Munich secondary markets are expanding as land scarcity and power constraints tighten in the Frankfurt Rhine-Main cluster.
Singapore
Port automation and maritime logistics generate latency-sensitive edge computing demand from autonomous systems. The country's national data center regulator imposes moratoriums on new facility approvals until renewable energy sourcing commitments are verified. Tuas industrial corridor is absorbing new capacity as the government relaxes deployment restrictions for carbon-neutral projects.
India
Domestic digital infrastructure buildout and local data residency requirements create underpenetrated demand from enterprises and multinational subsidiaries. The country's central bank mandates data localization for payment systems, compelling financial services capacity deployment. Mumbai and Chennai industrial zones are attracting hyperscale investments as submarine cable landing stations multiply interconnection options.
United Kingdom
London-based financial services and fintech clusters sustain demand for low-latency cross-Atlantic connectivity. The national data protection regulator enforces strict breach notification timelines that elevate facility security certification requirements. Slough and Docklands data center zones are densifying as operators retrofit legacy facilities for liquid cooling compatibility.
Managed Data Center Services Market Competitive Environment
Capital-heavy facility owners compete with asset-light service integrators for enterprise workload contracts. The market exhibits tiered consolidation with hyperscale specialists, regional platform operators, and IT services conglomerates occupying distinct competitive bands. Strategic archetypes include interconnection density leaders, renewable energy anchored developers, and network-services bundlers. Dominant competitive moves center on long-term power purchase agreements and edge micro-facility deployment partnerships.
Among platform operators with global interconnection footprints, Equinix and Digital Realty exemplify contrasting approaches to sustainability-linked positioning. NTT DATA occupies a position within the integrated IT services tier, bundling network operations with facility management. These three entities anchor the competitive spectrum from pure-play colocation through full-stack infrastructure outsourcing.
| Leading Market Players |
|---|
| Equinix |
| Digital Realty |
| NTT DATA |
| IBM Corporation |
| Rackspace Technology |
| Kyndryl |
| Dell Inc. |
| Hewlett Packard Enterprise |
| DXC Technology |
| Others |
Value Chain & Pricing Dynamics
Certified data center engineers concentrated in Northern Virginia, Frankfurt, and Singapore drive labor-cost differentials that widen pricing-tier spreads between premium-certified facilities and standard-grade alternatives.
Pricing Analysis
Long-term power purchase agreements anchor facility economics, with pricing stratifying across premium, standard, and economy tiers based on renewable energy certification and uptime guarantee stringency. Tier differentiation hinges on LEED certification level and mean time to repair commitments under SLA terms. Pricing pressure stems from electricity input cost volatility in grid-dependent markets without captive generation. Small enterprises exhibit highest price sensitivity, while financial services firms prioritize compliance certification over per-kilowatt rates.
Supply Chain Analysis
Electrical distribution equipment supply rests on manufacturing concentrations in Germany, China, and the United States, with cooling systems and backup power units drawing from overlapping industrial bases. Critical inputs include uninterruptible power supplies, precision cooling units, and fiber optic interconnection hardware. Single-source vulnerability in semiconductor-based power management components creates procurement risk for facility expansion timelines. Distribution runs through direct OEM relationships with engineering-procurement-construction contractors rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed data center services constitute a late-cycle quality market where procurement teams are consolidating vendor relationships around sustainability-certified operators with verified power usage effectiveness metrics.
For Market Incumbents: Anchor competitive position through long-term renewable energy contracting and liquid cooling retrofit investments that preserve addressability for high-density GPU workloads. Threats from hyperscale self-build programs and edge computing specialists compress margin pools in traditional colocation tiers. Prioritize certification maintenance under EPA ENERGY STAR and EU Code of Conduct frameworks to sustain enterprise contract eligibility. For New Entrants and Emerging Players: AI-optimized facility designs offer a technology-first wedge into underserved industrial corridors requiring latency-sensitive edge nodes. White-space targets include India's Mumbai-Chennai corridor and secondary German markets beyond Frankfurt Rhine-Main. Go-to-market positioning should emphasize integrated network-services bundling rather than pure-play space-and-power offerings. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking facility footprints with verified interconnection density and renewable energy sourcing. Long-term viability favors operators with captive power generation assets and established edge micro-facility partnerships. Watch for regulatory relaxation on data center moratoriums in supply-constrained markets as an inflection signal for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Renewable Power Purchase Agreement | Secures carbon-neutral positioning for EPA ENERGY STAR and EU Code of Conduct compliance. |
| Liquid Cooling Infrastructure Retrofit | Enables rack densities above 50 kilowatts for AI training workload capture. |
| Edge Micro-facility Deployment Partnership | Extends addressable demand into latency-sensitive manufacturing and autonomous systems segments. |
| Integrated Network-services Bundling | Consolidates procurement relationships around single-source operational accountability. |
| Certified Critical Facilities Engineering Talent Acquisition | Resolves expansion velocity constraints from technician shortages in electrical and thermal disciplines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center operations executives, enterprise IT procurement officers, critical facilities engineering directors, and interconnection platform managers with secondary validation through SEC filings of publicly traded operators, FERC interconnection databases, EPA ENERGY STAR certification records, and EU Energy Efficiency Directive compliance disclosures. Bottom-up facility capacity tracking and top-down enterprise spending analysis were triangulated against regional regulatory filings.
Comparable historical absorption patterns anchored the forecast window across the modeling period, with segmentation dimensions including service type, deployment model, end-user vertical, and facility technology tier. CAGRs were derived from facility pipeline tracking and enterprise contract renewal velocity. Forecast inputs incorporated hyperscaler capex disclosure trends and renewable energy certificate market pricing trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to power cost volatility, regulatory tightening on carbon intensity metrics, and liquid cooling technology adoption curves. A small set of triggers—including EU directive enforcement intensity and hyperscale self-build program announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Korea Data Center Rack Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Vietnam Data Center Power Market