
 High-Efficiency Particulate Air (HEPA) Filters Market | 2026-2036
High-Efficiency Particulate Air (HEPA) Filters Market Size, Share, and Industry Trends Forecast 2026-2036
High-Efficiency Particulate Air (HEPA) Filters Market Intelligence
The basis of competition in the HEPA filter market is shifting from price alone to certified performance and application-specific engineering. Camfil specializes in high-purity filters for life sciences and electronics cleanrooms, commanding premium pricing. In contrast, Donaldson Company, Inc. leverages its scale in industrial ventilation to offer standardized filter solutions. Meanwhile, Mann + Hummel Group competes across both automotive and industrial sectors with a broad product portfolio.
A High-Efficiency Particulate Air (HEPA) filter is a mechanical air filter designed to capture airborne particles. To meet the standard, it must remove at least 99.97% of particles with a diameter of 0.3 micrometers from the air that passes through. Cleanroom applications represent the highest-value segment, demanding filters with minimal outgassing and precise pressure drop characteristics. While glass fiber remains the dominant filter media, advanced PTFE membranes are gaining share in applications requiring superior chemical resistance and durability.
ISO 14644 standards for cleanrooms and associated controlled environments define the required air cleanliness levels, directly influencing filter selection. Regulations from bodies like the US FDA for pharmaceutical manufacturing and the CE marking requirements in Europe for medical devices impose strict validation protocols for filtration systems. Future profitability for filter manufacturers depends on developing materials that can meet tightening energy efficiency and particle capture standards simultaneously.
Market Dynamics
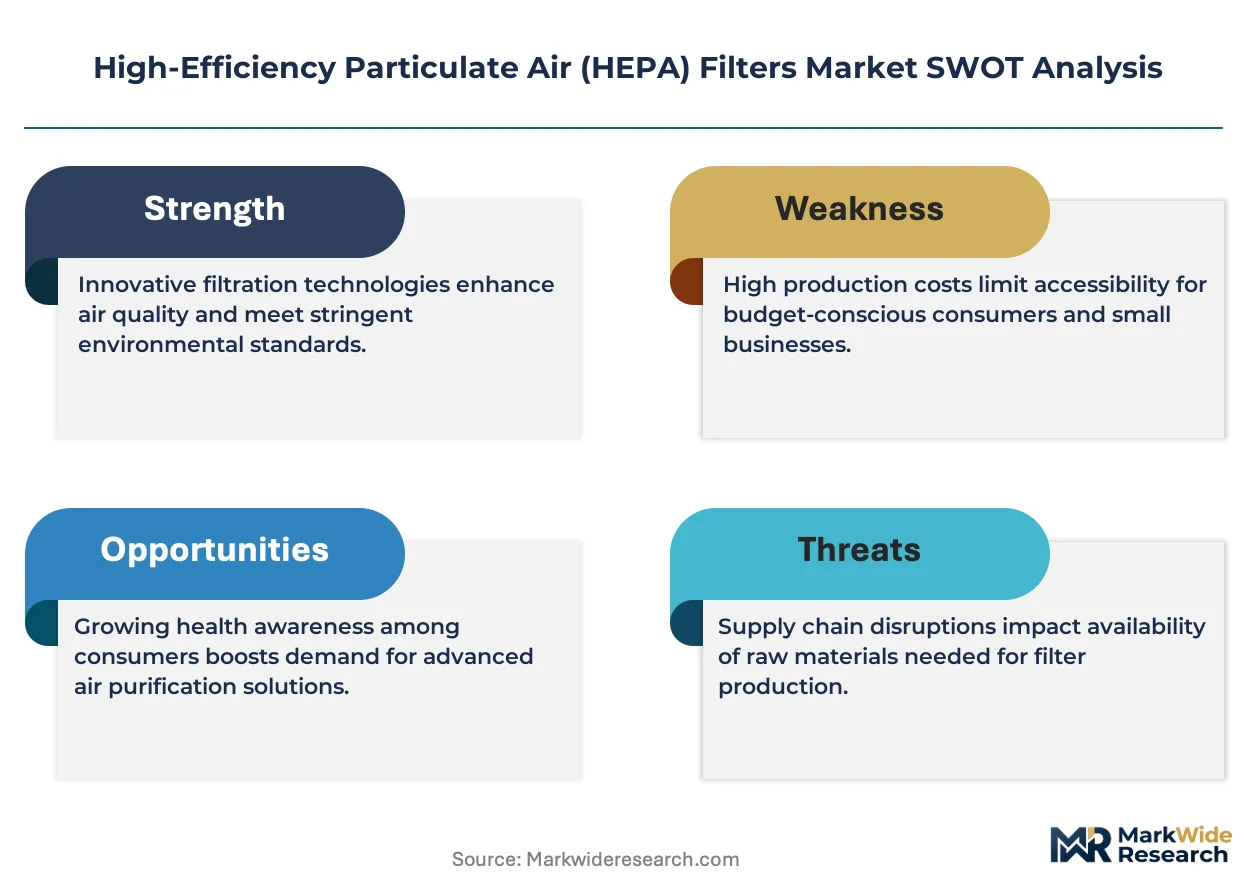
The central tension shaping the HEPA filter market is the simultaneous demand for higher particle capture efficiency and lower energy consumption. This dynamic forces innovation in filter media and design to resolve the inherent trade-off between filtration performance and air-handling system operating costs.
Growth Catalysts
- Stringent Cleanroom Standards:The enforcement of ISO 14644 standards in new semiconductor and pharmaceutical facilities, particularly in Asia, mandates the use of high-grade HEPA and ULPA filters to achieve specified air cleanliness classes.
- Public Health Policies:Government and corporate initiatives promoting healthier indoor air quality in public buildings, schools, and transportation hubs following global health events are driving large-scale HVAC system upgrades with HEPA-grade filters.
- Advanced Manufacturing Expansion:The proliferation of electronics, battery, and life sciences manufacturing requires pristine production environments, boosting demand for filters engineered for specific chemical and particulate contaminants found in those processes.
Market Restraints
- High Energy Consumption:The dense media required for HEPA-level filtration creates significant pressure drop, increasing the energy load on HVAC systems and representing a major operational cost for end-users, especially in large facilities.
- Raw Material Price Volatility:The market depends on specialized inputs like borosilicate micro-glass fibers and PTFE membranes, whose prices can be volatile and supply chains concentrated, creating cost pressure for filter manufacturers.
- Substitution by Alternative Technologies:In less critical applications, the emergence of electronic air purifiers and other non-mechanical filtration technologies presents a lower-cost alternative, limiting HEPA penetration in some consumer and light commercial segments.
Strategic Opportunities
- Smart Filtration Systems:Integrating sensors into filter units to monitor pressure drop, particle load, and remaining lifespan in real-time creates opportunities for data-driven service models and predictive maintenance revenue streams.
- Automotive Cabin Air Quality:The growing consumer focus on in-vehicle air pollution offers a significant opportunity for higher-grade, HEPA-equivalent filters as a standard or premium feature in passenger cars and electric vehicles.
- Antimicrobial Filter Media:Developing filter media with inherent antimicrobial or antiviral properties provides a value-added solution for healthcare, food processing, and public transportation applications where pathogen control is a primary concern.
Industry Challenges
- Validation and Certification Complexity:Navigating the patchwork of regional and application-specific certification standards, such as FDA protocols for pharmaceuticals or CE marking for medical devices, creates long lead times and high compliance costs.
- Disposal and Sustainability:Used HEPA filters, often loaded with hazardous particulates from industrial or medical environments, pose a disposal challenge, pressuring manufacturers to develop more sustainable or recyclable filter designs.
- Energy Efficiency Mandates:Evolving energy performance standards for buildings and equipment, such as those within the EU Green Deal, create a significant engineering challenge to reduce filter pressure drop without compromising particle capture efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Efficiency Particulate Air (HEPA) Filters Market |
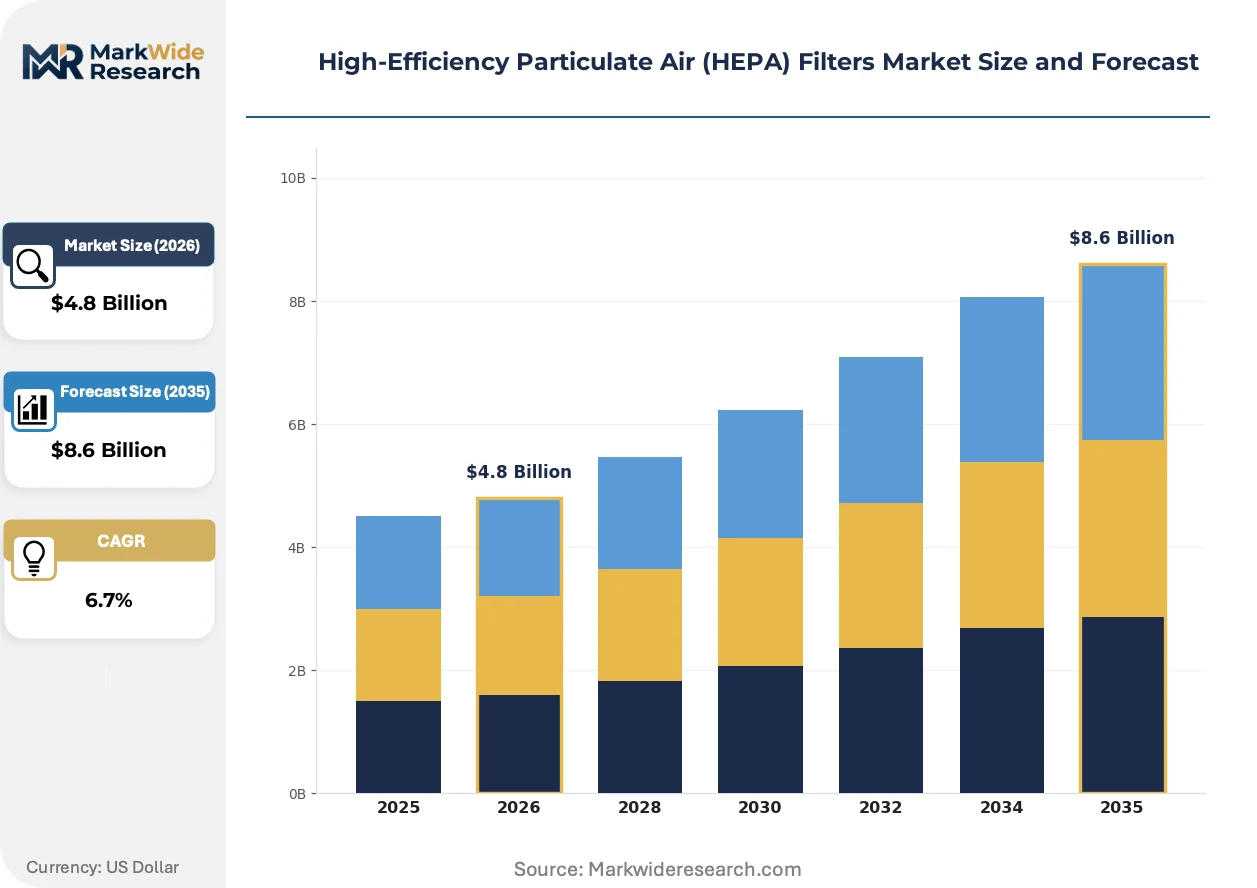
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute HEPA, ULPA, Mini-Pleat HEPA, Medium Efficiency Filter, Electrostatic HEPA Application: Cleanrooms, HVAC Systems, Medical Facilities, Industrial Ventilation, Laboratories End User: Pharmaceutical Manufacturers, Semiconductor Fabricators, Food Processing Units, Residential Buildings, Data Centers Filter Media: Glass Fiber, Synthetic Microfiber, Activated Carbon, Cellulose, PTFE Membrane |
| Companies Covered | Koch Filter Corporation, Flanders Filters, Camfil, Hengst Filtration, SIDCO Filter, AAF International, Mann + Hummel Group, Eurovent Filters, Donaldson Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Efficiency Particulate Air (HEPA) Filters Market Strategic Shifts & Innovations
A fundamental reevaluation of air as a critical utility is underway, driven by a convergence of public health awareness and advanced manufacturing needs. This shift elevates filtration from a building commodity to an engineered system integral to process yield, occupant well-being, and energy strategy.
Composite filter media combines different material layers to achieve targeted performance characteristics. These constructions are seeing rapid adoption in demanding HVAC and automotive cabin applications where a single material cannot meet all requirements. This layering approach is modularizing filter design, enabling manufacturers to create application-specific solutions by altering the media stack rather than engineering entirely new materials.
Regulations from the US FDA, particularly the cGMP guidelines for aseptic processing, impose non-negotiable standards for air quality in sterile manufacturing environments. This directly compels pharmaceutical and biotechnology firms to invest in validated HEPA and ULPA filtration systems with complete traceability. The biopharmaceutical sector is most affected, treating filtration not as an expense but as a critical component of risk mitigation and regulatory compliance.
Procurement patterns for critical environments are moving beyond initial purchase price to a total cost of ownership (TCO) model. This evaluation includes the filter's impact on energy consumption, its operational lifespan, and associated replacement labor costs. This trend is most visible in data centers and hospitals in Europe, where high energy costs and sustainability goals make energy-efficient filtration a primary purchasing criterion.
High-Efficiency Particulate Air (HEPA) Filters Market Segmentation
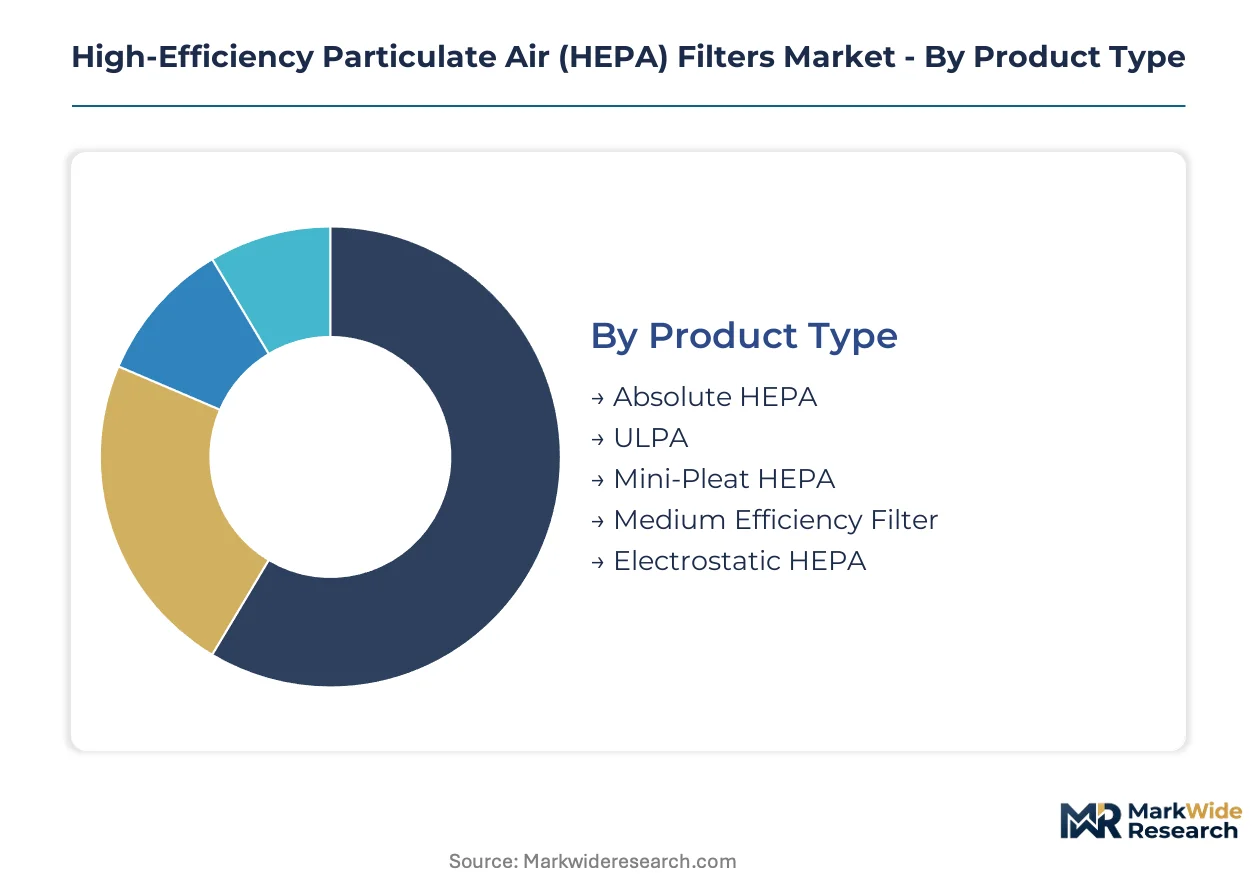
Understanding the High-Efficiency Particulate Air (HEPA) Filters Market through its segmentation reveals the specialized requirements driving product development and end-user adoption. This granular analysis highlights where technological innovation and regulatory compliance intersect, shaping purchasing decisions for critical air filtration systems. The market's diverse segments reflect varying performance needs, from ultra-high purity manufacturing to general indoor air quality improvements.
Product Type:
The upgrade and replacement cycles for HEPA filters are significantly influenced by the specific product type, with advanced filters often mandated for new installations or performance-critical retrofits. Different filter constructions offer distinct advantages in particle capture and lifespan, dictating their suitability across various demanding environments.
- Absolute HEPA:These filters are engineered to remove at least 99.97% of particles 0.3 micrometers in diameter, utilizing dense media to achieve high efficiency. Demand concentrates in pharmaceutical cleanrooms and biological safety cabinets, where stringent particle control is paramount for product integrity and personnel safety.
- ULPA:Ultra-Low Penetration Air (ULPA) filters exceed HEPA standards, capturing 99.999% of particles 0.12 micrometers or larger. Semiconductor fabrication facilities in Taiwan and South Korea represent a primary demand driver, requiring ULPA filters for advanced microchip production to prevent yield-reducing contamination.
- Mini-Pleat HEPA:Featuring a compact design with closely spaced pleats, these filters maximize media surface area for extended lifespan and lower pressure drop in HVAC systems.
- Medium Efficiency Filter:Positioned below HEPA, these filters offer good particulate removal for less critical applications, often serving as pre-filters to prolong HEPA filter life.
- Electrostatic HEPA:These filters use an electric charge to enhance particle capture while maintaining lower airflow resistance, finding use in energy-sensitive commercial buildings.
Volume placements concentrate in Mini-Pleat HEPA filters due to their balanced performance and energy efficiency; the faster expansion belongs to ULPA filters, driven by semiconductor industry growth.
Application:
Each application segment dictates specific performance requirements for HEPA filters, ranging from ultra-clean environments to general air purification. The operational demands of these diverse settings directly influence filter design, material selection, and overall system integration. Regulatory frameworks also play a substantial role in defining filtration standards for critical uses.
- Cleanrooms:These controlled environments demand the highest-grade HEPA and ULPA filters to meet ISO 14644 standards for particle cleanliness, essential for semiconductor manufacturing and sterile pharmaceutical production. The biopharmaceutical sector in Germany and the US mandates validated filtration systems for aseptic processing.
- HVAC Systems:HEPA filters integrated into Heating, Ventilation, and Air Conditioning systems enhance indoor air quality in commercial and public buildings, driven by public health policies following global health events. Government initiatives in the UK and France promoting healthier indoor spaces are accelerating upgrades.
- Medical Facilities:Hospitals and clinics require HEPA filtration in operating theaters and isolation rooms to prevent airborne pathogen transmission, adhering to strict health authority guidelines.
- Industrial Ventilation:Large-scale industrial operations use HEPA filters to capture process-generated particulates and protect workers from hazardous dusts and fumes.
- Laboratories:Research and development facilities employ HEPA filters in fume hoods and biosafety cabinets to maintain sterile conditions and contain hazardous biological agents.
The highest value applications are found in Cleanrooms, while HVAC Systems drive significant volume due to widespread public health initiatives.
End User:
End-user segments are differentiated by their unique operational needs and the regulatory frameworks governing their industries, directly influencing HEPA filter procurement specifications. Compliance with quality standards and safety protocols is a primary driver for filter selection among these diverse user groups. The risk profile of each industry also shapes investment in advanced filtration.
- Pharmaceutical Manufacturers:These users require validated HEPA filtration systems for sterile manufacturing and aseptic processing, complying with US FDA cGMP guidelines and European EMA regulations. Facilities in Ireland and Singapore invest heavily in filtration to ensure drug product quality and safety.
- Semiconductor Fabricators:Fabricators demand ULPA and high-grade HEPA filters to achieve ultra-clean environments necessary for microchip production, minimizing defects and maximizing yield. Major foundries in Taiwan and South Korea continuously upgrade filtration to support advanced node manufacturing.
- Food Processing Units:HEPA filters prevent airborne contamination in food production areas, ensuring product safety and compliance with hygiene standards.
- Residential Buildings:Homeowners and developers increasingly adopt HEPA-grade filters for improved indoor air quality, driven by health awareness and smart home integration trends.
- Data Centers:These facilities utilize HEPA filters to protect sensitive electronic equipment from particulate contamination, ensuring operational reliability and preventing system downtime.
The most stringent regulatory demands originate from Pharmaceutical Manufacturers, with Semiconductor Fabricators expanding rapidly due to continuous technological advancements.
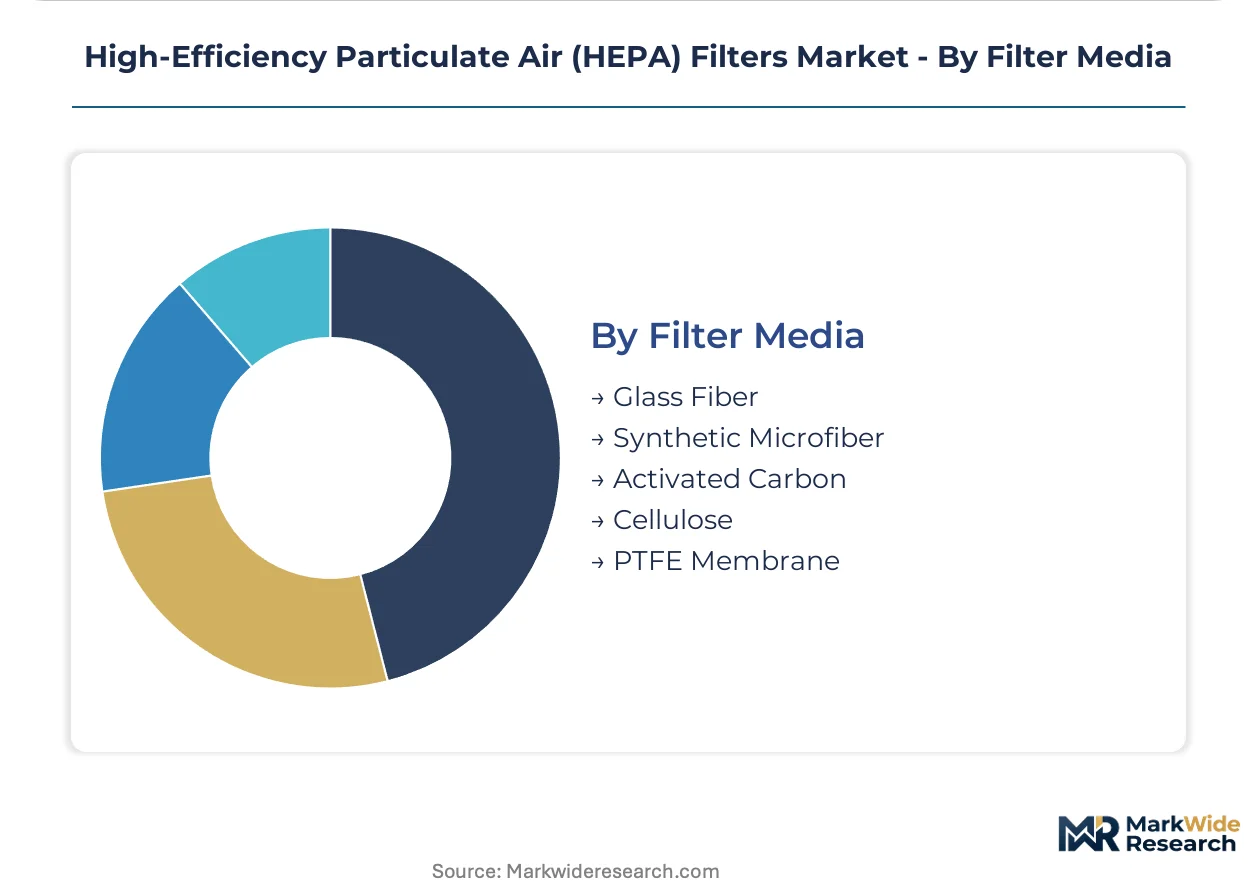
Filter Media:
The choice of filter media is fundamental to a HEPA filter's performance, dictating its particle capture efficiency, pressure drop, and resistance to environmental factors. Material science innovations are continuously improving media capabilities, addressing the simultaneous demand for higher efficiency and lower energy consumption. Each material offers a distinct balance of properties.
- Glass Fiber:Borosilicate micro-glass fibers remain the dominant filter media, providing high particle capture efficiency and mechanical strength for a wide range of HEPA applications. Its cost-effectiveness contributes to its widespread use in industrial and commercial settings globally.
- PTFE Membrane:Advanced Polytetrafluoroethylene (PTFE) membranes are gaining share in applications requiring superior chemical resistance, hydrophobicity, and durability, particularly in corrosive environments and high-humidity cleanrooms in Japan. These membranes offer low pressure drop characteristics.
- Synthetic Microfiber:These media offer an alternative to glass fiber, providing good filtration efficiency with enhanced moisture resistance and often lower energy consumption.
- Activated Carbon:Primarily used for gas and odor removal, activated carbon media are often combined with particulate filters for comprehensive air purification solutions.
- Cellulose:Less common in true HEPA applications, cellulose-based media are used in lower-efficiency filters or as pre-filters, offering cost-effective particulate capture.
While Glass Fiber remains the foundational material, advanced applications increasingly specify PTFE Membrane for enhanced performance and durability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta in China drives significant demand for advanced HEPA filters, supporting its expansive electronics and pharmaceutical manufacturing base. This region's industrial growth mandates high-efficiency filtration systems. Strict domestic air quality standards influence procurement patterns across its industrial zones.
China
China's expanding electronics and pharmaceutical manufacturing sectors require high-grade HEPA filters. Stringent GB standards for cleanroom environments enforce superior air cleanliness levels. Industrial parks in Suzhou are continuously investing in advanced filtration systems to meet production demands.
United States
United States pharmaceutical manufacturers and the biopharmaceutical sector demand validated HEPA filtration systems. US FDA cGMP guidelines for aseptic processing impose non-negotiable standards for air quality. The Boston biotech cluster mandates validated filtration for sterile drug production and research facilities.
Germany
Germany's biopharmaceutical sector and advanced manufacturing facilities require high-grade HEPA filters. The EU Green Deal influences energy performance standards for buildings and equipment. Munich's high-tech manufacturing facilities prioritize energy-efficient HEPA solutions to reduce operational costs.
Taiwan
Taiwan's semiconductor fabricators drive demand for ULPA and high-grade HEPA filters. Adherence to ISO 14644 standards is essential for achieving ultra-clean production environments. Foundries in Hsinchu Science Park continuously upgrade ULPA filtration for advanced node manufacturing.
Japan
Japanese industries require advanced HEPA filters for high-humidity cleanrooms and corrosive environments. JIS standards for air filters ensure performance and material durability. Electronics manufacturing plants in Osaka increasingly specify PTFE membrane filters for superior chemical resistance.
High-Efficiency Particulate Air (HEPA) Filters Market Key Industry Players
Premium-margin players sit above commodity-margin players across certified performance and application-specific engineering in the HEPA filter market. This market exhibits a tiered structure, with specialized firms focusing on high-value segments and larger industrial players offering standardized solutions. Strategic archetypes include niche innovators, broad portfolio providers, and scale-driven manufacturers catering to diverse needs. Capacity expansion and strategic partnerships are dominant competitive moves as companies seek to secure supply chains and penetrate new applications.
On the premium-tier vector, Camfil represents a specialist in high-purity filters for life sciences and electronics cleanrooms. Donaldson Company, Inc. occupies a position among scale-driven industrial suppliers, leveraging its extensive industrial ventilation presence. Mann + Hummel Group sits within the broad portfolio archetype, competing across both automotive and industrial sectors. These entities anchor distinct competitive strategies within the market, reflecting different approaches to product development and customer engagement. Their varied operational models exemplify the diverse paths to market leadership in filtration.
| Leading Market Players |
|---|
| Koch Filter Corporation |
| Flanders Filters |
| Camfil |
| Hengst Filtration |
| SIDCO Filter |
| AAF International |
| Mann + Hummel Group |
| Eurovent Filters |
| Donaldson Company, Inc. |
Cost & Logistics Intelligence
The clear performance divergence between ultra-high purity filters and standardized solutions shapes both pricing dynamics and supply chain configurations within the HEPA filter market. This bifurcation concentrates premium pricing power in specialized segments, while volume-driven offerings face greater cost scrutiny.
Pricing Analysis
Value-based pricing anchored to process yield and regulatory compliance dictates pricing for advanced HEPA filters. Certification level, such as ISO 14644 adherence or US FDA cGMP validation, drives premium pricing, alongside application-specific engineering for minimal outgassing. Pricing pressure stems from increased competition in standard HEPA filters for commercial HVAC applications. Cleanroom applications in semiconductor fabrication and pharmaceutical manufacturing demonstrate the least price sensitivity, prioritizing performance over cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized material suppliers for borosilicate micro-glass fibers and advanced PTFE membranes. Geographic supply concentration includes China for general manufacturing, Japan for PTFE membrane production, and Germany for specialized glass fiber. Raw material price volatility for these key inputs presents a structural risk to filter manufacturers. Distribution runs through direct sales channels for high-value cleanroom projects and established distributor networks for industrial and HVAC applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, as advanced PTFE membranes are displacing traditional glass fiber in critical applications demanding superior chemical resistance and durability.
For Market Incumbents:Cement leadership in high-purity segments by investing heavily in advanced material science R&D, particularly for lower pressure drop PTFE membranes. Acquire specialized media manufacturers to mitigate raw material price volatility and secure critical input supply. This strategy defends against emerging electronic air purifiers in less critical applications and strengthens compliance with evolving energy efficiency mandates like the EU Green Deal. Capacity additions in Asia support expanding semiconductor and biopharmaceutical sectors.
For New Entrants and Emerging Players:HVAC system integrators present a significant channel for penetrating the commercial and public building segments. Target underpenetrated applications like automotive cabin air quality or smart filtration systems for predictive maintenance. Develop antimicrobial filter media for healthcare and public transportation, offering a value-added solution for pathogen control. A go-to-market strategy focusing on data-driven service models can differentiate offerings from established players.
For Investors and Strategic Acquirers:Re-rating potential sits with niche innovators specializing in advanced filter media or integrated smart filtration solutions given sustained demand from cleanroom expansion and indoor air quality mandates. The long-term viability of this market over the next decade is strong, driven by stricter regulatory standards and public health awareness. Target acquisition archetypes include firms with proprietary PTFE membrane technology or those developing sustainable filter disposal solutions. Increased M&A activity in antimicrobial media represents a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports the growing demand from semiconductor and biopharmaceutical manufacturing in Asia. |
| Material Science R&D | Develops lower pressure drop media to meet tightening energy efficiency standards. |
| Digital Integration | Embeds sensors for predictive maintenance, creating new service revenue streams in HVAC systems. |
| Sustainability Initiatives | Engineers recyclable filter designs, addressing the environmental challenge of hazardous waste. |
| Strategic Partnerships | Collaborates with HVAC system manufacturers to offer integrated and optimized air filtration solutions. |
Research Approach
Multi-period observation of cleanroom construction pipelines and indoor air quality policy adoption rates anchored the trend analysis, supplemented by interviews with cleanroom facility managers and filter material scientists. This approach combined primary insights from industry stakeholders with secondary validation from regulatory documents. We engaged HVAC system engineers and regulatory compliance officers to triangulate market dynamics, ensuring comprehensive data coverage.
An input-output matrix framing guided the quantitative model, projecting market growth across the analysis window. Segmentation dimensions modeled included product type, application, end-user, filter media, and regional regulatory enforcement. Compound annual growth rates were derived through regression analysis of historical data and future market drivers. Key industry-specific forecast inputs included advancements in microchip manufacturing nodes and global health event response policies.
Caveats apply where unforeseen global health crises or rapid material science breakthroughs could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Activated Carbon Market
Filters
Diatomaceous Filter Aid Market
Filters
Coolant Filtration Systems Market
Filters
High Purity Chemical Filters Market
Filters
Europe Industrial Air Filtration Market
Filters
Filtration and Separation Market
Filters
Global Gas Phase Filtration Market
Filters
North America Gas Filtration Media Market
Filters
United States Activated Carbon Market
Filters
Hydraulic Filters Market
Filters
Zeolite Adsorbents Market
Filters
Global Baghouse Filters Market
Filters
Europe Activated Carbon Market
Filters
Furnace Filters Market
Filters
Global Gas Filtration Media Market
Filters
Fabric Filter System Market