
 Granular Polytetrafluoroethylene (PTFE) Market | 2026-2036
Granular Polytetrafluoroethylene (PTFE) Market Size, Share, and Industry Trends Forecast 2026-2036
Granular Polytetrafluoroethylene (PTFE) Market Analysis
High-purity semiconductor-grade granular PTFE is collapsing the price premium between electronic and industrial resin tiers, forcing specification convergence across buyer categories. Chemours leverages captive fluorspar mining and integrated tetrafluoroethylene production to sustain margin control against Asian cost structures. Daikin Industries anchors Japanese supply through Osaka-based compounding facilities that dominate thin-film extrusion for wafer processing equipment. Gujarat Fluorochemicals competes on backward integration into chlorodifluoromethane feedstock, positioning it as India's largest integrated fluoropolymer producer.
Granular polytetrafluoroethylene denotes a free-flowing resin form produced by suspension polymerization of tetrafluoroethylene monomer, yielding particles typically 20-500 microns with melt viscosity exceeding 10¹⁰ poise that prevents conventional melt processing and mandates sintering above 327°C. The material serves primarily as a feedstock for compression-molded billets, extruded rods, and skived films requiring chemical inertness and service temperatures from -200°C to 260°C. Resin and powder categories command the deepest margin pools where semiconductor and pharmaceutical buyers enforce lot-traceable purity certifications, while films for dielectric insulation represent the fastest-growing application dimension as 5G infrastructure deployment accelerates substrate demand. Compression molding remains the dominant manufacturing stage for thick-walled components in chemical processing equipment, though injection molding of modified granular grades is displacing machined shapes in automotive bearing applications.
EPA regulations under the Toxic Substances Control Act restrict long-chain perfluoroalkyl substance releases from PTFE manufacturing, compelling Chemours and Daikin to invest in aqueous film-forming foam alternative chemistries and wastewater treatment infrastructure. REACH Annex XVII restrictions on perfluorooctanoic acid precursors shape European import requirements, with ECHA evaluations determining whether recycled PTFE content qualifies for polymer exemption thresholds. FDA 21 CFR 177.1550 compliance governs granular PTFE contact with food in processing equipment, creating a dual-certification burden for suppliers serving both industrial and consumables markets. Stakeholders must monitor evolving fluoropolymer classification under the EU F-Gas Regulation, as potential HFC-phase-down extensions could restrict feedstock availability or trigger carbon border adjustments on imported resin.
Market Dynamics
Semiconductor-grade purity certification is compressing the historical tiering between electronic and industrial resin specifications, forcing specification convergence that eliminates margin arbitrage between buyer categories.
Growth Catalysts
- 5G substrate deployment:Dielectric film demand from base station manufacturers in China's electronics manufacturing belt is pulling high-frequency grade granular PTFE into antenna substrate laminates.
- REACH Annex XVII compliance:European industrial coating buyers are consolidating purchases around lot-traceable virgin resin to satisfy perfluorooctanoic acid precursor restrictions.
- Aerospace sealing systems:FAA pressure specifications for next-generation aircraft are expanding fluoropolymer adoption in critical O-ring and gasket applications.
Market Restraints
- Fluorspar supply concentration:Captive mining access in China and Mexico creates input cost volatility for non-integrated compounders in Europe and North America.
- Melt viscosity limitation:The 10¹⁰ poise threshold prevents conventional injection molding, restricting design freedom in thin-wall automotive components.
- EPA TSCA release restrictions:Long-chain perfluoroalkyl substance wastewater rules impose capital-intensive treatment infrastructure on US-based suspension polymerization facilities.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Backward integration into chlorodifluoromethane feedstock positions domestic producers to capture import-substitution volume in industrial coatings.
- Wafer processing equipment films:Thin-film extrusion for 300mm wafer handling components represents an emerging application with qualification timelines shortening to 18 months.
- EU F-Gas Regulation evolution:Potential carbon border adjustments on imported resin create regulatory tailwinds for European compounding facilities with verified low-emission tetrafluoroethylene production.
Industry Challenges
- Sintering technician scarcity:Compression molding operations above 327°C require specialized thermal process engineers, with training pipelines failing to match capacity expansion in Germany's industrial corridor.
- FDA dual-certification burden:Suppliers serving both food-contact and industrial markets face 14-18 month validation timelines for 21 CFR 177.1550 compliance on shared production lines.
- Legacy equipment integration:Modified granular grades for injection molding demand screw-and-barrel retrofits that compress cycle economics for automotive bearing producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granular Polytetrafluoroethylene (PTFE) Market |
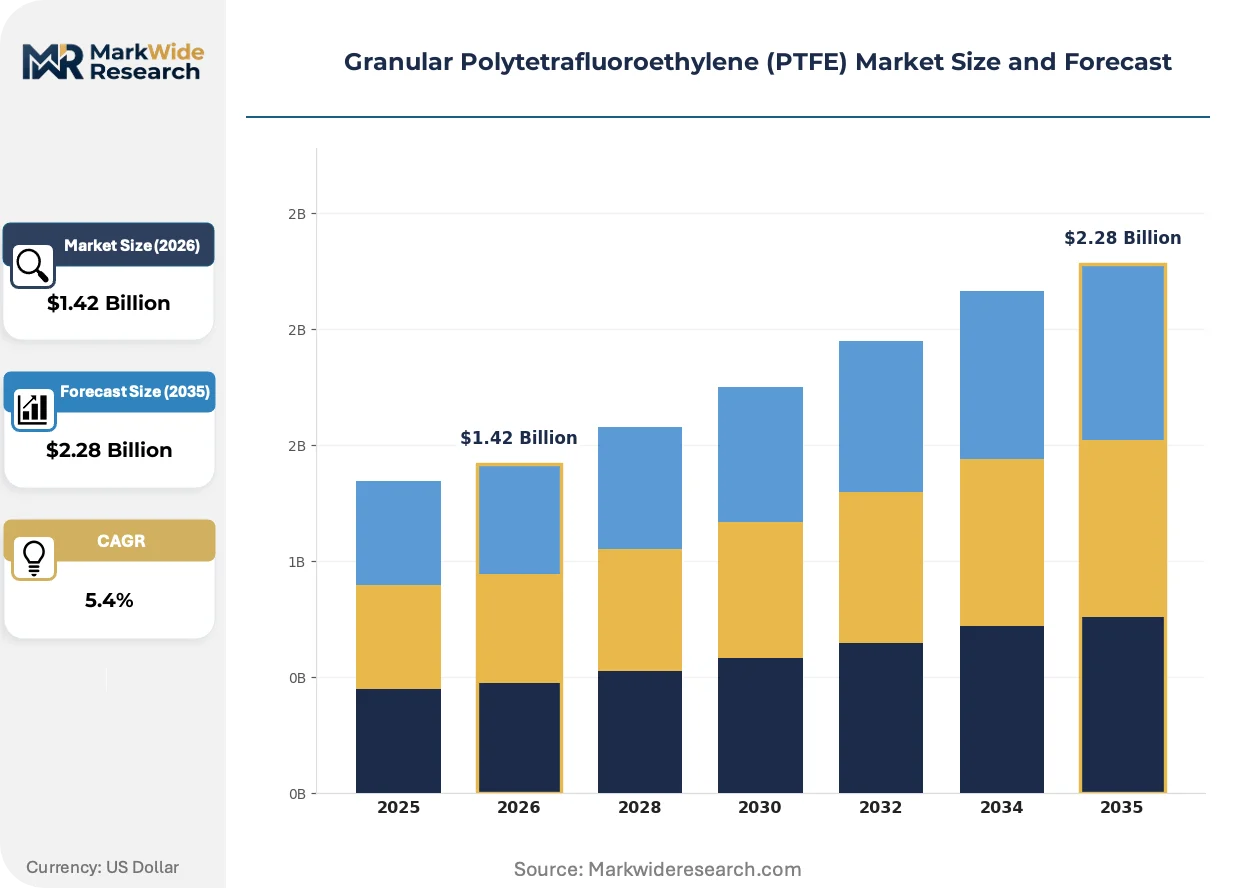
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin, Powder, Granules, Films End Use Industry: Aerospace, Automotive Components, Electronics, Industrial Coatings Manufacturing Stage: Extrusion, Compression Molding, Injection Molding, Coating Application: Seals, Gaskets, Bearings, Insulation |
| Companies Covered | Chemours, Daikin Industries, 3M, Gujarat Fluorochemicals, AGC Inc., Dongyue Group, Solvay, Shanghai 3F New Materials, HaloPolymer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granular Polytetrafluoroethylene (PTFE) Market Emerging Trajectories
Process innovation and regulatory recalibration are actively restructuring how resin grades are specified, priced, and supplied across end-use verticals.
Modified granular PTFE compounds with controlled molecular weight distribution are supplanting machined virgin shapes in automotive bearing cages. Tier-1 suppliers in Germany's automotive supply chain are qualifying these grades for electric vehicle thermal management modules. The shift compresses unit economics by eliminating post-machining scrap while demanding tighter lot-to-lot viscosity control from compounders.
REACH RoHS alignment on purity thresholds is tightening import documentation requirements for Asian resin entering European coating applications. ECHA evaluations of recycled content exemption qualifications are forcing compounders to segregate virgin and reprocessed streams. German industrial buyers are responding by consolidating supplier panels around integrated producers with in-house tetrafluoroethylene synthesis.
Direct mill relationships are displacing distributor-led specification in semiconductor-grade procurement. Wafer equipment OEMs in Japan and South Korea are requiring resin suppliers to co-locate technical service engineers at their Osaka and Suwon facilities. This channel compression is most visible in dielectric film contracts where qualification data packages now transfer directly between compounder and substrate laminator.
Granular Polytetrafluoroethylene (PTFE) Market Segmentation
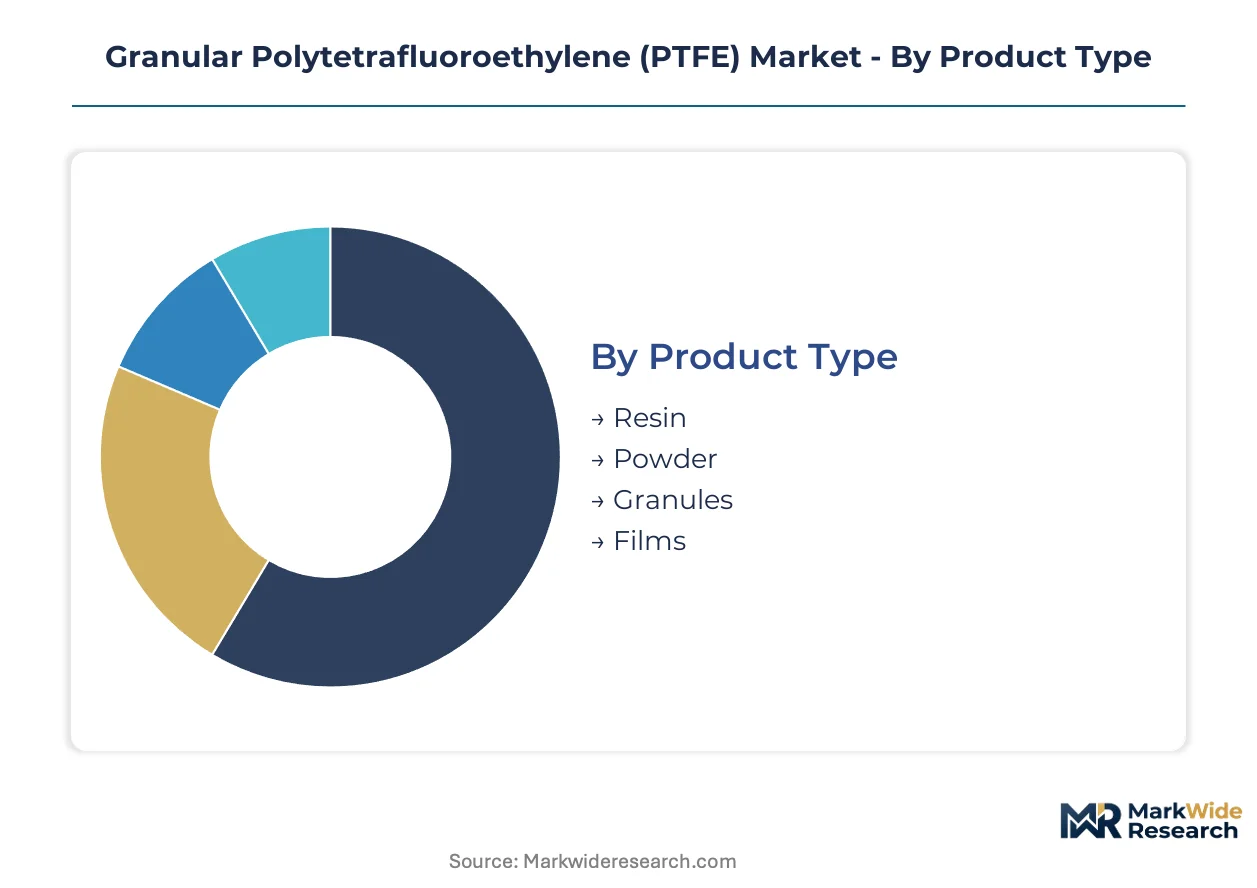
Granular PTFE segmentation reveals how resin specifications, manufacturing methods, and end-use requirements channel material flows through distinct procurement pathways. Buyers in semiconductor and pharmaceutical verticals enforce lot-traceable purity tiers that reshape supplier relationships across each category.
Product Type:
Resin and powder grades move through direct mill relationships with compounders, while films and granules increasingly route through specialized distributors serving regional coating clusters.
- Resin:Virgin suspension-polymerized material with melt viscosity exceeding 10¹⁰ poise serves as the foundational feedstock for compression-molded billets. Semiconductor-grade resin demand concentrates in Japan's Osaka-based compounding facilities where wafer processing equipment manufacturers enforce sub-ppm metallic contamination thresholds.
- Films:Skived or extruded dielectric layers ranging from 25 microns to several millimeters enable high-frequency signal transmission. 5G infrastructure deployment in China's electronics manufacturing belt is pulling high-frequency grade films into antenna substrate laminates as the steepest expansion trajectory within this category.
- Powder:Fine-particle fractions below 20 microns facilitate spray coating and dispersion applications in industrial corrosion protection.
- Granules:Agglomerated free-flowing forms optimize handling in automated feeding systems for continuous extrusion operations.
Resin dominates installed base. Films are where expansion concentrates.
End Use Industry:
Cost tier stratification separates aerospace and electronics buyers—who absorb premium pricing for certification documentation—from automotive and industrial coating purchasers focused on volume scale.
- Electronics:Dielectric substrates, connector insulators, and wafer handling components demand semiconductor-grade purity with full lot traceability. Japanese and South Korean wafer equipment OEMs now require resin suppliers to co-locate technical service engineers at their Osaka and Suwon facilities.
- Aerospace:FAA pressure specifications for next-generation aircraft are expanding fluoropolymer adoption in critical O-ring and gasket applications requiring sustained performance from -200°C to 260°C.
- Automotive Components:Modified granular grades for bearing cages and thermal management modules in electric vehicles are displacing machined virgin shapes.
- Industrial Coatings:REACH Annex XVII compliance is consolidating European purchases around lot-traceable virgin resin to satisfy perfluorooctanoic acid precursor restrictions.
Industrial coatings anchor volume throughput. Electronics commands margin concentration.
Manufacturing Stage:
Application maturity determines whether processes run on legacy equipment or demand capital-intensive retrofits, with compression molding retaining deepest penetration in thick-walled chemical processing components.
- Compression Molding:The dominant stage for thick-walled components in chemical processing equipment requires sintering above 327°C with specialized thermal process engineers. Germany's industrial coatings corridor faces technician scarcity as training pipelines fail to match capacity expansion.
- Injection Molding:Modified granular grades with controlled molecular weight distribution are supplanting machined shapes in automotive bearing applications, though screw-and-barrel retrofits compress cycle economics.
- Extrusion:Continuous profile production for rods, tubes, and wire insulation coatings serves electrical infrastructure and fluid handling systems.
- Coating:Dispersion-based surface treatments for corrosion protection in chemical processing equipment leverage powder and fine-particle resin fractions.
Compression molding holds installed base dominance. Injection molding is gaining share fastest among automotive qualifiers.
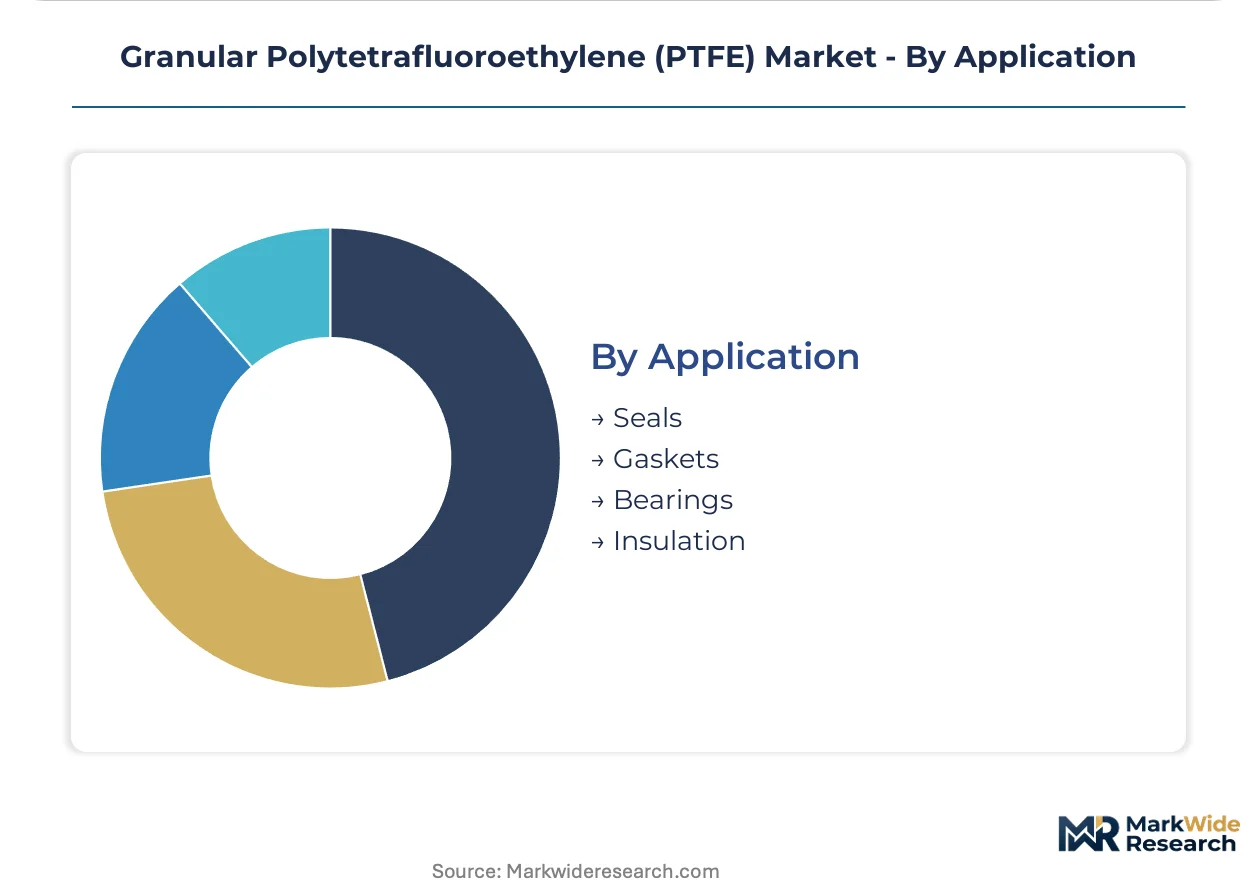
Application:
Customer type bifurcation separates specification-driven OEM procurement from maintenance-repair-operations purchasing in aftermarket channels.
- Seals:Critical O-ring and gasket applications in aerospace and chemical processing demand compression-molded billets with verified dimensional stability across thermal cycling.
- Insulation:Dielectric films and extruded wire coatings for 5G infrastructure and electrical systems represent the most rapidly expanding application dimension as substrate laminates multiply.
- Gaskets:Sheet and cut-gasket formats serve flange connections in process industries with FDA 21 CFR 177.1550 compliance required for food-contact installations.
- Bearings:Automotive and industrial machinery applications are shifting toward injection-molded modified grades to eliminate post-machining scrap.
Seals retain the broadest cross-industry penetration. Insulation is where specification investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese resin exports dominate supply into South Korea's wafer equipment sector and Germany's industrial coatings corridor, establishing the primary east-west trade corridor for semiconductor-grade granular PTFE.
United States
EPA TSCA release restrictions on long-chain perfluoroalkyl substances drive capital allocation toward wastewater treatment infrastructure at suspension polymerization facilities. The regulatory burden compresses operating margins for non-integrated compounders serving aerospace sealing OEMs. Texas and Louisiana host concentrated fluoropolymer production clusters where captive fluorspar access determines cost competitiveness.
Germany
REACH Annex XVII compliance on perfluorooctanoic acid precursors consolidates procurement around lot-traceable virgin resin suppliers. ECHA evaluations of recycled content exemptions reshape import documentation requirements for Asian material. The industrial coatings corridor spanning North Rhine-Westphalia and Bavaria faces technician scarcity as sintering training pipelines lag capacity expansion.
China
Electronics manufacturing belt demand for 5G antenna substrates pulls high-frequency grade films into dielectric laminates. MIIT standards on fluoropolymer purity align with export requirements for Japanese and South Korean wafer equipment OEMs. The Yangtze River Delta concentration of compounding facilities supplies compression-molded billets for regional chemical processing equipment fabricators.
Japan
Wafer processing equipment manufacturers in Osaka enforce sub-ppm metallic contamination thresholds on semiconductor-grade resin procurement. METI guidance on fluoropolymer supply chain security encourages domestic compounding capacity retention. The Kansai industrial cluster anchors thin-film extrusion qualification for 300mm wafer handling components.
India
PLI scheme incentives for specialty chemicals attract backward integration investment into chlorodifluoromethane feedstock production. BIS certification requirements for industrial coating resins create compliance barriers for unqualified imports. Gujarat's integrated fluoropolymer production base targets import substitution in automotive bearing and chemical processing applications.
Granular Polytetrafluoroethylene (PTFE) Market Vendor Landscape
Listed leaders compete with private specialists across integrated versus non-integrated business models, creating a tiered structure where captive feedstock access separates margin tiers. The vendor base concentrates around suspension polymerization specialists with in-house tetrafluoroethylene synthesis and regional compounders dependent on merchant monomer supply. Three archetypes dominate: integrated miners-to-resin producers, regional compounding specialists, and application-focused film extruders. Competitive moves center on backward integration into fluorspar mining and qualification co-location with semiconductor equipment OEMs.
Among integrated producers with captive supply chains, Chemours and Daikin Industries exemplify the miner-to-resin archetype that controls cost volatility through upstream ownership. Gujarat Fluorochemicals occupies a position representing regional backward integration strategy, anchoring Indian supply through chlorodifluoromethane feedstock control. These three entities sit within distinct geographic spheres—North American, Japanese, and Indian—yet converge on similar structural approaches to margin defense.
| Leading Market Players |
|---|
| Chemours |
| Daikin Industries |
| 3M |
| Gujarat Fluorochemicals |
| AGC Inc. |
| Dongyue Group |
| Solvay |
| Shanghai 3F New Materials |
| HaloPolymer |
| Others |
Supply Flow & Price Mechanics
Modified granular grades displacing machined virgin shapes in automotive bearing cages simultaneously redraw procurement geography toward Germany's automotive supply chain and compress unit economics by eliminating post-machining scrap recovery value. This substitution dynamic concentrates margin pressure on non-integrated compounders while rewarding producers with captive tetrafluoroethylene synthesis.
Pricing Analysis
Prior-generation virgin resin, current-generation semiconductor-grade material, and next-generation high-frequency dielectric films operate under a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale differentiate tiers, with lot-traceable pharmaceutical and semiconductor buyers absorbing premium pricing while automotive purchasers drive cost compression. Pricing pressure stems from REACH Annex XVII compliance costs transferring to European industrial coating buyers. Automotive bearing producers exhibit highest price sensitivity due to injection-molding retrofit investments.
Supply Chain Analysis
Strategic stockpiling of fluorspar concentrates dominates over just-in-time preferences given China's and Mexico's captive mining concentration and input cost volatility. Supply draws from China, Japan, and Germany for resin compounding, with tetrafluoroethylene monomer, chlorodifluoromethane feedstock, and high-purity suspension polymerization equipment as critical inputs. Single-source vulnerability in fluorspar access creates structural risk for European and North American non-integrated producers. Distribution runs through direct mill relationships for semiconductor-grade resin and specialized distributors for industrial coating powders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: REACH Annex XVII and FDA 21 CFR 177.1550 compliance timelines create 14-18 month validation barriers that lock in qualified supplier relationships.
For Market Incumbents: Compound captive fluorspar access through backward integration into mining concessions or long-term offtake agreements with Mexican and Chinese concentrate producers. Expand Osaka and Suwon technical service co-location to capture wafer equipment OEM qualification timelines. Defend against Gujarat Fluorochemicals' import-substitution momentum in India's automotive bearing segment by accelerating modified grade FDA dual-certification on shared production lines. For New Entrants and Emerging Players: Anchor in India's PLI scheme for specialty chemicals as the most penetrable geography, targeting chlorodifluoromethane backward integration to supply Gujarat's compounding cluster. Pursue thin-film extrusion qualification for 300mm wafer handling components as the fastest-expanding white-space application. Lead with technical service co-location at Japanese and South Korean OEM facilities as the qualifying go-to-market mechanism. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated miner-to-resin producers with verified low-emission tetrafluoroethylene synthesis. Long-term viability over a five-to-ten-year window rests on regulatory compliance infrastructure rather than commodity scale. Prioritize acquisition targets with REACH Annex XVII documentation systems and FDA 21 CFR 177.1550 validation history. Monitor ECHA recycled content exemption rulings as the critical inflection signal for reprocessed resin economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive fluorspar mining in China and Mexico insulates Chemours and Daikin from merchant concentrate volatility. |
| Capacity Expansion | Osaka-based compounding facilities anchor Japanese semiconductor-grade resin supply for wafer processing equipment. |
| Long-term Supply Agreement | Direct mill relationships with South Korean wafer OEMs compress qualification timelines to 18 months. |
| Green Manufacturing Transition | Verified low-emission tetrafluoroethylene production positions European compounders for EU F-Gas carbon border adjustments. |
| Joint Venture | PLI scheme partnerships in Gujarat target chlorodifluoromethane feedstock control for India's largest fluoropolymer base. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, and ECHA regulatory submissions to validate supply concentration and pricing tier assumptions. Primary interviews with suspension polymerization plant managers, procurement leads at aerospace sealing OEMs, distribution channel partners, and technical R&D directors at compounding facilities informed operational cost structures and qualification timelines. Bottom-up resin volume estimates triangulated against top-down end-use demand modeling across electronics, aerospace, and automotive segments.
Segmentation dimensions modeled include resin grade tier, end-use industry, manufacturing stage, and regional production hub across the analysis window. CAGRs derive from elasticity-adjusted demand projections for 5G substrate deployment, semiconductor capital expenditure cycles, and automotive electric vehicle thermal management module adoption. Forecast inputs incorporate EPA TSCA compliance cost trajectories and REACH Annex XVII enforcement intensity assumptions.
Decision-makers should treat outputs as directional under sustained fluorspar supply concentration and REACH RoHS alignment on purity thresholds; material deviation in ECHA recycled content rulings or EU F-Gas Regulation extensions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
South America Epoxy Resins Market