
 United States Activated Carbon Market | 2026-2036
United States Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
United States Activated Carbon Market Outlook
Direct sales channels serving municipal water treatment authorities is narrowing as utilities consolidate procurement through regional cooperative purchasing agreements. Calgon Carbon Corporation leverages its vertical integration from raw material sourcing through reactivation services to sustain long-term contracts with major metropolitan water districts. Ingevity competes through specialized wood-based activated carbon formulations optimized for industrial air emission controls in the Ohio River Valley manufacturing corridor.
Activated carbon is a highly porous carbonaceous material produced from coconut shells, wood, coal, or peat through controlled pyrolysis and steam or chemical activation, achieving internal surface areas exceeding 1,000 square meters per gram for adsorbing contaminants from liquids and gases. Its primary industrial purpose centers on purifying drinking water, treating industrial wastewater, capturing volatile organic compounds from air streams, and decolorizing food and pharmaceutical products. Powdered activated carbon dominates municipal water treatment applications where rapid dispersion and high dosing flexibility offset shorter contact times, while granular activated carbon commands premium positioning in fixed-bed filtration systems for EPA-compliant surface water treatment plants. Extruded activated carbon occupies a specialized niche in industrial air purification where low pressure drop and uniform particle size distribution justify higher unit costs.
The EPA's Safe Drinking Water Act enforcement and pending PFAS maximum contaminant levels are reshaping product specifications, forcing suppliers to demonstrate NSF/ANSI 61 certification and enhanced iodine numbers for new municipal contract eligibility. OSHA permissible exposure limits for workplace air quality and the Department of Energy's industrial emissions guidelines further segment demand between standard reactivated carbon and virgin high-performance grades. Stakeholders must monitor regulatory rulemaking timelines and pre-position reactivation infrastructure ahead of anticipated compliance deadlines.
Market Dynamics
The EPA's pending PFAS maximum contaminant levels are compressing replacement cycles across municipal water systems, forcing utilities toward higher-iodine coconut shell grades and accelerating the obsolescence of legacy coal-based reactivated carbon inventories.
Growth Catalysts
- EPA PFAS Rulemaking:The Safe Drinking Water Act enforcement is mandating granular activated carbon upgrades in Midwest and Southeast utilities, creating specification-driven demand for NSF/ANSI 61 certified products.
- Texas Industrial Cluster Density:Petrochemical and refining operations along the Gulf Coast are expanding vapor recovery and wastewater treatment capacity, pulling substantial volumes of extruded activated carbon for emission controls.
- Coconut Shell Activation Advances:Steam activation process improvements are yielding surface areas exceeding 1,200 square meters per gram, enabling single-pass PFAS removal that reduces municipal operating costs.
Market Restraints
- Raw Material Concentration Risk:Premium coconut shell supply concentrates in Southeast Asian processing hubs, exposing US buyers to shipping cost volatility and tariff exposure.
- Coal-Based Carbon Obsolescence:Bituminous coal feedstock faces structural displacement as EPA specifications harden against trace heavy metal content, stranding reactivation infrastructure investments.
- Reactivation Service Bottlenecks:Thermal reactivation furnace capacity is geographically concentrated in Ohio and Pennsylvania, creating logistics constraints for coastal utilities seeking closed-loop carbon management.
Strategic Opportunities
- Ohio River Valley Manufacturing Corridor:Industrial air emission controls in chemical and metals processing present underpenetrated demand for specialized wood-based formulations optimized for VOC capture.
- Regional Cooperative Purchasing:Consolidated procurement through interlocal agreements in California and Texas is creating channel openings for suppliers offering integrated reactivation services.
- PFAS Destruction Integration:Convergence of granular activated carbon adsorption with supercritical water oxidation or plasma destruction technologies is enabling onsite regeneration and hazardous waste elimination.
Industry Challenges
- NSF/ANSI 61 Certification Timelines:Third-party testing and certification for new activated carbon formulations requires 12-18 month lead times, compressing product development windows ahead of compliance deadlines.
- Reactivation Furnace Emissions Compliance:Thermal reactivation operations face escalating EPA Maximum Achievable Control Technology standards for mercury and acid gas emissions, requiring substantial capex for pollution control retrofits.
- PFAS Analytical Capacity Scarcity:EPA Method 537.1 testing for trace PFAS compounds in spent carbon samples is bottlenecked at certified laboratories, delaying reactivation qualification and contract renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Activated Carbon Market |
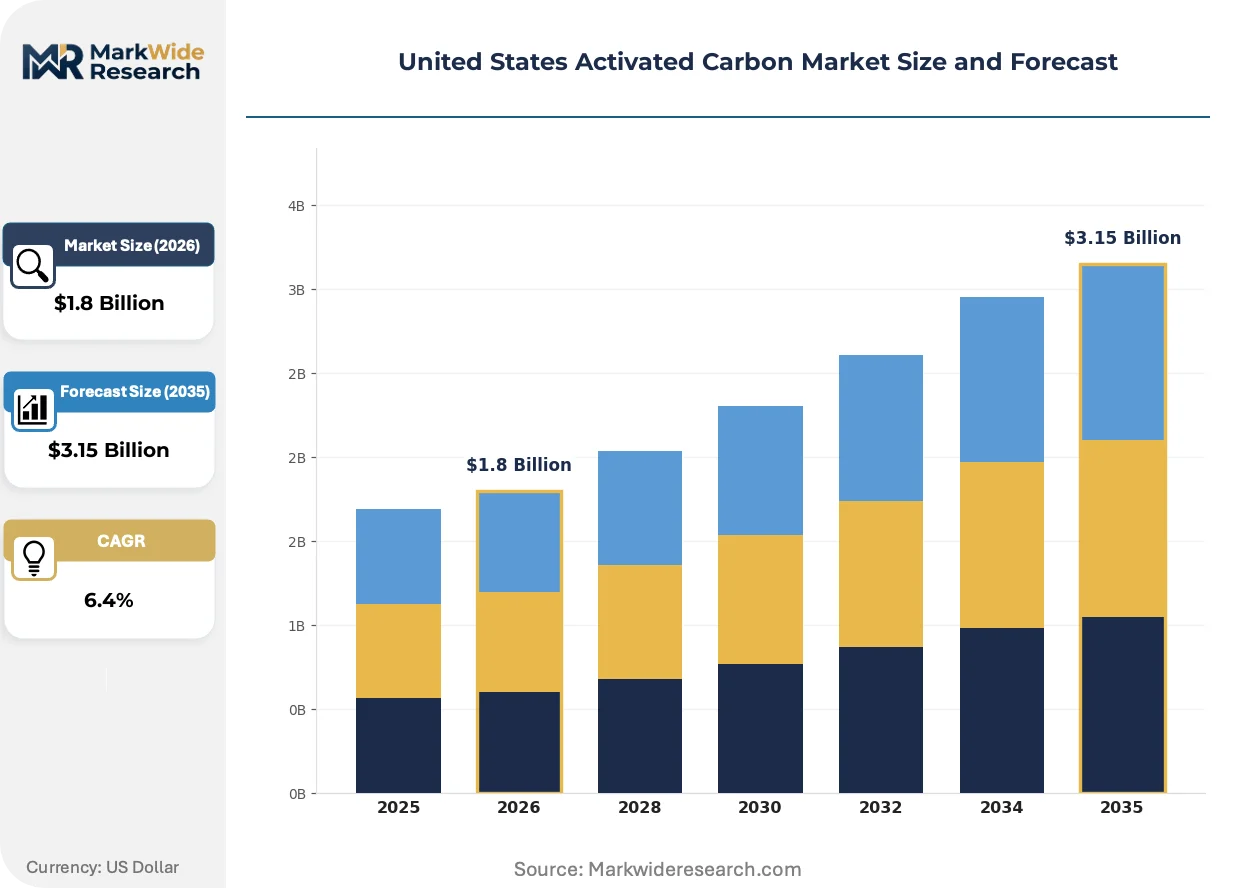
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Activated Carbon, Powdered Activated Carbon, Extruded Activated Carbon, Cocoanut Shell Activated Carbon Application: Water Treatment, Air Purification, Food & Beverage, Chemical Processing End User: Industrial, Commercial, Residential, Environmental Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Calgon Carbon Corporation, Carbon Activated Corporation, Ingevity, Cabot Corporation, Evoqua Water Technologies, Oxbow Activated Carbon, ADA Carbon Solutions, Donau Carbon U.S., Arq Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Activated Carbon Market Strategic Shifts
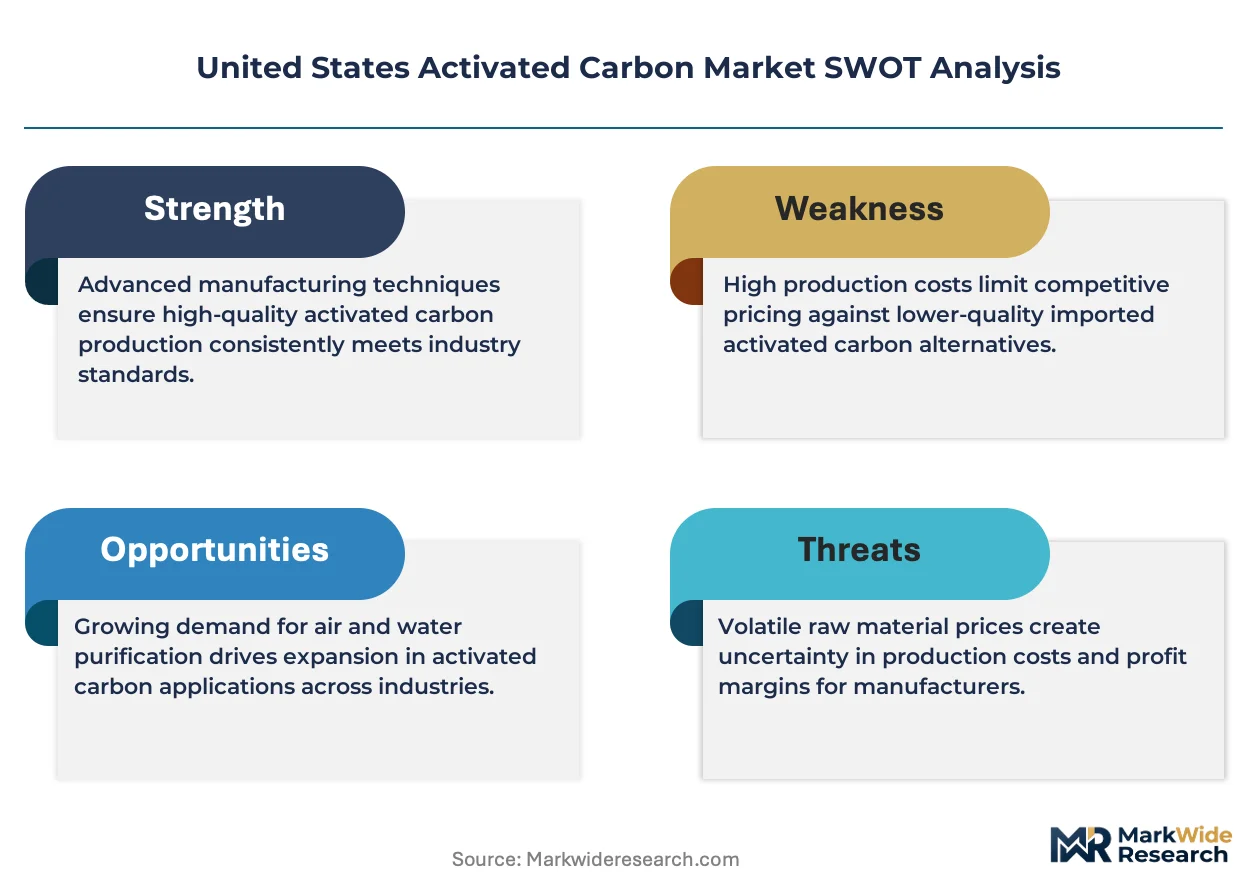
Activated carbon technology is hybridizing with advanced oxidation and destruction systems, shifting value capture from commodity adsorbent supply toward integrated contaminant management services.
Steam-activated coconut shell carbon with enhanced mesopore distribution is hybridizing with UV-photocatalytic regeneration systems. Municipal utilities in California are piloting these coupled technologies to extend carbon bed life and reduce hazardous waste generation. The structural consequence is compressing the addressable market for standalone virgin carbon resupply while expanding service-contract revenue pools.
The EPA's proposed PFAS National Primary Drinking Water Regulation is forcing surface water treatment plants toward continuous monitoring and predictive replacement scheduling. Industrial facilities in Ohio and Texas are pre-positioning higher-iodine inventory to avoid non-compliance exposure. Powdered activated carbon dosing systems are seeing accelerated retrofit demand as utilities seek operational flexibility ahead of final rule promulgation.
Regional cooperative purchasing agreements are consolidating municipal procurement authority across Texas, California, and Ohio metropolitan areas. Long-term supply contracts with integrated reactivation provisions are displacing spot-market carbon purchases in the largest water districts. This concentration is most visible in the Southeast, where rural utilities are ceding procurement autonomy to state-level purchasing cooperatives to access volume pricing and technical support.
United States Activated Carbon Market Segmentation
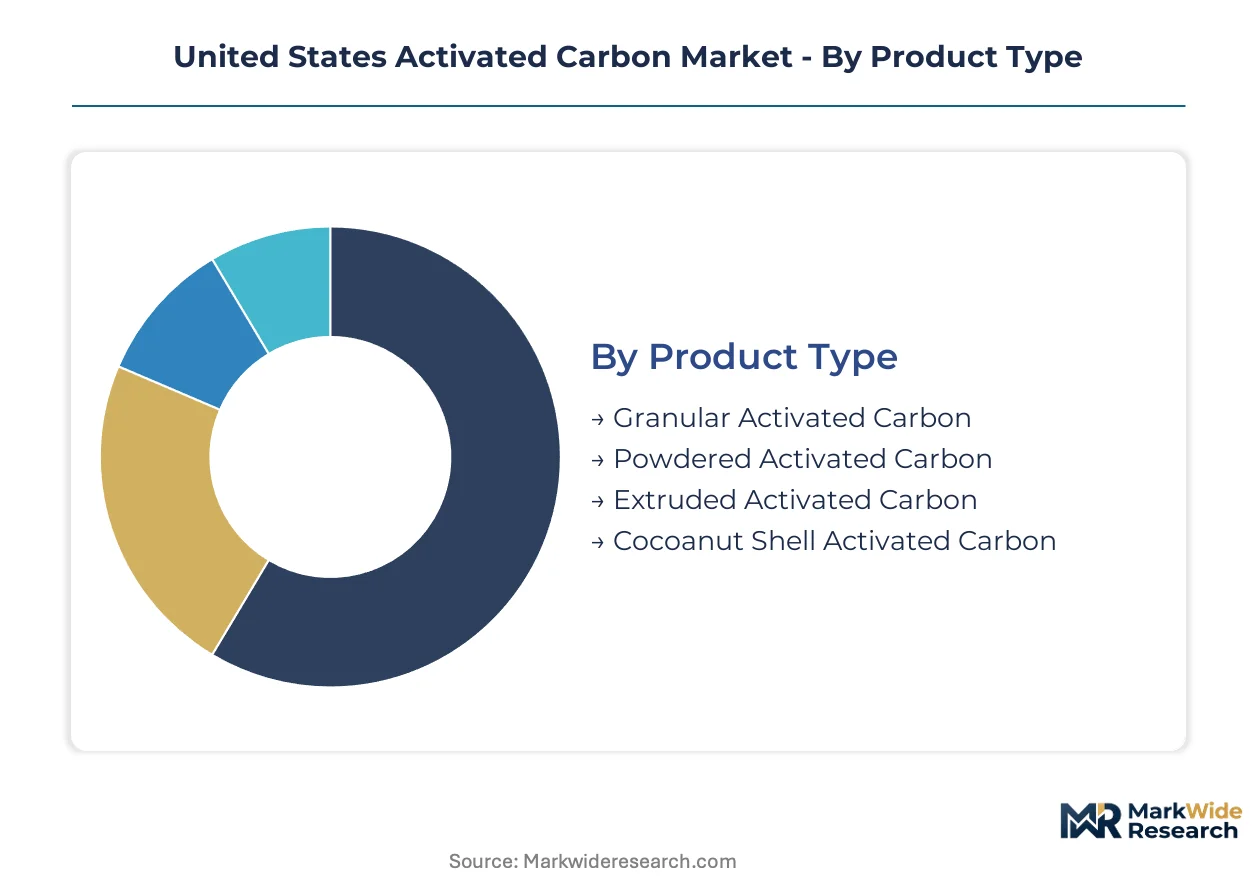
Activated carbon segmentation in the United States reflects divergent technical specifications across EPA compliance mandates, industrial process requirements, and channel consolidation trends. Product form factor determines reactivation economics and replacement cadence, while application verticals concentrate demand in water-stressed geographies and petrochemical corridors.
Product Type:
Use-case spectrum spans fixed-bed filtration systems requiring mechanical durability through rapid-dose applications prioritizing dispersion speed.
- Granular Activated Carbon:Irregular particle structure engineered for fixed-bed adsorption columns with controlled pressure drop characteristics. Municipal water utilities in Texas and Ohio are specifying higher-iodine GAC grades to meet pending EPA PFAS maximum contaminant levels, compressing replacement cycles from 36 to 18 months.
- Powdered Activated Carbon:Pulverized particle distribution below 0.18 millimeters enables rapid dispersion for seasonal taste-and-odor events or emergency contaminant spikes. Southeast utilities facing algal bloom seasonality are expanding PAC dosing infrastructure ahead of surface water treatment rule enforcement.
- Extruded Activated Carbon:Cylindrical pellet geometry minimizes pressure drop in vapor-phase applications across Gulf Coast petrochemical facilities.
- Cocoanut Shell Activated Carbon:Steam-activated lignocellulosic precursor delivers mesopore dominance optimized for trace organic removal in California groundwater remediation.
Established volume favors granular configurations; emerging adoption favors coconut shell grades.
Application:
Cost tier stratification separates capital-intensive municipal infrastructure from operational expenditure-driven industrial maintenance cycles.
- Water Treatment:Surface water filtration, groundwater remediation, and wastewater discharge compliance consume the majority of domestic activated carbon volume. Midwest utilities confronting agricultural runoff and legacy industrial contamination are accelerating GAC filter upgrades ahead of EPA enforcement deadlines.
- Air Purification:Volatile organic compound capture from industrial processes, indoor air quality management, and vapor recovery systems. Ohio River Valley chemical manufacturers are retrofitting carbon canister systems to meet OSHA permissible exposure limits for benzene and toluene.
- Food & Beverage:Decolorization of sweeteners, purification of edible oils, and alcohol filtration for product quality consistency.
- Chemical Processing:Catalyst support, solvent recovery, and product purification in specialty chemical and pharmaceutical synthesis.
Municipal water treatment commands procurement scale; industrial air purification is climbing the fastest.
End User:
Customer type determines specification rigor, with environmental compliance mandates forcing premium grade adoption against cost-sensitive commercial maintenance cycles.
- Industrial:Petrochemical refining, metals processing, and chemical manufacturing operations with continuous emission monitoring requirements. Texas Gulf Coast facilities are pre-positioning extruded carbon inventory to avoid vapor recovery system downtime during hurricane season supply disruptions.
- Commercial:Food production, beverage bottling, and hospitality operations with periodic carbon replacement schedules. Restaurant chains and brewing operations in California are consolidating procurement through regional cooperative agreements to access NSF-certified product volumes.
- Residential:Point-of-use filtration devices and whole-home water treatment systems.
- Environmental:Superfund site remediation, landfill leachate treatment, and emergency spill response contracting.
Industrial contracts anchor supplier manufacturing schedules; environmental remediation projects show the steepest specification escalation.
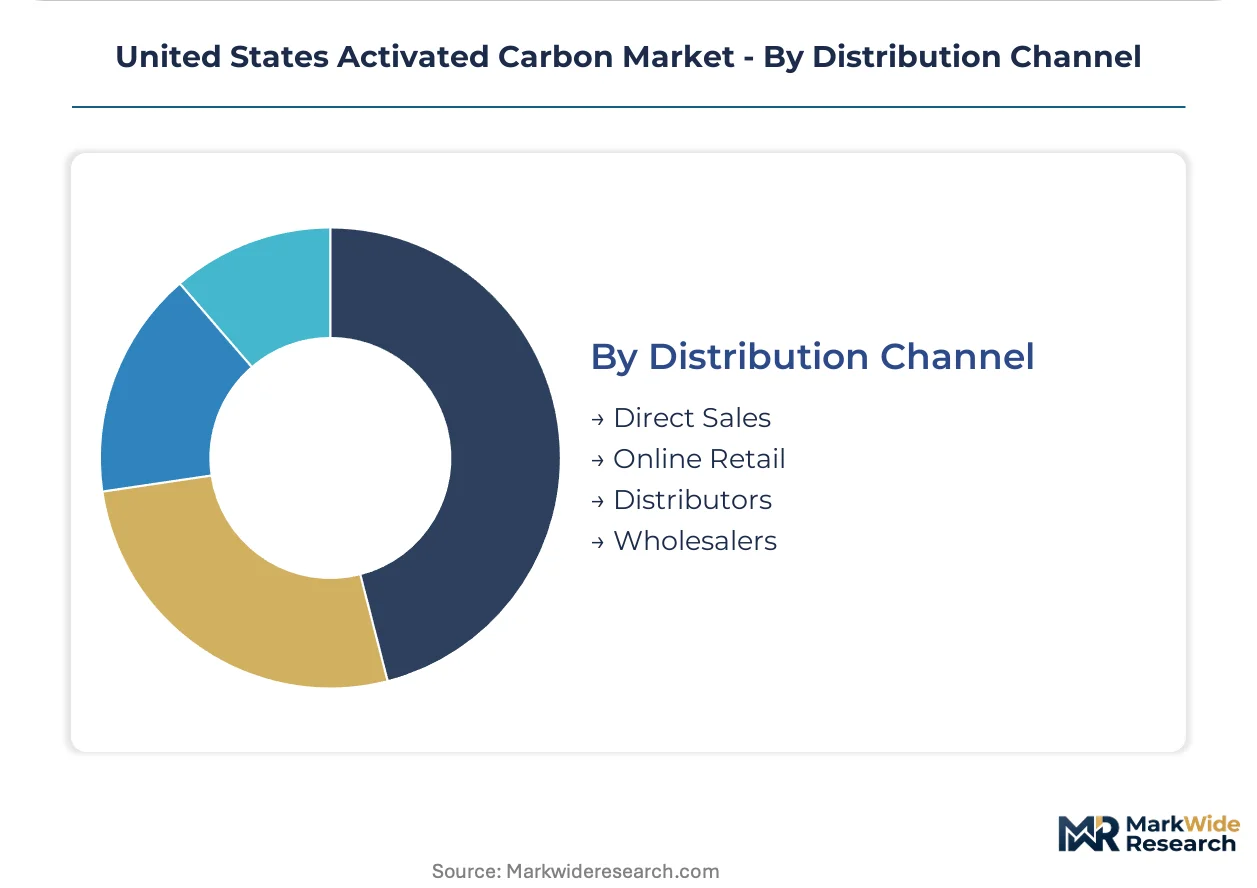
Distribution Channel:
Supply concentration in reactivation infrastructure is reshaping channel economics toward integrated service contracts and away from transactional spot purchasing.
- Direct Sales:Long-term supply agreements with municipal water authorities and industrial accounts specifying reactivation service inclusion. Metropolitan water districts in California and Texas are consolidating procurement through direct negotiations with vertically integrated suppliers offering closed-loop carbon management.
- Distributors:Regional inventory positioning for maintenance, repair, and operations purchasing across fragmented commercial and small industrial accounts.
- Online Retail:E-commerce platforms serving residential point-of-use filter replacements and small commercial maintenance orders.
- Wholesalers:Bulk volume aggregation for downstream redistribution to contractors and specialized system integrators.
Direct sales capture municipal infrastructure investment; distributor networks retain commercial maintenance flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage tilts toward Gulf Coast utilities with integrated reactivation access, while Midwest rural districts absorb freight premiums on spot-market deliveries. This asymmetry is widening as regional cooperative purchasing consolidates procurement authority in Texas and California.
Texas
Petrochemical corridor expansion along the Houston Ship Channel and Corpus Christi industrial complex is pulling extruded activated carbon volumes for vapor recovery systems. EPA Region 6 enforcement of refinery emission standards is tightening benzene capture requirements. Port Arthur and Beaumont refineries are pre-positioning carbon inventory ahead of hurricane season supply disruptions.
California
Groundwater remediation in the Central Valley and PFAS contamination in Orange County municipal systems are driving coconut shell grade specification upgrades. State Water Resources Control Board mandates for 1,2,3-TCP and PFAS treatment are compressing replacement cycles. Los Angeles and San Diego metropolitan water districts are consolidating procurement through the California Urban Water Agencies cooperative.
Ohio
Ohio River Valley chemical manufacturing and metals processing operations are retrofitting carbon canister systems for VOC capture. OSHA permissible exposure limits for toluene and xylene are forcing industrial air quality upgrades. Cincinnati and Cleveland municipal utilities are accelerating GAC filter replacements ahead of EPA Safe Drinking Water Act enforcement deadlines.
Southeast
Algal bloom seasonality in Florida and Georgia surface water systems is expanding powdered activated carbon dosing infrastructure. EPA pending PFAS maximum contaminant levels are forcing rural utilities toward regional cooperative purchasing agreements. Atlanta and Charlotte metropolitan water authorities are specifying higher-iodine coconut shell grades for combined taste-and-odor and trace organic removal.
Midwest
Agricultural runoff contamination and legacy industrial sites in Illinois and Michigan are driving groundwater remediation demand. EPA Region 5 enforcement of surface water treatment rules is mandating granular activated carbon upgrades in Chicago and Detroit metropolitan systems. Aging infrastructure in Milwaukee and Minneapolis-St. Paul is creating simultaneous pull from municipal compliance and industrial process applications.
United States Activated Carbon Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on feedstock and activation technology. The United States activated carbon market structures around three tiers: multinational chemical conglomerates with captive carbon divisions, independent reactivation service operators, and regional virgin carbon fabricators. Consolidation pressure concentrates in the reactivation services layer, where furnace capacity scarcity is driving partnership formations between utilities and integrated suppliers. Geographic expansion into coastal markets and backward integration into coconut shell sourcing represent the dominant competitive vectors.
Among established reactivation service providers, Calgon Carbon Corporation and Ingevity occupy positions exemplifying the vertically integrated archetype, combining raw material sourcing through closed-loop carbon management. Carbon Activated Corporation represents the independent fabricator tier focused on virgin carbon production and regional distribution networks. These three entities anchor the competitive structure, with Calgon Carbon Corporation leveraging long-term municipal contracts and Ingevity competing through specialized formulation capabilities in industrial air emission applications.
| Leading Market Players |
|---|
| Calgon Carbon Corporation |
| Carbon Activated Corporation |
| Ingevity |
| Cabot Corporation |
| Evoqua Water Technologies |
| Oxbow Activated Carbon |
| ADA Carbon Solutions |
| Donau Carbon U.S. |
| Arq Limited |
| Others |
Value Chain & Pricing Dynamics
Long Beach port congestion and inland rail bottlenecks amplify cost differentials between coconut shell imports from Southeast Asian processing hubs and domestic coal-based reactivation services, concentrating pricing power with vertically integrated suppliers while fragmenting procurement leverage among coastal utilities lacking furnace access.
Pricing Analysis
Configured-to-order pricing for NSF/ANSI 61 certified coconut shell grades commands spreads exceeding standard coal-based reactivated carbon by factors tied to iodine number certification and mercury content guarantees. Contract-based long-term offtake dominates municipal procurement through regional cooperative agreements, compressing spot-market premiums. Price differentiation rests on certification grade and geographic delivery cost, with Ohio River Valley utilities absorbing freight premiums against Gulf Coast buyers with integrated reactivation access. Cost compression in standard reactivated tiers is intensifying because coal-based inventory faces EPA specification obsolescence. Small commercial food and beverage processors exhibit highest price sensitivity; metropolitan water districts with federal compliance mandates show lowest.
Supply Chain Analysis
Contract manufacturing concentration among thermal reactivation furnace operators in Ohio and Pennsylvania anchors domestic closed-loop carbon management capacity, with Calgon Carbon Corporation and Ingevity controlling majority furnace infrastructure. Geographic supply concentrates in Indonesia, Sri Lanka, and the Philippines for premium coconut shell feedstock, while bituminous coal sourcing draws from Pennsylvania and West Virginia mines. Raw material dependencies rest on steam activation energy inputs, chemical impregnation reagents, and specialized furnace refractories. Tariff exposure on Southeast Asian carbon imports constitutes the primary supply chain risk. Distribution runs through direct sales channels for municipal accounts, with regional distributors retaining commercial and industrial maintenance flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against advanced oxidation processes and membrane filtration technologies that threaten granular activated carbon's dominance in PFAS treatment applications.
For Market Incumbents: Entrench position through captive reactivation furnace capacity additions in Texas and California coastal corridors, offsetting logistics constraints that disadvantage competitors. Secure long-term coconut shell supply agreements with Indonesian and Sri Lankan processors before tariff escalation. Prioritize NSF/ANSI 61 certification maintenance as EPA rulemaking tightens municipal eligibility requirements. For New Entrants and Emerging Players: Pursue white-space opportunities in industrial air emission controls across the Ohio River Valley manufacturing corridor, where specialized wood-based formulations for VOC capture remain underpenetrated. Target environmental remediation contractors serving Superfund sites with mobile carbon exchange services. Differentiate through integrated PFAS destruction technology partnerships rather than commodity carbon supply. For Investors and Strategic Acquirers: EPA's pending PFAS National Primary Drinking Water Regulation reshapes the acquisition landscape toward reactivation infrastructure assets with coastal geographic positioning. Long-term viability favors furnace operators with pollution control retrofit completion and closed-loop municipal contracts. Monitor reactivation furnace emissions compliance capex burdens as inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Reactivation Furnace Capacity Expansion | Ohio and Pennsylvania furnace additions reduce coastal logistics premiums for municipal utilities. |
| Backward Integration into Coconut Shell Sourcing | Indonesian and Sri Lankan supply agreements insulate against tariff volatility on premium grades. |
| PFAS Destruction Technology Partnership | Supercritical water oxidation integration extends service-contract revenue beyond commodity carbon. |
| NSF/ANSI 61 Certification Investment | Third-party testing completion maintains municipal contract eligibility under tightening EPA rules. |
| Regional Cooperative Purchasing Alignment | California and Texas interlocal agreements consolidate procurement authority for volume pricing access. |
Study Parameters
A standing panel of municipal water utility procurement directors, industrial environmental compliance officers, reactivation furnace operations managers, and activated carbon distribution channel heads provided ongoing calibration against secondary validation. Primary interviews combined with EPA rulemaking dockets, NSF certification databases, customs import records, and SEC filings from publicly traded chemical conglomerates. Bottom-up volume triangulation across product grades and top-down value reconciliation against end-use expenditure patterns anchored the analytical framework.
Scenario-bracketing around EPA PFAS rulemaking timelines and coconut shell supply disruption probabilities framed the projection horizon. Segmentation dimensions spanned product form factor, application vertical, end-user compliance tier, and regional procurement concentration. CAGRs derived from installed base replacement cycle compression and specification upgrade intensity across the modeling period. Forecast inputs incorporated reactivation furnace capacity utilization rates and third-party certification backlog durations.
Sensitivities concentrate around EPA rulemaking acceleration, Southeast Asian supply chain disruptions, and reactivation furnace emissions compliance capex escalation. Quarterly review of NSF certification approval timelines, spent carbon laboratory testing backlogs, and regional cooperative purchasing formation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Activated Carbon Filter Market
Filters
Europe Industrial Air Filtration Market
Filters
Respirator Cartridges and Filters Market
Filters
Canada Filtration and Separation Market
Filters
Global High Temperature Filters Market
Filters
Global Filter Market
Filters
Single-Use Filtration Assemblies Market
Filters
Residential Filters Market
Filters
Compact Filters Market
Filters
Fabric Filters Market
Filters
Global Baghouse Filters Market
Filters
Global Filtration and Contamination Control Market
Filters
Filters and Particle Monitoring Market
Filters
Global Sterile Filtration Market
Filters
Filter Bag Market
Filters
Color Filter Glass Market