
 North America Gas Filtration Media Market | 2026-2036
North America Gas Filtration Media Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gas Filtration Media Market Analytics
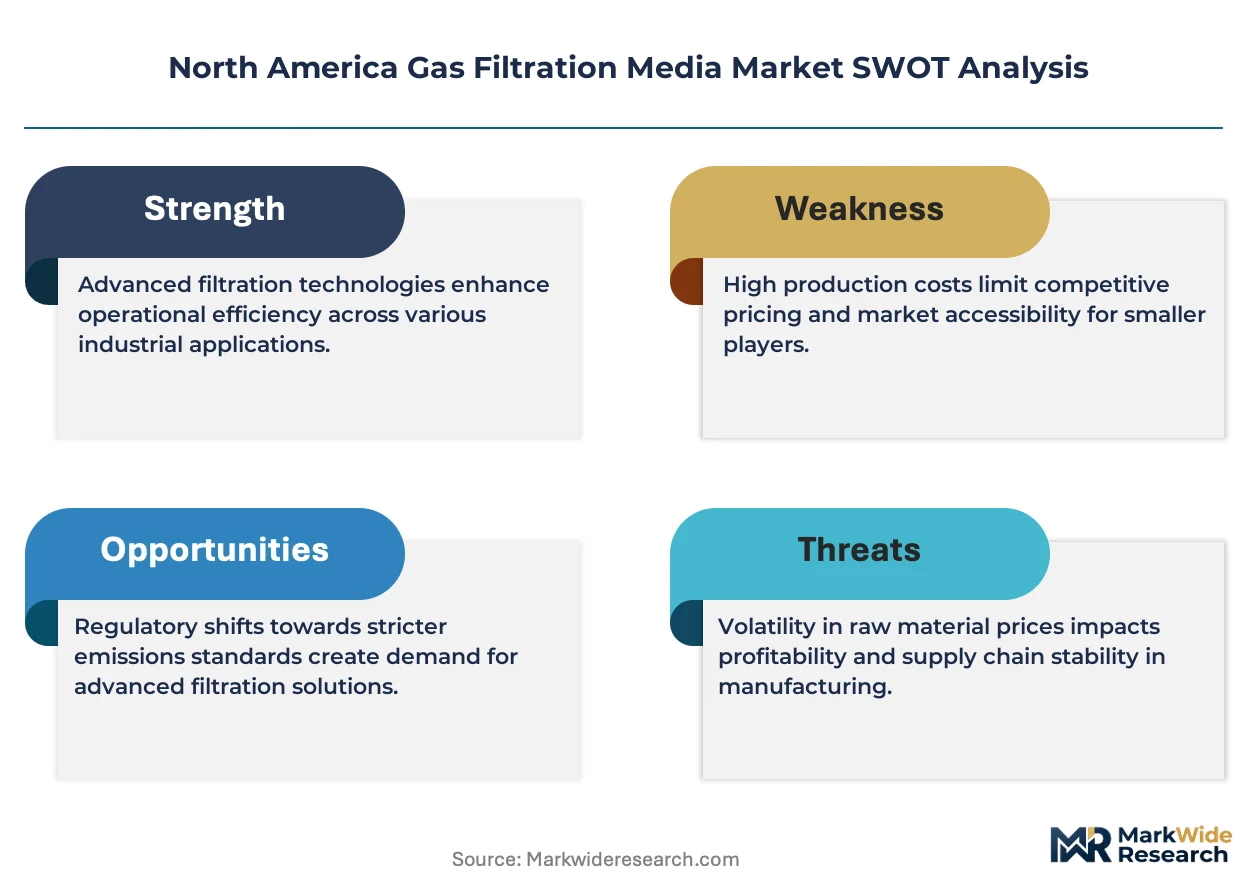
The EPA's Mercury and Air Toxics Standards is consolidating demand for high-performance gas filtration across North American power generation and industrial boiler operators. 3M Company leverages its deep materials science portfolio to sustain technology leadership in synthetic fiber media for extreme-temperature applications. Pall Corporation anchors its position through specialized membrane and sorbent technologies serving pharmaceutical and chemical processing facilities. Graver Technologies competes with differentiated ceramic and metallic filter solutions targeting refinery and petrochemical end users.
Gas filtration media encompasses engineered porous materials designed to capture particulate matter, acid gases, volatile organic compounds, and toxic metal vapors from industrial exhaust streams, typically achieving removal efficiencies from 95% to 99.97% depending on media configuration and operating conditions. Fiberglass media dominates high-temperature power generation applications due to thermal stability exceeding 260°C, while synthetic media variants are gaining traction in automotive and commercial HVAC systems where moisture resistance and mechanical durability prove critical. Activated carbon segments command premium positioning in mercury and dioxin control applications where impregnated chemisorbent formulations justify higher unit economics against baseline particulate filters.
The EPA enforces National Ambient Air Quality Standards that directly mandate filtration performance thresholds for stationary sources, while OSHA's permissible exposure limits for industrial air contaminants shape workplace ventilation specifications across manufacturing end users. State-level regulators including the California Air Resources Board impose supplemental requirements that exceed federal baselines, particularly for refinery and chemical processing facilities operating in the Los Angeles Basin and San Francisco Bay Area. Stakeholders must monitor evolving particulate matter designations and emerging per- and polyfluoroalkyl substances restrictions that could force reformulation of synthetic media coatings and binder chemistries.
Market Dynamics
The EPA's Mercury and Air Toxics Standards is compressing replacement cycles for legacy sorbent systems across coal-fired power generation and industrial boiler installations. Utilities face simultaneous pressure from state-level ambient air mandates and asset-aging infrastructure, forcing coordinated capital planning around filtration media procurement.
Growth Catalysts
- MATS compliance deadlines:Stationary sources must upgrade mercury capture systems, driving demand for impregnated activated carbon and specialized sorbent blends in high-temperature flue gas streams.
- Texas Gulf Coast industrial clustering:Petrochemical capacity expansions near Houston and Corpus Christi concentrate demand for ceramic and metallic filtration media resistant to corrosive process gases.
- Fiberglass thermal stability advances:Reformulated binder chemistries now sustain continuous operation above 260°C, extending service intervals in coal and biomass power generation applications.
Market Restraints
- Petroleum pitch supply concentration:Activated carbon precursor materials face pricing volatility tied to refinery output decisions in the US Gulf Coast region.
- High-temperature ceramic media manufacturing:Domestic production capacity for silicon carbide and aluminosilicate filters remains concentrated among a limited supplier base.
- Per- and polyfluoroalkyl substances restrictions:Emerging state-level bans on PFAS chemistries threaten synthetic media coatings and PTFE membrane formulations.
Strategic Opportunities
- Mexico manufacturing corridor expansion:Nearshoring of automotive and appliance production creates demand for industrial HVAC filtration media in Monterrey and Tijuana industrial parks.
- Hydrogen economy pilot projects:Carbon capture and hydrogen production facilities require novel filtration media for syngas purification and CO2 separation processes.
- California Air Resources Board refinery rules:Supplementary emissions controls in the Los Angeles Basin and San Francisco Bay Area mandate premium sorbent formulations.
Industry Challenges
- Materials science talent scarcity:Formulation chemists with expertise in high-temperature ceramic binders and impregnated carbon surface chemistry command premium compensation.
- Legacy boiler integration complexity:Retrofitting MATS-compliant filtration into pre-1990s power generation infrastructure requires custom engineering and extended outage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gas Filtration Media Market |
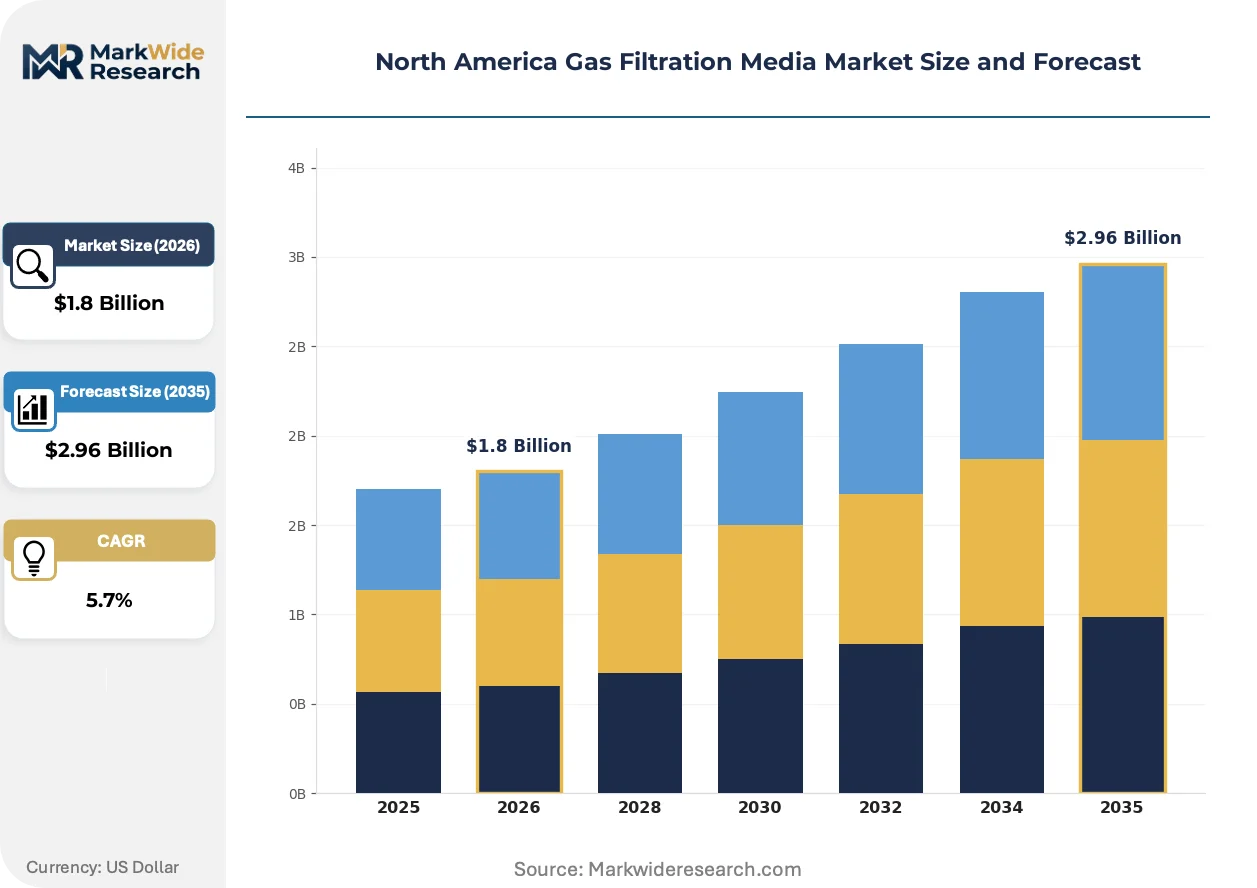
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Electrostatic Precipitators, Panel Filters Application: Industrial Filtration, Commercial HVAC, Automotive, Laboratories Material: Fiberglass, Polyester, Cellulose, Synthetic Media End User: Manufacturing, Healthcare, Transportation, Power Generation |
| Companies Covered | Porous Media Corporation, SPX FLOW, Graver Technologies, 3M Company, Pall Corporation, HYDAC International, Delta Pure Filtration, Ahlstrom-Munksjö, Purolator Advanced Filtration, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gas Filtration Media Market Evolving Landscape
Digital process control and advanced materials science are converging to reshape how filtration media is specified, monitored, and replaced across North American industrial infrastructure. Three developments are compressing traditional procurement cycles and redefining performance benchmarks.
Smart sensor-embedded filtration media is automating condition-based replacement scheduling in power generation and chemical processing facilities. Embedded pressure-drop and particulate-loading sensors transmit real-time data to plant distributed control systems. Duke Energy and ExxonMobil refineries have piloted these systems, reducing unplanned outage frequency and compressing maintenance labor allocation.
The EPA's updated National Ambient Air Quality Standards for fine particulate matter is tightening allowable emissions thresholds for stationary sources. Industrial boiler operators must now achieve sub-5 mg/m³ stack concentrations, forcing adoption of multi-stage filtration configurations. Texas and Ohio manufacturing facilities are responding by layering ceramic pre-filters with final-stage membrane elements.
Consolidated procurement through integrated facility management contractors is displacing direct OEM relationships among mid-sized chemical processors. Sodexo and Aramark service agreements now bundle filtration media supply with predictive maintenance analytics. This pattern concentrates purchasing power in the US Midwest chemical corridor and compresses margins for specialty media distributors.
North America Gas Filtration Media Market Segmentation
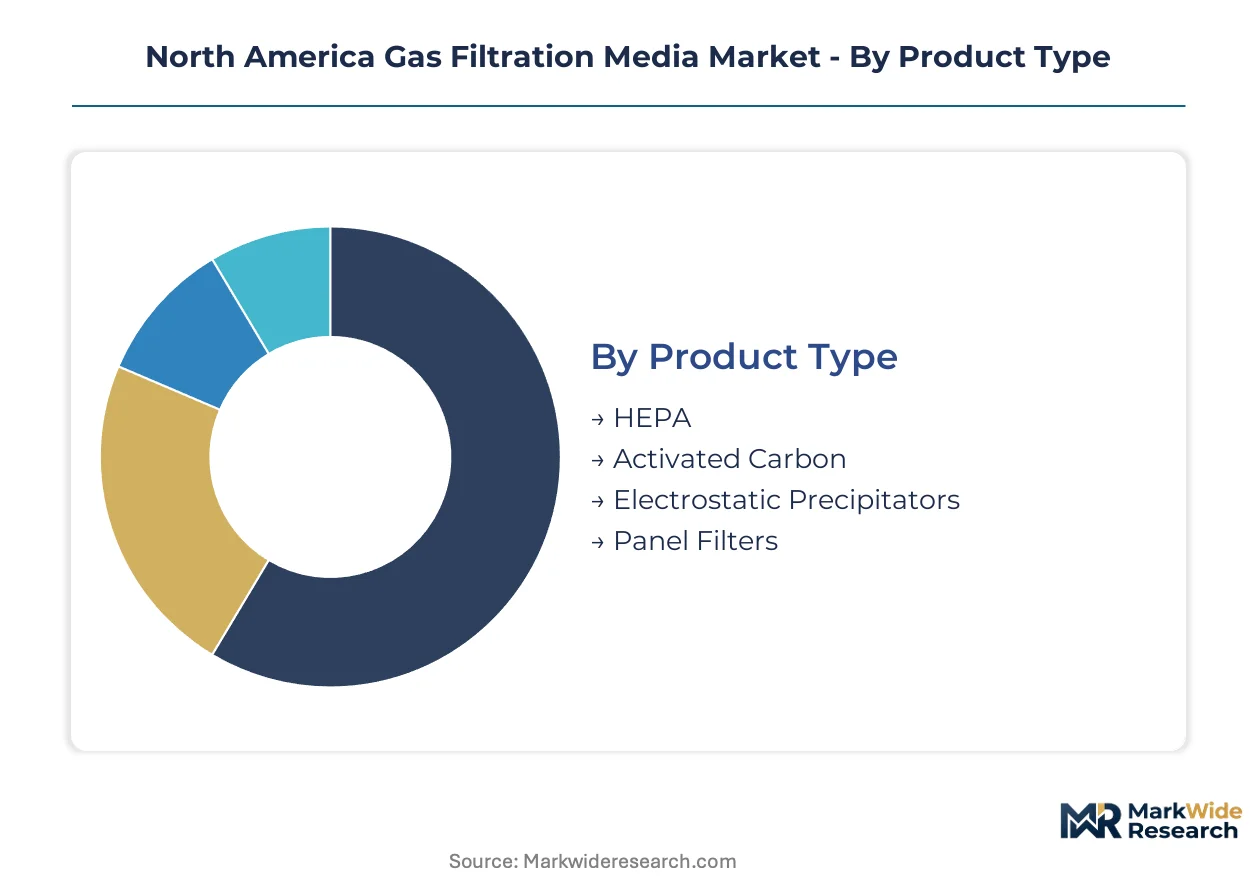
Gas filtration media segmentation reveals distinct performance tiers across material chemistry, application intensity, and regulatory exposure. Procurement patterns diverge sharply between commodity replacement cycles and engineered systems requiring custom formulation.
Product Type:
Volume concentration sits in standard panel and electrostatic systems, while premium capture belongs to specialized HEPA and impregnated carbon formulations.
- HEPA:Constructed from sub-micron glass or synthetic fibers achieving 99.97% efficiency at 0.3 microns. Demand concentrates in pharmaceutical cleanrooms across New Jersey and North Carolina research corridors where FDA aseptic processing mandates drive specification. Replacement cycles compress under continuous operation protocols.
- Activated Carbon:Derived from petroleum pitch or coconut shell precursors with impregnated chemisorbent surface modifications. Texas Gulf Coast refineries and coal-fired utilities in Ohio and Pennsylvania deploy these for mercury and VOC capture under EPA MATS compliance deadlines. Supply volatility in precursor materials constrains procurement flexibility.
- Electrostatic Precipitators:Ionization-based particulate removal systems common in heavy industrial boiler applications.
- Panel Filters:Pleated cellulose or synthetic media for low-pressure commercial HVAC systems.
Mature deployment sits with Panel Filters. Newer deployment is concentrated in Activated Carbon.
Application:
Application segmentation tracks regulatory intensity, with industrial and laboratory environments commanding engineered solutions while commercial HVAC operates on cost-optimized replacement schedules.
- Industrial Filtration:High-temperature ceramic and metallic media configurations handling corrosive process streams above 260°C. Petrochemical clusters along the Texas Gulf Coast and Great Lakes chemical corridor drive specification for silicon carbide and aluminosilicate formulations. OSHA permissible exposure limits shape workplace ventilation procurement.
- Laboratories:HEPA and ULPA-grade containment systems for biosafety level 2 and 3 facilities. Boston-Cambridge pharmaceutical research concentration and San Diego biotech corridor sustain demand for validated filter integrity testing protocols. FDA 21 CFR Part 11 compliance requirements extend procurement lead times.
- Commercial HVAC:Standard efficiency filtration for office and retail building mechanical systems.
- Automotive:Cabin air and powertrain ventilation media for manufacturing and aftermarket channels.
Commercial HVAC represents the highest-volume replacement cycle. Laboratories claim the steepest expansion trajectory.
Material:
Material selection trades thermal stability against moisture resistance and mechanical durability across operating environments.
- Fiberglass:Borosilicate glass microfiber matrices with thermal stability exceeding 260°C continuous operation. Coal and biomass power generation facilities in the Midwest and Southeast specify these for flue gas particulate control. Reformulated binder chemistries now extend service intervals under acid gas exposure.
- Synthetic Media:Polypropylene, PTFE, and composite fiber constructions offering moisture resistance and mechanical resilience. Automotive underhood applications and pharmaceutical processing facilities favor these for pulse-clean compatibility and chemical inertness. Emerging PFAS restrictions threaten PTFE membrane formulations in California and New York.
- Polyester:Spunbond and meltblown configurations for standard industrial dust collection.
- Cellulose:Cost-optimized pleated media for low-temperature commercial and residential applications.
Cellulose dominates unit volume in price-sensitive segments. Synthetic Media is gaining share fastest in performance-critical applications.
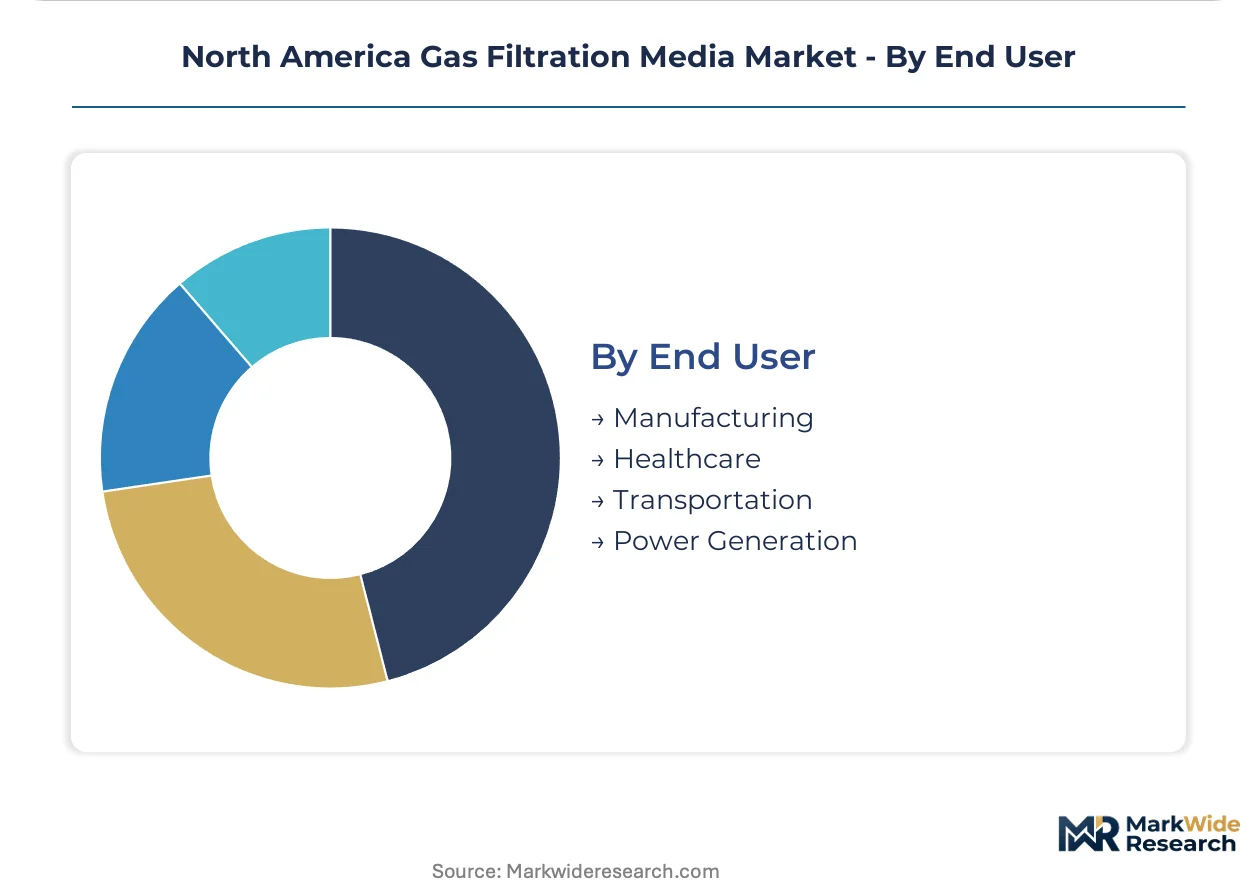
End User:
End user segmentation reflects divergent procurement authority, with centralized utility engineering teams versus fragmented manufacturing maintenance operations.
- Power Generation:Centralized procurement of high-temperature filtration media for coal, natural gas, and biomass combustion systems. EPA MATS compliance deadlines compress replacement cycles for legacy sorbent installations across Ohio River Valley and Southwest generating stations. Integrated resource planning coordinates outage windows with media procurement.
- Manufacturing:Dispersed maintenance organizations across automotive, food processing, and metal fabrication facilities. California Air Resources Board refinery rules and Midwest OSHA enforcement patterns create geographic variation in specification intensity. Consolidated facility management contracts concentrate purchasing power among mid-sized chemical processors.
- Healthcare:Hospital HVAC and surgical suite filtration systems.
- Transportation:Aviation, rail, and marine cabin air applications.
Healthcare maintains the most standardized specification protocols. Manufacturing exhibits the widest regional variation in compliance-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates regional consumption while Canada supplies specialized precursor materials. Mexico's manufacturing corridor is emerging as a demand growth vector. Cross-border supply chains link Texas Gulf Coast petrochemical clusters with Ontario-based activated carbon feedstock operations.
United States
Coal-fired power retrofits and refinery emissions controls drive specification intensity. EPA Mercury and Air Toxics Standards compress replacement cycles for legacy sorbent installations across Ohio River Valley generating stations. Texas Gulf Coast industrial clusters near Houston and Corpus Christi concentrate demand for ceramic and metallic filtration media resistant to corrosive process gases.
Canada
Petroleum pitch and coconut shell precursor supply anchors activated carbon production. Health Canada and Environment and Climate Change Canada enforce stationary source emissions guidelines that align with US EPA thresholds. Alberta's oil sands operations and Ontario's chemical processing corridor sustain demand for high-temperature filtration systems.
Mexico
Nearshoring of automotive and appliance manufacturing creates industrial HVAC filtration demand. SEMARNAT's emissions regulations for stationary sources tighten compliance requirements in Monterrey and Tijuana industrial parks. The Bajío Region's expanding aerospace and automotive supplier base drives specification for synthetic media in clean manufacturing environments.
North America Gas Filtration Media Market Competitive Landscape
The competitive structure tilts toward diversified materials science conglomerates with filtration divisions. Tiered specialization separates high-temperature ceramic and metallic media fabricators from standardized HVAC replacement suppliers. Three archetypes dominate: integrated conglomerates leveraging cross-divisional R&D, specialized filtration pure-plays, and diversified industrial manufacturers with captive media operations. Capacity expansion in high-temperature ceramic segments and strategic partnerships for PFAS-compliant synthetic formulations represent the dominant competitive moves.
Within the integrated conglomerate tier, 3M Company and Pall Corporation exemplify materials science depth applied to extreme-temperature and membrane applications. Graver Technologies occupies a position among specialized ceramic and metallic filtration fabricators serving corrosive industrial process streams. These three anchors represent distinct strategic postures: broad synthetic fiber and sorbent portfolios, specialized membrane and validation capabilities, and differentiated refractory metal and ceramic solutions respectively.
| Leading Market Players |
|---|
| Porous Media Corporation |
| SPX FLOW |
| Graver Technologies |
| 3M Company |
| Pall Corporation |
| HYDAC International |
| Delta Pure Filtration |
| Ahlstrom-Munksjö |
| Purolator Advanced Filtration |
| Others |
Value Network & Pricing Analysis
Reformulated high-temperature binder chemistries now sustaining continuous operation above 260°C simultaneously compress manufacturing cost curves and consolidate production capability among US-based specialty ceramic fabricators. This dual effect reshapes procurement economics for coal-fired utilities and Texas Gulf Coast petrochemical operators facing synchronized EPA compliance deadlines and infrastructure aging.
Pricing Analysis
Margin tightening in impregnated activated carbon reflects petroleum pitch precursor volatility tied to Gulf Coast refinery output decisions. Three-tier pricing structure across premium impregnated formulations, standard activated carbon, and commodity cellulose alternatives separates buyers by mercury capture efficiency requirements and MATS compliance urgency. Consolidated facility management contracts at Midwest chemical processors concentrate purchasing power and accelerate cost-down pressure on specialty media distributors. Power generation utilities exhibit lowest price sensitivity due to regulatory non-compliance penalties, while mid-sized manufacturing maintenance organizations prioritize unit cost minimization over performance tier.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility procurement, while specialty distributors serve fragmented manufacturing maintenance operations. Raw material supply concentrates in the United States for fiberglass and synthetic fiber media, Canada for petroleum pitch and coconut shell activated carbon precursors, and Mexico for nearshored automotive HVAC component integration. Ceramic and metallic filtration media production draws from limited domestic silicon carbide and aluminosilicate manufacturing capacity. Single-source vulnerability in high-temperature ceramic binder chemistries creates procurement risk for refinery and power generation end users. Distribution runs through integrated facility management contractors consolidating mid-sized chemical processor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over activated carbon precursor supply and downstream captive service contracts determine margin capture. Players are pursuing backward integration into petroleum pitch refining and synthetic fiber polymer production.
For Market Incumbents: Acquire ceramic precursor mining and processing assets to secure silicon carbide and aluminosilicate supply against limited domestic manufacturing capacity. Consolidate regional distribution networks serving Texas Gulf Coast petrochemical clusters to defend position against integrated facility management contractor displacement. PFAS chemistry restrictions in California and New York threaten synthetic media formulations; certification investment in fluorine-free alternatives represents critical defensive R&D allocation. For New Entrants and Emerging Players: Smart sensor-embedded filtration media with predictive replacement analytics offers technology-first entry into power generation and chemical processing facilities piloting condition-based maintenance. Mexico's Monterrey and Tijuana industrial parks present underpenetrated white-space for industrial HVAC filtration media serving nearshored automotive and appliance manufacturing. California Air Resources Board refinery rules mandate premium sorbent formulations in Los Angeles Basin and San Francisco Bay Area, creating specification-intensive segment entry with validation-focused go-to-market. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified materials science conglomerates seeking high-temperature filtration capability. Long-term viability hinges on PFAS-compliant formulation portfolios and hydrogen economy syngas purification positioning. Acquisition target archetype: specialized ceramic fabricators with silicon carbide production expertise and existing EPA MATS validation. Watch EPA particulate matter designation updates and emerging state-level PFAS restriction enforcement as inflection indicators for synthetic media asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive petroleum pitch sourcing insulates activated carbon margins from Gulf Coast refinery output volatility. |
| PFAS-Compliant Formulation Development | Fluorine-free synthetic media coatings preserve California and New York market access under emerging state bans. |
| Smart Sensor-Embedded Media Launch | Duke Energy and ExxonMobil pilot programs validate predictive replacement scheduling for condition-based maintenance contracts. |
| Hydrogen Economy Filtration Partnership | Carbon capture and syngas purification pilot projects require novel media for CO2 separation process integration. |
| Consolidated Facility Management Alliance | Sodexo and Aramark service agreements bundle media supply with predictive analytics, concentrating Midwest chemical corridor purchasing power. |
Research Methodology
Multi-period observation of EPA MATS compliance deployment timelines, activated carbon precursor pricing indices, and ceramic media manufacturing capacity utilization anchored the trend analysis, supplemented by interviews with plant engineers at Ohio River Valley coal-fired stations, procurement leads at Texas Gulf Coast refineries, technical R&D directors at synthetic fiber manufacturers, and aftermarket service heads at filtration distributors. Secondary validation drew from EPA enforcement and compliance databases, EIA power generation fuel mix disclosures, SEC 10-K filings from diversified materials science conglomerates, and customs trade data for activated carbon precursor imports. Bottom-up segment sizing triangulated against top-down regulatory mandate impact modeling.
Segment-weighting across material chemistry, application intensity, and regulatory exposure tiers structured the analytical framework. Product type segmentation modeled HEPA, activated carbon, electrostatic precipitator, and panel filter categories. Application segmentation distinguished industrial filtration, laboratory, commercial HVAC, and automotive end uses. Material segmentation captured fiberglass, synthetic media, polyester, and cellulose performance tiers. End user segmentation separated power generation centralized procurement from manufacturing dispersed maintenance operations. CAGRs derived from replacement cycle compression analysis under MATS deadlines and infrastructure aging patterns. Hydrogen economy pilot project filtration requirements and PFAS restriction enforcement timelines served as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including potential National Ambient Air Quality Standards particulate matter designation revisions, breakthrough ceramic manufacturing process innovations, and geopolitical disruptions to petroleum pitch precursor trade flows. Forecasts reflect base-case assumptions regarding EPA enforcement continuity and state-level regulatory alignment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Aerospace Filter Market
Filters
Filter Bag Market
Filters
US Baghouse Filters Market
Filters
Respirator Cartridges and Filters Market
Filters
Fabric Filters Market
Filters
United States Activated Carbon Market
Filters
Global Liquid Filtration Market
Filters
Global Hollow Fiber Filtration Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
String Wound Filter Materials Market
Filters
Ceramic Filters Market
Filters
Global Gas Phase Filtration Market
Filters
ePTFE Filter Film Market
Filters
Global Laboratory Filtration Market
Filters
Filter Coatings Market
Filters
Sintered Metal Filters Market