
 Diatomaceous Filter Aid Market | 2026-2036
Diatomaceous Filter Aid Market Size, Share, and Industry Trends Forecast 2026-2036
Diatomaceous Filter Aid Market Outlook
Technical support and filtration system maintenance subscriptions is expanding as a recurring revenue layer that redefines how diatomaceous filter aid suppliers capture lifetime customer value. Imerys leverages its integrated mining and processing footprint to sustain long-term supply agreements with municipal water authorities. EP Minerals anchors its position through vertical control over Nevada diatomite deposits, ensuring feedstock security. Showa Chemical Industry competes on specialized pre-coat formulations for Asian pharmaceutical manufacturers.
Diatomaceous filter aid consists of the fossilized remains of diatoms, siliceous microalgae processed into powders with median particle sizes typically ranging from 5 to 40 microns and permeabilities spanning 0.1 to 30 Darcy units; its primary commercial purpose is to form porous cake layers that trap suspended solids from liquids without altering chemical composition. Filter powder and pre-coat grades dominate volume flows in mature water treatment and food processing installations where operational familiarity reduces switching costs. Depth filters and specialized filter aids command margin premiums in pharmaceutical sterile filtration and high-purity chemical applications where validation documentation and batch consistency requirements create stickier supplier relationships.
The EPA regulates drinking water filtration under the Safe Drinking Water Act, while the FDA oversees food contact notifications for filter aids used in edible oil and beverage clarification; these frameworks elevate barrier-to-entry for unvalidated suppliers and steer procurement toward documented quality systems. ISO 9001 and NSF/ANSI certification requirements further constrain market access for regional producers lacking laboratory infrastructure. Stakeholders must monitor evolving PFAS filtration mandates and corresponding test protocol changes that could redirect specification priorities toward modified diatomite grades or hybrid media formulations.
Market Dynamics
Water treatment infrastructure renewal cycles and tightening purity mandates are compressing procurement timelines for diatomaceous filter aid, forcing suppliers to embed technical validation deeper into pre-sales engineering workflows.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Municipal water authorities in the United States face upgraded filtration mandates that expand specification volumes for documented pre-coat grades.
- Craft brewery expansion:Small-scale beverage producers across the Great Lakes corridor adopt diatomaceous earth clarification for its chemical neutrality and operational familiarity.
- California agricultural processing corridors:Fruit juice and edible oil refiners concentrate demand for food-grade filter aids with NSF/ANSI certification trails.
Market Restraints
- Nevada deposit concentration:Domestic feedstock security depends on a narrow geographic band of diatomite mining operations, creating single-source vulnerability.
- Perlite substitution threat:Expanded perlite offers comparable permeability at lower unit cost in non-critical water treatment applications.
- ISO 9001 certification friction:Laboratory infrastructure requirements for quality system documentation block regional producers from municipal procurement pools.
Strategic Opportunities
- PFAS filtration mandates:Emerging test protocol changes redirect specification priorities toward modified diatomite grades with enhanced microporosity.
- Technical support subscriptions:Filtration system maintenance contracts create recurring revenue layers beyond commodity powder sales.
- Asian pharmaceutical sterile filtration:Pre-coat formulations validated for batch consistency command margin premiums in injectable drug manufacturing.
Industry Challenges
- Filtration engineering talent scarcity:Field application expertise in cake formation optimization remains concentrated among retiring specialists.
- Legacy system integration complexity:Pre-coat filtration skids in mature food plants require retrofit engineering to accommodate automated dosing controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diatomaceous Filter Aid Market |
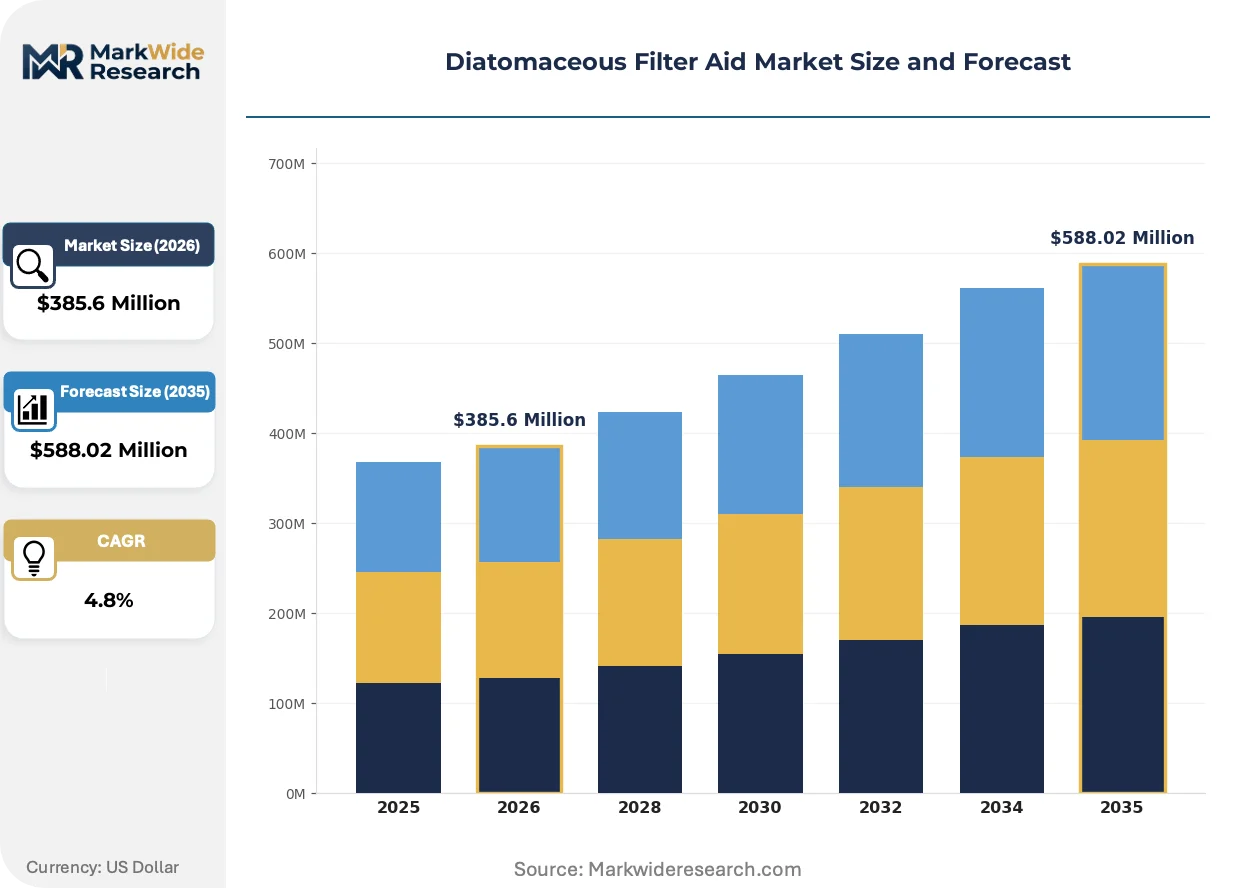
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filter Powder, Pre-Coat, Depth Filters, Filter Aids Application: Water Treatment, Food and Beverage, Pharmaceutical, Chemicals End User: Industrial, Commercial, Residential, Agriculture Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | Imerys, EP Minerals, Showa Chemical Industry, Dicalite Management Group, Jilin Yuan Tong Mineral, Shengzhou Huali Diatomite Products, Calgon Carbon Corporation, ErtelAlsop, Xinghui, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diatomaceous Filter Aid Market Strategic Shifts
Hybrid media formulations and digital filtration monitoring are compressing the traditional specification cycle, forcing suppliers to demonstrate real-time performance transparency rather than static certification packets.
Calcined diatomaceous earth with enhanced permeability is overtaking natural-grade powders in high-throughput municipal installations. Water treatment authorities in Texas and Florida specify these thermally processed variants for their reduced pre-coat mass requirements. The technology is overtaking legacy natural-grade procurement in applications where hydraulic capacity constraints dominate capital planning.
EU REACH substance registration requirements are extending documentation obligations to imported filter aids used in beverage clarification. European bottlers now demand full supply chain disclosure for diatomite sourcing and calcination parameters. German mineral water producers have pioneered audit protocols that North American exporters must replicate to maintain continental market access.
Specification decisions now hinge on lifetime cost modeling rather than unit price comparisons. Craft breweries in Colorado and Oregon contract directly with technical service teams for seasonal filtration optimization. This behavioral shift concentrates supplier relationships around embedded engineering support rather than distributor intermediaries.
Diatomaceous Filter Aid Market Segmentation
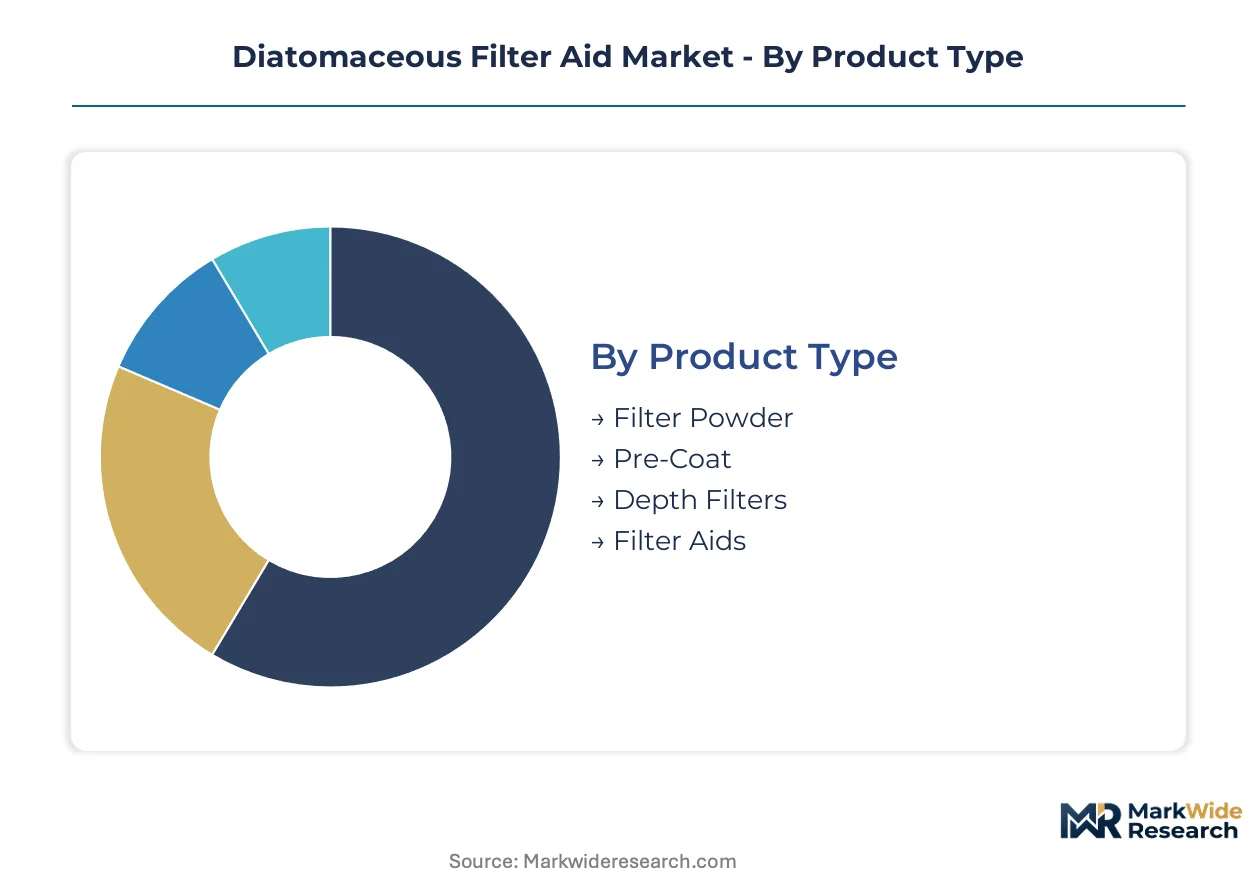
Diatomaceous filter aid procurement splits between standalone powder sales and integrated filtration systems, with each configuration demanding distinct validation protocols and supplier relationships. Understanding these segment boundaries clarifies where technical service investments yield recurring revenue versus commodity margin compression.
Product Type:
Integration depth separates powders sold for manual dosing from pre-engineered systems with embedded media cartridges.
- Filter Powder:Natural and calcined diatomite grades with permeabilities from 0.1 to 30 Darcy units flow as bulk commodities to water treatment plants and food processors. Municipal authorities in Texas specify calcined variants for reduced pre-coat mass requirements. Filter powder leads volumes today; pre-coat is gaining share fastest.
- Pre-Coat:Formulated blends with controlled particle size distributions create uniform cake layers on filter septa. Craft breweries across Oregon contract directly with technical teams for seasonal optimization support. Pre-coat formulations command specification stickiness through embedded engineering relationships.
- Depth Filters:Rigid media cartridges incorporating diatomaceous earth eliminate manual dosing labor in pharmaceutical sterile filtration.
- Filter Aids:Hybrid formulations combining diatomite with perlite or cellulose target specific contaminant profiles in chemical processing.
Filter powder dominates tonnage flows; pre-coat climbs fastest on technical service attachment rates.
Application:
Regulatory stringency tiers separate commodity clarification from validated sterile processes.
- Water Treatment:EPA Safe Drinking Water Act amendments compress procurement timelines for documented pre-coat grades in municipal installations. Great Lakes water authorities upgrade filtration infrastructure with calcined diatomite for hydraulic capacity expansion. Water treatment anchors absolute demand; pharmaceutical expands most quickly.
- Food and Beverage:FDA food contact notifications and NSF/ANSI certification requirements steer edible oil and juice refiners toward documented supply chains. California agricultural processors concentrate procurement for fruit juice clarification systems.
- Pharmaceutical:Injectable drug manufacturing demands batch consistency validation and sterile filtration documentation from Asian producers.
- Chemicals:High-purity solvent filtration tolerates broader specification variance than pharmaceutical applications.
Water treatment commands volume leadership; pharmaceutical shows steepest expansion trajectory on purity mandate tightening.
End User:
Operational scale determines whether procurement flows through distributor networks or direct technical relationships.
- Industrial:Continuous-process manufacturers in chemicals and food operate captive filtration engineering teams that source directly from mineral processors. Industrial segments concentrate procurement volume through long-term supply agreements.
- Commercial:Craft breweries and bottled water producers purchase through regional distributors with limited technical support capabilities.
- Residential:Point-of-use filtration systems represent minimal diatomaceous earth consumption relative to institutional scales.
- Agriculture:Irrigation water treatment and crop processing generate seasonal demand spikes with lower specification rigor.
Industrial end users dominate procurement values; commercial segments expand quickest on craft beverage proliferation.
Distribution Channel:
Channel selection reflects buyer technical sophistication and validation documentation requirements.
- Direct Sales:Municipal water authorities and pharmaceutical manufacturers negotiate multi-year agreements with mineral processors for guaranteed supply security. Direct relationships embed technical validation into pre-sales engineering workflows.
- Distributors:Regional chemical supply houses serve food processors and smaller water treatment facilities with standardized product grades.
- Online Retail:E-commerce platforms capture residential and small commercial buyers seeking low-volume replenishment with minimal technical consultation.
- Others:OEM filtration system manufacturers bundle diatomaceous media with capital equipment sales.
Direct sales channels command value concentration; distributor networks capture widest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting production footprints as diatomite processors weigh EPA compliance costs against ECHA REACH documentation burdens and Asian permitting efficiency. Feedstock security and end-market proximity now override labor cost considerations in site selection decisions.
United States
Nevada diatomite deposits anchor domestic calcination capacity for municipal water treatment upgrades. EPA Safe Drinking Water Act amendments compress procurement timelines for documented pre-coat grades across Great Lakes infrastructure authorities. California agricultural processing corridors concentrate food-grade filter aid demand from fruit juice and edible oil refiners seeking NSF/ANSI certification trails.
Germany
EU REACH substance registration requirements extend documentation obligations to imported filter aids used in beverage clarification. German mineral water producers have pioneered audit protocols that North American exporters must replicate to maintain continental market access. Bavarian brewing clusters drive technical service attachment rates for seasonal filtration optimization contracts.
China
Domestic diatomite mining in Jilin and Zhejiang provinces supplies regional food processing and chemical filtration demand. GB standards for drinking water treatment filter media elevate barrier-to-entry for unvalidated suppliers. Yangtze River Delta pharmaceutical manufacturers import validated pre-coat formulations for injectable drug sterile filtration processes.
Japan
Specialized pre-coat formulations for Asian pharmaceutical manufacturers concentrate procurement among documented quality system suppliers. METI industrial standards for chemical processing filtration steer specification toward batch consistency validation. Osaka-Kobe chemical corridor demands hybrid media formulations combining diatomite with perlite for high-purity solvent applications.
Brazil
Fruit juice and edible oil refiners in São Paulo state adopt food-grade filter aids as ANVISA tightens food contact substance notification requirements. Agricultural processing infrastructure expansion in Minas Gerais generates seasonal demand spikes for irrigation water treatment. Regional distributors serve commercial segments with limited technical support capabilities compared to direct sales channels.
Diatomaceous Filter Aid Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated mineral processors commanding municipal water authority relationships while regional blenders serve food processing distributors. The vendor base organizes around three strategic archetypes: mining-integrated multinationals with captive feedstock security, formulation specialists with embedded technical service capabilities, and regional distributors with logistics scale but limited application engineering. Competitive moves concentrate on backward integration into diatomite deposits and filtration system bundling to capture recurring maintenance revenue.
Among mining-integrated multinationals, Imerys and EP Minerals exemplify the feedstock-security archetype through upstream control over Nevada diatomite deposits. Showa Chemical Industry occupies a position within the formulation-specialist tier, representing technical service attachment strategies for Asian pharmaceutical sterile filtration. Dicalite Management Group and Calgon Carbon Corporation sit within the diversified-minerals segment, anchoring portfolio breadth across filtration and adsorption applications.
| Leading Market Players |
|---|
| Imerys |
| EP Minerals |
| Showa Chemical Industry |
| Dicalite Management Group |
| Jilin Yuan Tong Mineral |
| Shengzhou Huali Diatomite Products |
| Calgon Carbon Corporation |
| ErtelAlsop |
| Xinghui |
| Others |
Value Chain & Pricing Dynamics
Calcination energy costs cascade through Nevada diatomite processing into three distinct pricing tiers downstream, with thermally treated grades commanding premiums over natural powders based on permeability performance and pre-coat mass efficiency.
Pricing Analysis
Distributor markups separate commodity filter powder flows from direct technical service relationships that embed filtration optimization subscriptions. Pricing stratifies across pharmaceutical-grade certified pre-coat, food-grade NSF/ANSI validated blends, and municipal water treatment bulk powders. Cost compression in natural-grade segments intensifies as expanded perlite substitutes erode unit economics at the specification margin. Municipal procurement officers demonstrate lowest price sensitivity due to lifetime cost modeling mandates, while craft breweries exhibit highest elasticity to per-kilogram quotes.
Supply Chain Analysis
Direct-to-municipal channels handle Great Lakes water authority demand through long-term offtake agreements with calcination facilities anchored in Nevada. Raw material security draws from domestic diatomite deposits, with supplemental feedstock sourcing from Chinese Jilin province and German Bavarian mining operations. Single-source vulnerability concentrates in Nevada's geographic band of thermally processed capacity. Distribution runs through mineral processors for validated grades and regional chemical distributors for standardized commodity flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Safe Drinking Water Act amendments compound procurement urgency for documented pre-coat grades, transforming filtration infrastructure cycles into sustained demand corridors for validated suppliers.
For Market Incumbents: Lock in municipal water authority relationships through multi-year technical service subscriptions that embed filtration system maintenance beyond commodity powder sales. Backward integration into Nevada diatomite deposits secures feedstock autonomy against perlite substitution threats. Expand calcination capacity to capture specification shifts toward thermally processed variants in high-throughput installations. For New Entrants and Emerging Players: Regional distributors serving California agricultural processors represent the most penetrable channel partner type for food-grade filter aid market entry. White-space concentrates in craft brewery technical service gaps across Colorado and Oregon, where seasonal filtration optimization contracts remain underserved. Target ANVISA-aligned Brazilian fruit juice refiners through documentation-ready export formulations. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation specialists lack captive diatomite supply and mining-integrated players seek technical service capabilities. Long-term viability favors acquisition of pre-coat blenders with embedded engineering teams and Asian pharmaceutical validation trails. Watch for PFAS filtration mandate finalization as inflection signal redirecting specification priorities toward enhanced microporosity grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diatomite Mining | Nevada deposit control eliminates single-source vulnerability for calcination-dependent suppliers. |
| Technical Service Subscription Launch | Craft breweries in Oregon contract directly for seasonal filtration optimization beyond commodity sales. |
| Pharmaceutical Pre-Coat Validation Investment | Asian injectable drug manufacturers demand batch consistency documentation for sterile filtration processes. |
| Hybrid Media Formulation Development | Osaka-Kobe chemical corridor specifications combine diatomite with perlite for high-purity solvent applications. |
| EU REACH Documentation Compliance | German mineral water audit protocols require full supply chain disclosure for continental market access. |
Study Parameters
Coverage spans the United States, Germany, China, Japan, and Brazil, with primary inputs from each market combining interviews with municipal water authority procurement officers, filtration engineering directors at craft breweries, pharmaceutical sterile filtration specialists, and mineral processing plant managers. Secondary validation draws from EPA Safe Drinking Water Act filings, FDA food contact substance notifications, ECHA REACH substance registrations, and customs trade data for diatomite import flows. Bottom-up volume modeling triangulates against top-down value estimates across the analysis window.
Granularity-level modeling operates at product type by application by end user, with separate permeability tier specifications for natural versus calcined grades and distinct validation requirements for municipal, food-grade, and pharmaceutical procurement pools. CAGRs derive from segment-level demand elasticity analysis against regulatory mandate timelines and infrastructure renewal cycle phasing. Forecast inputs incorporate calcination capacity expansion announcements and PFAS filtration protocol development trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA rulemaking finalization dates and ECHA documentation burden evolution. Outputs reflect documented assumptions regarding regulatory implementation pacing and substitution elasticity thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Filtering Centrifuges Market
Filters
Zeolite Adsorbents Market
Filters
Respirator Cartridges and Filters Market
Filters
Global Hollow Fiber Filtration Market
Filters
Global Filter Market
Filters
Air Filtration Media Market
Filters
Global Gas Filtration Media Market
Filters
Fiberglass Filters Market
Filters
Color Filter Glass Market
Filters
United States Activated Carbon Market
Filters
Global Liquid Filtration Market
Filters
Compact Filters Market
Filters
GCC Industrial Air Filtration Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Canada Filtration and Separation Market
Filters
Global Pleated Filters Market