
 Global Gas Filtration Media Market | 2026-2036
Global Gas Filtration Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Filtration Media Market Foresight
Service-layer contracts for predictive filter monitoring and replacement scheduling is restructuring how buyers procure gas filtration media. Donaldson Company leverages its connected filtration platform to anchor long-term industrial accounts. MANN+HUMMEL sustains European automotive and industrial demand through captive manufacturing scale. Freudenberg Filtration Technologies GmbH & Co. KG dominates specialized membrane applications for chemical processing environments.
Gas filtration media comprises engineered porous materials—activated carbon, ceramic monoliths, PTFE membranes, and nano-fiber composites—designed to remove particulate, gaseous, or molecular contaminants from air and process streams based on pore size, surface area, and adsorption capacity specifications. These media serve critical functions in protecting equipment, ensuring product purity, and meeting occupational exposure limits across industrial and commercial operations. Activated carbon and PTFE membrane segments command premium margins due to specialized performance requirements in pharmaceutical and electronics manufacturing applications. HEPA and molecular sieve technologies are displacing conventional filtration in cleanroom and semiconductor facilities where contamination control thresholds tighten progressively.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate continuous monitoring and upgraded filtration at refineries and chemical plants. The EU F-Gas Regulation and REACH framework restrict fluorinated gas releases while requiring validated adsorption media for compliance documentation. Semiconductor facilities in Taiwan, South Korea, and Germany now specify filtration media certified to ISO 14644 cleanroom standards as a procurement prerequisite. Stakeholders must weigh regional regulatory divergence against the capital cost of multi-standard product platforms.
Market Dynamics
Service-layer contracts for predictive filter monitoring are restructuring how buyers procure gas filtration media, locking in multi-year industrial accounts through integrated hardware-software platforms rather than transactional media replacement.
Growth Catalysts
- Semiconductor cleanroom expansion:Taiwan and South Korea fabs are adding capacity that mandates ISO 14644-certified filtration media as a procurement prerequisite, pulling premium membrane and activated carbon volumes.
- EPA NESHAP enforcement:Continuous monitoring mandates at US refineries and chemical plants require upgraded adsorption systems, creating replacement cycles for validated compliance documentation.
- EU F-Gas Regulation phase-down:Fluorinated gas restrictions force chemical processors to install molecular sieve and activated carbon systems with traceable capture efficiency records.
Market Restraints
- Petroleum-based precursor volatility:Activated carbon production depends on coal and coconut shell feedstocks concentrated in Indonesia and Sri Lanka, exposing margins to energy-linked commodity swings.
- PTFE membrane supply concentration:High-performance fluoropolymer film production clusters with three specialized chemical processors, creating single-source vulnerability for semiconductor-grade specifications.
- Technical limitation in high-temperature acid gas:Ceramic monoliths face brittleness thresholds above 800°C in sulfur-rich process streams, restricting deployment in certain refinery catalytic cracker vent applications.
Strategic Opportunities
- India industrial corridor buildout:Gujarat and Tamil Nadu chemical parks lack mature filtration infrastructure, opening first-mover positioning for media suppliers meeting BIS emission standards.
- Hydrogen economy purification demand:Electrolyzer and fuel cell manufacturing requires ultra-high purity gas streams, converging membrane drying with catalytic impurity removal in integrated skid designs.
- Carbon capture integration:Amine-based post-combustion capture units at German and Dutch power stations need specialized pre-treatment media to protect solvents from particulate and SOx contamination.
Industry Challenges
- Cross-functional talent scarcity:Filter media engineering now requires combined expertise in materials science, IoT sensor integration, and regulatory compliance documentation, a skill set rarely found in single hires.
- Multi-standard certification timelines:Simultaneous EPA Method 18 validation, EU F-Gas compliance certification, and ISO 14644 cleanroom rating can extend product launch cycles by 18-24 months.
- Legacy DCS integration friction:Predictive monitoring platforms must interface with decades-old distributed control systems common in US and European process industries, complicating sensor deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Filtration Media Market |
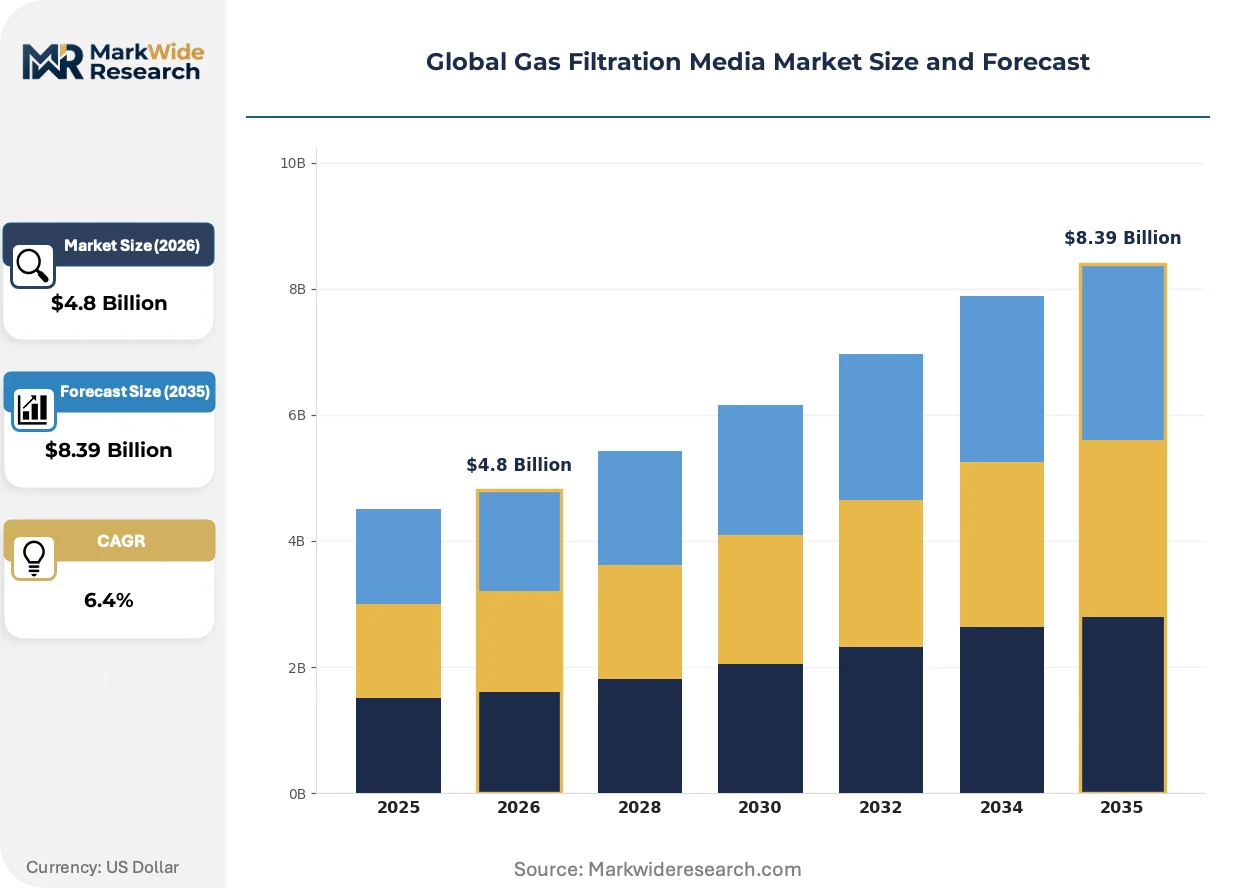
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Fiberglass, Activated Carbon, Synthetic Fiber, Ceramic, PTFE Membrane, Cellulose Technology: Electrostatic Precipitation, HEPA, ULPA, Molecular Sieves, Nano-Fiber, Adsorption Application: Air Purification, Industrial Emissions Control, Chemical Processing, Food & Beverage, Pharmaceuticals, Electronics Manufacturing End User: Power Plants, Refineries, Semiconductor Facilities, Food Processing Units, Laboratories, Cleanrooms |
| Companies Covered | Donaldson Company, Inc., Camfil, MANN+HUMMEL, Freudenberg Filtration Technologies GmbH & Co. KG, Parker Hannifin Corporation, Koch Filter, PURAFIL, INC., Circul-aire Inc., American Air Filter Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Filtration Media Market Shifts & Advancements
Nano-fiber composite media are consolidating performance tiers across electronics and pharmaceutical manufacturing, compressing the historical separation between HEPA and molecular filtration into unified substrate architectures.
Nano-fiber electrospinning is consolidating gas filtration media design by embedding adsorptive particles directly into non-woven PTFE matrices. Semiconductor fabs in Taiwan and South Korea specify these composites for sub-0.1 micron particle retention combined with AMC removal. The technology is consolidating what previously required separate pre-filter and chemical filter stages into single-stage configurations.
REACH SVHC disclosure requirements are forcing chemical processors to document full material composition of installed filtration media. The regulation mandates substitution planning for substances of very high concern, including certain impregnated activated carbons. German chemical clusters are responding by qualifying coconut shell-based alternatives ahead of formal restriction dates.
Industrial buyers are bundling filter media procurement with predictive replacement services, unbundling the hardware-software stack from traditional distributor channels. Original equipment manufacturers are capturing this margin directly through subscription monitoring platforms. This pattern is most visible in US and German automotive paint shops where downtime costs exceed media price differentials.
Global Gas Filtration Media Market Segmentation
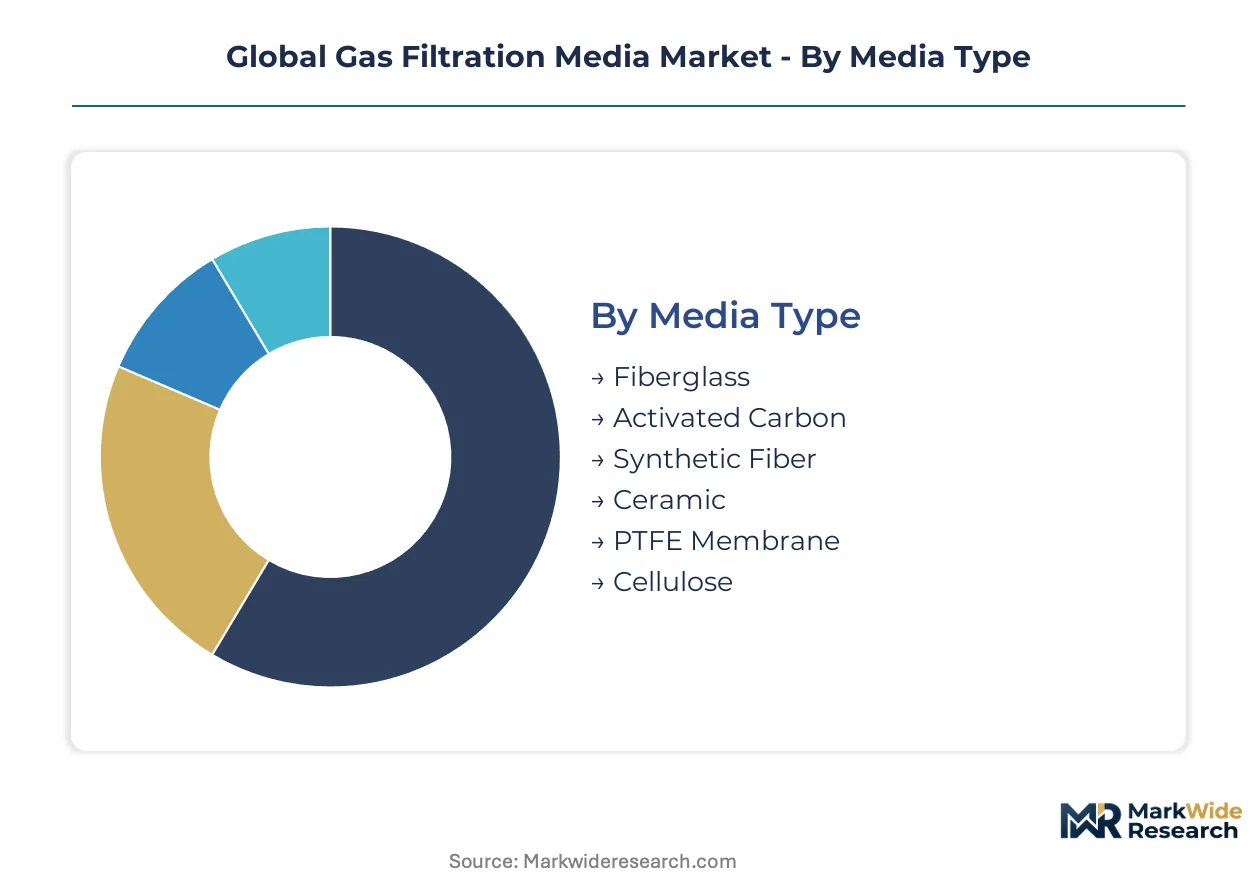
Gas filtration media segmentation reflects divergent capital requirements across substrate manufacturing, certification protocols, and end-use specifications. Media type determines feedstock processing intensity while technology tier governs cleanroom validation costs. Application and end-user dimensions further stratify procurement patterns between compliance-driven replacement cycles and performance-premium installations.
Media Type:
Activated carbon and PTFE membrane production demand the heaviest upfront capital outlays for carbonization kilns and fluoropolymer extrusion lines, while cellulose and synthetic fiber operations scale with lower equipment thresholds.
- Activated Carbon:Derived from coconut shell, coal, or wood through high-temperature steam activation. Semiconductor fabs in Taiwan specify acid-washed variants for AMC control, with EPA NESHAP compliance documentation adding procurement validation layers.
- PTFE Membrane:Expanded fluoropolymer film with sub-micron pore structures produced via biaxial stretching. South Korean electronics manufacturers drive demand for hydrophobic grades in aggressive chemical environments, though supply concentrates with specialized chemical processors.
- Fiberglass:Borosilicate glass microfibers formed into depth media for high-temperature applications. Power plants in Germany deploy these for flue gas conditioning.
- Synthetic Fiber:Polypropylene and polyester melt-blown nonwovens for general industrial pre-filtration. Food processing units in India favor these for moisture resistance.
- Ceramic:Aluminum oxide and silicon carbide monoliths for thermal stability above 800°C. Refinery catalytic cracker vents impose brittleness constraints.
- Cellulose:Wood pulp-based depth media for low-cost HVAC and coarse particulate removal. Laboratories specify these for non-critical pre-filtration stages.
Activated carbon absorbs the bulk of installed capacity; PTFE membrane is expanding most quickly.
Technology:
ULPA and molecular sieve systems command premium pricing tiers tied to semiconductor yield protection, while electrostatic precipitation serves cost-sensitive industrial boiler applications.
- HEPA:High-efficiency particulate air filters capturing 99.97% of 0.3 micron particles. Cleanrooms in Germany require EN 1822 certification alongside ISO 14644 validation.
- Nano-Fiber:Electrospun polymer matrices embedding adsorptive particles. Taiwan fabs specify these composites for single-stage sub-0.1 micron retention combined with AMC removal.
- Molecular Sieves:Crystalline aluminosilicates with precise pore apertures for selective gas separation. EU F-Gas Regulation compliance drives replacement cycles at Dutch chemical processors.
- ULPA:Ultra-low penetration air filters exceeding HEPA capture thresholds. South Korean memory chip facilities mandate these for Class 1 cleanroom zones.
- Adsorption:Surface-based contaminant capture using activated carbon or zeolite media. US refineries deploy these for benzene and VOC control under EPA enforcement.
- Electrostatic Precipitation:Charged particle collection without filter media replacement. Indian power sector adoption lags due to maintenance complexity.
HEPA dominates current procurement volumes; nano-fiber technology is climbing the fastest.
Application:
Electronics manufacturing and pharmaceuticals concentrate the most stringent media specifications, while air purification applications tolerate broader performance variance.
- Electronics Manufacturing:Wafer fabs and flat-panel display facilities requiring AMC and particulate control. Taiwan and South Korea capacity expansion pulls premium membrane volumes.
- Industrial Emissions Control:Stack gas treatment at refineries and chemical plants. EPA Method 18 validation requirements structure procurement decisions.
- Air Purification:Commercial and residential HVAC systems. German building codes specify minimum efficiency ratings.
- Chemical Processing:Process stream protection and solvent recovery. REACH SVHC disclosure mandates reshape activated carbon selection.
- Pharmaceuticals:Sterile manufacturing and aseptic filling operations. FDA guidance on contamination control drives HEPA specification.
- Food & Beverage:Edible oil filtration and beverage clarification. BIS standards in India govern migration limits.
Industrial emissions control carries the largest installed base; electronics manufacturing shows the steepest expansion trajectory.
End User:
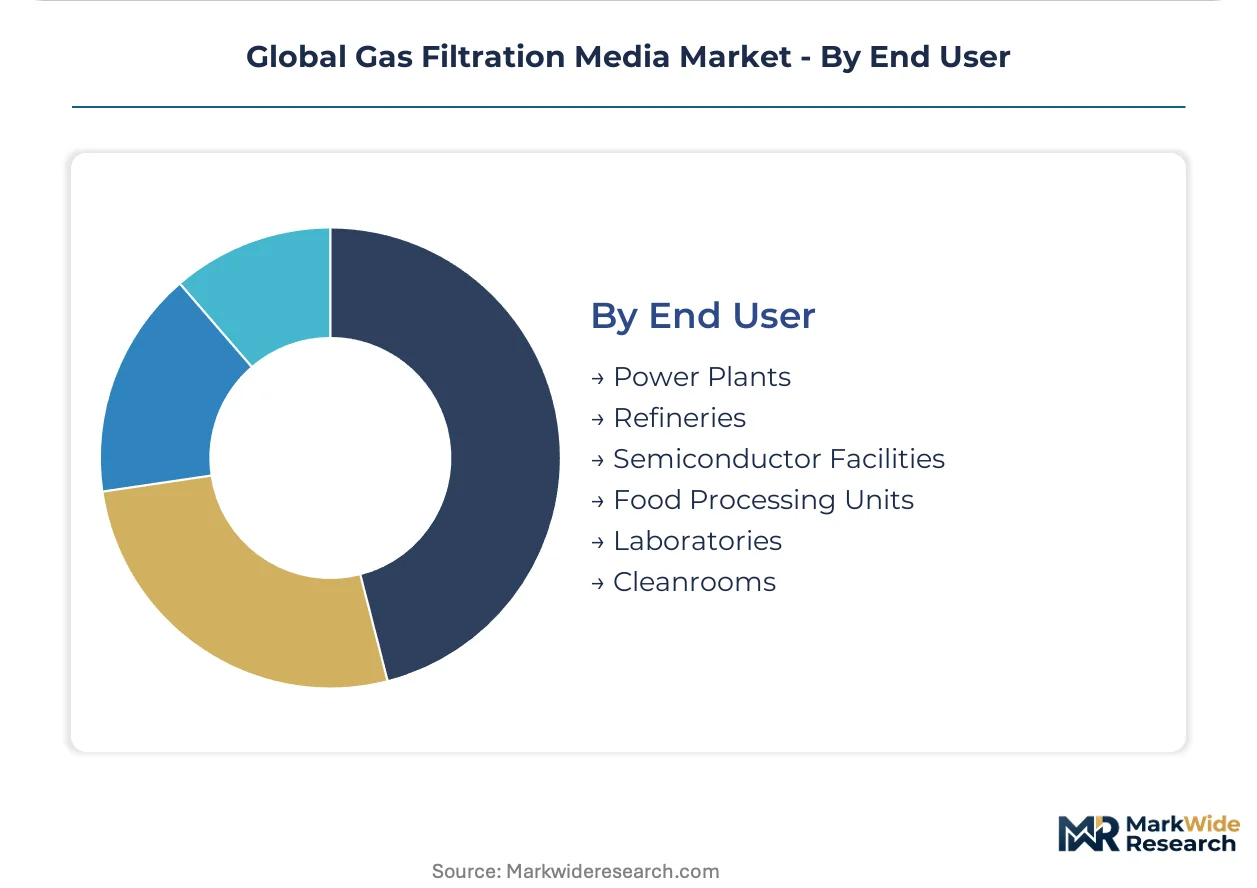
Semiconductor facilities and cleanrooms impose the most demanding certification protocols, while food processing units prioritize operational cost over capture efficiency.
- Semiconductor Facilities:Foundries and memory plants with Class 1-10 cleanroom requirements. ISO 14644 certification is a non-negotiable procurement prerequisite.
- Refineries:Fluid catalytic cracking and sulfur recovery units. EPA NESHAP continuous monitoring mandates drive media replacement cycles.
- Power Plants:Coal and natural gas combustion facilities. German carbon capture pilots require specialized pre-treatment media.
- Cleanrooms:Pharmaceutical, aerospace, and research installations. EN 1822 and ISO 14644 dual certification extends supplier qualification timelines.
- Laboratories:Research and analytical facilities with fume hood and biosafety cabinet requirements. Academic procurement emphasizes initial cost over lifecycle value.
- Food Processing Units:Dairy, meat, and packaged goods operations. Moisture-resistant synthetic media dominates this segment.
Refineries represent the deepest installed capacity; semiconductor facilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taipei anchors the densest concentration of semiconductor cleanroom demand, with Hsinchu Science Park fabs specifying ISO 14644-certified filtration media as non-negotiable procurement terms. This cluster pulls premium activated carbon and PTFE membrane volumes across the Asia-Pacific manufacturing corridor.
United States
EPA NESHAP enforcement at Gulf Coast refineries mandates continuous benzene monitoring and upgraded adsorption systems. Houston and Corpus Christi chemical complexes drive replacement cycles for validated compliance documentation. The Permian Basin gas processing expansion adds molecular sieve demand for dehydration units.
Germany
Leverkusen and Ludwigshafen chemical parks face REACH SVHC disclosure requirements forcing substitution planning for impregnated activated carbons. The EU F-Gas Regulation phase-down drives molecular sieve installations at Ruhr Valley processors. Carbon capture pilots at Emsland and Wilhelmshaven power stations require specialized pre-treatment media.
South Korea
Pyongtaek and Yongin memory chip fabs mandate ULPA filtration for Class 1 cleanroom zones under MFDS pharmaceutical-adjacent standards. Samsung and SK Hynix capacity expansions pull hydrophobic PTFE membrane volumes. The government's K-Semiconductor Belt initiative accelerates domestic filtration media qualification timelines.
India
Gujarat and Tamil Nadu chemical parks lack mature filtration infrastructure, opening positioning for suppliers meeting BIS emission standards. The PLI scheme for specialty chemicals attracts process industry investment to Dahej and Mundra corridors. Mumbai-Pune pharmaceutical clusters drive HEPA specification for sterile manufacturing.
Netherlands
Rotterdam and Antwerp port chemical processors face EU F-Gas Regulation compliance deadlines requiring traceable capture efficiency records. Shell and Dow facilities deploy molecular sieves for fluorinated gas recovery. North Sea carbon capture projects at Eemshaven and Rotterdam need amine solvent protection media.
Global Gas Filtration Media Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the filtration media value chain. Integrated substrate manufacturers with captive carbonization kilns and fluoropolymer extrusion lines hold margin advantages in activated carbon and PTFE membrane tiers. Three archetypes dominate: diversified industrial conglomerates with filtration divisions, pure-play filtration specialists, and regional fabricators serving cost-sensitive HVAC segments. Capacity expansion and predictive service platform development represent the dominant competitive vectors.
Within the diversified industrial tier, Donaldson Company, Inc. and Parker Hannifin Corporation exemplify the hardware-software integration archetype. MANN+HUMMEL and Freudenberg Filtration Technologies GmbH & Co. KG occupy positions among European-based specialists with captive manufacturing scale. These entities anchor the premium tier through multi-standard certification capabilities and long-term industrial account structures.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Camfil |
| MANN+HUMMEL |
| Freudenberg Filtration Technologies GmbH & Co. KG |
| Parker Hannifin Corporation |
| Koch Filter |
| PURAFIL, INC. |
| Circul-aire Inc. |
| American Air Filter Company, Inc. |
| Others |
Supply & Pricing Matrix
Coconut shell feedstock costs from Indonesia and Sri Lanka cascade through activated carbon kilning operations into tiered membrane pricing at semiconductor fabs. Energy intensity in carbonization and fluoropolymer extrusion anchors cost structures that buyers absorb through multi-year service contracts rather than spot procurement.
Pricing Analysis
Yield-protection value anchors pricing at Taiwan and South Korean fabs where unplanned downtime exceeds media replacement costs by orders of magnitude. Pricing stratifies across ISO 14644-certified premium tiers, EPA-validated compliance tiers, and standard industrial grades. Cost compression in cellulose pre-filtration stems from synthetic fiber substitution in Indian food processing. Academic laboratories exhibit highest price sensitivity; semiconductor cleanrooms show least.
Supply Chain Analysis
Specialized fluoropolymer chemist shortages in Germany and Japan constrain PTFE membrane expansion despite demand pull from electronics manufacturers. Activated carbon production draws from Indonesian coconut shell and Chinese coal feedstocks, with ceramic monolith sourcing concentrated in German refractory corridors. Single-source vulnerability pervades semiconductor-grade fluoropolymer film. Distribution runs through captive OEM service platforms and regional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nano-fiber composite architectures are displacing legacy two-stage pre-filter and chemical filter configurations across electronics manufacturing, compressing procurement categories and rewiring supplier relationships.
For Market Incumbents: Deepen backward integration into coconut shell carbonization capacity in Southeast Asia to defend margin position against feedstock volatility. Accelerate ISO 14644-1:2015 certification breadth to lock out regional fabricators lacking cleanroom validation infrastructure. Prioritize predictive monitoring platform R&D to capture service-layer recurring revenue before hardware commoditization accelerates. For New Entrants and Emerging Players: Direct-to-facility digital sales channels bypass entrenched distributor relationships in Indian chemical parks where BIS compliance documentation remains underdeveloped. Target Gujarat and Tamil Nadu process industries with modular skid designs bundling media and monitoring. Qualify coconut shell alternatives ahead of REACH SVHC restriction formalization to capture substitution demand. For Investors and Strategic Acquirers: Donaldson Company's connected filtration platform expansion is the leading indicator that hardware-software integration is consolidating procurement decision-making. Position for five-to-ten year holding periods around filtration-as-a-service business models. Acquire specialists with captive PTFE extrusion capability and multi-standard certification pipelines. Watch for EPA NESHAP enforcement acceleration as inflection signal for compliance-driven replacement cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Processing | Captive coconut shell carbonization kilns in Indonesia insulate margins from commodity volatility. |
| Predictive Monitoring Platform Development | Donaldson's iCue platform locks in multi-year industrial accounts through integrated hardware-software subscriptions. |
| Multi-Standard Certification Investment | Simultaneous EPA Method 18, EU F-Gas, and ISO 14644 qualification extends product launch cycles but blocks competitors. |
| Regional Manufacturing Footprint Expansion | Local PTFE membrane production in South Korea reduces lead times for Samsung and SK Hynix capacity expansions. |
| Joint Venture with Carbon Capture Developers | Amine solvent protection media partnerships at Rotterdam and Eemshaven secure first-mover positioning in emerging application. |
Research Methodology
Document review covered EPA enforcement actions, EU F-Gas Regulation implementation guidance, and SEC 10-K filings from diversified industrial conglomerates, complemented by interviews with cleanroom engineering directors, refinery environmental compliance officers, activated carbon procurement leads at chemical processors, and aftermarket service heads at filtration OEMs. Secondary validation drew from customs trade data, ISO certification registries, and national emission inventory submissions. Bottom-up segment sizing triangulated against top-down industrial output and capacity expansion announcements.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling by media type, technology tier, application intensity, and end-user certification requirements. CAGRs were derived from regression against semiconductor fab capital expenditure cycles, EPA enforcement intensity indices, and EU regulatory phase-down schedules. Industry-specific forecast inputs included Taiwan and South Korea cleanroom capacity buildout pipelines and German carbon capture pilot deployment timelines.
The model holds under stable regulatory enforcement intensity and continued semiconductor capital expenditure commitment; deviation in EPA NESHAP penalty escalation or memory chip demand contraction would shift replacement cycle timing and premium media absorption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Furnace Filters Market
Filters
String Wound Filter Materials Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Industrial Filter Paper Market
Filters
Global Filtration and Contamination Control Market
Filters
Filtration and Separation Market
Filters
Global Gas Phase Filtration Market
Filters
Anti-Microbial Filter Market
Filters
Filters and Particle Monitoring Market
Filters
Coolant Filtration Skids Market
Filters
Industrial Filtration Market
Filters
Filter Media Market
Filters
Residential Filters Market
Filters
North America Gas Filtration Media Market
Filters
Filtering Centrifuges Market
Filters
Global Depth Filtration Market