

Polishing Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Polishing Filter Market Insights
The capital-intensity divergence between membrane specialists and diversified filtration conglomerates is redrawing competitive boundaries in the Polishing Filter Market. Pall Corporation leverages its vertically integrated membrane manufacturing to sustain premium positioning in pharmaceutical aseptic filtration. Donaldson Company anchors its position through industrial-scale pleated media production for chemical processing installations. Amazon Filters competes on customization velocity, serving mid-size semiconductor fabricators with application-specific cartridge geometries.
A polishing filter performs final-stage particulate and contaminant removal downstream of primary separation systems, typically employing pleated polyethersulfone membranes, sintered ceramic matrices, or activated carbon composites rated between 0.03 and 10 microns to achieve fluid purity specifications critical to downstream process integrity. Membrane filters occupy the highest-margin tier in pharmaceutical manufacturing where sterilizing-grade validation is mandatory, while ceramic filters dominate semiconductor production due to thermal and chemical compatibility with aggressive process chemistries. Ion exchange polishing configurations represent the fastest-growing product type as lithium-ion battery electrolyte purification requirements intensify.
The EPA enforces maximum contaminant level goals under the Safe Drinking Water Act that directly mandate terminal filtration upgrades in municipal water treatment, while the FDA's process validation guidance for sterile drug products compels pharmaceutical companies to maintain certified polishing filtration protocols. Semiconductor fabricators must additionally comply with SEMI standards for ultrapure water quality that specify particle counts below detectable thresholds at critical process points. Stakeholders must monitor evolving material compatibility requirements as per- and polyfluoroalkyl substance regulations tighten across multiple jurisdictions, potentially restricting certain membrane chemistries and forcing reformulation investments.
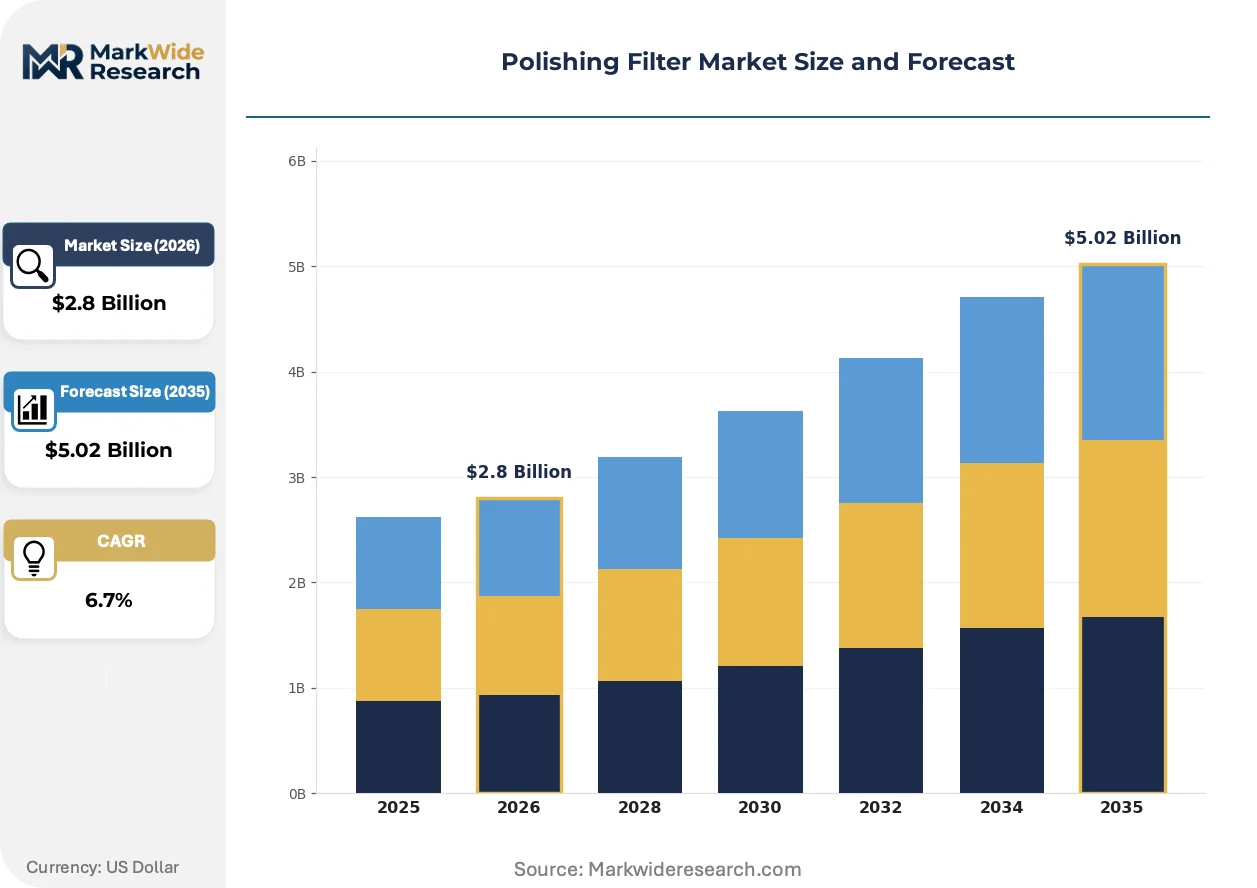
Market Dynamics
Semiconductor node shrinkage below 7 nanometers is forcing fabs to replace polyethersulfone cartridges with chemically inert ceramic polishing stages, compressing replacement cycles and elevating membrane validation costs across East Asia's fabrication corridor.
Growth Catalysts
- SEMI F104 ultrapure water standards:Taiwan and South Korean wafer fabs must deploy sub-10 nanometer rated terminal filtration for chemical mechanical planarization slurries, mandating capacity expansion at foundry clusters in Hsinchu and Pyeongtaek.
- EU Drinking Water Directive revisions:Municipal operators across Germany, France, and the Netherlands face tightened microbial and particulate limits, requiring ceramic membrane upgrades at legacy sand-filtration plants.
- Lithium-ion battery electrolyte purification:Ion exchange polishing configurations are capturing demand from gigafactory construction in Hungary and Poland as cell manufacturers target 99.99% electrolyte purity thresholds.
Market Restraints
- High-purity alumina supply concentration:Sintered ceramic matrix production depends on captive Japanese and German alumina refining, exposing fabricators to input cost volatility when energy prices spike.
- Per- and polyfluoroalkyl substance restrictions:ECHA proposals to limit fluoropolymer membrane chemistries threaten validated pharmaceutical filtration protocols, forcing reformulation investments before regulatory deadlines.
- Extended validation timelines:FDA process validation guidance for sterile drug products requires 12-18 month certification cycles for new membrane geometries, freezing supplier switching.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's alignment with PIC/S certification standards is attracting sterile injectable investments from European and North American drugmakers, creating demand for pre-validated polishing skids.
- Hydrogen electrolyzer stack purification:Proton exchange membrane electrolysis systems require sub-micron polishing of deionized water feeds, opening a channel for ceramic filter suppliers in German and Danish green hydrogen projects.
- Direct-to-fab technical service models:Semiconductor equipment OEMs are unbundling filtration maintenance from capital sales, enabling aftermarket specialists to capture recurring revenue at Arizona and Texas fab sites.
Industry Challenges
- Cross-functional membrane engineering talent:The intersection of polymer chemistry, semiconductor process engineering, and regulatory documentation expertise remains scarce, elongating product development cycles.
- Legacy water treatment infrastructure:Municipal operators in older European and North American cities face physical space constraints when retrofitting ceramic polishing trains into Victorian-era plant footprints.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polishing Filter Market Trends and Innovations
Material science breakthroughs and regulatory tightening are converging to displace legacy polymer membranes in the most demanding fluid purification applications, while digital integration is reshaping how filter performance is monitored and validated.
Ceramic matrix composites incorporating silicon carbide and yttria-stabilized zirconia are fragmenting the historical dominance of polyethersulfone in semiconductor slurry filtration. Taiwan Semiconductor Manufacturing and Samsung Foundry have qualified these materials for 3 nanometer node production, where thermal cycling and aggressive chemical exposure degrade organic membranes within weeks. The technology is fragmenting supplier concentration by enabling Chinese and Korean ceramic manufacturers to bypass incumbents' polymer IP portfolios.
EPA's revised National Primary Drinking Water Regulations are mandating granular activated carbon or membrane filtration for perchlorate and PFAS removal at municipal treatment plants. The industrial consequence is a surge in combined activated carbon-ceramic polishing train orders for utilities serving metropolitan areas with legacy industrial contamination. California and Michigan water authorities are most affected, accelerating procurement of validated multi-barrier systems ahead of compliance deadlines.
Semiconductor fabs are compressing filter replacement cycles from quarterly to monthly intervals as advanced nodes tolerate fewer particles per milliliter. This consumption-pattern shift is disrupting traditional distribution through regional distributors, with fabs now demanding vendor-managed inventory programs co-located at Hsinchu, Pyeongtaek, and Phoenix manufacturing sites. The model concentrates purchasing power with membrane specialists capable of guaranteeing 48-hour replenishment.
Polishing Filter Market Segmentation
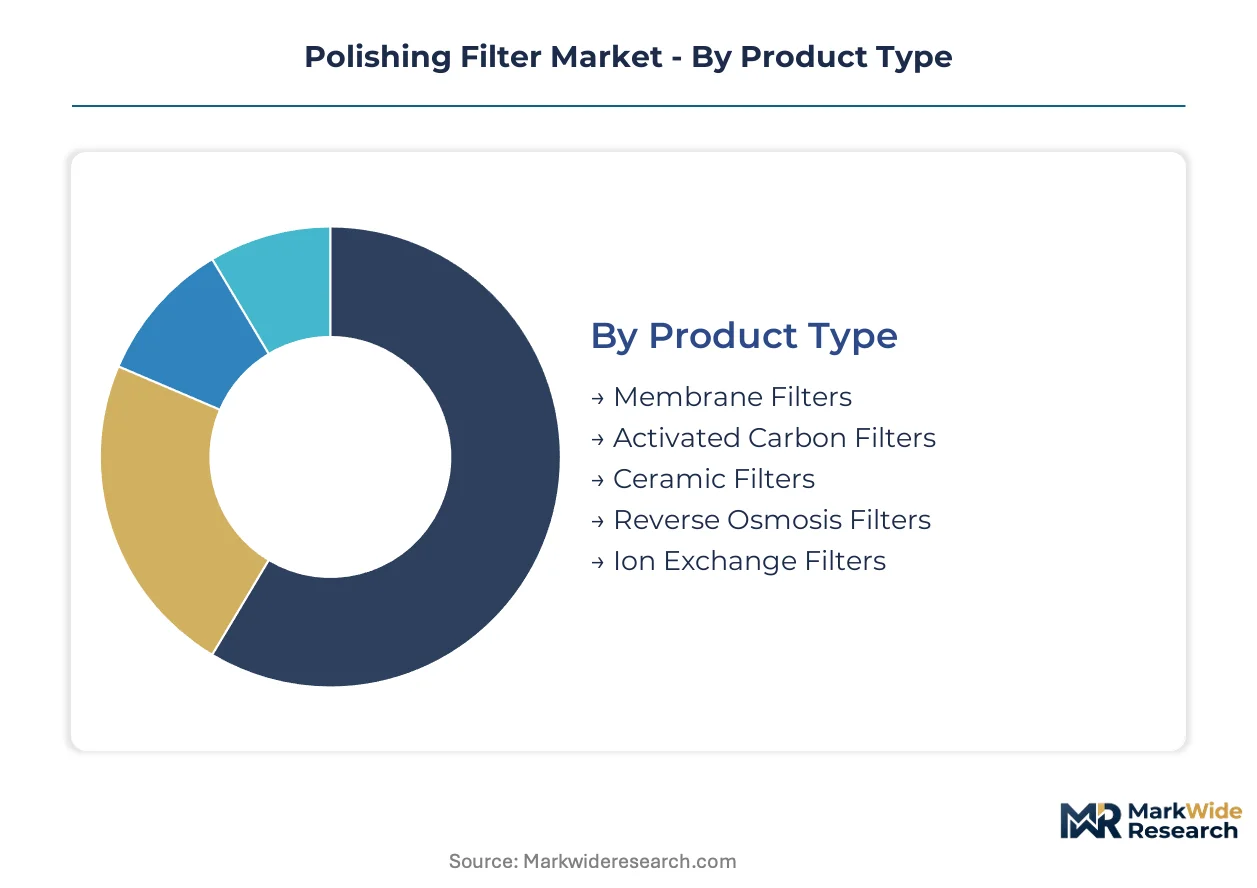
Polishing filter procurement patterns diverge sharply across end-use verticals, with semiconductor fabricators demanding sub-10 nanometer ceramic validation while pharmaceutical operators prioritize FDA-compliant membrane sterilization protocols. Regulatory frameworks in Taiwan, Germany, and the United States create distinct specification tiers that reshape supplier positioning within each segment category.
Product Type:
EPA Safe Drinking Water Act enforcement and ECHA fluoropolymer restrictions are fragmenting material selection criteria across jurisdictions, forcing manufacturers to maintain parallel certification portfolios for membrane chemistries.
- Membrane Filters:Pleated polyethersulfone configurations rated 0.03 to 10 microns dominate pharmaceutical aseptic filtration where FDA sterilizing-grade validation is mandatory. German and Swiss drug manufacturers absorb premium pricing for pre-validated cartridge geometries to compress batch release timelines.
- Ceramic Filters:Sintered alumina and silicon carbide matrices withstand thermal cycling and aggressive chemistries in semiconductor chemical mechanical planarization. Taiwan Semiconductor Manufacturing and Samsung Foundry have qualified yttria-stabilized zirconia for 3 nanometer node production, displacing organic membranes that degrade within weeks.
- Activated Carbon Filters:Granular activated carbon composites target perchlorate and PFAS removal at California and Michigan municipal plants under EPA revised National Primary Drinking Water Regulations.
- Reverse Osmosis Filters:Terminal RO stages achieve ultrapure water specifications for lithium-ion battery electrolyte production in Hungarian and Polish gigafactories.
- Ion Exchange Filters:Polishing configurations capture fastest expansion as cell manufacturers target 99.99% electrolyte purity thresholds.
Membrane filters dominate installed base in pharmaceutical sterile processing. Ceramic filters are where expansion concentrates for advanced semiconductor node production.
Application:
Cost tier differentiation separates commodity municipal water upgrades from premium semiconductor and pharmaceutical installations where validation documentation commands 40-60% price premiums over functionally equivalent unvalidated alternatives.
- Semiconductor Production:Chemical mechanical planarization slurry filtration and ultrapure water systems require sub-10 nanometer rated terminal stages. Hsinchu and Pyeongtaek foundry clusters mandate SEMI F104 compliance, compressing replacement cycles to monthly intervals.
- Pharmaceutical Manufacturing:Sterile injectable production lines in India and Ireland require 12-18 month FDA process validation cycles for new membrane geometries, freezing supplier switching and concentrating purchasing with incumbents.
- Water Treatment:Municipal operators across Germany, France, and the Netherlands face EU Drinking Water Directive microbial limit tightening, forcing ceramic membrane retrofits into legacy sand-filtration infrastructure.
- Chemical Processing:Industrial-scale pleated media production serves aggressive process chemistries where thermal compatibility exceeds polymer limits.
- Food & Beverage Processing:Terminal filtration for bottled water and brewing applications emphasizes activated carbon polishing for taste and odor control.
Water treatment commands largest unit volumes. Semiconductor production is climbing the fastest on value intensity per installation.
End User:
Customer type stratification concentrates high-margin technical service relationships with semiconductor fabricators while laboratories and food processors prioritize catalog distribution and price competition.
- Semiconductor Fabricators:Vendor-managed inventory programs co-located at Hsinchu, Pyeongtaek, and Phoenix manufacturing sites demand 48-hour replenishment guarantees, concentrating purchasing power with membrane specialists.
- Pharmaceutical Companies:CDSCO alignment with PIC/S certification standards in India is attracting sterile injectable investments from European and North American drugmakers, creating demand for pre-validated polishing skids.
- Chemical Plants:Donaldson Company anchors industrial-scale pleated media production for chemical processing installations requiring thermal and chemical compatibility.
- Food Processing Plants:Mid-size operators compete on customization velocity for application-specific cartridge geometries.
- Laboratories:Research and analytical applications prioritize portable and batch configurations for method development flexibility.
Pharmaceutical companies dominate validation-intensive premium tier. Semiconductor fabricators are gaining share fastest through consumption-pattern compression.
Installation Type:
Supply concentration in captive Japanese and German alumina refining shapes stationary and centralized plant configurations, while portable and batch systems enable geographic flexibility for emerging hydrogen electrolyzer and battery gigafactory deployments.
- Centralized Plants:Multi-barrier activated carbon-ceramic polishing trains serve metropolitan utilities with legacy industrial contamination in California and Michigan, accelerating procurement ahead of EPA compliance deadlines.
- Inline Systems:Continuous processing integration dominates semiconductor fab ultrapure water loops where particle count tolerance approaches undetectable thresholds.
- Stationary Units:Fixed installations anchor municipal and industrial infrastructure with 10-15 year capital depreciation cycles.
- Batch Systems:Flexibility for campaign-based pharmaceutical manufacturing accommodates multi-product facility changeover requirements.
- Portable Units:Field deployment for hydrogen electrolyzer stack purification in German and Danish green hydrogen projects requires rapid relocation between development sites.
Centralized plants dominate municipal infrastructure installed base. Inline systems are expanding most quickly through semiconductor fab capacity buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss pharmaceutical filtration corridors where sterilizing-grade validation commands 40-60% premiums, while Taiwanese and South Korean semiconductor clusters absorb cost volatility through vendor-managed inventory programs. The asymmetry reflects divergent regulatory stringency and replacement cycle compression across end-use verticals.
United States
EPA's revised National Primary Drinking Water Regulations mandate granular activated carbon or membrane filtration for perchlorate and PFAS removal at municipal plants. California and Michigan water authorities accelerate procurement of multi-barrier polishing trains ahead of compliance deadlines. Arizona and Texas fab sites drive demand for direct-to-fab technical service models.
Germany
EU Drinking Water Directive revisions force ceramic membrane retrofits at legacy sand-filtration infrastructure across municipal networks. Green hydrogen projects in northern states require sub-micron polishing of deionized water feeds for proton exchange membrane electrolysis systems. Bavarian chemical processing installations anchor industrial-scale pleated media consumption.
South Korea
SEMI F104 ultrapure water standards mandate sub-10 nanometer rated terminal filtration for chemical mechanical planarization slurries at Pyeongtaek foundry clusters. Monthly replacement cycles compress traditional quarterly intervals, disrupting regional distributor relationships. Samsung Foundry's qualification of yttria-stabilized zirconia ceramic matrices for 3 nanometer production elevates material specification tiers.
India
CDSCO alignment with PIC/S certification standards attracts sterile injectable investments from European and North American drugmakers. Pre-validated polishing skid demand concentrates at contract manufacturing facilities serving export markets. Domestic pharmaceutical production expansion creates procurement scale for membrane specialists establishing local technical service presence.
Japan
High-purity alumina supply concentration in captive domestic refining exposes sintered ceramic matrix producers to input cost volatility during energy price spikes. METI process standards for semiconductor materials reinforce qualification barriers for imported membrane alternatives. Domestic ceramic manufacturers leverage silicon carbide IP to penetrate East Asian fab supply chains.
Polishing Filter Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with membrane specialists commanding validation-intensive pharmaceutical premiums while diversified conglomerates capture industrial-scale volume through pleated media manufacturing. The market structure fragments across three tiers: vertically integrated membrane manufacturers, application-specific customization specialists, and broad-line filtration conglomerates. Dominant competitive moves include strategic partnerships with semiconductor equipment OEMs and geographic expansion through vendor-managed inventory co-location at foundry clusters.
Among diversified filtration conglomerates, Parker Hannifin and Eaton Corporation occupy positions spanning industrial fluid power and process filtration, while Pall Corporation exemplifies the vertically integrated membrane specialist archetype with captive manufacturing control over sterilizing-grade validation protocols. These three anchors represent the structural divergence between scale-driven diversification and premium-tier specialization that defines competitive positioning across pharmaceutical, semiconductor, and municipal end-use verticals.
| Leading Market Players |
|---|
| Parker Hannifin |
| Pall Corporation |
| Donaldson Company |
| Merck KGaA |
| Sartorius AG |
| 3M Company |
| Eaton Corporation |
| Graver Technologies |
| Amazon Filters |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Taiwanese semiconductor fabricators and ceramic membrane suppliers lock in both supply access and price visibility, insulating advanced node producers from alumina cost volatility while freezing out spot-market buyers during capacity crunches. These contracts concentrate purchasing power with vertically integrated membrane specialists capable of guaranteeing 48-hour replenishment at Hsinchu and Pyeongtaek manufacturing sites.
Pricing Analysis
Configured-to-order pricing commands 40-60% premiums over standard catalog offerings in pharmaceutical sterilizing-grade filtration, where FDA validation documentation absorbs substantial upfront engineering costs. Three-tier pricing structure across premium, standard, and economy levels separates validated membrane geometries for sterile injectables from unvalidated industrial cartridges and commodity municipal water replacements. Cost compression in standard-tier ceramic filters is intensifying because Chinese and Korean manufacturers are bypassing incumbents' polymer IP portfolios with silicon carbide alternatives. Municipal water operators exhibit highest price sensitivity due to public procurement constraints, while semiconductor fabricators absorb premium positioning to secure node-shrinkage compatibility.
Supply Chain Analysis
Inventory cycles have compressed from quarterly to monthly intervals at advanced semiconductor fabs, forcing vendor-managed inventory co-location at Arizona, Texas, and East Asian manufacturing sites. High-purity alumina supply concentrates in captive Japanese and German refining operations, while silicon carbide matrix production feeds from Korean and Chinese ceramic manufacturers. Single-source vulnerability in yttria-stabilized zirconia qualification for 3 nanometer nodes exposes Samsung Foundry and Taiwan Semiconductor Manufacturing to disruption if primary suppliers face energy price spikes. Distribution runs through direct-to-fab technical service models for semiconductor and pharmaceutical verticals, with regional distributors retaining relevance only in chemical processing and municipal water segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor node shrinkage below 7 nanometers constitutes a high-growth disruption, with EPA and EU Drinking Water Directive revisions simultaneously expanding addressable market scope across electronics and municipal infrastructure verticals.
For Market Incumbents: Fortify validation-intensive relationships with pharmaceutical manufacturers by accelerating FDA pre-submission programs for novel membrane geometries before ECHA fluoropolymer restrictions force reformulation investments. Deepen backward integration into high-purity alumina refining to offset Japanese and German supply concentration, or secure captive offtake agreements with energy-hedged refiners to defend margin position against input cost volatility. For New Entrants and Emerging Players: Lead with ion exchange polishing configurations targeting lithium-ion battery electrolyte purification at Hungarian and Polish gigafactories, where 99.99% purity thresholds and absence of entrenched incumbents create immediate white-space opportunity. Pursue direct technical service partnerships with proton exchange membrane electrolyzer developers in German and Danish green hydrogen projects, leveraging portable system flexibility to bypass stationary infrastructure incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane specialists with vendor-managed inventory programs co-located at semiconductor foundry clusters, where monthly replacement cycles generate predictable consumable income streams. Prioritize acquisition targets possessing cross-functional membrane engineering talent spanning polymer chemistry, semiconductor process engineering, and regulatory documentation expertise. Monitor SEMI standards evolution for ultrapure water quality specifications as the primary inflection indicator for ceramic filter demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Captive supply of high-purity alumina insulates Japanese ceramic manufacturers from energy price volatility. |
| Vendor-Managed Inventory Co-location | 48-hour replenishment guarantees at Hsinchu and Pyeongtaek concentrate purchasing power with membrane specialists. |
| FDA Pre-Validation Investment | 12-18 month certification cycles for sterile drug products freeze supplier switching in pharmaceutical filtration. |
| Silicon Carbide Matrix Development | Thermal cycling compatibility displaces polyethersulfone in 3 nanometer semiconductor node production. |
| Direct-to-Fab Technical Service Expansion | Unbundled filtration maintenance from capital sales captures recurring revenue at Arizona and Texas fab sites. |
Research Methodology
Desk research of SEMI standards documentation, EPA enforcement actions, and EU regulatory filings preceded structured interviews with semiconductor process engineers, pharmaceutical regulatory affairs leads, municipal water procurement officers, and ceramic membrane R&D directors. Primary fieldwork validated secondary findings through plant-level observations at foundry clusters in Taiwan and South Korea, water treatment facilities in Germany and the Netherlands, and battery gigafactories in Central Europe. Trade data from customs authorities, SEC filings from diversified filtration conglomerates, and industry association reports from SEMI and Cefic provided bottom-up volume triangulation against top-down macroeconomic indicators.
Variance decomposition across product type, application vertical, end-user category, and installation configuration enabled granular segment attribution throughout the projection horizon. Analytical framework incorporated SEMI F104 compliance timelines, ECHA regulatory proposal trajectories, and foundry capacity buildout schedules as industry-specific forecast inputs without assuming fixed implementation dates. CAGRs were derived from segment-level volume trajectories weighted by value intensity differentials between membrane, ceramic, and ion exchange product tiers.
Underlying assumptions cover continued semiconductor node shrinkage, EPA enforcement continuity, and EU Drinking Water Directive implementation pace, with deviation risk concentrated in ECHA fluoropolymer restriction timing and high-purity alumina supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.