
 Europe Activated Alumina Market | 2026-2036
Europe Activated Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Activated Alumina Market Insights
REACH compliance is expanding the cost-of-entry calculus for activated alumina suppliers serving European industrial buyers. BASF SE leverages its integrated alumina precursor network to control raw material quality from bauxite refining through final pelletization. Honeywell International Inc. dominates the desiccant segment through captive supply chains tied to its fluorocarbon handling systems. Evonik Industries AG differentiates via high-purity catalyst support grades engineered for European petrochemical licensors.
Activated alumina is a highly porous, granular form of aluminum oxide manufactured through controlled thermal dehydration of aluminum hydroxide, typically presenting surface areas between 150 and 350 square meters per gram and pore volumes optimized for adsorption or catalytic duty. Its primary industrial purpose centers on selective adsorption of moisture, fluoride compounds, and polar contaminants across gas and liquid process streams. The fluoride adsorbent category leads value generation due to tightening potable water standards across EU member states, while catalyst support demand accelerates fastest as European refiners retool for biofeedstock compatibility. Water treatment media occupies a mature volume position anchored by municipal procurement cycles, though margin pools concentrate in pharmaceutical-grade desiccant specifications.
EMA guidelines on active pharmaceutical ingredient stability and the EU F-Gas Regulation together reshape product certification requirements for suppliers targeting European healthcare and refrigeration end users. ECHA's evolving candidate list for Substances of Very High Concern pressures reformulation of binder systems used in alumina pellet manufacturing. Stakeholders must monitor how the EU Green Deal's embodied carbon tracking rules alter sourcing economics for bauxite-derived feedstocks entering European conversion facilities.
Market Dynamics
REACH compliance is restructuring supplier economics across the European activated alumina value chain, forcing reformulation of binder chemistries and recertification of production batches before they can enter German or French industrial procurement channels.
Growth Catalysts
- EU F-Gas Regulation:Tightened desiccant specifications for industrial refrigeration systems are mandating higher-grade activated alumina procurement across the continent.
- Germany:Water purification utilities along the Rhine corridor are scaling fluoride adsorbent procurement to meet stricter potable water standards.
- Biofeedstock refinery conversions:European petrochemical licensors are retooling catalytic processes, accelerating demand for high-purity catalyst support grades.
Market Restraints
- Bauxite feedstock concentration:Sourcing economics for European conversion facilities face pressure from embodied carbon tracking rules under the EU Green Deal.
- REACH registration costs:The cost-of-entry calculus for activated alumina suppliers serving industrial buyers continues expanding as ECHA's SVHC candidate list evolves.
- Zeolite substitution:Molecular sieve materials are capturing moisture adsorption applications in select pharmaceutical packaging segments.
Strategic Opportunities
- Poland and Czech Republic:Underpenetrated municipal water treatment infrastructure presents procurement expansion potential as EU cohesion funds flow eastward.
- EMA stability guidelines:Active pharmaceutical ingredient storage mandates are creating certified desiccant specification tiers with premium margin pools.
- Digital procurement platforms:Direct contracting between alumina pellet manufacturers and municipal utilities is compressing traditional distributor margins.
Industry Challenges
- Thermal process engineering expertise:Controlled dehydration of aluminum hydroxide requires specialized kiln operation skills that are scarce across Central European manufacturing zones.
- Batch-to-batch certification timelines:REACH-compliant documentation for each production lot extends order fulfillment cycles by several weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Activated Alumina Market |
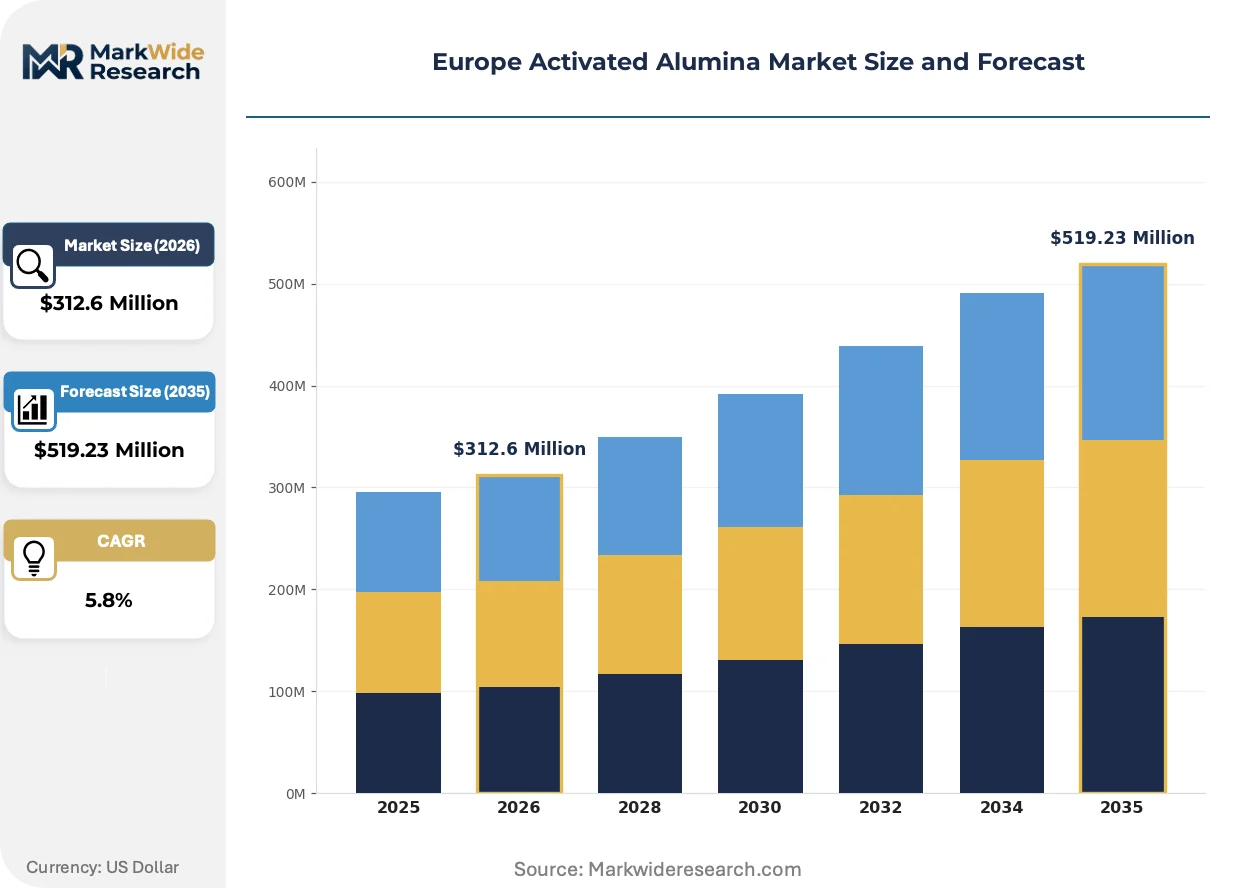
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desiccants, Catalyst Supports, Fluoride Adsorbents, Water Treatment Media Application: Chemical Processing, Oil & Gas, Pharmaceuticals, Water Purification End User: Industrial, Municipal, Pharmaceutical, Chemical Manufacturing Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | Honeywell International Inc., CHALCO Shandong Co Ltd, BASF SE, Sumitomo Chemical Co Ltd, Petrosadid, Huber Engineered Materials, Evonik Industries AG, Sorbead India, Axens, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Activated Alumina Market Trends and Innovations
Product certification requirements are fragmenting across healthcare and refrigeration end uses, while manufacturing technology shifts toward precision-controlled thermal processing.
Advanced pelletization systems with real-time moisture monitoring and automated density control are decentralizing production capability across mid-scale European facilities. Specialty chemical manufacturers in Belgium and the Netherlands are adopting these systems to serve regional pharmaceutical desiccant demand without transcontinental logistics exposure. This capability diffusion is compressing the historical advantage of integrated alumina precursor networks.
The EU F-Gas Regulation's phasedown schedule is forcing refrigeration OEMs to redesign sealed system architectures, with desiccant cartridge specifications now requiring compatibility testing against lower-GWP refrigerant chemistries. Industrial cold chain operators in France and Italy are front-loading activated alumina procurement to lock in qualified supply before 2027 compliance deadlines hit. The regulatory pressure is accelerating product lifecycle compression in the desiccant segment.
Consolidated procurement by Rhine corridor chemical processors is shifting contract structures toward multi-year volume commitments with price adjustment clauses tied to alumina precursor indices. Municipal water utilities in Scandinavia are unbundling media replacement services from equipment supply, creating standalone service revenue pools. This purchasing model evolution is most visible in Germany, where Verband kommunaler Unternehmen members are harmonizing tender specifications across state boundaries.
Europe Activated Alumina Market Segmentation
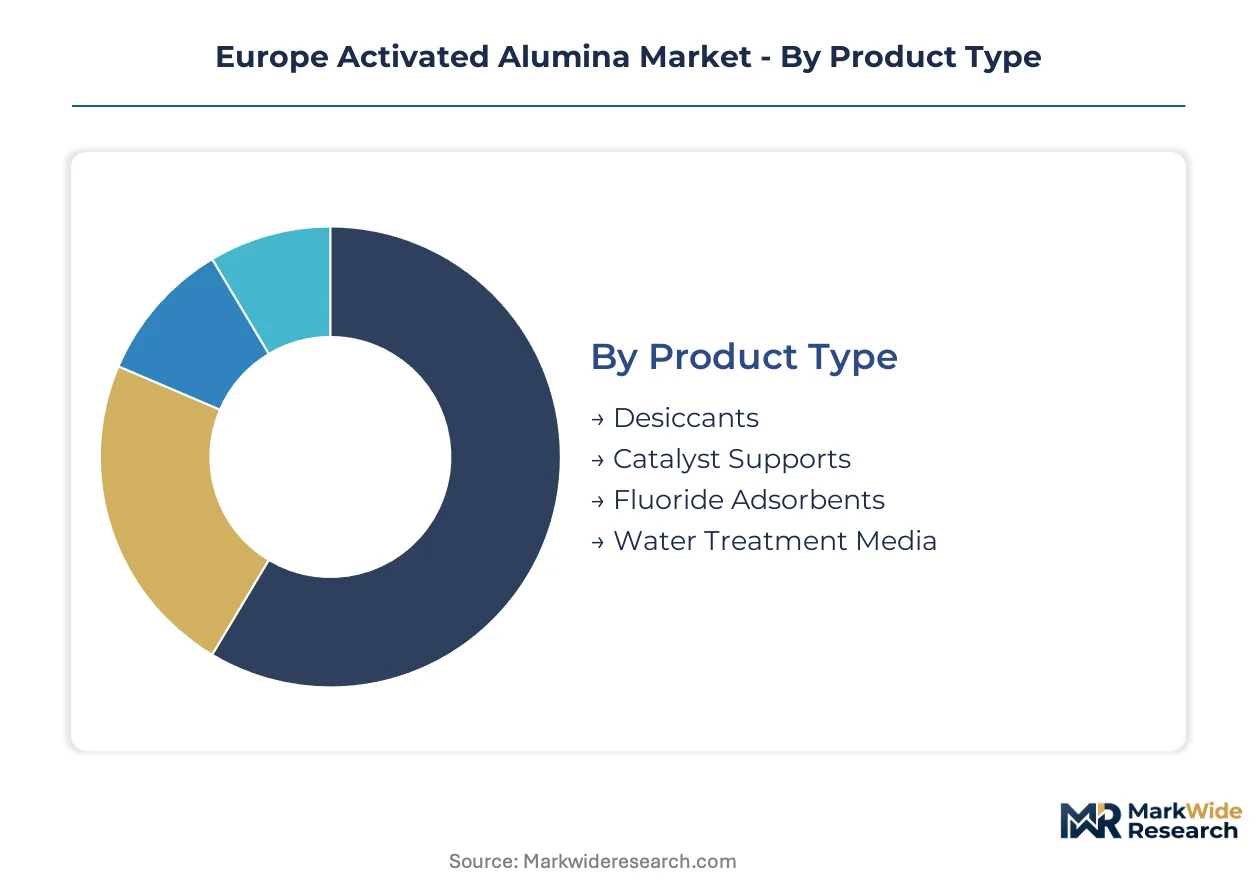
Activated alumina procurement patterns diverge sharply across end-use specifications, with REACH-compliant documentation and EMA stability guidelines fragmenting product tiers. Certification burdens concentrate in pharmaceutical and refrigeration segments, while municipal buyers prioritize volume scalability over documentation depth.
Product Type:
REACH registration requirements intensify with product purity, creating tiered compliance costs that reshape supplier economics across each grade.
- Fluoride Adsorbents:High-purity aluminum oxide pellets engineered for selective fluoride ion capture in potable water systems. German and French utilities along the Rhine corridor are scaling procurement to meet tightening EU Drinking Water Directive limits, with batch certification timelines extending order cycles by several weeks.
- Catalyst Supports:Engineered porous structures with surface areas between 150 and 350 square meters per gram, optimized for petrochemical reactor beds. European refiners retooling for biofeedstock compatibility are accelerating demand for high-purity grades that meet licensor specifications from Rotterdam to Antwerp.
- Desiccants:Moisture-adsorbing formulations for industrial refrigeration and pharmaceutical packaging, subject to EU F-Gas Regulation compatibility testing against lower-GWP refrigerant chemistries.
- Water Treatment Media:Granular activated alumina for general filtration duty, occupying mature volume positions anchored by municipal procurement cycles across Scandinavia and Central Europe.
Water treatment media sits at the top of the volume ranking, with catalyst supports climbing the fastest as refinery conversions accelerate.
Application:
Margin pools concentrate where regulatory scrutiny intersects with performance-critical duty cycles, creating distinct pricing architectures across each use case.
- Pharmaceuticals:EMA guidelines on active pharmaceutical ingredient stability mandate certified desiccant specifications for storage and transport, creating premium tiers with documentation requirements that extend fulfillment timelines.
- Water Purification:Municipal utilities across Germany, France, and Poland drive procurement volume through fluoride removal and general filtration applications, with Verband kommunaler Unternehmen members harmonizing tender specifications across state boundaries.
- Chemical Processing:Rhine corridor processors consolidate procurement through multi-year volume commitments with price adjustment clauses tied to alumina precursor indices.
- Oil & Gas:Refinery and pipeline operators utilize activated alumina for dehydration and contaminant removal, with demand tied to European energy infrastructure maintenance cycles.
Water purification commands the largest volume position, while pharmaceuticals generates the steepest margin expansion trajectory.
End User:
Procurement sophistication varies with organizational scale and regulatory exposure, fragmenting contract structures across buyer categories.
- Municipal:Public water utilities in Scandinavia and Central Europe are unbundling media replacement services from equipment supply, creating standalone service revenue pools with multi-year framework agreements.
- Pharmaceutical:Drug manufacturers and contract packaging organizations demand EMA-compliant documentation tiers, with stability testing requirements compressing qualified supplier lists.
- Industrial:Cold chain operators in France and Italy are front-loading desiccant procurement to lock in qualified supply before F-Gas Regulation compliance deadlines.
- Chemical Manufacturing:Integrated producers along the Belgian and Dutch chemical clusters leverage regional sourcing to minimize transcontinental logistics exposure.
Municipal end users anchor volume demand, with pharmaceutical buyers expanding most quickly as stability guidelines tighten.
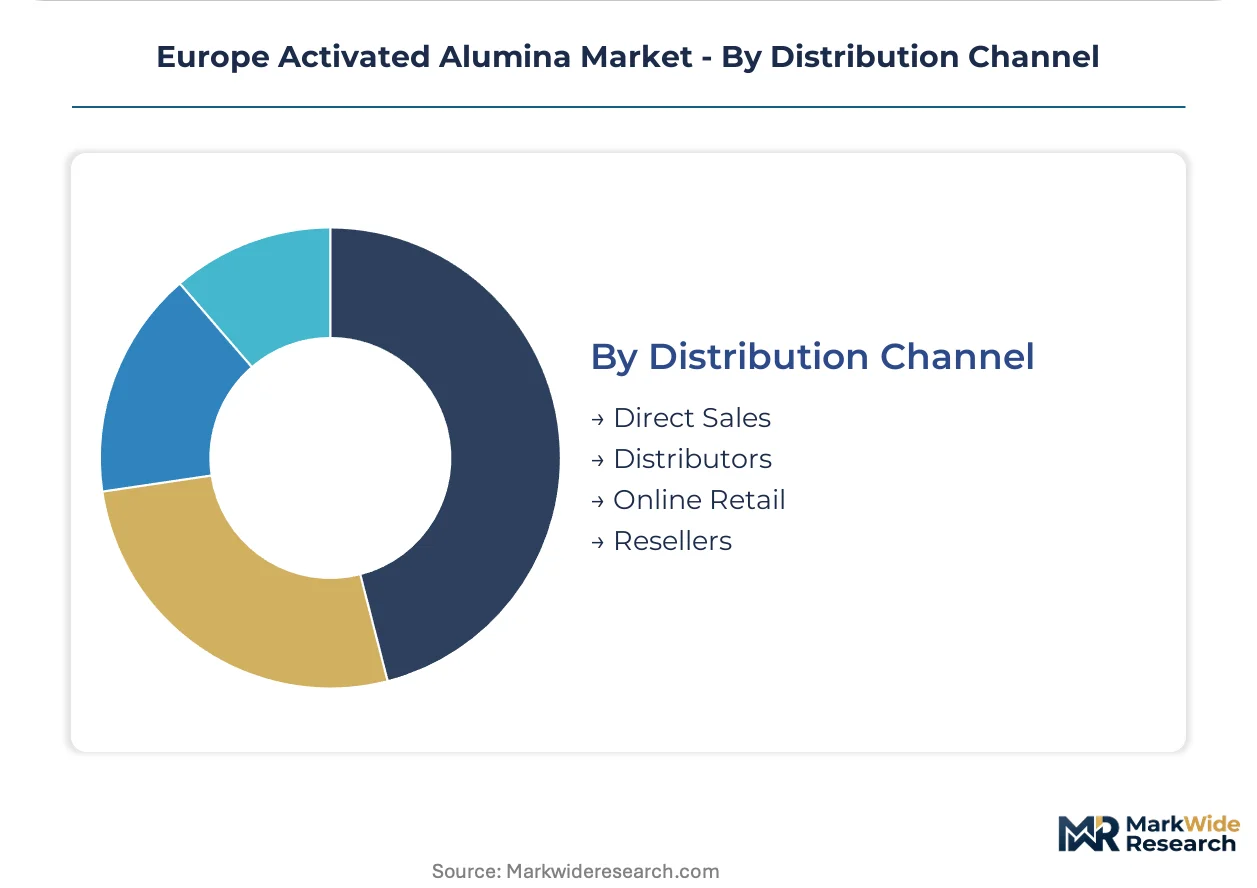
Distribution Channel:
Digital procurement platforms are compressing traditional intermediary margins, reshaping route-to-market economics across each channel.
- Direct Sales:Pellet manufacturers are establishing direct contracting relationships with municipal utilities and large chemical processors, bypassing distributor markups through digital tender platforms.
- Distributors:Traditional stock-and-resell networks retain relevance for mid-scale industrial buyers requiring technical support and smaller lot sizes.
- Resellers:Regional specialists serve niche applications with localized inventory and rapid fulfillment for maintenance-driven demand.
- Online Retail:Emerging channel for standardized desiccant specifications in pharmaceutical packaging and small-scale industrial applications.
Direct sales captures the dominant volume share, with online retail gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Activated alumina production first scaled in Germany's industrial corridor during the post-war chemicals expansion. European demand now concentrates along the Rhine and in Benelux petrochemical clusters. Regulatory fragmentation across member states shapes procurement patterns.
Germany
Municipal utilities along the Rhine corridor are scaling fluoride adsorbent procurement to meet tightened Drinking Water Directive limits. REACH registration requirements from ECHA extend batch certification timelines for suppliers entering German industrial channels. BASF SE's integrated precursor network in Ludwigshafen anchors regional supply security for high-purity grades.
France
Industrial cold chain operators are front-loading desiccant procurement ahead of F-Gas Regulation compliance deadlines. ANSM stability guidelines intersect with EMA mandates to create dual certification burdens for pharmaceutical-grade suppliers. The Paris-Saclay research cluster drives pilot programs for biofeedstock-compatible catalyst supports.
Netherlands
Rotterdam-Antwerp petrochemical licensors are retooling catalytic processes for renewable feedstock compatibility. The EU Green Deal's embodied carbon tracking rules pressure sourcing economics for bauxite-derived feedstocks entering Dutch conversion facilities. Specialty chemical manufacturers in the Belgian-Dutch border region adopt precision pelletization systems to serve regional pharmaceutical demand.
Poland
Underpenetrated municipal water treatment infrastructure presents procurement expansion potential as EU cohesion funds flow eastward. Polish utilities are harmonizing tender specifications with German Verband kommunaler Unternehmen standards. The Silesian industrial zone generates maintenance-driven demand for oil and gas dehydration applications.
Italy
Refrigeration OEMs in northern Italy are redesigning sealed system architectures for lower-GWP refrigerant compatibility. The Po Valley chemical cluster concentrates catalyst support demand from regional refiners. Italian pharmaceutical packagers are unbundling media replacement services from equipment supply contracts.
Europe Activated Alumina Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive alumina precursor networks. Tiered supplier tiers separate REACH-compliant documentation specialists from volume-focused commodity producers. Three archetypes dominate: integrated petrochemical majors controlling upstream bauxite refining, specialty chemical houses engineering high-purity catalyst grades, and regional fabricators serving maintenance-driven replacement cycles. Competitive moves concentrate on backward integration into precursor supply and multi-year procurement contracting with municipal utilities.
Among integrated chemical conglomerates, BASF SE and Evonik Industries AG exemplify the precursor-control archetype through their positions within German industrial chemistry. Honeywell International Inc. occupies a distinct tier tied to refrigeration system desiccant specifications. CHALCO Shandong Co Ltd represents the Asia-Europe supply bridge, with Sumitomo Chemical Co Ltd anchoring the catalyst support specialization vector. These four names illustrate how geographic origin and corporate structure map onto competitive positioning without requiring specific product or strategic claims.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| CHALCO Shandong Co Ltd |
| BASF SE |
| Sumitomo Chemical Co Ltd |
| Petrosadid |
| Huber Engineered Materials |
| Evonik Industries AG |
| Sorbead India |
| Axens |
| Others |
Pricing and Supply Chain Analysis
Alumina precursor indices cascading from bauxite refining hubs set the baseline for European activated alumina pricing tiers, with REACH compliance costs layering additional premiums onto pharmaceutical and refrigeration grades before they reach German municipal utilities or French cold chain operators.
Pricing Analysis
Contract-based long-term offtake agreements with price adjustment clauses dominate Rhine corridor chemical procurement, separating EMA-certified pharmaceutical desiccants from standard industrial grades through documentation depth and batch certification timelines. Price differentiation hinges on REACH registration tier and volume scale, with municipal buyers extracting discounts through consolidated Verband kommunaler Unternehmen tenders. Cost compression in water treatment media intensifies as Polish utilities harmonize specifications with German standards. Pharmaceutical packagers show least price sensitivity due to stability guideline mandates, while municipal water utilities drive hardest bargains.
Supply Chain Analysis
EU Green Deal embodied carbon tracking rules are reshaping sourcing economics for bauxite-derived feedstocks entering European conversion facilities, pressuring suppliers to document supply chain emissions. Production concentrates in Germany, Belgium, and the Netherlands, with specialty pelletization systems diffusing toward mid-scale regional fabricators. Raw material dependencies draw from Guinean and Australian bauxite, German caustic soda, and natural gas for kiln operations. Single-source vulnerability runs through precursor supply controlled by integrated chemical majors. Distribution runs through direct digital platforms for large utilities, with traditional distributors retaining mid-scale industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Western European REACH compliance costs and Eastern European cohesion fund infrastructure builds, with Poland and Czech Republic offering procurement expansion at lower certification burdens.
For Market Incumbents: Deepen backward integration into bauxite refining to secure precursor quality control against CHALCO Shandong's Asia-Europe supply bridge. Lock multi-year framework agreements with Verband kommunaler Unternehmen members before digital procurement platforms erode distributor relationships. Invest in automated pelletization systems to match Belgian-Dutch specialty manufacturers' regional service capabilities. For New Entrants and Emerging Players: Precision-controlled thermal processing technology offers entry into pharmaceutical desiccant tiers where EMA documentation requirements compress qualified supplier lists. Target Poland's underpenetrated municipal water infrastructure through EU cohesion fund procurement channels. Pursue white-label manufacturing partnerships with established REACH registrants to bypass batch certification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where thermal process engineering expertise scarcity intersects with REACH registration cost escalation. Mid-scale European fabricators with automated pelletization capability represent prime acquisition targets over the coming decade. Watch for F-Gas Regulation compliance deadline front-loading as demand inflection signal in French and Italian cold chain segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | BASF SE's Ludwigshafen precursor network demonstrates quality control from raw material through final pelletization. |
| Automated Pelletization System Deployment | Belgian-Dutch border manufacturers adopt real-time moisture monitoring to serve regional pharmaceutical demand without transcontinental logistics. |
| REACH Registration Tier Investment | ECHA's evolving SVHC candidate list forces reformulation of binder chemistries for continued German industrial channel access. |
| Direct Digital Procurement Platform Launch | Pellet manufacturers bypass distributor markups by contracting directly with municipal utilities through tender platforms. |
| Multi-Year Volume Commitment Structuring | Rhine corridor chemical processors consolidate procurement through price adjustment clauses tied to alumina precursor indices. |
Research Methodology
Direct dialogue with activated alumina plant managers, municipal water utility procurement leads, pharmaceutical packaging technical directors, and refrigeration OEM supply chain heads grounded qualitative findings in operational reality. Secondary validation drew from ECHA REACH registration databases, EU F-Gas Regulation implementation reports, customs trade data for bauxite and alumina precursor flows, and SEC filings of integrated chemical conglomerates. Bottom-up demand modeling across end-use segments triangulated against top-down European chemicals production capacity assessments.
Bottom-up segment analysis tracked fluoride adsorbent, catalyst support, desiccant, and water treatment media demand across municipal, pharmaceutical, industrial, and chemical manufacturing end users. Top-down validation referenced European petrochemical licensor specifications, EMA stability guideline evolution, and EU Drinking Water Directive implementation timelines. CAGRs derived from regression analysis of historical procurement patterns against regulatory compliance deadline schedules. Key inputs included refinery biofeedstock conversion announcements, F-Gas Regulation phasedown milestones, and cohesion fund disbursement flows to Eastern European water infrastructure.
The model holds under stable REACH registration cost trajectories and continued EU Green Deal carbon tracking implementation; deviation in bauxite supply disruptions or ECHA SVHC list acceleration would shift volume and value outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Germany Ceramic Tiles Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
North America Activated Alumina Market
Ceramics
Stoneware Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Transparent Ceramics Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
US Kaolin Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Earthenware Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
Ceramic Substrate Market