
 Canada Filtration and Separation Market | 2026-2036
Canada Filtration and Separation Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Filtration and Separation Market Insights
HEPA and sub-HEPA specification upgrades is unwinding across Canada's industrial base as manufacturers face stricter cleanroom and emissions protocols. Parker Hannifin Corp leverages its pneumatic and filtration integration to dominate aerospace and life science applications in the Greater Toronto Area. Donaldson Company, Inc. anchors its position through specialized industrial air filtration systems serving Alberta's energy corridor.
Filtration and separation encompasses the mechanical, chemical, and membrane-based processes that remove particulates, contaminants, and immiscible phases from fluid streams, with pore ratings spanning from coarse macrofiltration at 100 microns down to reverse osmosis membranes at 0.0001 microns for ionic rejection. Membrane filters and reverse osmosis technology lead capital deployment in Canadian municipal desalination and wastewater reuse projects. Liquid filters command the largest installed base across pulp and paper operations in British Columbia and Quebec, while air filtration systems sustain replacement demand cycles in mining and mineral processing facilities.
Health Canada sets national drinking water quality guidelines that provinces adopt into enforceable standards, while Environment and Climate Change Canada administers the Wastewater Systems Effluent Regulations mandating secondary treatment nationwide. The Canadian Council of Ministers of the Environment coordinates harmonized standards that reduce interprovincial compliance fragmentation for equipment suppliers. Stakeholders must monitor how the federal Clean Fuel Regulations and provincial carbon pricing mechanisms reshape investment priorities in carbon capture filtration and biogas upgrading infrastructure.
Market Dynamics
Membrane filtration technology is fragmenting Canada's water treatment infrastructure as municipalities abandon legacy sand filtration for nanofiltration and reverse osmosis systems. Health Canada's tightening contaminant thresholds are forcing wholesale equipment replacement cycles across Ontario and Alberta utilities.
Growth Catalysts
- Wastewater Systems Effluent Regulations:Environment and Climate Change Canada's secondary treatment mandate is driving membrane bioreactor installations at municipal facilities nationwide.
- Oil sands produced water volumes:Alberta's thermal extraction operations require intensive filtration for steam-assisted gravity drainage wastewater recycling.
- Clean Fuel Regulations:Federal carbon intensity requirements are accelerating carbon capture filtration and biogas upgrading equipment deployment.
Market Restraints
- Membrane fouling chemistry:Silica and organic fouling in oil sands brines accelerates replacement cycles and operating expenditure.
- Specialized polymer supply:Polyethersulfone and polyvinylidene fluoride resin production concentrates among Asian chemical manufacturers.
- Arctic logistics:Remote northern mining and military installations face 300% freight premiums on filtration consumables.
Strategic Opportunities
- First Nations water infrastructure:Federal settlement agreements are unlocking capital for decentralized membrane treatment in 63 long-term boil water advisory communities.
- Carbon capture solvents:Amine filtration and dehydration systems represent emerging demand from Saskatchewan and Alberta power generation retrofits.
- Digital twin integration:Predictive membrane lifecycle analytics are creating aftermarket service revenue streams for equipment OEMs.
Industry Challenges
- Membrane technician certification:The Canadian Water Quality Association lacks standardized training protocols for advanced oxidation system maintenance.
- Legacy lime softening integration:Municipal utilities in Quebec and Manitoba face parallel operation costs during multi-year filtration transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Filtration and Separation Market |
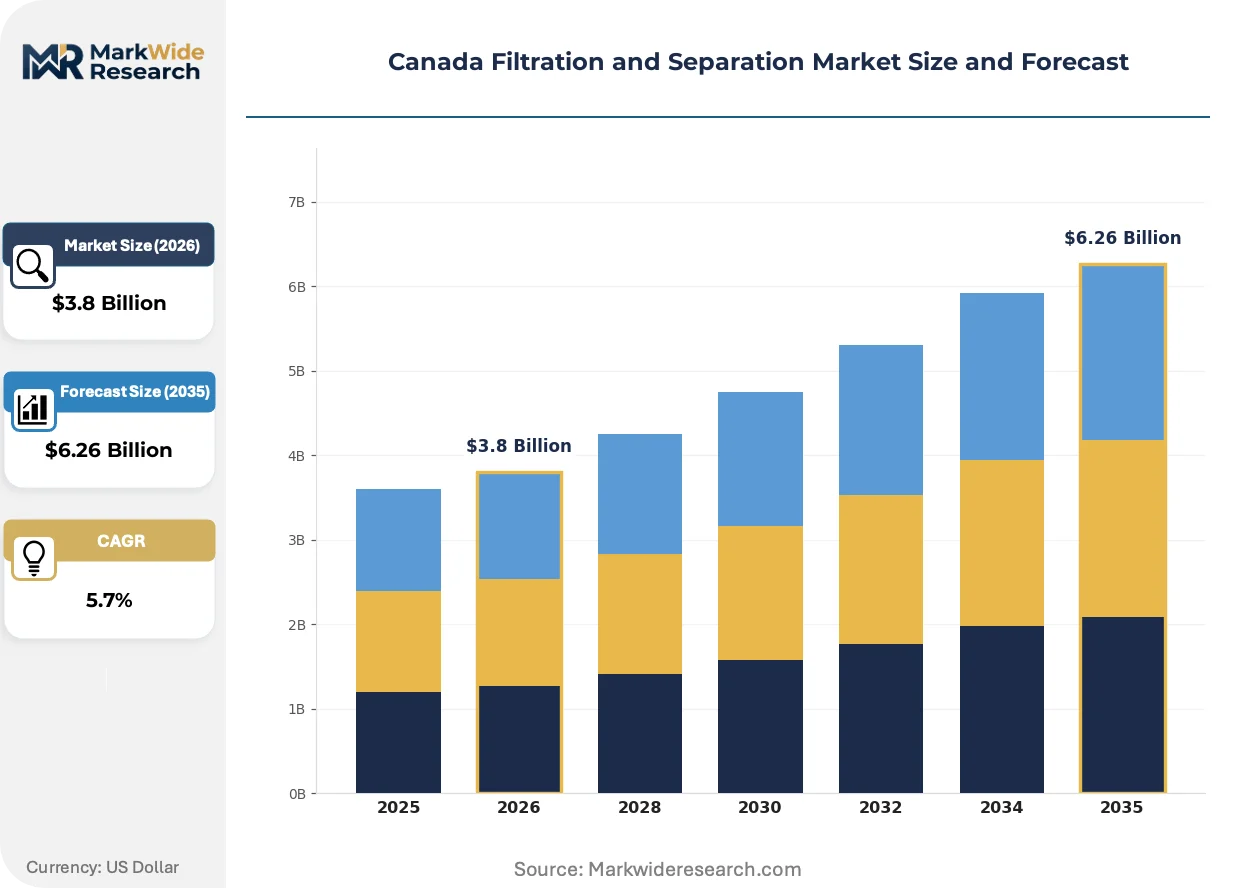
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Filters, Air Filters, Membrane Filters, Particle Separators End User: Food & Beverage, Pharmaceuticals, Water Treatment, Chemicals Technology: Microfiltration, Ultrafiltration, Reverse Osmosis, Adsorption Application: Industrial Processes, Environmental Management, Medical Devices, Oil & Gas |
| Companies Covered | Parker Hannifin Corp, Ahlstrom-Munksjö, Alfa Laval, Danaher (Pall Corporation), MANN+HUMMEL, Donaldson Company, Inc., Eaton Corporation, Filtration & Separation Technologies Inc., Freudenberg Filtration Technologies SE & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Filtration and Separation Market Trends and Innovations
Ceramic and polymeric membrane technologies are fragmenting Canada's established filtration equipment base as performance specifications diverge across industrial verticals. Digital monitoring platforms are compressing replacement cycle forecasting from annual inspections to continuous sensor feedback.
Forward osmosis draw solute recovery systems are fragmenting brine concentration economics for Alberta oil sands operators. Suncor and Canadian Natural Resources are piloting ammonia-carbonate draw solutions for produced water volume reduction. The technology is enabling zero liquid discharge configurations that were previously uneconomical with mechanical vapor recompression alone.
Health Canada's revised Guidelines for Canadian Drinking Water Quality on per- and polyfluoroalkyl substances are forcing activated carbon and anion exchange capacity expansions. Municipalities serving populations under 10,000 face disproportionate compliance costs relative to treatment scale. Ontario's Clean Water Wastewater Fund is prioritizing grants to small systems for granular activated carbon contactor installations.
Equipment-as-a-service contracting is displacing capital purchase models among British Columbia pulp and paper mills. Maintenance-inclusive membrane replacement agreements align supplier incentives with operational uptime metrics. This shift is most pronounced in Vancouver Island facilities where mill consolidation has concentrated procurement authority.
Canada Filtration and Separation Market Segmentation
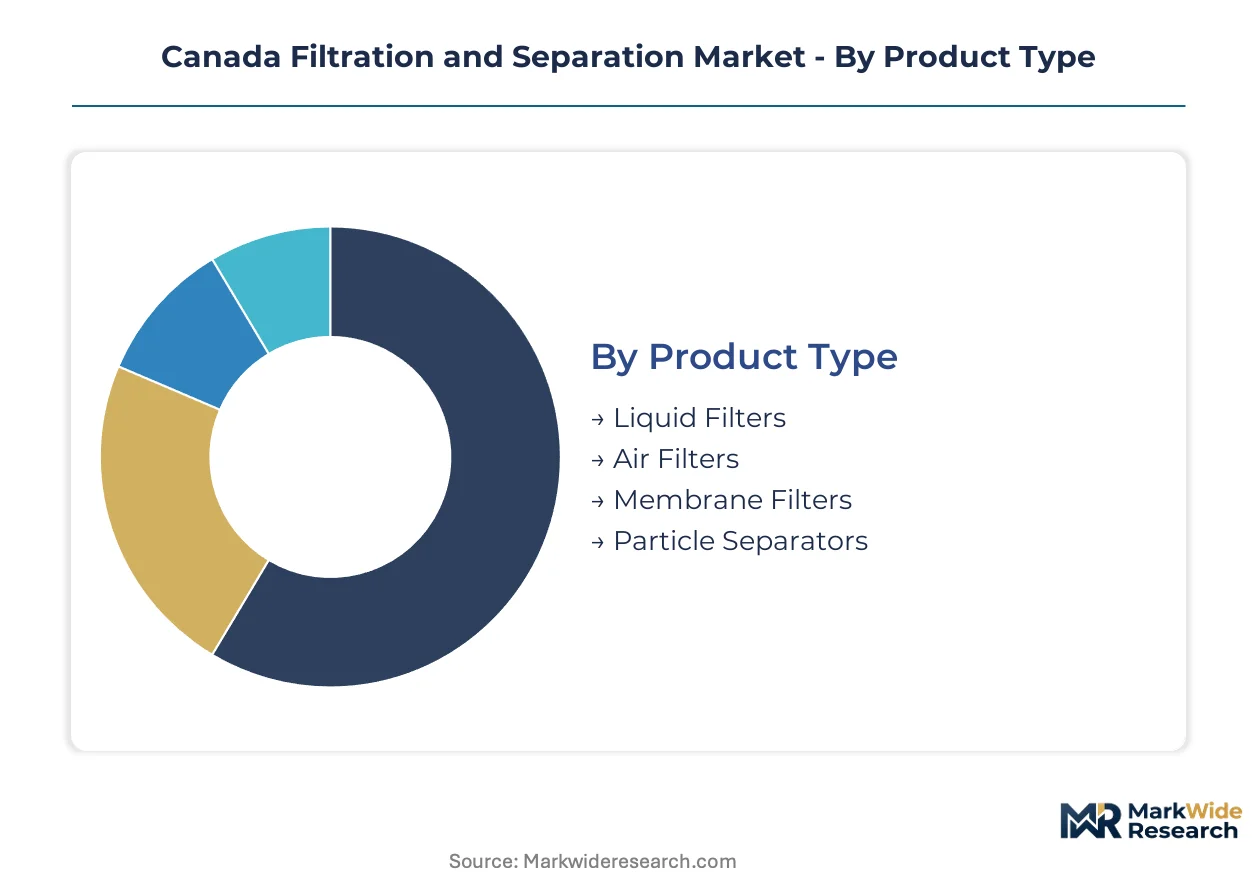
Canada's filtration and separation market fragments across four intersecting dimensions that determine equipment specification, procurement channel, and lifecycle economics. Product type governs capital intensity and replacement cadence. End user verticals dictate regulatory compliance pathways. Technology selection fixes operating expenditure profiles. Application context shapes geographic demand concentration.
Product Type:
Channel flow varies sharply by product category—membrane filters move through specialized water treatment distributors while air filtration systems route through HVAC contractors and industrial supply houses.
- Membrane Filters:Polymeric and ceramic porous structures with pore ratings from 0.1 to 10 microns separate dissolved solids and microorganisms. Ontario municipal utilities and Alberta oil sands operators are concentrating procurement for nanofiltration and reverse osmosis skids as Health Canada tightens drinking water guidelines.
- Liquid Filters:Cartridge, bag, and pressure vessel configurations remove suspended solids from process streams. British Columbia pulp mills and Quebec mining operations sustain replacement demand for high-capacity pleated media.
- Air Filters:HEPA, ULPA, and industrial dust collection systems capture particulate matter from ventilation and process exhaust. Aerospace cleanrooms in the Greater Toronto Area and Alberta energy corridor facilities drive specification upgrades.
- Particle Separators:Cyclonic, centrifugal, and gravitational systems separate immiscible phases and dense particulates. Oil sands thermal extraction operations deploy hydrocyclone trains for produced water primary treatment.
Liquid filters dominate installed base across Canadian heavy industry. Membrane filters are where expansion concentrates.
End User:
Cost tier stratification separates premium-specification pharmaceutical installations from standard-grade food processing equipment.
- Water Treatment:Municipal utilities, industrial wastewater facilities, and decentralized First Nations infrastructure deploy membrane bioreactors and advanced oxidation. Federal settlement agreements for long-term boil water advisory communities are unlocking capital for compact treatment systems.
- Oil & Gas:Alberta thermal extraction and Saskatchewan carbon capture projects require intensive filtration for produced water recycling and amine solvent purification. Steam-assisted gravity drainage operations generate the highest brine treatment volumes.
- Pharmaceuticals:Sterile manufacturing and active pharmaceutical ingredient production mandate validated filtration trains with full traceability. Toronto and Montreal biomanufacturing clusters specify single-use membrane capsules.
- Food & Beverage:Dairy processing, brewing, and bottled water operations employ sanitary-grade cartridge and membrane systems. Quebec cheese production and British Columbia craft beverage sectors sustain mid-tier equipment demand.
Water treatment commands the largest equipment installed base. Oil & gas is climbing the fastest on carbon capture and produced water tightening.
Technology:
Application context determines technology selection—industrial process streams tolerate fouling-prone microfiltration while potable water mandates reverse osmosis for ionic rejection.
- Reverse Osmosis:Dense polyamide thin-film composite membranes operating at 10-80 bar reject dissolved salts and small organics at 0.0001 micron effective pore size. Alberta oil sands zero liquid discharge pilots and Ontario municipal desalination projects are expanding membrane area.
- Ultrafiltration:Porous polymeric membranes at 0.01-0.1 micron retain colloids, proteins, and macromolecules. Food & beverage concentration and pharmaceutical pre-filtration concentrate demand.
- Microfiltration:Larger pore structures at 0.1-10 micron clarify suspensions with lower fouling propensity. Pulp and paper whitewater recycling and mining process water clarification employ crossflow configurations.
- Adsorption:Activated carbon, zeolite, and specialty resin media remove dissolved organics and trace contaminants. Health Canada PFAS guidelines are forcing granular activated carbon contactor expansions at small municipal systems.
Reverse osmosis leads capital deployment for new capacity. Adsorption is gaining share fastest on emerging contaminant compliance.
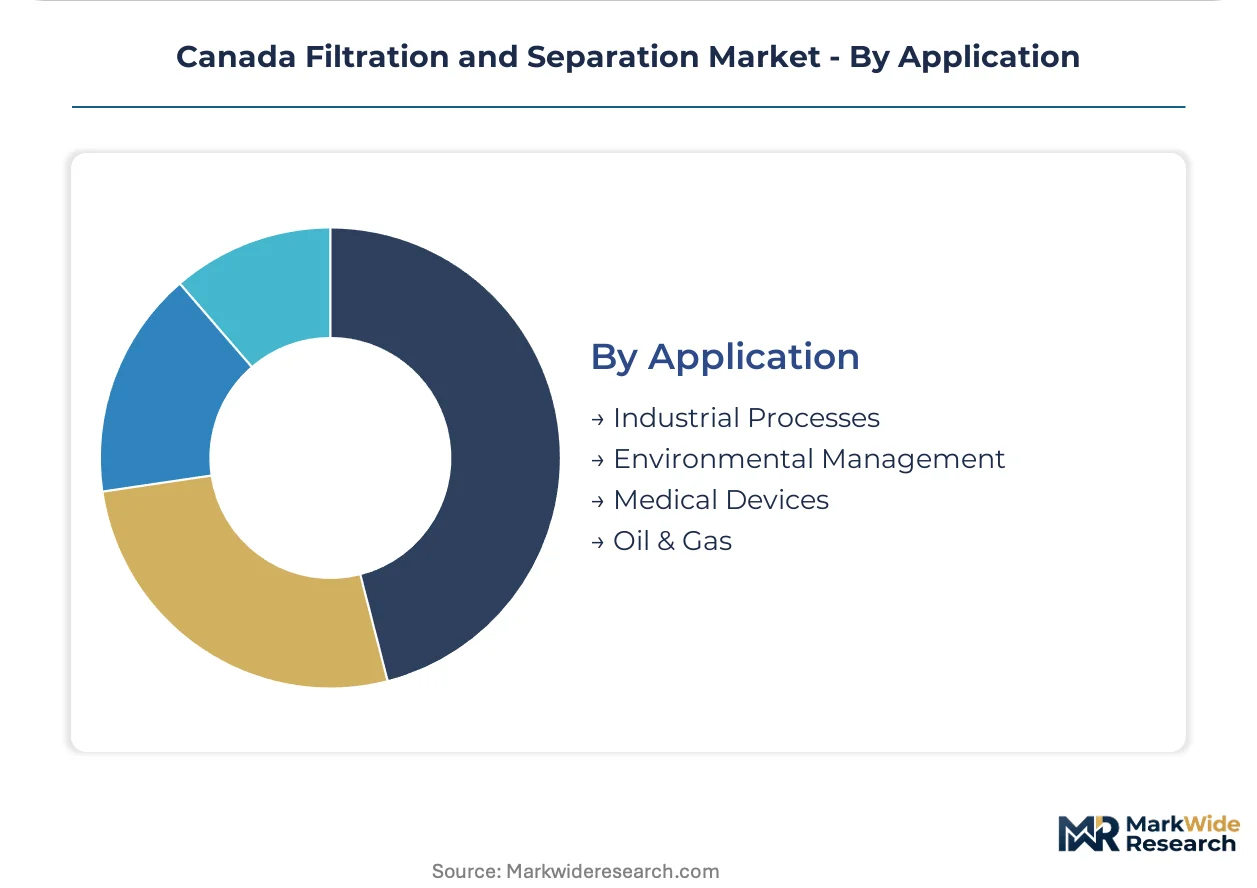
Application:
Geographic concentration aligns application type with provincial industrial structure—Alberta anchors oil & gas demand while Ontario and Quebec concentrate medical device and pharmaceutical filtration.
- Environmental Management:Wastewater treatment, emissions control, and remediation systems respond to Environment and Climate Change Canada regulations. The Wastewater Systems Effluent Regulations mandate secondary treatment upgrades nationwide.
- Industrial Processes:Manufacturing quality control, product recovery, and equipment protection filtration sustain replacement cycles. British Columbia pulp mills are shifting to equipment-as-a-service contracting models.
- Oil & Gas:Upstream production, midstream processing, and downstream refining employ specialized high-pressure and corrosion-resistant systems. Forward osmosis draw solute recovery is piloting for produced water volume reduction.
- Medical Devices:Sterile filtration, blood processing, and diagnostic equipment require validated biocompatibility and extractables documentation. Toronto and Montreal manufacturing clusters specify single-use assemblies.
Industrial processes dominate current installed base. Environmental management is where expansion concentrates on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Ontario and Quebec, where integrated suppliers serve municipal utilities and pharmaceutical manufacturers. Western provinces anchor demand for oil sands and mining applications. Atlantic Canada presents underserved infrastructure gaps.
Ontario
Toronto's biomanufacturing corridor drives single-use membrane demand for sterile filtration. Health Canada's updated drinking water guidelines force granular activated carbon upgrades at small municipal systems. The Greater Toronto Area hosts aerospace cleanroom specifications that pull HEPA filtration upgrades through the supply chain.
Alberta
Thermal extraction operations in the Athabasca oil sands generate produced water volumes requiring intensive brine treatment. Environment and Climate Change Canada's Wastewater Systems Effluent Regulations mandate secondary treatment at remote camp facilities. Calgary anchors engineering procurement for zero liquid discharge pilot projects deploying forward osmosis draw recovery.
Quebec
Montreal's pharmaceutical manufacturing cluster specifies validated filtration trains with full extractables documentation. The Canadian Council of Ministers of the Environment coordinates harmonized standards that reduce interprovincial compliance costs. Legacy lime softening systems in Quebec City and Trois-Rivières face parallel operation costs during multi-year membrane transitions.
British Columbia
Vancouver Island pulp mills shift procurement toward equipment-as-a-service contracting models. The province's CleanBC plan tightens emissions protocols for mining ventilation systems. Whistler and Vancouver municipal utilities deploy membrane bioreactors for wastewater reuse in water-scarce coastal basins.
Canada Filtration and Separation Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that integrate pneumatic and filtration capabilities across aerospace, life science, and energy verticals. The market structure shows moderate consolidation at the top tier with fragmentation among regional specialists serving municipal and First Nations infrastructure. Two strategic archetypes dominate: integrated motion and control suppliers leveraging cross-selling synergies, and dedicated filtration pure-plays with specialized oil sands and mining expertise. Competitive moves center on aftermarket service contracting and predictive analytics integration rather than capacity expansion.
Among North American-diversified industrials, Parker Hannifin Corp and Donaldson Company, Inc. occupy positions that exemplify the integrated supplier archetype. Danaher (Pall Corporation) represents the premium-tier life science specialist. Ahlstrom-Munksjö and MANN+HUMMEL sit within the European-headquartered materials and media tier that supplies membrane substrates and engineered filtration media to Canadian system integrators. Alfa Laval exemplifies the process equipment specialist with heat transfer and separation technology integration.
| Leading Market Players |
|---|
| Parker Hannifin Corp |
| Ahlstrom-Munksjö |
| Alfa Laval |
| Danaher (Pall Corporation) |
| MANN+HUMMEL |
| Donaldson Company, Inc. |
| Eaton Corporation |
| Filtration & Separation Technologies Inc. |
| Freudenberg Filtration Technologies SE & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Ninety-day membrane module lead times from Asian polymer suppliers compress pricing power for Canadian system integrators serving municipal utilities. This inventory exposure forces domestic distributors to absorb freight volatility or pass through cost surges to price-sensitive small-system operators in First Nations communities.
Pricing Analysis
Health Canada's Wastewater Systems Effluent Regulations dictates the pricing tier structure across membrane filtration equipment. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical-grade systems from industrial process units and basic municipal skids. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from membrane fouling chemistry accelerating replacement cycles in Alberta oil sands brines. Small municipal systems serving populations under 10,000 exhibit highest price sensitivity due to disproportionate compliance costs relative to treatment scale.
Supply Chain Analysis
Polyethersulfone resin inventories held at 45-60 days by Canadian distributors reflect Asian chemical manufacturer concentration. Supply draws from China, Japan, and South Korea for specialized polymer substrates. Raw material dependencies center on polyvinylidene fluoride resins, ceramic membrane substrates, and activated carbon media. Single-source vulnerability concentrates in polymeric membrane feedstock production. Distribution runs through specialized water treatment distributors for membrane filters and HVAC contractors for air filtration systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting represents a substitution threat that incumbent capital-sale suppliers must neutralize through aftermarket service integration. Incumbents face margin compression if predictive analytics platforms displace traditional replacement cycle forecasting.
For Market Incumbents: Fortify aftermarket revenue streams by integrating digital twin lifecycle analytics with membrane replacement agreements. Secure backward integration into specialty polymer distribution to offset Asian supplier concentration. Counter equipment-as-a-service entrants by bundling predictive maintenance with capital equipment sales.
For New Entrants and Emerging Players: Aftermarket service gaps in remote northern mining installations offer white-space entry points. Target First Nations decentralized water infrastructure unlocked by federal settlement agreements. Deploy mobile membrane technician certification programs to bypass Canadian Water Quality Association training bottlenecks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking filtration portfolio rationalization. Five-to-ten year viability rests on carbon capture filtration and biogas upgrading equipment deployment scaling. Monitor Clean Fuel Regulations carbon intensity compliance deadlines as inflection indicators for amine filtration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Transition | Aligns supplier incentives with operational uptime metrics at British Columbia pulp mills. |
| Predictive Analytics Integration | Compresses membrane replacement forecasting from annual inspections to continuous sensor feedback. |
| First Nations Infrastructure Focus | Captures federal settlement capital for decentralized treatment in long-term boil water advisory communities. |
| Carbon Capture Filtration Buildout | Serves Saskatchewan and Alberta power generation retrofits under Clean Fuel Regulations. |
| Ceramic Membrane Technology Expansion | Addresses silica fouling challenges in Alberta oil sands produced water recycling. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal utility procurement managers, oil sands water treatment engineers, membrane OEM technical directors, and First Nations infrastructure coordinators. Secondary validation drew from Environment and Climate Change Canada regulatory filings, Health Canada drinking water quality guidelines, Canadian Council of Ministers of the Environment harmonized standards, and provincial utility capital expenditure disclosures. Bottom-up equipment shipment tracking and top-down industrial water demand modeling were triangulated to anchor volume estimates.
Across the analysis window, forecasts segment by product type, end user vertical, technology category, and application context with particular attention to municipal versus industrial deployment patterns. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance timeline modeling. Forecast inputs incorporate membrane fouling chemistry impacts on operating expenditure and federal infrastructure settlement disbursement schedules.
Underlying assumptions cover regulatory enforcement consistency and polymer supply chain stability, with deviation risk concentrated in Arctic logistics cost volatility and membrane technician certification standardization delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Fiberglass Filters Market
Filters
Global Sterile Filtration Market
Filters
Europe Activated Carbon Market
Filters
Global High Temperature Filters Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Filter Coatings Market
Filters
Air Filtration Media Market
Filters
Drum Filters Market
Filters
Zeolite Adsorbents Market
Filters
Global Hollow Fiber Filtration Market
Filters
Coolant Filtration Systems Market
Filters
Round Plate Filter Press Market
Filters
Filter Paper Market
Filters
Global Filtration and Contamination Control Market
Filters
Global Liquid Filtration Market
Filters
Global Industrial Filters Market