
 Zeolite Adsorbents Market | 2026-2036
Zeolite Adsorbents Market Size, Share, and Industry Trends Forecast 2026-2036
Zeolite Adsorbents Market Analytics
Aftermarket service revenue for spent zeolite regeneration and reactivation is narrowing as producers build captive recycling capabilities. BASF SE leverages its Ludwigshafen integrated site to control spent catalyst recovery loops. Clariant AG anchors its position through specialized zeolite formulations for emissions control. Zeochem AG competes in medical oxygen purification niches with high-purity molecular sieve beads.
Zeolite adsorbents are crystalline aluminosilicate materials with defined pore structures typically measuring 3–10 angstroms, manufactured through hydrothermal synthesis or mined from natural deposits for selective molecular separation and catalytic applications. Synthetic zeolites command premium pricing due to tunable silica-to-alumina ratios that determine acidity and thermal stability for petrochemical catalysis. Powder and granule forms dominate environmental applications where rapid ion exchange kinetics matter, while pellet and bead configurations capture margin pools in pressure-swing adsorption systems for industrial gas separation. Water treatment and air purification applications are expanding fastest as municipalities and manufacturers face stricter effluent and emission limits.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate activated carbon or zeolite capture systems in petrochemical facilities, while REACH requires full substance registration and toxicity documentation for synthetic zeolite imports into Europe. FDA and EMA pharmaceutical purity standards also shape demand for ultra-high-purity zeolites in drug formulation and separation processes. Stakeholders must track evolving carbon border adjustment mechanisms and regional mining restrictions on natural zeolite deposits to secure feedstock access and maintain cost competitiveness.
Market Dynamics
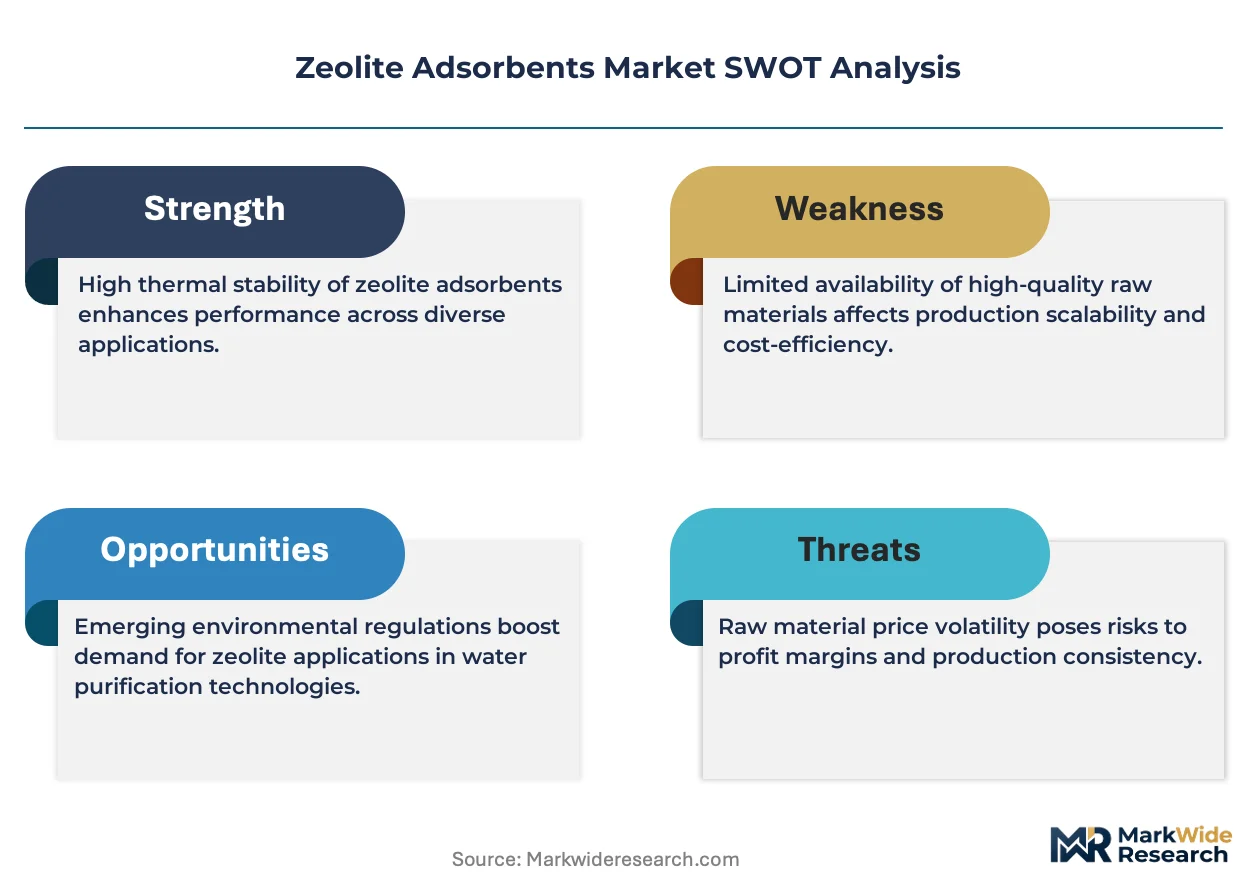
Petrochemical refiners are retooling molecular sieve units to process heavier crude slates with higher sulfur and metal content, forcing adsorbent specifications toward higher thermal stability and acid resistance.
Growth Catalysts
- EPA NESHAP mandates:Petrochemical facilities must install zeolite-based capture systems for hazardous air pollutants, creating replacement demand across US Gulf Coast refineries.
- Ethylene purification scaling:China's state-backed petrochemical complexes are importing specialized molecular sieves for polymer-grade ethylene production.
- Dual carbon targets:China's MEE enforcement of carbon intensity benchmarks is accelerating adoption of energy-efficient pressure-swing adsorption systems.
Market Restraints
- Alumina supply volatility:Synthetic zeolite production depends on refined alumina from concentrated bauxite processing regions, exposing margins to input cost swings.
- Natural zeolite deposit access:Mining restrictions in Turkey and Jordan constrain feedstock alternatives for cost-sensitive environmental applications.
- Activated carbon substitution:Steam-activated coconut shell carbons compete in VOC capture where pore size specificity matters less than capital cost.
Strategic Opportunities
- Medical oxygen PSA systems:High-purity lithium-exchanged zeolite formulations for portable oxygen concentrators remain underpenetrated in Southeast Asian healthcare infrastructure.
- EU F-Gas Regulation phase-down:The synthetic zeolite sector gains share in refrigeration dehydration as hydrofluorocarbon quotas tighten.
- Biogas upgrading convergence:Membrane-zeolite hybrid systems for biomethane purification combine selective adsorption with permeation economics.
Industry Challenges
- Hydrothermal synthesis expertise:Tight labor markets for crystallization chemists and kiln operators constrain capacity expansion timelines.
- REACH registration complexity:Full substance dossiers for synthetic zeolite variants require 18-24 month toxicology documentation cycles before EU market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zeolite Adsorbents Market |
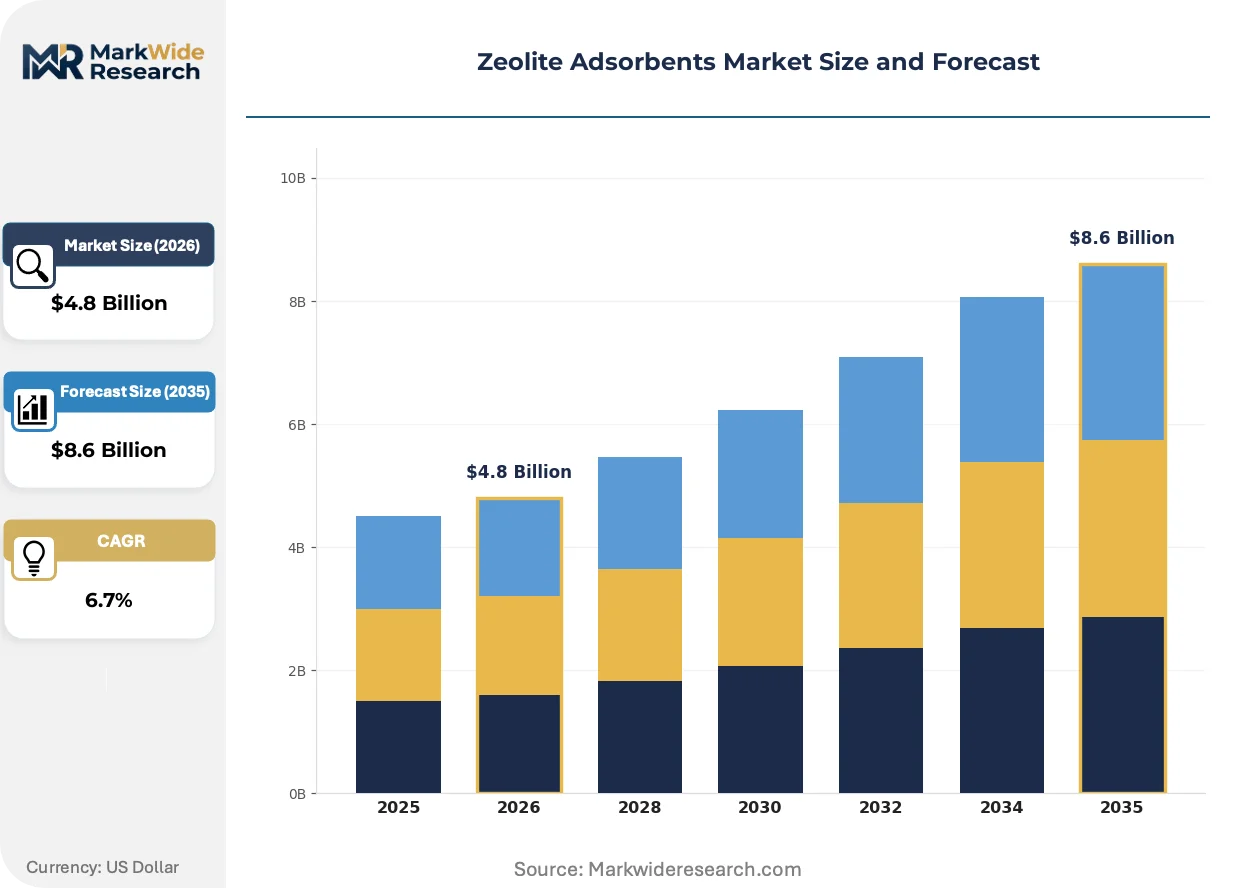
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Naturally Occurring, Synthetic Zeolites, Modified Zeolites, Zeolite Composites Application: Water Treatment, Air Purification, Catalysis, Agriculture End User: Environmental Industry, Petrochemical Industry, Pharmaceutical Industry, Food Processing Form: Powder, Granules, Pellets, Beads |
| Companies Covered | BASF SE, Honeywell International Inc., Clariant AG, W.R. Grace & Co., Arkema, Tosoh Corporation, Zeochem AG, Zeolyst International, UOP LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zeolite Adsorbents Market Evolving Landscape
Synthesis control and post-treatment chemistry are redefining performance tiers, with tailored acidity and pore architecture displacing commodity grades in high-value separations.
Core-shell zeolite architectures with mesoporous outer layers and microporous crystalline cores are rendering obsolete conventional pelletized adsorbents in catalytic cracking units. Refiners in the US and Middle East are retrofitting FCC units with these structured catalysts to handle resid feedstocks. The technology is compressing regeneration cycles and extending operational run lengths between turnarounds.
REACH authorization requirements for synthetic aluminosilicates are tightening substance documentation thresholds for imports into Europe. ECHA's expanding candidate list of substances of very high concern now captures certain zeolite manufacturing byproducts. Formulators are responding by shifting crystallization chemistries to exclude templating agents under regulatory scrutiny.
Refinery procurement teams are consolidating molecular sieve specifications across multiple process units to reduce supplier qualification overhead. Long-term framework agreements with technical service attachments are displacing spot purchasing for FCC and reforming catalysts. This consolidation is most visible in integrated sites operated by majors along the US Gulf Coast and Rotterdam-Antwerp refining cluster.
Zeolite Adsorbents Market Segmentation
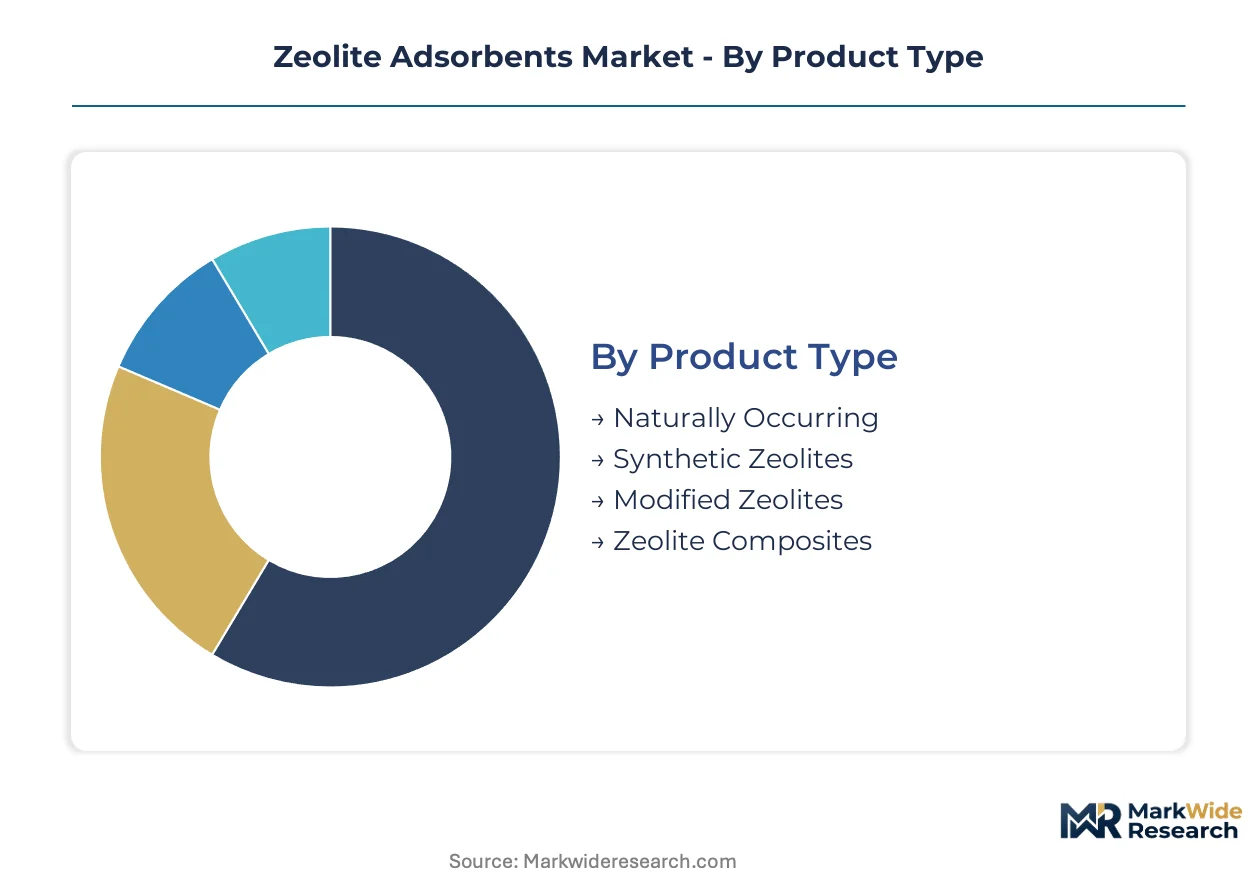
Zeolite adsorbent specifications diverge sharply across end-use contexts. Synthetic variants command premium positioning in petrochemical catalysis where tunable acidity matters, while natural grades compete on cost in bulk environmental remediation.
Product Type:
Manufacturing method determines performance tier and pricing architecture across the use-case spectrum.
- Synthetic Zeolites:Hydrothermally synthesized crystalline aluminosilicates with engineered silica-to-alumina ratios deliver precise pore architecture and thermal stability. BASF SE and Clariant AG concentrate production for FCC units and ethylene purification systems where acid site density controls catalytic selectivity.
- Modified Zeolites:Post-synthesis ion exchange and dealumination treatments tailor adsorption kinetics for pressure-swing oxygen separation. Lithium-exchanged formulations from Zeochem AG capture margin pools in portable medical concentrators across Southeast Asian healthcare infrastructure.
- Naturally Occurring:Mined clinoptilolite and mordenite deposits from Turkey and Jordan supply cost-sensitive ion exchange applications.
- Zeolite Composites:Hybrid matrices combining zeolite crystals with polymer or ceramic binders optimize mechanical strength for fluidized bed operations.
The dominant share belongs to Synthetic Zeolites, while Modified Zeolites is closing the gap fastest.
Application:
Regulatory enforcement intensity shapes demand concentration across functional domains.
- Catalysis:Fluid catalytic cracking and hydrocracking units consume specialized molecular sieve formulations to process heavier crude slates. US Gulf Coast refiners retrofit FCC systems with core-shell architectures as EPA NESHAP mandates tighten hazardous air pollutant capture requirements.
- Water Treatment:Municipal effluent remediation and industrial wastewater polishing employ natural zeolite ion exchange for ammonia and heavy metal removal. China's MEE enforcement of carbon intensity benchmarks accelerates adoption in state-backed chemical parks.
- Air Purification:VOC capture systems compete with activated carbon where pore specificity determines adsorption efficiency.
- Agriculture:Slow-release fertilizer carriers and soil amendment applications leverage cation exchange capacity in cost-sensitive bulk markets.
Catalysis captures the dominant revenue position, while Water Treatment is expanding most quickly.
End User:
Procurement sophistication and technical service requirements stratify customer segments.
- Petrochemical Industry:Integrated refiners negotiate long-term framework agreements with regeneration service attachments to minimize FCC turnaround frequency. Rotterdam-Antwerp cluster operators consolidate molecular sieve specifications across reforming and cracking units.
- Environmental Industry:Remediation contractors face margin pressure from REACH registration costs and natural deposit access constraints in Turkey.
- Pharmaceutical Industry:FDA and EMA purity standards drive demand for ultra-high-purity zeolites in active pharmaceutical ingredient separation and excipient formulations.
- Food Processing:Desiccant and purification applications in edible oil refining and beverage dehydration follow FSSAI and FDA food-contact regulations.
The Petrochemical Industry maintains the dominant share, while the Pharmaceutical Industry is climbing the fastest.
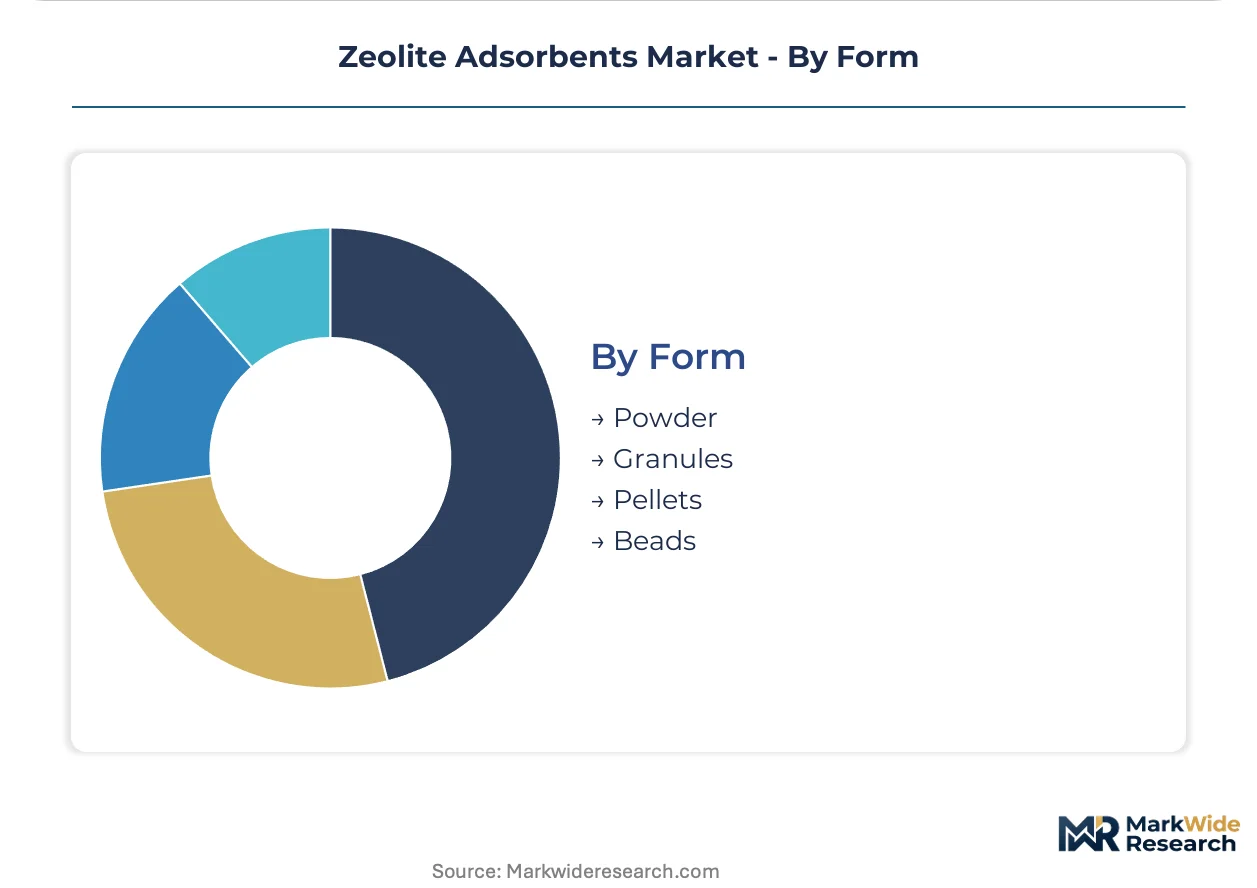
Form:
Physical configuration determines equipment compatibility and mass transfer kinetics in fixed-bed versus fluidized systems.
- Pellets:Extruded cylindrical forms optimize pressure drop characteristics in large-scale PSA hydrogen purification units. China's state-backed ethylene complexes specify pelletized molecular sieves for polymer-grade production trains.
- Beads:Spherical configurations minimize attrition in moving-bed applications and deliver uniform flow distribution. Medical oxygen concentrator manufacturers specify bead diameters for optimal lithium-exchange zeolite packing density.
- Powder:Fine particulate grades maximize surface area for rapid ion exchange in batch water treatment processes.
- Granules:Intermediate sizing balances mechanical durability with adsorption kinetics in environmental remediation columns.
Pellets hold the dominant volume position, while Beads is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in environmental remediation show acute price sensitivity to natural zeolite grades, while petrochemical refiners absorb premium synthetic pricing for FCC catalysts without volume elasticity.
United States
EPA NESHAP mandates on hazardous air pollutants drive replacement demand across Gulf Coast refineries. The regulations force retrofitting of fluid catalytic cracking units with advanced molecular sieve systems. Houston-area petrochemical complexes consolidate procurement specifications across multiple process units to reduce supplier qualification overhead.
China
State-backed ethylene purification complexes scale imports of specialized molecular sieves for polymer-grade production. MEE enforcement of dual carbon intensity benchmarks accelerates adoption of energy-efficient pressure-swing adsorption systems. Yangtze River Delta chemical parks retrofit molecular sieve units to meet stricter effluent standards.
Germany
REACH registration complexity for synthetic zeolite variants extends toxicology documentation cycles to 18-24 months before EU market entry. ECHA's expanding candidate list of substances of very high concern captures certain manufacturing byproducts. Ludwigshafen chemical cluster operators leverage integrated sites to control spent catalyst recovery loops.
Saudi Arabia
Refinery procurement teams negotiate long-term framework agreements with technical service attachments for FCC catalysts. The kingdom's downstream expansion programs import specialized formulations for resid feedstock processing. Jubail Industrial City complexes adopt core-shell zeolite architectures to handle heavier crude slates.
India
Municipal water treatment authorities deploy natural zeolite ion exchange systems for ammonia removal in cost-sensitive bulk markets. FSSAI regulations on food-contact materials shape specifications for desiccant applications in edible oil refining. Gujarat chemical parks test hybrid membrane-zeolite systems for industrial wastewater polishing.
Zeolite Adsorbents Market Competitive Landscape
Capability concentration sits with specialized formulation developers; scale advantage sits with integrated chemical majors. The market structures around three tiers: global diversified conglomerates with captive synthesis capacity, mid-size specialists in modified zeolite chemistries, and regional natural zeolite miners. Strategic moves center on backward integration into alumina supply and technology licensing for core-shell architectures.
Within the integrated chemical major tier, BASF SE and Clariant AG exemplify archetypes combining synthesis scale with regeneration service capabilities. Zeochem AG occupies a specialist position in high-purity formulations. These three represent distinct competitive vectors: Ludwigshafen-based integrated production, Swiss precision in emissions-control grades, and Swiss-American focus on medical oxygen purification niches.
| Leading Market Players |
|---|
| BASF SE |
| Honeywell International Inc. |
| Clariant AG |
| W.R. Grace & Co. |
| Arkema |
| Tosoh Corporation |
| Zeochem AG |
| Zeolyst International |
| UOP LLC |
| Others |
Value Network & Pricing Analysis
Ludwigshafen's integrated chemical cluster anchors European synthetic zeolite capacity, with BASF SE's captive alumina supply conferring downstream pricing power against Asian imports. This concentration enables premium positioning for FCC catalyst formulations while forcing cost-sensitive natural zeolite buyers toward Turkish and Jordanian deposit alternatives.
Pricing Analysis
Spent catalyst regeneration service contracts drive lifetime value for integrated producers. Three-tier pricing structure across premium synthetic, modified specialty, and natural bulk grades separates petrochemical refiners from municipal water authorities. Cost compression in natural zeolite ion exchange reflects mining restrictions in Turkey. Environmental contractors show acute price sensitivity; integrated refiners absorb premium positioning without volume elasticity.
Supply Chain Analysis
Export control regimes on hydrothermal synthesis equipment limit technology transfer to emerging producers. Synthetic zeolite manufacturing draws from concentrated bauxite processing in Guinea, Australia, and China; natural clinoptilolite mining rests on Turkish and Jordanian deposit access. Single-source vulnerability in refined alumina supply exposes margins to input cost swings. Distribution runs through long-term framework agreements with technical service attachments for major petrochemical complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zeolite adsorbent incumbents face sustained substitution pressure from steam-activated coconut shell carbons in VOC capture applications where pore specificity matters less than capital cost. Defensive positioning requires strategic moves before carbon border mechanisms reshape competitive economics.
For Market Incumbents: Entrench through backward integration into alumina supply and captive spent catalyst recovery loops. BASF SE's Ludwigshafen model demonstrates how controlling regeneration cycles compresses customer turnaround frequency. Counter activated carbon substitution by emphasizing EPA NESHAP compliance bundling with molecular sieve system retrofits.
For New Entrants and Emerging Players: Pursue lithium-exchanged zeolite formulations for portable medical oxygen concentrators across Southeast Asian healthcare infrastructure. Zeochem AG's specialist positioning reveals margin pools in underpenetrated PSA niches. Partner with regional hospital procurement networks to bypass established petrochemical supply relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with REACH registration dossiers already filed. The five-to-ten year viability window rewards targets with core-shell architecture licensing capabilities. Watch ECHA's expanding candidate list of substances of very high concern as inflection indicator for crystallization chemistry shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | Captive refined alumina access insulates margins from bauxite processing concentration in Guinea and Australia. |
| Core-Shell Architecture Licensing | Mesoporous outer layer patents enable resid feedstock processing for US and Middle East FCC retrofits. |
| REACH Registration Dossier Completion | ECHA substance documentation clears 18-24 month toxicology cycles for EU market entry. |
| Long-Term Framework Agreements with Service Attachments | Technical service bundling displaces spot purchasing across Rotterdam-Antwerp refining clusters. |
| Biogas Upgrading Hybrid System Development | Membrane-zeolite convergence captures biomethane purification economics as EU F-Gas Regulation tightens. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across petrochemical procurement teams, molecular sieve plant managers, environmental remediation contractors, and pharmaceutical formulation scientists. Secondary validation drew from EPA NESHAP enforcement records, ECHA substance registration databases, USGS mineral commodity summaries, and customs trade data for synthetic zeolite imports. Bottom-up capacity assessments and top-down demand modeling were triangulated against refinery FCC unit retrofit announcements.
Calibration against historical capacity utilization and disclosed framework agreement volumes anchored projections across the analysis window. Segmentation dimensions included manufacturing method, application function, end-use industry procurement sophistication, and physical form configuration. CAGRs were derived from elasticity-adjusted demand curves incorporating alumina input cost trajectories and regulatory enforcement intensity indices for environmental remediation.
Macroeconomic conditions sit as an overlay; deviation in bauxite pricing, carbon border adjustment implementation timelines, or refinery throughput cycles would shift the trajectory. Cross-checking against disclosed petrochemical capital expenditure plans and ECHA authorization timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Hollow Fiber Filtration Market
Filters
Coolant Filtration Systems Market
Filters
Industrial Filter Paper Market
Filters
Diatomaceous Filter Aid Market
Filters
Europe Industrial Air Filtration Market
Filters
Global Industrial Filters Market
Filters
Filter Paper Market
Filters
Global Liquid Filtration Market
Filters
Fabric Filters Market
Filters
Global Gas Phase Filtration Market
Filters
Fabric Filter System Market
Filters
Global Pleated Filters Market
Filters
Color Filter Glass Market
Filters
Hydraulic Filters Market
Filters
Respirator Cartridges and Filters Market
Filters
Intake Filter Media Market