
 Europe Industrial Air Filtration Market | 2026-2036
Europe Industrial Air Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Air Filtration Market Intelligence
Asset-light leasing and performance-contracting models are reshaping competitive entry in European industrial air filtration, allowing mid-scale operators to deploy advanced systems without heavy capital outlay. Camfil AB leverages its Nordic manufacturing footprint to sustain premium positioning across pharmaceutical and food-grade installations. MANN+HUMMEL GmbH anchors its competitiveness through deep integration with automotive OEM supply chains. Freudenberg Group differentiates via specialized membrane and chemical filtration media developed for VOC-intensive process industries.
Industrial air filtration encompasses engineered systems that remove particulate matter, gaseous contaminants, and biological agents from process and ambient air streams, typically achieving capture efficiencies from MERV 11 through HEPA H14 grades depending on pore structure and media composition. These installations protect equipment integrity, ensure occupational exposure limits, and maintain product purity in controlled manufacturing environments. HEPA filters and activated carbon filters command the dominant share of replacement revenue, with electrostatic precipitators gaining traction in high-temperature metalworking applications where pressure-drop sensitivity constrains mechanical alternatives. Baghouse filters retain cost advantages in bulk mineral and cement processing, though margin pools increasingly shift toward integrated monitoring and predictive maintenance services bundled with media supply.
The EU Green Deal and F-Gas Regulation are tightening permissible emission thresholds for industrial VOC and particulate releases, compelling facility upgrades across Germany, Poland, and Italy. ECHA REACH compliance adds material disclosure requirements that filter manufacturers must embed into supply chain documentation. Stakeholders should monitor how CSRD sustainability reporting obligations redirect procurement criteria toward lifecycle carbon metrics and circular media recovery programs rather than upfront equipment cost alone.
Market Dynamics
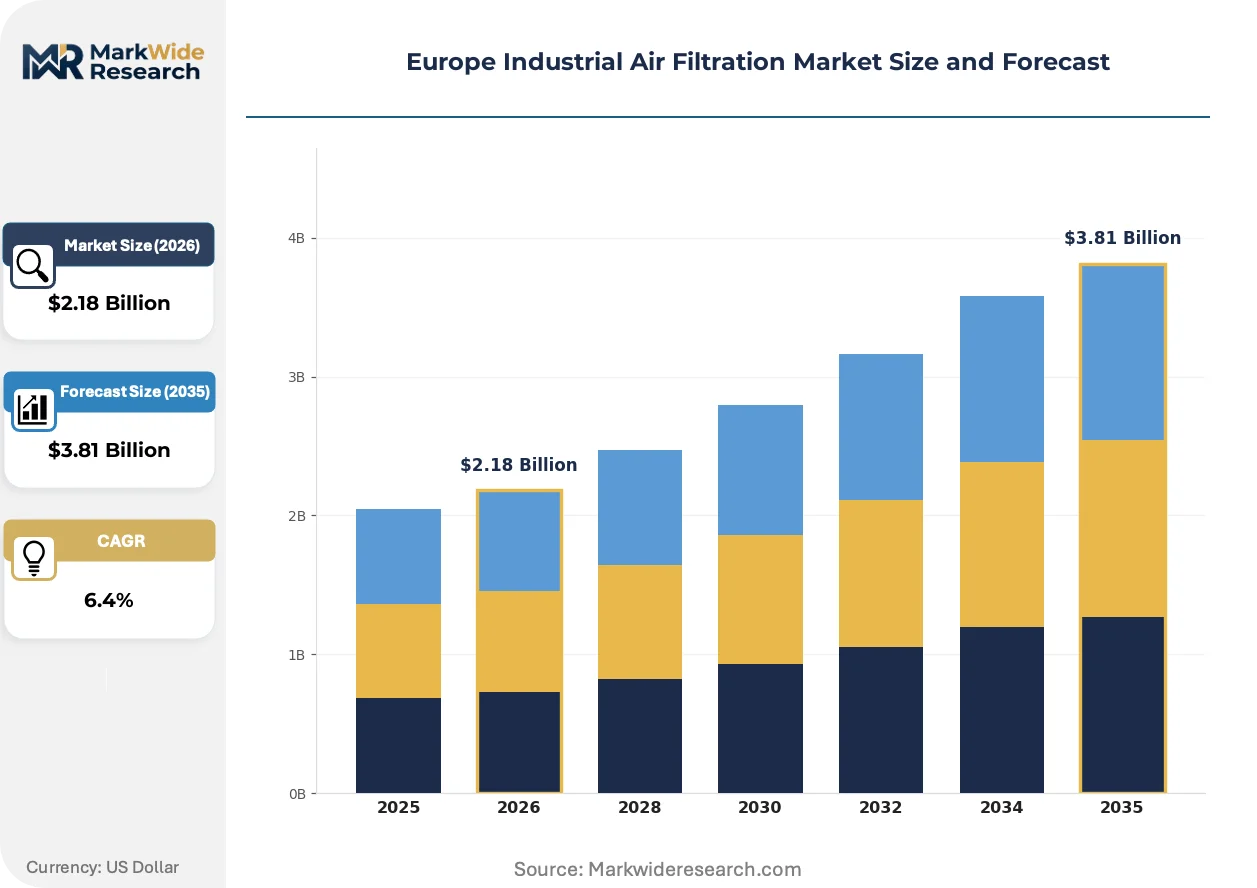
EU F-Gas Regulation and the Green Deal are compressing replacement cycles while forcing facility upgrades across German automotive clusters and French pharmaceutical corridors, creating a structural pull toward premium filtration media and integrated monitoring services.
Growth Catalysts
- REACH compliance mandates:ECHA disclosure requirements for filter materials are compelling manufacturers to upgrade supply chain documentation, driving procurement of certified media across chemical processing installations.
- Cleanroom expansion:Sterile manufacturing requirements in German and French pharmaceutical corridors are accelerating HEPA filter deployment for aseptic filling and biologics production.
- Electrostatic precipitators:High-temperature metalworking applications in Polish and Italian steel clusters are adopting ESP systems where pressure-drop sensitivity constrains mechanical baghouse alternatives.
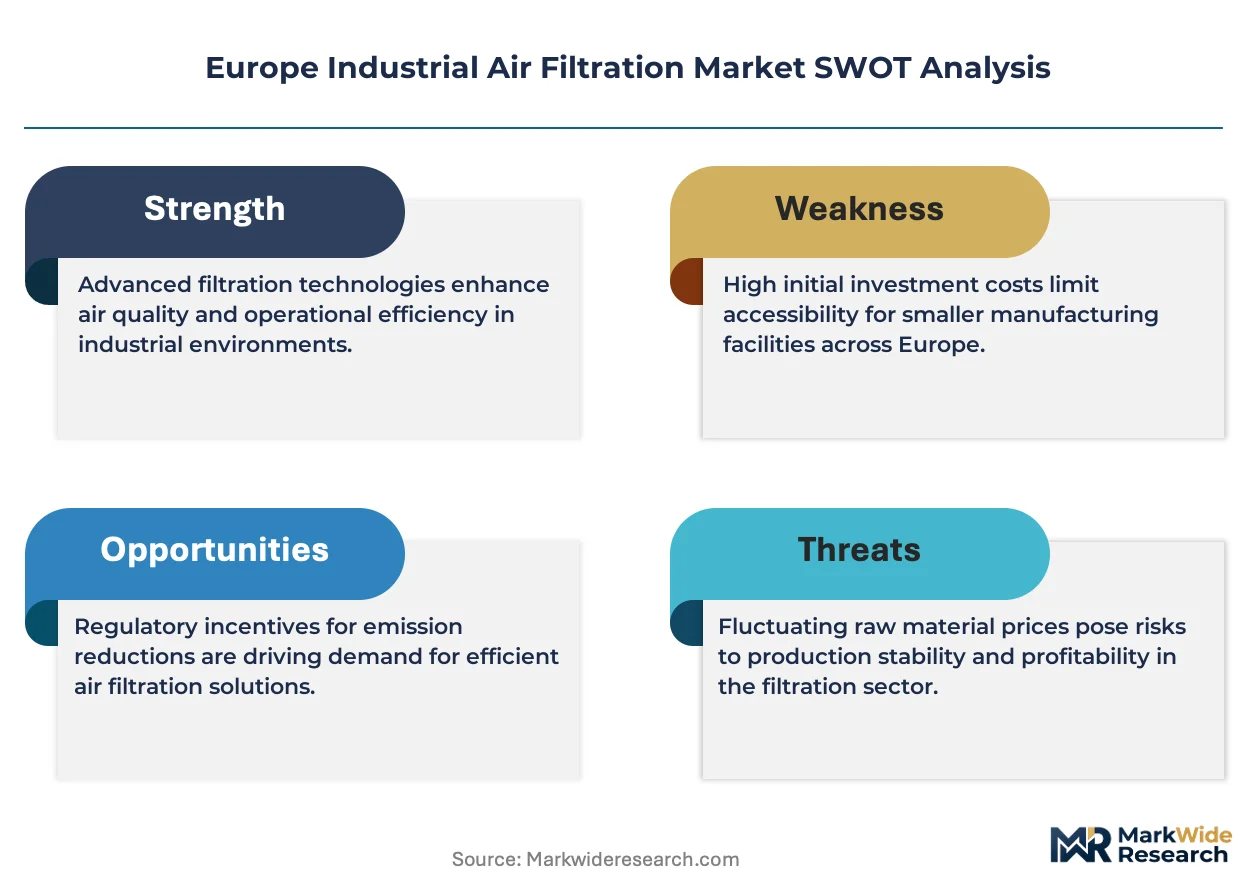
Market Restraints
- Activated carbon supply concentration:Coconut shell and coal-based carbon sourcing concentrates in Southeast Asian suppliers, exposing European filter manufacturers to freight cost volatility and extended lead times.
- Membrane material cost structure:PTFE and fiberglass media require petroleum-derived feedstocks, tying margin stability to hydrocarbon price swings that compress mid-tier system profitability.
- Retrofit technical limitations:Legacy ductwork configurations in aging Italian and Spanish industrial facilities constrain drop-in HEPA upgrades without structural HVAC modifications.
Strategic Opportunities
- Polish industrial corridor penetration:Coal-to-gas transition programs and EU cohesion fund infrastructure investments are opening premium filtration procurement in Silesian manufacturing zones previously served by basic baghouse systems.
- Predictive maintenance convergence:IoT sensor networks and AI-driven pressure-drop analytics are enabling filter-as-a-service models that bundle media replacement with uptime guarantees.
- CSRD reporting tailwinds:Corporate Sustainability Reporting Directive obligations are redirecting procurement criteria toward lifecycle carbon metrics and circular media recovery programs rather than upfront equipment cost.
Industry Challenges
- Certification timeline compression:EN 1822 HEPA testing and CE marking procedures for novel nanofiber media are extending product launch cycles, delaying revenue recognition for R&D-intensive suppliers.
- Integration complexity with legacy Building Management Systems:New filtration monitoring platforms require protocol translation layers to communicate with 1990s-era Siemens and Honeywell installations common in German automotive plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Air Filtration Market |
| Market Size in 2026 | $2.18 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, Electrostatic Precipitators, Baghouse Filters End User: Manufacturing, Pharmaceutical, Food Processing, Automotive Technology: Mechanical Filtration, Chemical Filtration, Biological Filtration, Membrane Filtration Application: Air Quality Control, Dust Removal, Odor Control, VOC Removal |
| Companies Covered | Camfil AB, MANN+HUMMEL GmbH, Donaldson Company, Inc., Freudenberg Group, Honeywell International Inc., Parker Hannifin Corporation, AAF International, Daikin Industries, Ltd., Nordic Air Filtration A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Air Filtration Market Strategic Shifts & Innovations
Digital twin architectures and membrane material science are converging to transform how European industrial operators specify, monitor, and maintain air filtration assets across regulated manufacturing environments.
Computational fluid dynamics is virtualizing filter selection and ductwork design processes that previously required physical prototyping and on-site pressure mapping. Automotive OEM cleanroom engineers in Stuttgart and Wolfsburg are deploying CFD simulations to optimize HEPA bank configurations before capital deployment, compressing project timelines and reducing commissioning failures. This virtualization is displacing traditional specifier-consultant relationships with software-enabled self-service tools that OEMs license directly.
F-Gas Regulation phase-down schedules are tightening permissible emissions thresholds for industrial VOC releases, compelling activated carbon filter upgrades across German chemical processing and Italian coating operations. ECHA enforcement of material disclosure requirements adds documentation burdens that filter manufacturers must embed into supply chain traceability systems. Pharmaceutical and food-grade installations face the steepest compliance ramps, driving procurement toward suppliers with pre-validated REACH dossiers.
Asset-light leasing structures are displacing capital purchase models in mid-scale manufacturing facilities lacking balance sheet capacity for premium system deployment. German automotive tier suppliers and French contract manufacturers are contracting filtration performance through opex-based agreements that bundle media supply with predictive maintenance and regulatory compliance reporting. This servitization concentrates in industrial clusters where CSRD sustainability disclosure obligations elevate total-cost-of-ownership visibility above upfront equipment pricing.
Europe Industrial Air Filtration Market Segmentation
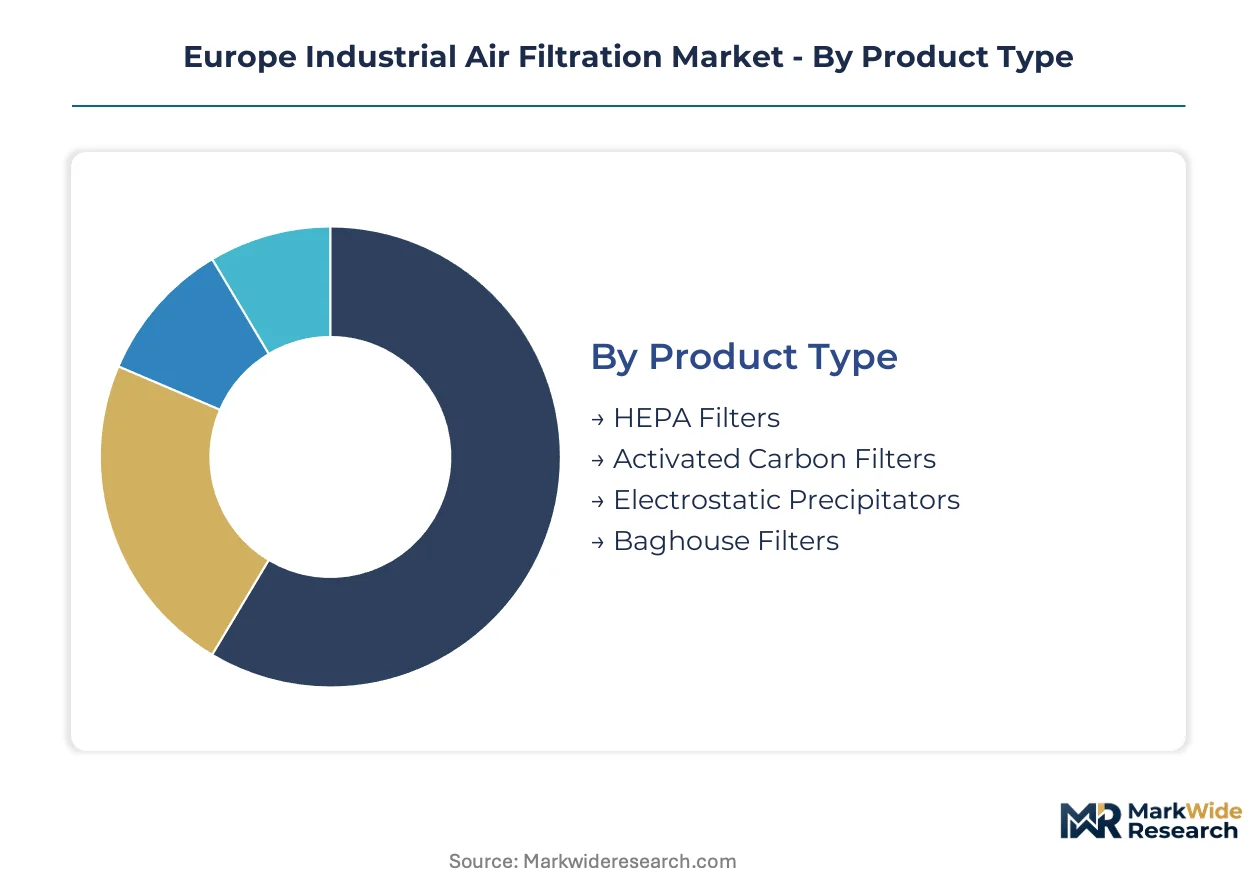
Segmentation in European industrial air filtration reveals how replacement cycles, regulatory thresholds, and process-specific contamination risks fragment procurement patterns across German automotive clusters and French pharmaceutical corridors. Filter media selection, technology architecture, and end-use compliance requirements each create distinct margin pools and service attachment opportunities.
Product Type:
After-sales intensity varies sharply across filter categories, with HEPA and activated carbon systems demanding scheduled media replacement programs while electrostatic precipitators concentrate revenue in electrode maintenance contracts.
- HEPA Filters:Pleated fiberglass or PTFE membrane media achieving H13-H14 capture efficiencies for particles down to 0.3 microns. German pharmaceutical cleanrooms in Ludwigshafen and French biologics facilities near Lyon are accelerating procurement for aseptic filling operations under tightening EU GMP Annex 1 revisions.
- Activated Carbon Filters:Impregnated coconut shell or coal-based carbon beds adsorbing VOCs and gaseous contaminants through physisorption and chemisorption mechanisms. Italian coating operations and German chemical processing clusters face compressed replacement cycles under F-Gas Regulation phase-down schedules.
- Electrostatic Precipitators:Corona discharge systems ionizing particulate matter for collection on charged plates, deployed where pressure-drop sensitivity constrains mechanical alternatives.
- Baghouse Filters:Woven or felt fabric media in tubular configurations, retaining cost advantages in Polish cement processing and Spanish mineral extraction where particulate loading is extreme.
HEPA filters hold the largest share; momentum sits with activated carbon systems as VOC compliance tightens.
End User:
Cost tier stratification separates premium-certified installations from standard industrial deployments, with pharmaceutical and food-grade facilities absorbing 3-4x media costs for validated supply chains.
- Manufacturing:General industrial facilities spanning metal fabrication, electronics assembly, and plastics processing. German Mittelstand machine shops and Polish Silesian metalworking clusters drive mid-tier baghouse and cartridge filter procurement.
- Pharmaceutical:Sterile manufacturing environments requiring EN 1822-validated HEPA banks, continuous monitoring, and documented filter integrity testing. French vaccine production corridors and German biologics hubs command premium service contracts with guaranteed uptime clauses.
- Food Processing:Dairy, beverage, and packaged goods facilities managing biological contamination risks and odor control. Italian Parmigiano-Reggiano aging facilities and Dutch dairy processors prioritize activated carbon for volatile organic compound management.
- Automotive:Paint shops, powertrain assembly, and battery manufacturing cleanrooms. Stuttgart and Wolfsburg OEM clusters are deploying computational fluid dynamics-optimized HEPA configurations for EV battery dry room operations.
Manufacturing absorbs the highest volume; pharmaceutical commands the steepest margin expansion.
Technology:
Application severity determines technology selection, with membrane and chemical filtration capturing value in corrosive or high-purity process streams where mechanical media degrade rapidly.
- Mechanical Filtration:Depth and surface filtration using fibrous media, mesh screens, or granular beds to capture particulate matter through interception, impaction, and diffusion. Polish coal-to-gas transition programs are displacing legacy mechanical systems with higher-efficiency alternatives.
- Chemical Filtration:Adsorptive and absorptive media targeting molecular contaminants through activated carbon, alumina, or impregnated substrates. German chemical processing corridors along the Rhine deploy chemical filtration for chlorine and sulfur compound removal.
- Biological Filtration:Bio-trickling filters and bioscrubbers employing microbial cultures to metabolize odorous or hazardous compounds. Dutch agro-industrial facilities and Danish wastewater treatment plants lead adoption for ammonia and hydrogen sulfide control.
- Membrane Filtration:Microporous and nanoporous barriers achieving sub-micron separation without depth loading. Spanish desalination pre-treatment and Italian pharmaceutical water-for-injection systems are expanding PTFE membrane procurement.
Mechanical filtration dominates installed base; membrane systems are climbing the fastest on purity requirements.
Application:
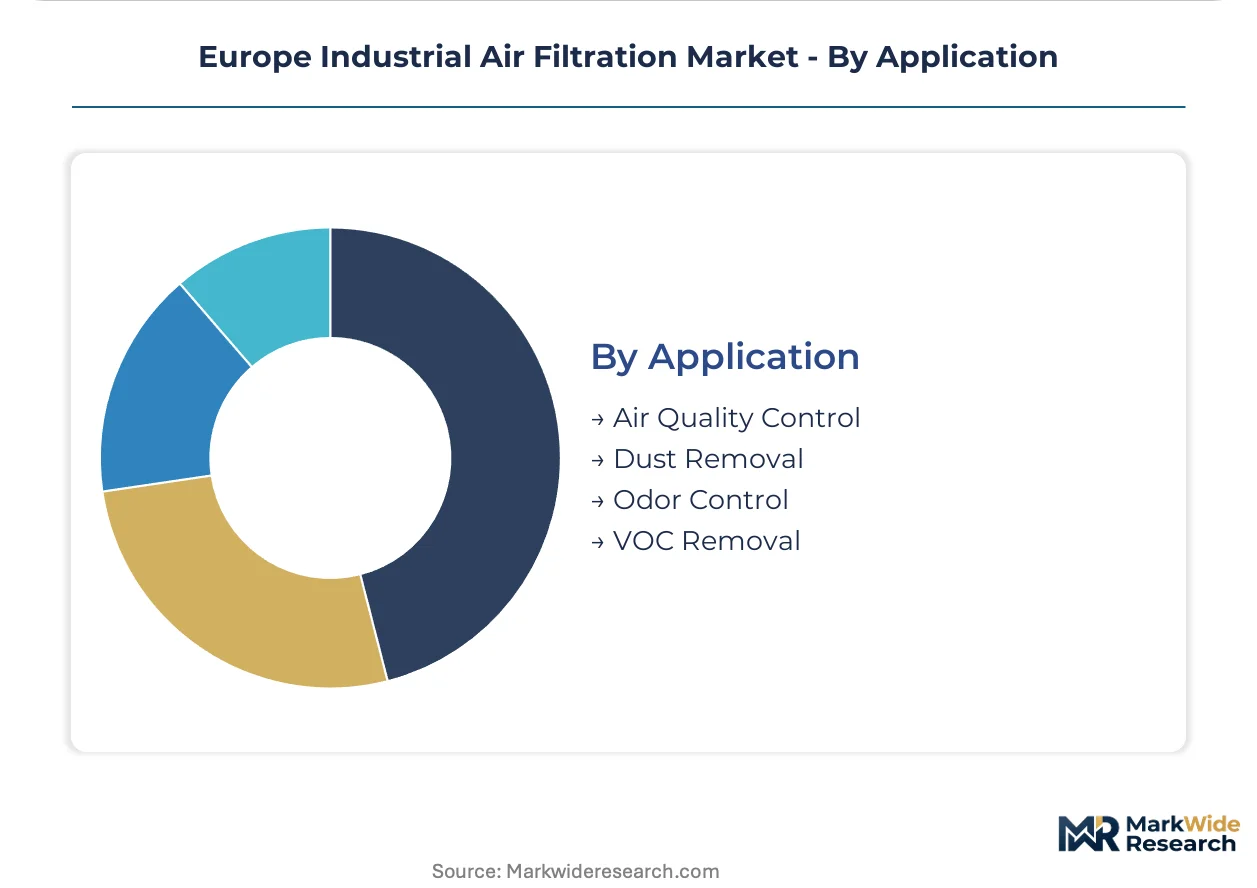
Geographic concentration of regulated industries shapes application demand, with dust removal concentrated in Central European manufacturing zones and VOC control expanding in Mediterranean coating and chemical corridors.
- Air Quality Control:Comprehensive ambient and process air management integrating particulate, gaseous, and biological control. German automotive paint shops and French semiconductor fabs deploy multi-stage systems with real-time monitoring.
- Dust Removal:Particulate capture in abrasive, cutting, grinding, and conveying operations. Italian marble processing in Carrara and Spanish ceramic tile manufacturing in Castellón drive heavy-duty baghouse specifications.
- Odor Control:Nuisance and hazardous odor mitigation through adsorption, absorption, or biological oxidation. Belgian rendering plants and Dutch food processing corridors face intensifying neighbor complaints and permit tightening.
- VOC Removal:Solvent and volatile organic compound abatement through thermal oxidation, adsorption, or recovery systems. German printing and coating operations in Baden-Württemberg face F-Gas Regulation-driven upgrade cycles.
Dust removal holds the largest share; VOC removal is gaining share fastest on regulatory compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal implementation and F-Gas Regulation phase-down schedules are redirecting capital toward filtration upgrades across German automotive corridors, French pharmaceutical clusters, and Polish industrial zones transitioning from coal-dependent processes.
Germany
Automotive OEM cleanrooms in Stuttgart and Wolfsburg are deploying HEPA banks for EV battery dry room operations under tightening EU GMP Annex 1 revisions. ECHA REACH compliance mandates are compelling filter manufacturers to upgrade supply chain documentation for chemical processing installations along the Rhine. Baden-Württemberg coating operations face compressed activated carbon replacement cycles driven by F-Gas Regulation enforcement.
France
Biologics production facilities near Lyon and vaccine manufacturing corridors are accelerating procurement of EN 1822-validated HEPA systems with guaranteed uptime clauses. ANSM oversight of sterile manufacturing is elevating documentation requirements for filter integrity testing protocols. Île-de-France contract manufacturers are contracting filtration performance through opex-based servitization models.
Poland
Silesian manufacturing zones are opening premium filtration procurement as EU cohesion fund investments support coal-to-gas transition programs. Polish steel clusters are adopting electrostatic precipitators where pressure-drop sensitivity constrains mechanical baghouse alternatives. Katowice-area cement processors retain cost-focused baghouse specifications amid margin pressure.
Italy
Carrara marble processing and Castellón ceramic tile manufacturing are driving heavy-duty baghouse specifications for extreme particulate loading. Italian coating operations face F-Gas Regulation-driven VOC abatement upgrade cycles requiring activated carbon system replacements. Aging ductwork configurations in legacy facilities constrain drop-in HEPA upgrades without structural HVAC modifications.
Netherlands
Dutch dairy processors and agro-industrial facilities are prioritizing activated carbon for volatile organic compound management and biological filtration for ammonia control. CSRD sustainability reporting obligations are redirecting procurement criteria toward lifecycle carbon metrics and circular media recovery programs. Randstad-based food-grade installations absorb premium media costs for validated supply chains.
Europe Industrial Air Filtration Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered service and equipment segments. The vendor base organizes around three strategic archetypes: Nordic-origin premium media suppliers, German-anchored automotive-integrated system providers, and diversified industrial conglomerates with membrane specialization. Consolidation pressure concentrates in mid-tier mechanical filtration where scale advantages determine replacement contract capture. Competitive moves center on predictive maintenance service bundling and circular media recovery program development.
Within the premium-tier vector, Camfil AB exemplifies Nordic manufacturing footprint leverage across pharmaceutical and food-grade installations. MANN+HUMMEL GmbH occupies a position as an automotive-integrated archetype with deep OEM supply chain embedding. Freudenberg Group represents diversified industrial conglomeration with specialized membrane and chemical filtration media development for VOC-intensive process industries.
| Leading Market Players |
|---|
| Camfil AB |
| MANN+HUMMEL GmbH |
| Donaldson Company, Inc. |
| Freudenberg Group |
| Honeywell International Inc. |
| Parker Hannifin Corporation |
| AAF International |
| Daikin Industries, Ltd. |
| Nordic Air Filtration A/S |
| Others |
Cost & Logistics Intelligence
Overcapacity in Southeast Asian activated carbon processing is compressing supplier margins while extending payment terms for European filter manufacturers sourcing coconut shell and coal-based media. This utilization imbalance simultaneously intensifies price competition at the commodity tier and creates procurement leverage for buyers consolidating volume across German automotive and French pharmaceutical clusters.
Pricing Analysis
Certification level creates the primary spread across the European industrial air filtration market, with EN 1822-validated HEPA systems commanding substantial premiums over standard mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels segments procurement patterns, where pharmaceutical cleanroom operators absorb elevated costs for documented supply chain traceability while Polish cement processors prioritize unit economics. Cost compression in mid-tier baghouse specifications is intensifying because petroleum-derived PTFE and fiberglass feedstock volatility squeezes manufacturer margins. Price sensitivity concentrates among aging Italian and Spanish facilities facing retrofit constraints, whereas German automotive OEMs prioritize total-cost-of-ownership metrics over upfront equipment expenditure.
Supply Chain Analysis
Extended payment terms from Southeast Asian activated carbon suppliers are becoming standard practice as freight cost volatility and extended lead times strain working capital across European filter manufacturers. Raw material sourcing draws from Indonesia and the Philippines for coconut shell carbon, Germany and China for PTFE membrane substrates, and Belgium for specialized fiberglass media. Single-source vulnerability in Southeast Asian carbon supply exposes manufacturers to logistics chokepoint risk through the Suez Canal corridor. Distribution runs through direct OEM supply agreements for premium-tier pharmaceutical and automotive installations, with regional distributors serving mid-scale industrial facilities across Central European manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European industrial air filtration market is recovering from cyclical capital expenditure compression as EU Green Deal enforcement and F-Gas Regulation phase-down schedules force facility upgrade commitments across German chemical processing and Italian coating corridors.
For Market Incumbents: Build predictive maintenance service moats through IoT sensor networks and AI-driven pressure-drop analytics that bundle media replacement with uptime guarantees. Deepen backward integration into membrane substrate production to offset petroleum feedstock volatility compressing PTFE and fiberglass margins. Consolidate replacement contract capture in Silesian manufacturing zones where EU cohesion fund investments are displacing legacy baghouse systems with premium filtration procurement. For New Entrants and Emerging Players: Mid-market French contract manufacturers and German automotive tier suppliers represent the most penetrable entry point for asset-light leasing models that convert capital expenditure to operational expenditure. Polish steel clusters adopting electrostatic precipitators offer white-space opportunity where pressure-drop sensitivity constrains incumbent mechanical filtration offerings. Lead with servitization value propositions emphasizing CSRD compliance reporting and circular media recovery programs rather than equipment specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across predictive maintenance and filter-as-a-service sub-segments as software-enabled monitoring displaces hardware-centric business models. Acquisition targets should emphasize suppliers with pre-validated REACH dossiers and embedded pharmaceutical cleanroom relationships that sustain pricing power through regulatory compliance moats. Watch for inflection in EN 1822 HEPA testing and CE marking timeline compression as signal of R&D-intensive supplier distress creating consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Circular Media Recovery Program | CSRD sustainability reporting obligations elevate lifecycle carbon metrics above upfront equipment cost in Dutch and German procurement. |
| Predictive Maintenance Platform | IoT sensor networks enable filter-as-a-service models with guaranteed uptime clauses in French biologics facilities. |
| REACH Compliance Dossier Investment | Pre-validated material documentation captures pharmaceutical procurement from competitors facing ECHA enforcement gaps. |
| Membrane Substrate Backward Integration | In-house PTFE production insulates margin stability from petroleum price swings compressing mid-tier profitability. |
| Silesian Industrial Corridor Expansion | EU cohesion fund investments open premium filtration procurement in Polish manufacturing zones previously served by basic systems. |
Research Approach
The analysis maps HEPA filtration, activated carbon systems, electrostatic precipitators, and baghouse configurations, each validated through filtration procurement managers, plant engineers at German automotive OEMs, pharmaceutical cleanroom operators, and aftermarket service directors. Primary interviews with these stakeholders combined with secondary validation from ECHA REACH filings, EU F-Gas Regulation implementation reports, SEC filings of listed filtration suppliers, and Cefic chemical industry statistics. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates across technology and end-use dimensions.
Forecast assumptions held EU Green Deal enforcement timelines and F-Gas Regulation phase-down schedules fixed while varying industrial production indices and energy price scenarios across the projection horizon. Segmentation dimensions modeled include filter media type, technology architecture, end-use industry vertical, application severity, and regional regulatory cluster. CAGRs were derived from replacement cycle compression analysis and upgrade intensity patterns by compliance tier. Industry-specific inputs incorporated EN 1822 validation timelines, activated carbon replacement frequency under VOC tightening, and servitization adoption rates by facility scale.
Stress conditions across energy price volatility, Southeast Asian supply disruption severity, and regulatory enforcement pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance timeline adherence and substitution elasticity between filtration technologies. Macroeconomic contraction, regulatory delay, or breakthrough membrane material innovation would prompt revision of projected market trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Lamella Clarifier Market
Filters
Industrial Filter Paper Market
Filters
Coolant Filtration Skids Market
Filters
Global Tangential Flow Filtration Market
Filters
Global Pleated Filters Market
Filters
Global Gas Filtration Media Market
Filters
High Purity Chemical Filters Market
Filters
Activated Carbon Filter Market
Filters
Diatomaceous Filter Aid Market
Filters
Global Hollow Fiber Filtration Market
Filters
Europe Activated Carbon Market
Filters
Respirator Cartridges and Filters Market
Filters
Global Baghouse Filters Market
Filters
Nonwoven Filter Media Market
Filters
Fiberglass Filters Market
Filters
Compact Filters Market