
 Global Gas Phase Filtration Market | 2026-2036
Global Gas Phase Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Phase Filtration Market Analysis
ISO 10121-3 test methodology for gas phase air cleaning devices is redrawing competitive access in the Global Gas Phase Filtration Market, disqualifying suppliers lacking certified performance data. Freudenberg Filtration Technologies leverages its captive nonwoven media production to control raw material quality from polymer to finished module. Donaldson Company anchors North American industrial demand through extensive distribution networks serving metalworking and power generation facilities. Camfil AB differentiates via R&D intensity in molecular filtration for life science cleanrooms.
Gas phase filtration removes molecular contaminants from air and process gas streams through adsorptive, absorptive, or reactive media typically engineered with activated carbon impregnated with potassium permanganate or proprietary catalytic coatings, achieving removal efficiencies exceeding 99.5% for target gases at parts-per-billion detection thresholds. Activated carbon filter types dominate current volume given mature supply chains and broad contaminant compatibility, though chemical absorbent formulations represent the fastest-expanding category as semiconductor fabs confront ever-tighter airborne molecular contamination limits. Adsorption technology leads installed base across industrial air purification applications, while advanced oxidation processes gain traction in wastewater treatment plant off-gas treatment where refractory volatile organic compounds resist conventional capture.
The U.S. EPA enforces Maximum Achievable Control Technology standards that mandate gas phase filtration upgrades at chemical processing and petroleum refining facilities, while the EU F-Gas Regulation progressively restricts hydrofluorocarbon emissions and drives adoption of alternative scrubbing media. China's Ministry of Ecology and Environment implements increasingly stringent volatile organic compound emission standards for pharmaceutical manufacturing and coating operations. Stakeholders must monitor divergence between regional test protocols and certification reciprocity, as incompatible validation requirements threaten to fragment procurement strategies across multinational facility footprints.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are forcing a step-change in molecular contamination control, compressing filter replacement cycles and demanding ISO 14644-1 compliance at parts-per-billion thresholds that legacy systems cannot achieve.
Growth Catalysts
- EPA ozone standards:The U.S. EPA's tightened National Ambient Air Quality Standards mandate gas phase filtration upgrades at chemical processing and petroleum refining facilities, accelerating scrubber replacement timelines.
- Taiwan semiconductor expansion:Fabrication facilities in Hsinchu and Tainan are expanding gas phase filtration deployments to meet ISO 14644-1 cleanroom standards for advanced node production.
- Activated carbon formulations:Chemical absorbent media impregnated with potassium permanganate and proprietary catalytic coatings achieve removal efficiencies exceeding 99.5% for target gases at detection thresholds conventional carbon cannot reach.
Market Restraints
- Carbon supply concentration:High-grade activated carbon feedstock concentrates among Southeast Asian suppliers, exposing filter manufacturers to raw material volatility and geopolitical sourcing risk.
- Test protocol fragmentation:Divergence between ISO 10121-3, ASHRAE 145.2, and regional validation requirements forces redundant certification investments that inflate compliance costs.
- Membrane contactors:Liquid absorption systems for acid gas removal threaten to displace packed-bed filtration in select petrochemical applications where water-based scrubbing achieves comparable removal rates.
Strategic Opportunities
- India pharmaceutical manufacturing:Volatile organic compound emission standards from the Ministry of Environment, Forest and Climate Change are creating first-mover advantage for suppliers establishing local test and certification capabilities.
- Advanced oxidation convergence:Integration of photocatalytic oxidation with adsorptive media is opening wastewater treatment plant off-gas applications where refractory volatile organic compounds resist conventional capture.
- EU F-Gas tailwind:Progressive hydrofluorocarbon restrictions are driving adoption of alternative scrubbing media for refrigeration and air conditioning service applications.
Industry Challenges
- ISO 10121-3 certification timelines:Extended third-party validation cycles for gas phase air cleaning devices are delaying product launches and compressing effective revenue windows.
- Legacy scrubber integration:Retrofitting molecular filtration into existing HVAC infrastructure at U.S. industrial facilities requires custom ductwork modifications that extend project timelines and inflate installation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Phase Filtration Market |
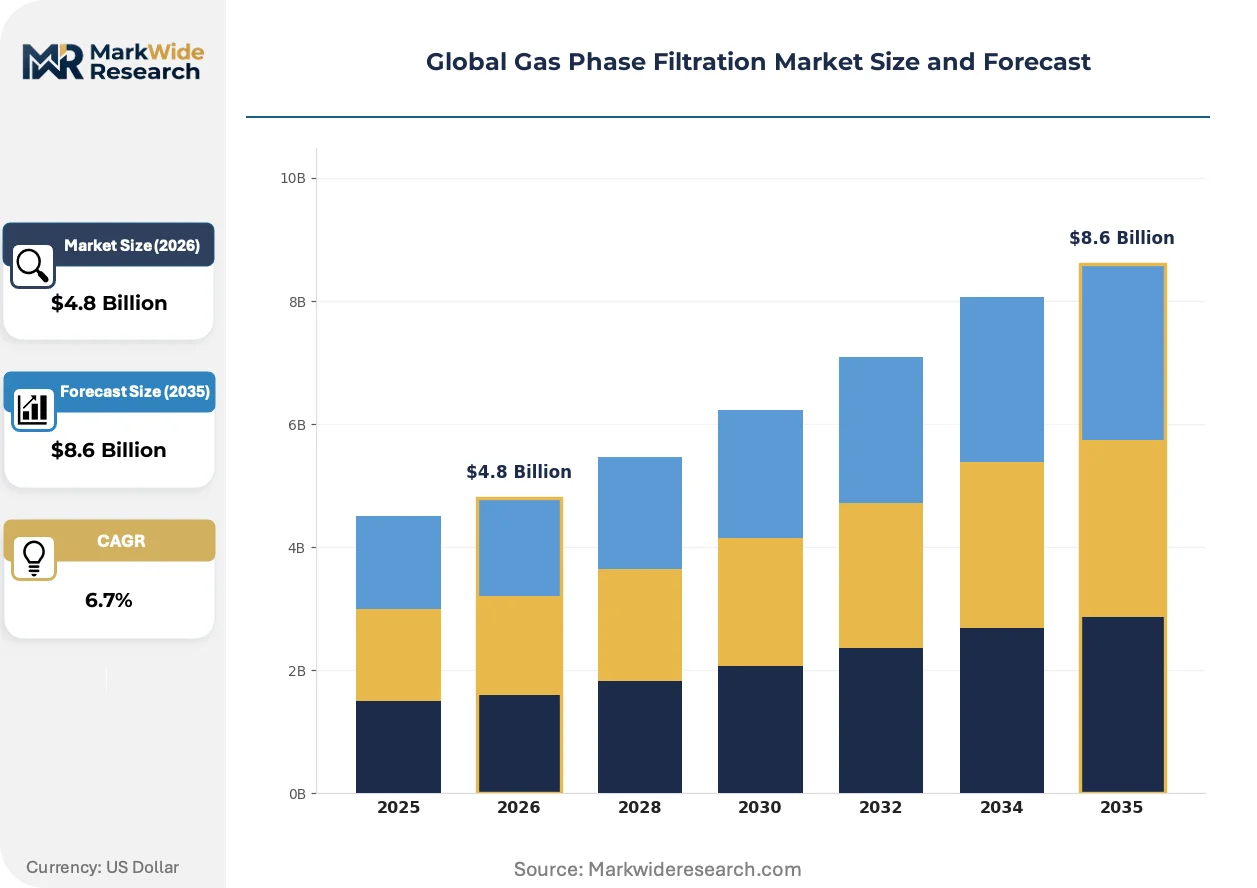
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Activated Carbon, Metal Mesh, Electrostatic Precipitator, Chemical Absorbents Application: Air Purification, Process Gas Treatment, Chemical Processing, Pharmaceutical Manufacturing End User: Industrial Facilities, Wastewater Treatment Plants, Pharmaceutical Companies, Food Processing Industries Technology: Adsorption, Advanced Oxidation, Plasma Treatment, Membrane Filtration |
| Companies Covered | Freudenberg Filtration Technologies SE & Co. KG, AAF International, Camfil AB, Bry-Air Inc., MANN+HUMMEL GmbH, Donaldson Company, Inc., Parker Hannifin Corporation, Circul-Aire, Inc., Filtration Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Phase Filtration Market Emerging Trajectories
Filter module architecture is miniaturizing while performance requirements intensify, compressing the physical footprint available for media beds and forcing innovation in adsorptive material density and flow distribution engineering.
Structured carbon monoliths with engineered pore hierarchies are displacing granular packed beds in semiconductor cleanroom applications. Samsung and TSMC fabs in South Korea and Taiwan are specifying these configurations for make-up air handlers where space constraints are severe. The technology is miniaturizing filtration footprints by 40% while maintaining equivalent removal capacity, enabling tool-level point-of-use deployment that was previously impractical.
China's Ministry of Ecology and Environment is tightening volatile organic compound emission standards for pharmaceutical manufacturing and coating operations. Facility operators in Jiangsu and Zhejiang provinces face inspection protocols that disqualify uncertified filtration equipment. Domestic suppliers are accelerating GB/T test method adoption to maintain procurement access against multinational competitors holding ISO 10121-3 validation.
Life science cleanroom operators are unbundling after-sales service contracts from initial equipment procurement. Biologics manufacturers in Switzerland and Massachusetts are negotiating separate multi-year service agreements with specialized molecular filtration service providers. This pattern is most visible in gene therapy manufacturing facilities where media replacement timing directly impacts batch release schedules and contamination control documentation requirements.
Global Gas Phase Filtration Market Segmentation
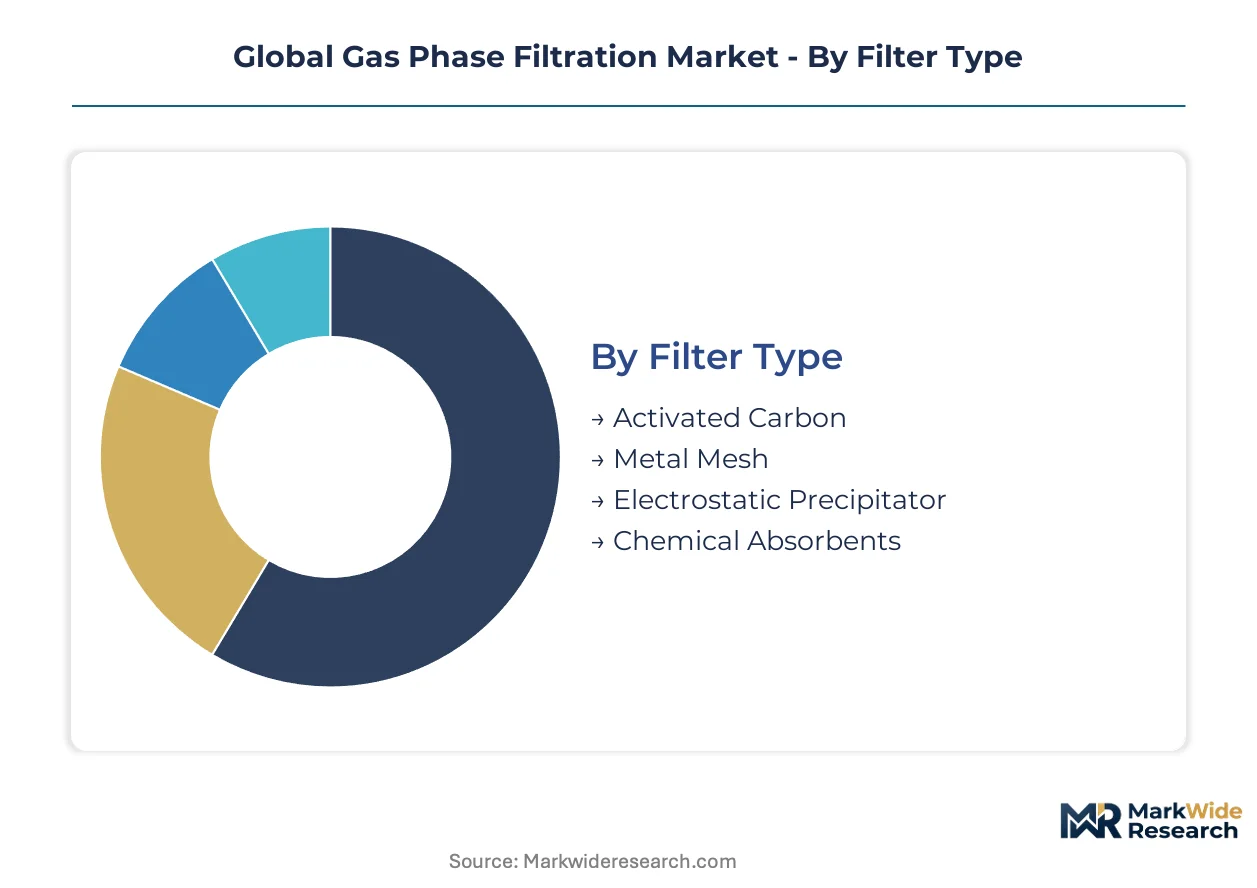
Gas phase filtration procurement diverges sharply by end-use environment, with cleanroom standards, emission limits, and process safety requirements dictating media selection and replacement protocols. Segmentation reveals how regulatory stringency concentrates demand in high-specification configurations while cost pressures sustain volume in legacy industrial applications.
Filter Type:
Regulatory differentiation separates certified high-efficiency media from commodity alternatives, with ISO 10121-3 validation increasingly gating procurement access in semiconductor and pharmaceutical cleanrooms.
- Activated Carbon:Porous carbonaceous media with engineered surface areas exceeding 1,000 square meters per gram, typically impregnated with potassium permanganate or proprietary catalytic coatings to target specific contaminant classes. Demand concentrates in U.S. chemical processing corridors where EPA Maximum Achievable Control Technology standards mandate continuous volatile organic compound capture at petroleum refining facilities.
- Chemical Absorbents:Formulated media combining base substrates with reactive chemisorbent agents that chemically bind target molecules rather than physically adsorbing them. Taiwan and South Korea semiconductor fabs are specifying these configurations for advanced node production where ISO 14644-1 compliance requires parts-per-billion detection thresholds.
- Metal Mesh:Stainless steel or aluminum mesh configurations providing structural support and pre-filtration for downstream adsorptive media in high-temperature process streams.
- Electrostatic Precipitator:Ionization-based particle removal systems adapted for gas phase applications where charged molecular species respond to electrostatic fields.
Established volume favors Activated Carbon; emerging adoption favors Chemical Absorbents.
Application:
Cost tier stratification separates mission-critical cleanroom deployments from compliance-driven industrial upgrades, with capital intensity and operating expenditure profiles diverging by threefold or more.
- Air Purification:HVAC-integrated and standalone systems for indoor air quality management across commercial, institutional, and industrial environments. Demand concentrates in East Asian manufacturing corridors where electronics and chemical processing clusters require continuous molecular contamination control.
- Process Gas Treatment:Point-of-use filtration for ultrapure gas delivery in semiconductor fabrication, with specifications tightening at each technology node. Samsung and TSMC fabs in South Korea and Taiwan are compressing filter replacement cycles to maintain yield rates at advanced lithography steps.
- Chemical Processing:Scrubber systems and emission control at petrochemical and specialty chemical facilities facing tightened National Ambient Air Quality Standards.
- Pharmaceutical Manufacturing:Contamination control for sterile processing environments, with China's Ministry of Ecology and Environment tightening volatile organic compound emission standards for coating and synthesis operations.
Capital deployment favors Process Gas Treatment; regulatory pressure favors Pharmaceutical Manufacturing.
End User:
Customer type determines procurement sophistication, with multinational pharmaceutical and semiconductor operators demanding certified performance data while municipal and mid-market industrial buyers prioritize unit economics.
- Industrial Facilities:Petroleum refining, petrochemical, and heavy manufacturing operations subject to EPA enforcement of Maximum Achievable Control Technology standards.
- Pharmaceutical Companies:Biologics and small-molecule manufacturers in Switzerland and Massachusetts unbundling after-sales service contracts from initial equipment procurement.
- Wastewater Treatment Plants:Off-gas treatment applications where advanced oxidation processes gain traction against refractory volatile organic compounds.
- Food Processing Industries:Odor control and contamination prevention in packaging and storage environments.
Specification intensity favors Pharmaceutical Companies; replacement volume favors Industrial Facilities.
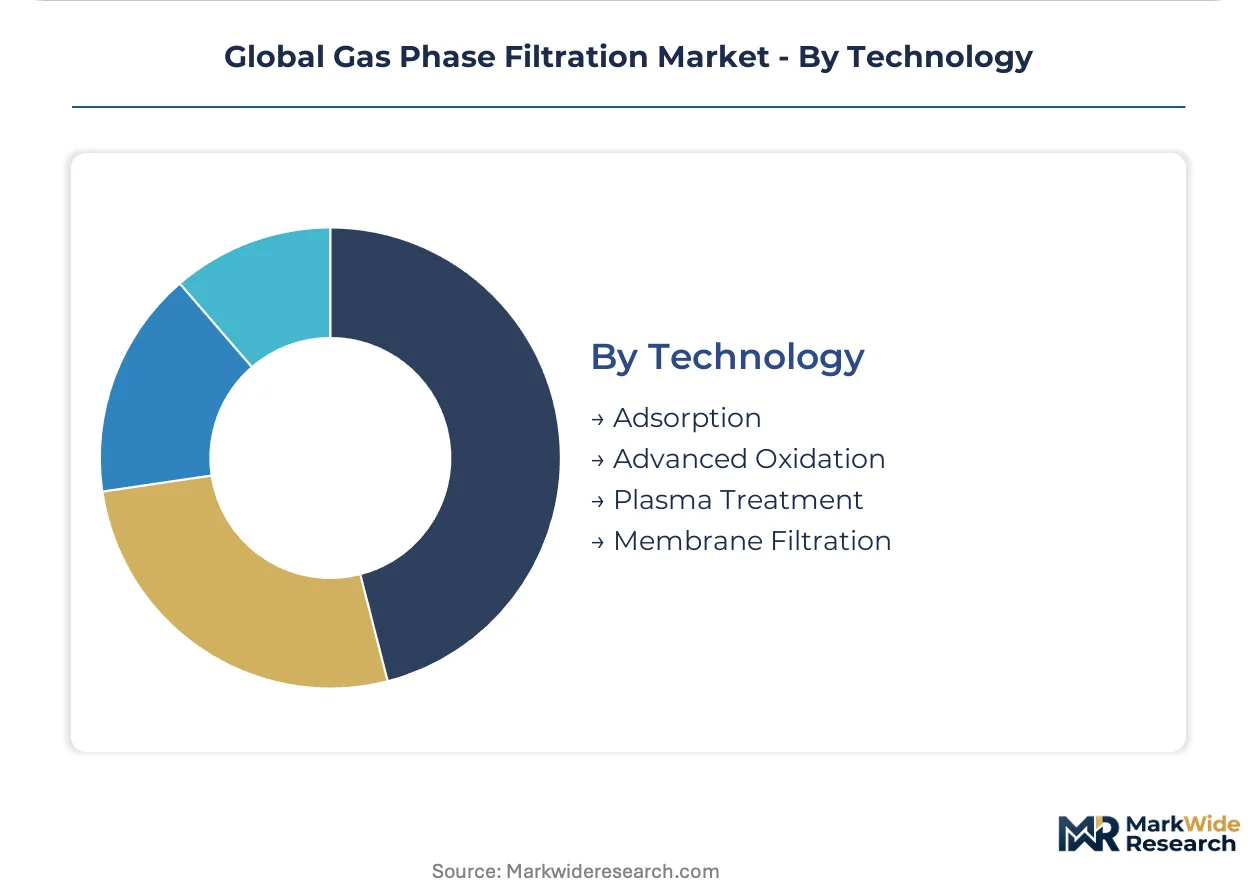
Technology:
Maturity gradients separate proven adsorptive methods from emerging destructive technologies, with integration trends blurring categorical boundaries.
- Adsorption:Physical and chemical capture on solid media, dominating installed base across industrial air purification with removal efficiencies exceeding 99.5% for target gases.
- Advanced Oxidation:Photocatalytic and chemical oxidation processes for refractory compounds, gaining traction in wastewater treatment plant off-gas applications.
- Plasma Treatment:Non-thermal plasma generation for radical-based contaminant destruction.
- Membrane Filtration:Selective permeability barriers for gas separation, threatening to displace packed-bed filtration in select petrochemical acid gas removal.
Proven reliability favors Adsorption; steepest expansion trajectory favors Advanced Oxidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabs and chemical processors concentrate procurement authority in East Asian manufacturing corridors, while U.S. and European industrial operators respond to tightening emission standards with compliance-driven upgrades.
United States
Petroleum refiners along the Gulf Coast and chemical processors in the Ohio River Valley drive replacement demand for legacy scrubber systems. The EPA enforces Maximum Achievable Control Technology standards that mandate continuous volatile organic compound capture. Houston-area facilities are retrofitting molecular filtration into existing HVAC infrastructure to meet tightened National Ambient Air Quality Standards for ozone and particulate matter.
Taiwan
Advanced node semiconductor fabrication in Hsinchu and Tainan compresses filter replacement cycles to maintain ISO 14644-1 cleanroom compliance. The Industrial Development Bureau coordinates with fabs to align local supply chains with international certification protocols. Samsung and TSMC suppliers are specifying structured carbon monoliths with engineered pore hierarchies for make-up air handlers where space constraints are severe.
South Korea
Memory and logic chip production in the Seoul Capital Area and Busan-Ulsan corridor requires parts-per-billion molecular contamination control. The Ministry of Trade, Industry and Energy supports domestic filter manufacturers through technology development programs. Pyeongtaek and Yongin fabrication complexes are deploying point-of-use filtration configurations that miniaturize footprints by 40% while maintaining equivalent removal capacity.
China
Pharmaceutical manufacturing in Jiangsu and Zhejiang provinces faces volatile organic compound emission standards from the Ministry of Ecology and Environment. Facility operators confront inspection protocols that disqualify uncertified filtration equipment. Domestic suppliers in Suzhou and Shanghai are accelerating GB/T test method adoption to maintain procurement access against multinational competitors holding ISO 10121-3 validation.
Germany
Chemical processing and automotive manufacturing in North Rhine-Westphalia and Baden-Württemberg sustain demand for high-efficiency gas phase filtration. The EU F-Gas Regulation progressively restricts hydrofluorocarbon emissions and drives adoption of alternative scrubbing media for refrigeration and air conditioning service applications. Ludwigshafen and Stuttgart industrial clusters are upgrading to chemical absorbent formulations impregnated with potassium permanganate and proprietary catalytic coatings.
Global Gas Phase Filtration Market Vendor Landscape
Player mix skews toward diversified filtration conglomerates with captive media production capabilities and specialized cleanroom equipment providers. Market structure concentrates among established industrial suppliers with validated ISO 10121-3 performance data, while mid-tier regional fabricators compete on unit economics for legacy industrial applications. Two strategic archetypes dominate: vertically integrated media-to-module manufacturers controlling raw material quality from polymer to finished product, and service-intensive specialists unbundling after-sales contracts from initial equipment procurement. Competitive moves center on certification acceleration to compress product launch timelines and geographic expansion into pharmaceutical manufacturing corridors with tightening emission standards.
Within the diversified conglomerate tier, Freudenberg Filtration Technologies SE & Co. KG and MANN+HUMMEL GmbH represent German-origin manufacturers with broad industrial filtration portfolios. Camfil AB exemplifies the R&D-intensive specialist archetype focused on molecular filtration for life science cleanrooms. Donaldson Company, Inc. anchors North American industrial demand through extensive distribution networks. These three companies occupy positions across distinct competitive vectors—integrated supply chain control, cleanroom specialization, and regional channel density—without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Freudenberg Filtration Technologies SE & Co. KG |
| AAF International |
| Camfil AB |
| Bry-Air Inc. |
| MANN+HUMMEL GmbH |
| Donaldson Company, Inc. |
| Parker Hannifin Corporation |
| Circul-Aire, Inc. |
| Filtration Group Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for high-grade activated carbon feedstock expose filter manufacturers to both pricing volatility and sourcing disruption, concentrating negotiating leverage with Southeast Asian suppliers while compressing margins for module assemblers lacking backward integration into media production.
Pricing Analysis
Cost-plus contracts indexed to coconut shell charcoal spot markets dominate procurement between Southeast Asian carbon producers and multinational filter manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10121-3 certified modules from uncertified alternatives and commodity industrial grades. Cost compression in the standard tier is intensifying because Chinese domestic suppliers are accelerating GB/T test method adoption to undercut validated competitors. Municipal wastewater treatment operators exhibit highest price sensitivity, while semiconductor fabs in Taiwan and South Korea prioritize certified performance data over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites the majority of high-grade activated carbon feedstock movement from Indonesian and Philippine production centers to module assembly operations in China, South Korea, and Germany. The supply chain draws from coconut shell carbonization facilities concentrated in Southeast Asia, potassium permanganate chemical processors in India and China, and nonwoven substrate manufacturers in Germany and the United States. Single-source vulnerability in coconut shell feedstock exposes manufacturers to agricultural yield fluctuations and climate-driven supply interruptions. Distribution runs through authorized distributor networks serving industrial facilities, direct OEM supply agreements with semiconductor fabs, and aftermarket service providers unbundling replacement media contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated semiconductor and pharmaceutical operators capable of dictating certification protocols and compressing supplier margins through volume concentration and specification standardization.
For Market Incumbents: Secure captive supply of activated carbon feedstock through equity partnerships or tolling arrangements with Southeast Asian carbonization facilities to insulate margin structures from raw material volatility. Accelerate ISO 10121-3 certification pipelines for next-generation chemical absorbent formulations before Chinese competitors achieve GB/T equivalency, preserving procurement access at Taiwan and South Korea fabs. Channel control through exclusive distributor agreements in the U.S. Gulf Coast petrochemical corridor defends position against emerging membrane contactor substitutes for acid gas removal. For New Entrants and Emerging Players: ISO 10121-3 fast-track programs for chemical absorbent media offer the most penetrable entry vector into semiconductor cleanroom supply chains where incumbent validation timelines create temporary procurement gaps. Target India's pharmaceutical manufacturing corridor, where Ministry of Environment, Forest and Climate Change emission standards are creating first-mover advantage for suppliers establishing local test and certification capabilities. A service-led go-to-market angle unbundling media replacement contracts from initial equipment procurement aligns with biologics manufacturers in Switzerland and Massachusetts seeking specialized molecular filtration service providers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-tightening play because successive revisions to EPA National Ambient Air Quality Standards and EU F-Gas Regulation create durable replacement demand independent of industrial production cycles. Acquisition targets should prioritize vertically integrated media-to-module manufacturers with captive nonwoven production and validated ISO performance data. The signal to watch is divergence between regional test protocols—fragmentation in certification reciprocity would favor specialists with multi-standard validation capabilities over single-market players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Feedstock | Captive coconut shell supply from Indonesian facilities insulates margin structures from agricultural yield volatility. |
| ISO 10121-3 Certification Acceleration | Compressed validation timelines defend procurement access at Samsung and TSMC fabs against Chinese GB/T competitors. |
| Service Contract Unbundling | Separate multi-year media replacement agreements align with gene therapy manufacturers' batch release documentation requirements. |
| Geographic Expansion into India Pharma Corridor | Local test capabilities capture first-mover advantage under Ministry of Environment emission standards tightening. |
| Advanced Oxidation Process Integration | Photocatalytic convergence opens wastewater treatment off-gas applications where refractory VOCs resist conventional capture. |
Methodological Framework
Desk research of customs trade databases, EPA enforcement records, and semiconductor industry capital expenditure disclosures preceded structured interviews with plant engineers at petroleum refining facilities, procurement leads at Taiwan and South Korea fabs, aftermarket service directors, and regulatory affairs specialists at filtration equipment manufacturers. Primary fieldwork combined telephone and video interviews with industry stakeholders across the United States, Germany, Taiwan, South Korea, China, and India. Secondary validation drew from SEC 10-K filings, EU ETS transaction data, and Ministry of Ecology and Environment inspection protocols. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Variance decomposition across filter type, application, end user, and technology dimensions isolated growth contributions over the projection horizon. Segmentation modeling incorporated ISO certification tier, cleanroom class specification, and regional regulatory stringency as cross-cutting variables. CAGRs derived from fitted growth curves applied to base-year market estimates, with cross-checks against capital expenditure pipelines at major semiconductor fabrication complexes and petrochemical facility upgrade schedules. Industry-specific forecast inputs included EPA Maximum Achievable Control Technology compliance timelines and EU F-Gas Regulation phase-down curves for hydrofluorocarbon emissions.
Decision-makers should treat outputs as directional under assumptions of continued semiconductor fab expansion in East Asia, sustained EPA enforcement of National Ambient Air Quality Standards, and stable coconut shell feedstock supply from Southeast Asian agricultural regions; material deviation in any assumption would warrant model refresh. Practitioners should keep alternative scenarios live as geopolitical sourcing risk, test protocol fragmentation, and membrane contactor substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Air Filtration Media Market
Filters
High Purity Chemical Filters Market
Filters
Zeolite Adsorbents Market
Filters
Industrial Filtration Market
Filters
Coolant Filtration Skids Market
Filters
Global Filter Market
Filters
Liquid Filter Bags Market
Filters
Global Tangential Flow Filtration Market
Filters
Global Baghouse Filters Market
Filters
Round Plate Filter Press Market
Filters
Respirator Cartridges and Filters Market
Filters
Color Filter Glass Market
Filters
String Wound Filter Materials Market
Filters
Hydraulic Filters Market
Filters
Chloramine Filter Market
Filters
Filter Bag Market