
 Global Laboratory Filtration Market | 2026-2036
Global Laboratory Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Filtration Market Foresight
Multi-source membrane procurement is recalibrating supply chain economics for large biopharma filter consumers. Merck KGaA leverages its integrated polymer science capabilities to sustain captive membrane production from raw resin to final cartridge. Danaher Corporation anchors North American service density through extensive field application scientist networks. Sartorius AG differentiates through single-use system integration that reduces cross-contamination risk in multi-product facilities.
Laboratory filtration encompasses the mechanical separation of particulates, microorganisms, and macromolecules from liquid or gas streams using porous media with defined pore size distributions, typically 0.1 to 10 micrometers for microfiltration applications. These systems serve critical functions in sterile processing, analytical sample preparation, and quality control verification across regulated industries. Membrane filters command the dominant product position due to their precise pore structure and compatibility with automated integrity testing protocols, while nanofiltration represents the fastest-expanding technology segment driven by gene therapy and viral vector purification requirements. Depth filters retain substantial volume in bioprocessing clarification steps where high dirt-holding capacity offsets lower absolute retention ratings.
The FDA enforces sterile product filtration guidelines under 21 CFR 211 that mandate bacterial retention validation and post-use integrity testing, directly shaping filter qualification protocols for pharmaceutical applications. EMA's Annex 1 revision on sterile medicinal products tightens requirements for single-use filtration assemblies in aseptic processing environments. ISO 13485 quality management standards govern filter manufacturing for medical device classifications in multiple jurisdictions. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on extractables and leachables testing as novel polymer chemistries enter clinical manufacturing workflows.
Market Dynamics
Single-use filtration architectures are compressing validation timelines and displacing stainless-steel systems across multi-product biopharma facilities, forcing incumbent suppliers to reconfigure cartridge-to-housing compatibility matrices.
Growth Catalysts
- EMA Annex 1 Revision:The updated sterile medicinal products mandate accelerates single-use assembly adoption in aseptic processing workflows across European contract manufacturing organizations.
- Gene therapy viral vector purification:Nanofiltration membrane demand surges as CDMOs scale lentiviral and AAV manufacturing for clinical pipeline candidates.
- German manufacturing cluster concentration:Goettingen and Darmstadt anchor specialized membrane R&D infrastructure that shortens development cycles for novel polymer chemistries.
Market Restraints
- PVDF resin supply volatility:Fluoropolymer feedstock price fluctuations compress margin structures for hydrophilic membrane producers dependent on specialty polymer grades.
- Integrity testing equipment oligopoly:Automated filter integrity verification systems concentrate among three specialized instrumentation suppliers, creating procurement bottlenecks for large biopharma consumers.
- Extractables validation burden:FDA 21 CFR 211 compliance timelines extend qualification cycles for novel single-use materials entering sterile drug product workflows.
Strategic Opportunities
- India biopharma manufacturing expansion:CDSCO regulatory harmonization with ICH Q5A guidelines creates membrane qualification pathways for export-oriented vaccine producers in Hyderabad and Bengaluru.
- Continuous bioprocessing integration:Perfusion culture systems demand real-time filtration modules that eliminate batch hold steps, opening hardware-software bundled service models.
- Japan PMDA accelerated review pathways:Sakigake designation for regenerative medicines compresses filtration validation timelines for domestic cell therapy manufacturers.
Industry Challenges
- Field application scientist scarcity:Membrane filtration process development expertise concentrates among experienced practitioners, constraining vendor technical service scaling.
- Legacy stainless-steel infrastructure stranded asset risk:Multi-product facilities face capital allocation dilemmas between retrofitting existing lines versus greenfield single-use installations.
- ISO 13485 certification timeline compression:Medical device classification requirements for certain filtration products extend quality management system implementation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Filtration Market |
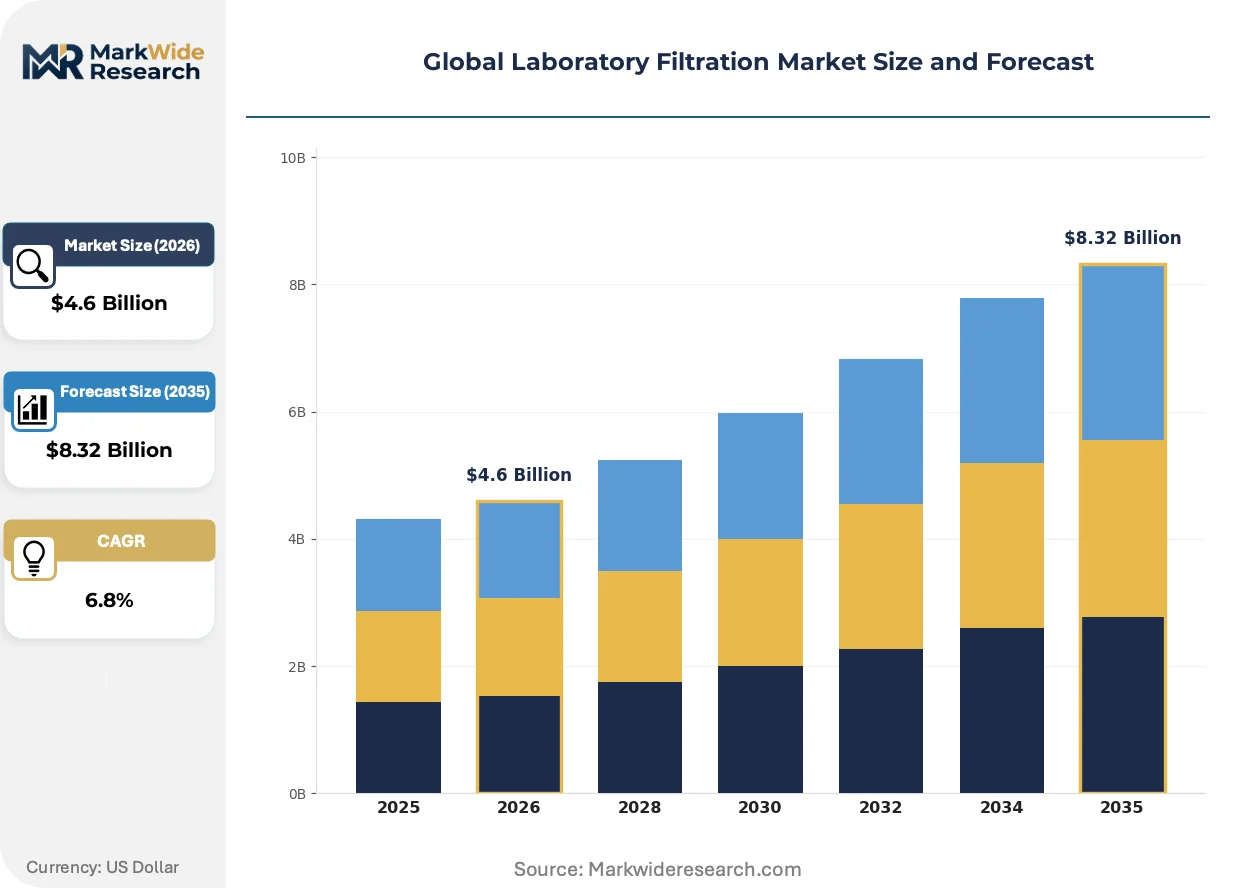
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $8.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Depth Filters, Syringe Filters, Vacuum Filter Systems, Filter Papers Technology: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis, Crossflow Filtration Application: Pharmaceutical R&D, Biotech Processing, Environmental Testing, Food & Beverage Analysis, Academic Research End User: Clinical Laboratories, Biopharmaceutical Firms, Quality Control Labs, Research Institutes, Contract Testing Organizations |
| Companies Covered | Merck KGaA, Danaher Corporation, Sartorius AG, Thermo Fisher Scientific Inc., 3M, Agilent Technologies, Inc., Avantor, Inc, GVS S.p.A, Ahlstrom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Filtration Market Shifts & Advancements
Membrane chemistry convergence with digital process control architectures is redefining competitive differentiation beyond pore size specifications toward integrated data integrity solutions.
Polyethersulfone track-etched membranes are consolidating position in critical sterile filtration applications where absolute retention ratings and low protein binding converge. Gene therapy manufacturers adopt these materials at accelerated pace for final fill-finish steps. The technology is consolidating supplier power among polymer science specialists with captive resin production.
REACH restrictions on per- and polyfluoroalkyl substances are forcing membrane producers to reformulate hydrophobic vent filters using alternative polymer platforms. Industrial consequence includes extended validation timelines for replacement materials in sterile tank venting applications. European biopharma facilities face compressed implementation deadlines compared to North American counterparts.
Biopharma procurement teams are consolidating supplier relationships around vendors offering integrated integrity testing hardware and consumable bundles. Traditional distribution channels face margin compression as direct manufacturer partnerships displace third-party distributors for high-volume filter consumers. This concentration is most visible among top-20 global biopharma companies with centralized global sourcing functions.
Global Laboratory Filtration Market Segmentation
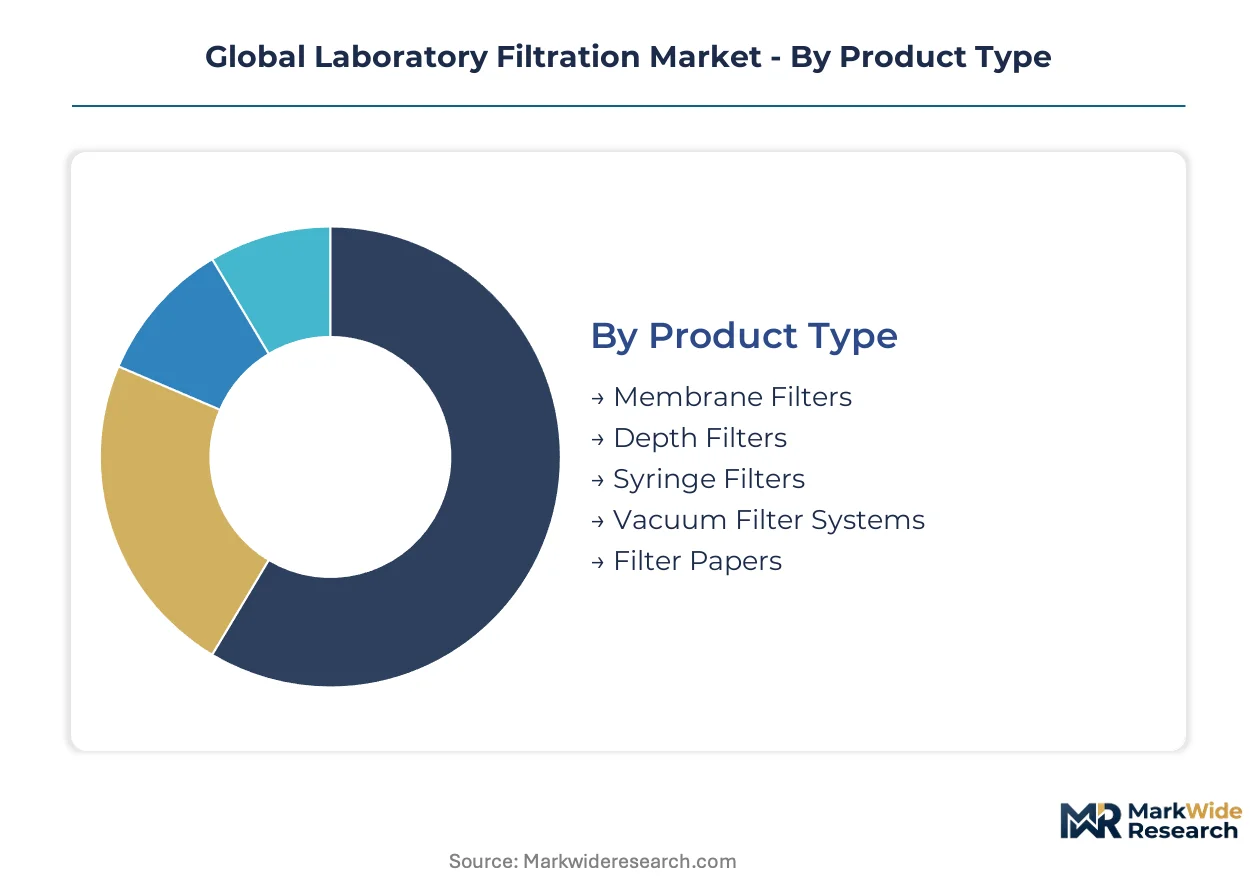
Laboratory filtration procurement decisions pivot on validation burden, automation compatibility, and single-use versus reusable architecture trade-offs. Segment-level dynamics reveal where membrane chemistry investments concentrate versus where hardware-software integration creates switching costs.
Product Type:
Upgrade cycles accelerate where single-use architectures displace stainless-steel systems and automated integrity testing becomes mandatory.
- Membrane Filters:Polyethersulfone and PVDF chemistries dominate sterile filtration with absolute pore ratings from 0.1 to 0.45 micrometers. Biopharma final fill-finish operations in Germany and Massachusetts drive specification tightening as FDA 21 CFR 211 compliance mandates bacterial retention validation.
- Depth Filters:Cellulose and diatomaceous earth matrices deliver high dirt-holding capacity for bioprocessing clarification steps. Demand concentrates in CDMO bulk harvest operations where protein recovery efficiency outweighs absolute retention requirements.
- Syringe Filters:Gamma-sterilized polypropylene housings with PTFE or nylon membranes serve analytical sample preparation workflows.
- Vacuum Filter Systems:Multi-well plate formats integrate with automated liquid handlers for high-throughput screening applications.
- Filter Papers:Qualitative and quantitative cellulose grades retain substantial volume in environmental testing and educational laboratories.
Volume placements concentrate in membrane filters; the faster expansion belongs to single-use vacuum systems.
Technology:
Process intensification demands are compressing the performance gap between traditional batch filtration and continuous processing architectures.
- Microfiltration:Tangential flow and normal flow configurations handle cell culture harvest clarification and sterile final filtration. Biopharma facilities in Switzerland and Singapore standardize on 0.2-micrometer rated membranes for bacterial retention per EMA Annex 1.
- Nanofiltration:Track-etched and composite membranes achieve viral clearance and endotoxin removal below 10 kilodaltons. Gene therapy CDMOs in California and Massachusetts adopt these systems for AAV and lentiviral vector purification.
- Ultrafiltration:Hollow fiber and cassette formats enable protein concentration and buffer exchange in downstream bioprocessing.
- Reverse Osmosis:Spiral-wound modules produce WFI and purified water for pharmaceutical manufacturing.
- Crossflow Filtration:Reduced-shear designs protect shear-sensitive biologics during extended perfusion culture operations.
Microfiltration commands the largest installed base; nanofiltration is climbing the fastest on gene therapy manufacturing expansion.
Application:
Regulatory stringency variance across end-use sectors determines qualification timeline and margin structure for filter suppliers.
- Pharmaceutical R&D:Early-stage molecule development requires flexible filtration scalability from bench to pilot scale. Formulation scientists in New Jersey and Basel prioritize filter extractables profiles that preempt late-stage validation failures.
- Biotech Processing:Commercial monoclonal antibody and recombinant protein manufacturing demands validated sterile filtration trains. Single-use adoption rates diverge between legacy stainless-steel facilities and greenfield CDMO investments.
- Environmental Testing:Regulatory compliance monitoring for water and air quality employs membrane filtration for particulate and microbial enumeration.
- Food & Beverage Analysis:Microbiological quality control in dairy and beverage production relies on membrane-based colony counting methods.
- Academic Research:Price-sensitive procurement prioritizes basic filtration performance over extensive validation documentation.
Biotech processing generates the highest per-unit revenue; pharmaceutical R&D offers the broadest customer base expansion.
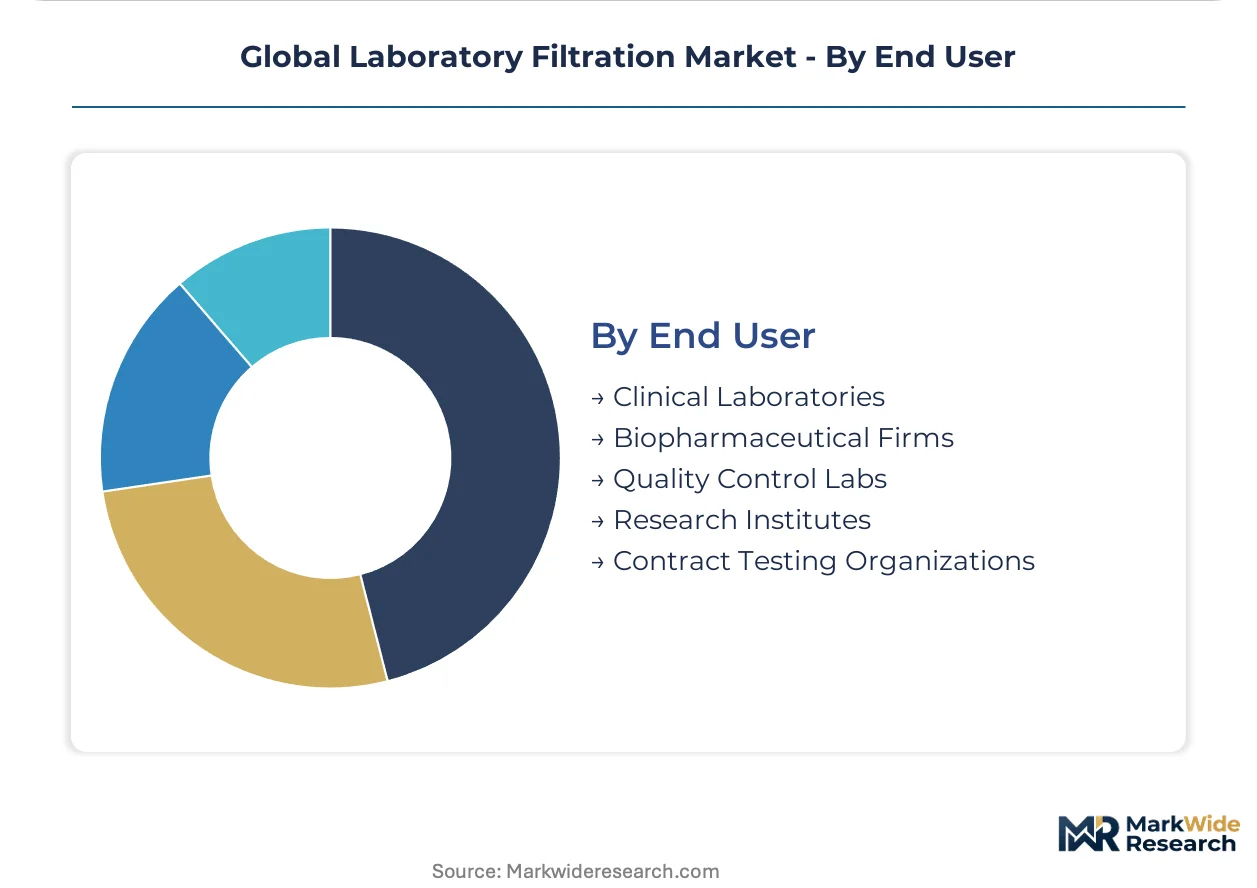
End User:
Centralized procurement functions at large biopharma organizations are consolidating supplier relationships around integrated hardware-consumable bundles.
- Biopharmaceutical Firms:In-house manufacturing and externalized production both demand validated filtration systems with complete extractables and leachables documentation. Quality agreements with filter suppliers now routinely specify change notification protocols.
- Contract Testing Organizations:High-throughput environmental and food safety labs prioritize filter throughput and automation compatibility over single-use convenience.
- Clinical Laboratories:Diagnostic sample preparation workflows standardize on syringe filters with low protein binding and minimal hold-up volume.
- Quality Control Labs:Release testing and stability studies require filter integrity test documentation for regulatory submissions.
- Research Institutes:Grant-funded academic labs balance performance specifications against budget constraints and distributor availability.
Biopharmaceutical firms dominate absolute spending; contract testing organizations are gaining share fastest on outsourced analytical services expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PVDF resin production clusters in Germany and fluoropolymer feedstock concentration in the eastern United States anchor membrane supply geography. Manufacturing gravity concentrates where polymer science infrastructure intersects with biopharma demand density.
United States
FDA 21 CFR 211 sterile product guidelines drive bacterial retention validation protocols across Massachusetts and New Jersey biopharma corridors. The EPA monitors extractables testing for environmental filtration applications in analytical laboratories. Greater Boston anchors gene therapy CDMO expansion, with nanofiltration membrane demand surging for viral vector purification workflows.
Germany
EMA Annex 1 revision on sterile medicinal products accelerates single-use assembly qualification timelines for Goettingen and Darmstadt manufacturing clusters. REACH restrictions on per- and polyfluoroalkyl substances force membrane chemistry reformulation for hydrophobic vent filters. The country's integrated polymer science infrastructure sustains captive membrane production from raw resin to final cartridge formats.
China
NMPA regulatory harmonization with ICH Q5A guidelines opens qualification pathways for domestic vaccine producers in Shanghai and Suzhou biotech parks. The MIIT promotes advanced materials manufacturing under national strategic emerging industry classifications. Yangtze River Delta concentration of CDMO infrastructure drives membrane filtration procurement for export-oriented biologics manufacturing.
India
CDSCO alignment with international GMP standards creates membrane validation frameworks for Hyderabad and Bengaluru vaccine export facilities. The PLI scheme incentivizes domestic manufacturing of critical bioprocessing inputs including filtration consumables. Telangana's biopharma corridor attracts contract manufacturing investment requiring scalable filtration infrastructure.
Switzerland
Swissmedic stringent quality requirements for sterile medicinal products elevate filter integrity documentation standards across Basel pharmaceutical operations. The country's medical device classification framework governs filtration product manufacturing under harmonized European procedures. Northwestern Switzerland maintains specialized membrane R&D proximity to major biopharma headquarters.
Global Laboratory Filtration Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers retrofit polymer production lines for gene therapy-compatible membrane chemistries. The vendor base stratifies between integrated polymer science conglomerates and specialized single-use system fabricators. Three archetypes define competitive positioning: captive resin-to-cartridge producers, hardware-software integrators, and regional service-density specialists. M&A activity and strategic technology licensing concentrate among mid-cap specialists seeking membrane chemistry differentiation.
Among Germany-based integrated producers, Merck KGaA and Sartorius AG exemplify the captive manufacturing archetype, anchoring advanced membrane R&D infrastructure around Goettingen and Darmstadt clusters. Danaher Corporation represents the North American service-density model, with field application scientist networks supporting biopharma process development. These three entities occupy distinct competitive vectors—polymer science depth, single-use system integration, and technical service proximity—rather than direct product substitution.
| Leading Market Players |
|---|
| Merck KGaA |
| Danaher Corporation |
| Sartorius AG |
| Thermo Fisher Scientific Inc. |
| 3M |
| Agilent Technologies, Inc. |
| Avantor, Inc |
| GVS S.p.A |
| Ahlstrom |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between validated pharmaceutical-grade membranes and unvalidated research-grade alternatives splits pricing power and procurement channels. FDA 21 CFR 211 compliance burdens concentrate premium pricing with integrated resin-to-cartridge producers in Germany and Massachusetts, while commodity-grade filters flow through distributor networks serving price-sensitive academic laboratories.
Pricing Analysis
Service-bundling divergence separates integrated hardware-software offerings from bare consumable transactions. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation depth, with gene therapy manufacturers absorbing highest tiers for extractables-qualified nanofiltration membranes. Cost compression in standard-grade microfiltration stems from Chinese membrane entrants targeting vaccine producers in India. Contract testing organizations exhibit greatest price sensitivity; biopharma quality control labs demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with fluoropolymer resin production concentrated in Germany and the eastern United States. PVDF and polyethersulfone feedstocks draw from specialty chemical producers in these geographies, with membrane casting operations tethered to polymer science clusters around Goettingen and Darmstadt. REACH restrictions on per- and polyfluoroalkyl substances pose regulatory restriction risks for hydrophobic vent filter formulations. Distribution runs through direct manufacturer partnerships for top-20 biopharma accounts; regional distributors serve fragmented research institute demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
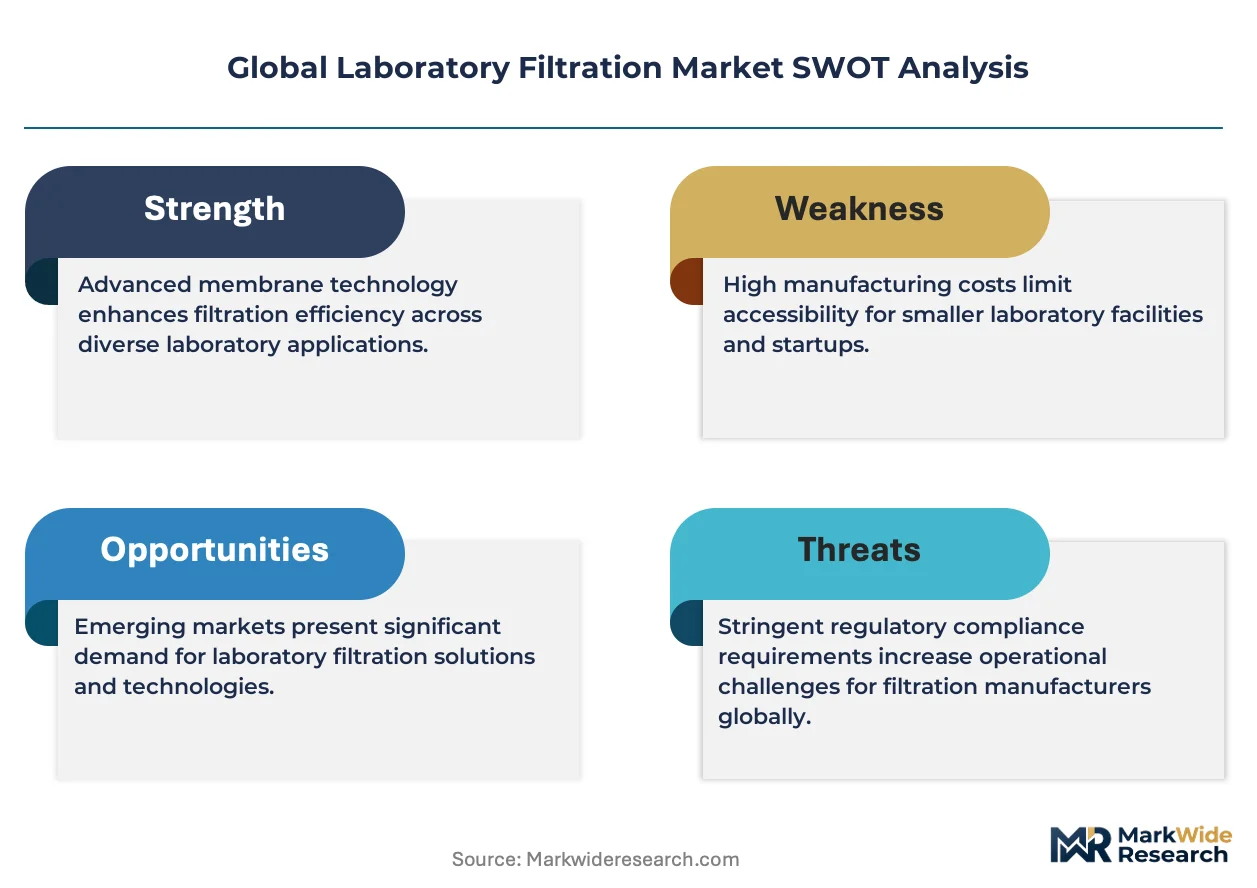
This market functions as a cost-of-compliance story where EMA Annex 1 revision constructs barrier-to-entry moats favoring incumbents with validated single-use assembly portfolios.
For Market Incumbents: Cement polymer science depth as defensive moat by expanding captive resin production for gene therapy-compatible track-etched membranes. Capacity addition in German manufacturing clusters sustains proximity advantage for EMA-regulated European biopharma. Channel control through direct service partnerships with top-20 global biopharma accounts neutralizes distributor margin compression.
For New Entrants and Emerging Players: Begin with India biopharma manufacturing expansion where CDSCO regulatory harmonization creates qualification pathways for export-oriented vaccine producers in Hyderabad. Perfusion culture filtration modules for continuous bioprocessing represent most penetrable white-space segment. Go-to-market angle: hardware-software bundled service models eliminating batch hold steps for CDMOs.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap membrane chemistry specialists given gene therapy viral vector purification demand acceleration. Long-term viability favors producers with backward integration into fluoropolymer resin production. Signal to watch: FDA-EMA convergence on extractables testing protocols as novel polymer platforms enter clinical workflows.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA Annex 1 compliance accelerates single-use assembly qualification for European sterile processing. |
| Backward Integration | Captive PVDF resin production insulates margin structures from fluoropolymer feedstock volatility. |
| Manufacturing Scale-Up | Gene therapy CDMO expansion in Greater Boston drives nanofiltration membrane capacity requirements. |
| Strategic Partnership | Integrated integrity testing hardware-consumable bundles consolidate procurement relationships. |
| Geographic Expansion | India PLI scheme incentives attract filtration infrastructure investment for vaccine export facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with bioprocess development scientists, regulatory affairs specialists, GPO contracts managers, and CDMO procurement directors combined with FDA 21 CFR 211 guidance documents, EMA Annex 1 revision texts, and ISO 13485 certification databases. Bottom-up membrane volume estimates triangulated against top-down biopharma capital expenditure disclosures.
Data-stream reconciliation across product type, technology, application, and end-user dimensions produced segment-level projections over the analysis window. CAGRs derived from elasticity modeling against biologics manufacturing capacity expansion. Forecast inputs incorporated gene therapy pipeline progression rates and single-use adoption curves across stainless-steel retrofit versus greenfield facility decisions.
Underlying measurement precision varies by segment; biopharmaceutical end-use carries tighter precision than academic research given disclosure requirements. Forecasts reflect assumptions on regulatory convergence timing and polymer chemistry innovation cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Tangential Flow Filtration Market
Filters
Residential Filters Market
Filters
Activated Carbon Market
Filters
Aerospace Filter Market
Filters
Nonwoven Filter Media Market
Filters
Filters and Particle Monitoring Market
Filters
Anti-Microbial Filter Market
Filters
High Purity Chemical Filters Market
Filters
Global Depth Filtration Market
Filters
Global Filtration and Contamination Control Market
Filters
Fabric Filter System Market
Filters
Compact Filters Market
Filters
Liquid Filter Bags Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
US Baghouse Filters Market
Filters
Drum Filters Market