
 Semiconductor Packaging Adhesives Market | 2026-2036
Semiconductor Packaging Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Packaging Adhesives Market Insights
Automotive electronics is decoupling from consumer electronics as the primary demand anchor for semiconductor packaging adhesives. Henkel AG & Co. KGaA leverages its die-attach portfolio to dominate European automotive qualification programs. Dow Inc. anchors North American supply through thermal management formulations tailored to power module packaging.
Semiconductor packaging adhesives are thermosetting polymer systems formulated to bond silicon dies to substrates while managing thermal expansion mismatches and conducting or insulating heat and electricity. These materials cure at elevated temperatures to form permanent joints that maintain electrical interconnect integrity across temperature cycling from minus forty to one hundred fifty degrees Celsius. Epoxy formulations occupy the largest volume share due to their balance of adhesion strength, thermal stability, and established processing infrastructure in wire bonding applications. Flip chip attachment represents the fastest-growing application segment as underfill and non-conductive paste technologies displace traditional wire bonding in high-density packages.
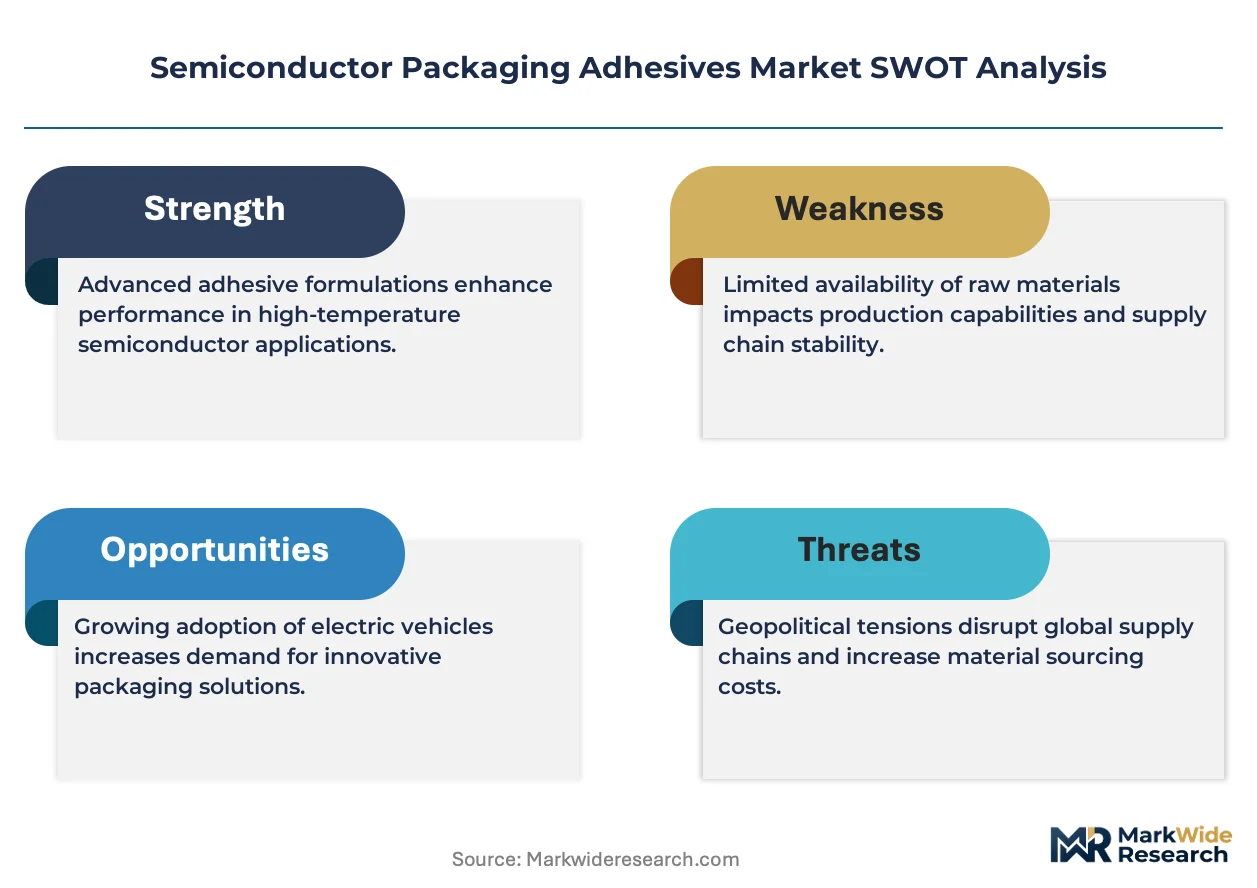
REACH registration requirements and RoHS substance restrictions in Europe are forcing reformulation away from legacy halogenated flame retardants toward phosphorus-based and inorganic alternatives. The US EPA and OSHA maintain workplace exposure limits for solvent constituents that affect adhesive curing processes and manufacturing location decisions. Stakeholders must monitor evolving semiconductor export controls and substrate material qualification timelines as packaging technology roadmaps accelerate toward heterogeneous integration architectures.
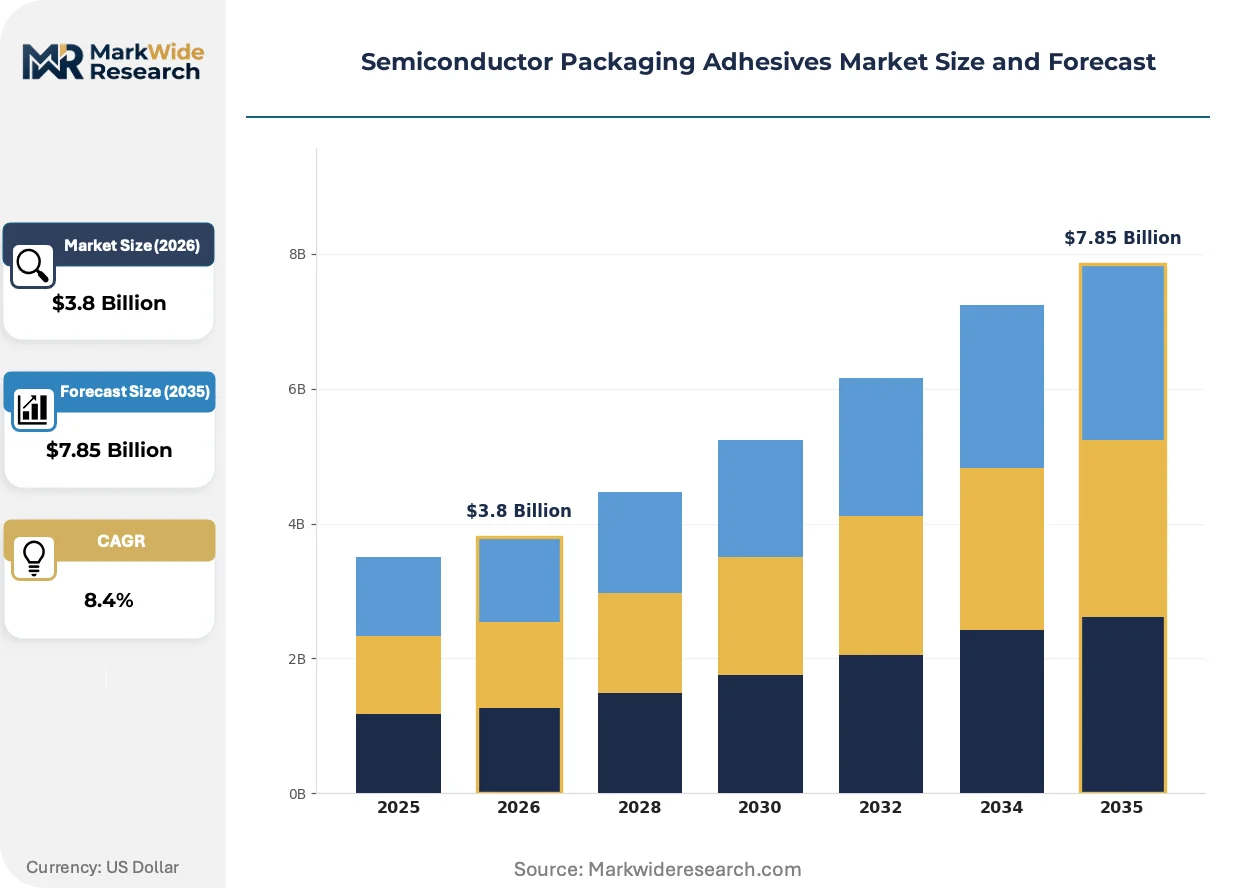
Market Dynamics
Heterogeneous integration roadmaps are compressing adhesive qualification timelines while bifurcating the supplier base between automotive-grade specialists and high-volume consumer electronics providers. This structural tension between reliability requirements and cost velocity now governs formulation development priorities across the value chain.
Growth Catalysts
- Advanced Driver-Assistance Systems:Automotive electronics now require multiple die-attach layers per module, expanding adhesive consumption per vehicle as lane-keeping and collision-avoidance functions proliferate.
- REACH and RoHS Frameworks:European chemical restrictions are accelerating halogen-free adhesive development, creating first-mover advantages for suppliers with qualified phosphorus-based flame retardant portfolios.
- TSMC Ecosystem Concentration:Taiwan's advanced packaging cluster around Hsinchu Science Park is concentrating demand and pulling material suppliers into co-location arrangements.
Market Restraints
- Silver Flake Cost Volatility:Conductive die-attach formulations depend on silver flake loadings of sixty to eighty percent by weight, exposing margins to London Bullion Market Association spot price swings.
- Epoxy Resin Supply Concentration:Bisphenol-A and specialty epoxy hardener production concentrates in China and South Korea, creating single-source vulnerability for Western formulators.
- Thermal Expansion Mismatch:Silicon-to-organic substrate coefficient of thermal expansion gaps limit maximum die sizes in power modules, constraining automotive inverter scaling.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic packaging facilities are creating greenfield adhesive qualification opportunities outside established East Asian supply chains.
- Chiplet Architectures:Die-to-die bonding in 2.5D and 3D packages is expanding underfill and non-conductive paste applications beyond traditional flip chip boundaries.
- EU Green Deal Alignment:Carbon border adjustment mechanisms will favor European-based adhesive manufacturing with renewable energy certificates, rewarding localized production investments.
Industry Challenges
- Automotive Qualification Timelines:AEC-Q100 stress testing requires eighteen to thirty-six months for full die-attach validation, compressing development windows for next-generation nodes.
- Process Engineer Scarcity:Dispensing and curing optimization for novel heterogeneous packages requires rare combinations of polymer chemistry and semiconductor packaging expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Packaging Adhesives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Chip-On-Board, Chip-On-Glass, Flip Chip, Wire Bonding End User: Consumer Electronics, Automotive, Industrial, Telecommunications Technology: Thermal Management, Electrical Insulation, Structural Adhesives, Conductive Adhesives |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller Company, Dow Inc., LG Chem Ltd., DuPont, BASF SE, Hitachi Chemical Company, Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Packaging Adhesives Market Trends and Innovations
Sintering technologies and nano-scale fillers are fragmenting the traditional epoxy-dominant landscape while regulatory chemistry mandates force simultaneous reformulation across multiple product lines. These parallel pressures are compressing R&D cycles and favoring suppliers with modular formulation platforms.
Silver sinter pastes with nano-particle loadings are replacing solder and conventional conductive epoxies in power module attachment for electric vehicle inverters. Automotive tier-one suppliers are qualifying these materials for 175°C continuous operation. This transition is decentralizing thermal management solutions away from wire-bonded discrete packages toward integrated power stages with direct-cooled substrates.
REACH authorization requirements for boric acid derivatives and certain amine hardeners are forcing systematic substitution in European-qualified formulations. The European Chemicals Agency's 2024 updated candidate list has accelerated phosphorus-nitrogen synergist adoption. High-reliability automotive segments are absorbing the reformulation costs fastest, while consumer electronics suppliers delay qualification pending volume certainty.
Direct material sourcing by foundries and OSATs is displacing traditional distributor channels for critical packaging materials. TSMC and ASE Group are building approved vendor lists with quarterly business reviews and locked pricing mechanisms. Taiwan and South Korea display the most advanced procurement centralization, with automotive packaging lines in Germany and Japan retaining more fragmented purchasing patterns.
Semiconductor Packaging Adhesives Market Segmentation
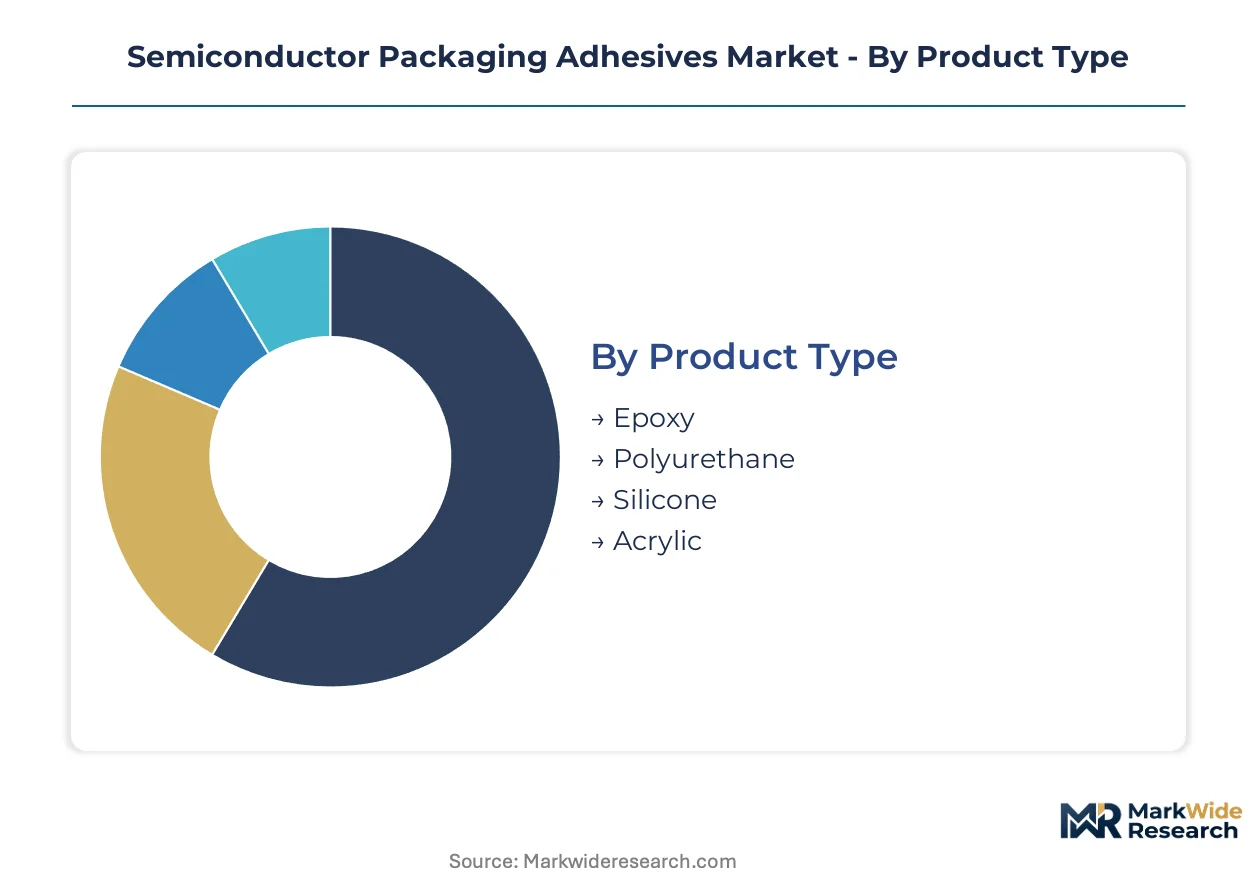
Semiconductor packaging adhesives fragment across formulation chemistry, assembly method, and thermal-electrical function. Each dimension carries distinct qualification timelines and margin structures that determine supplier positioning.
Product Type:
Epoxy formulations dominate volume shipments while silicone and acrylic alternatives command premium pricing in specialized thermal cycling applications.
- Epoxy:Thermosetting polymers built from bisphenol-A and specialty hardener chemistries deliver balanced adhesion strength and thermal stability. Wire bonding infrastructure across Taiwan and South Korea consumes the largest volumes, though REACH-mandated reformulation is elevating phosphorus-based flame retardant costs.
- Silicone:Elastomeric systems with broad operating temperature ranges from minus sixty to two hundred degrees Celsius accommodate extreme thermal expansion mismatches. Automotive power module suppliers in Germany are qualifying these formulations for 175°C continuous operation under AEC-Q100 stress protocols.
- Polyurethane:Flexible backbone chemistry suits low-stress die-attach in MEMS and sensor packages where silicon fragility demands compliance.
- Acrylic:UV-curable systems enable rapid processing in display driver IC attachment where throughput velocity outweighs thermal performance requirements.
Mature deployment sits with epoxy. Newer deployment is concentrated in silicone.
Application:
Assembly methodology determines adhesive specification, with flip chip and chip-on-glass demanding underfill precision that wire bonding processes avoid entirely.
- Flip Chip:Underfill and non-conductive paste technologies bond bumped dies directly to organic substrates, eliminating wire loops. TSMC's CoWoS and InFO packaging expansion in Hsinchu is pulling material suppliers into co-development programs for heterogeneous integration nodes.
- Wire Bonding:Die-attach epoxies secure silicon to leadframes before gold or copper wire interconnection. Legacy consumer electronics packaging in China retains this method for cost-sensitive memory and discrete devices.
- Chip-On-Board:Bare die attachment to printed circuit boards with glob-top encapsulation serves LED and simple microcontroller applications where package cost minimization dominates.
- Chip-On-Glass:Anisotropic conductive films and non-conductive pastes bond display driver ICs to TFT glass substrates. South Korean panel manufacturers anchor demand for ultra-fine pitch compatibility.
Volume concentration remains with wire bonding. Steepest expansion trajectory belongs to flip chip.
End User:
Automotive qualification requirements are decoupling adhesive specifications from consumer electronics cost structures, creating parallel supply chains with diverging margin profiles.
- Automotive:Multiple die-attach layers per advanced driver-assistance system module multiply adhesive consumption per vehicle. Lane-keeping and collision-avoidance function proliferation across German and Japanese OEM programs is expanding thermal cycling reliability requirements.
- Consumer Electronics:Smartphone and wearable device packaging prioritizes miniaturization and cost velocity over extended reliability. Taiwan-based OSATs concentrate procurement for this segment through quarterly locked pricing mechanisms.
- Industrial:Power supply and motor control modules demand extended operating lifetimes in harsh environments. European industrial automation OEMs specify halogen-free formulations to satisfy EU Green Deal alignment requirements.
- Telecommunications:Base station and optical transceiver packaging combines high-frequency electrical performance with thermal management. India's PLI scheme for domestic telecom equipment manufacturing is creating qualification opportunities outside established East Asian supply chains.
Consumer electronics retains volume leadership. Automotive is gaining share fastest.
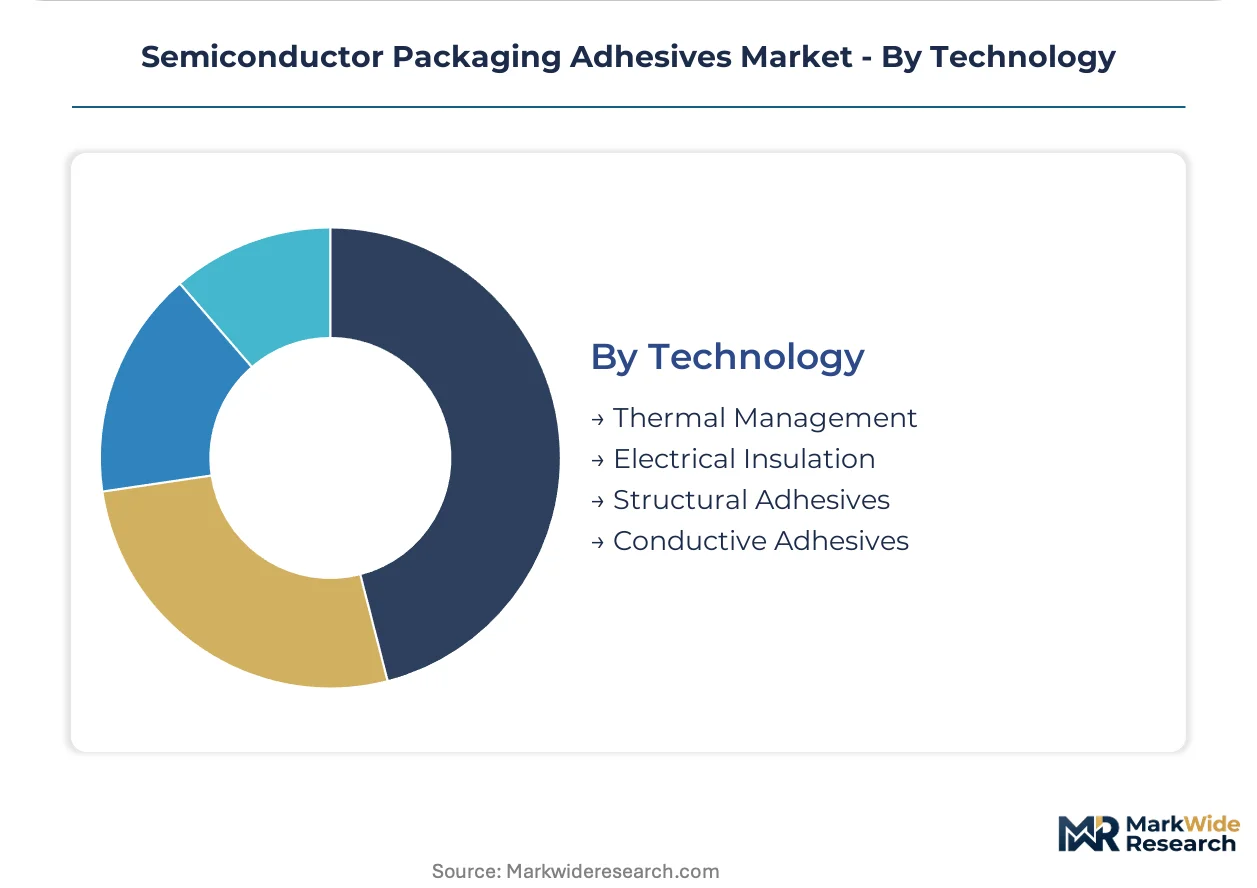
Technology:
Functional specialization splits the market between thermal management, electrical isolation, and mechanical integrity requirements that rarely overlap in single formulations.
- Conductive Adhesives:Silver flake loadings of sixty to eighty percent by weight enable die-attach with electrical and thermal conductivity. Electric vehicle inverter manufacturers are qualifying silver sinter pastes with nano-particle architectures to replace solder in 175°C continuous operation environments.
- Thermal Management:Boron nitride and alumina-filled systems conduct heat while maintaining electrical isolation. Power module packaging for renewable energy inverters in China and Germany drives specification evolution toward higher thermal conductivity targets.
- Electrical Insulation:Alumina and silica-filled epoxies prevent shorting between closely spaced bond pads in high-density packages. Fine-pitch wire bonding applications in memory modules require precise viscosity control to avoid bleed-out.
- Structural Adhesives:High-modulus formulations secure large dies and passive components against mechanical shock and vibration. Automotive underhood applications specify these systems for thermal cycling durability beyond consumer electronics requirements.
Established deployment centers on electrical insulation. Emerging deployment concentrates in conductive adhesives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian chemical manufacturing clusters while consumption splits between automotive electronics hubs in Germany and Japan and advanced packaging foundries in Taiwan. This geographic decoupling creates supply chain complexity for Western formulators.
Taiwan
TSMC's CoWoS and InFO expansion in Hsinchu Science Park pulls material suppliers into co-location arrangements. The National Development Council's semiconductor initiative accelerates packaging infrastructure investment. Kaohsiung's emerging packaging corridor hosts OSAT consolidation that concentrates adhesive procurement through quarterly locked pricing mechanisms.
Germany
Automotive tier-one suppliers qualify silver sinter pastes for 175°C continuous operation in electric vehicle inverters. The KBA enforces AEC-Q100 validation protocols that extend qualification timelines. Bavaria's automotive electronics corridor around Munich anchors European demand for halogen-free die-attach formulations.
United States
Power module packaging for renewable energy inverters drives specification evolution toward higher thermal conductivity targets. The EPA maintains workplace exposure limits for solvent constituents that affect manufacturing location decisions. Arizona's emerging semiconductor cluster attracts packaging material suppliers seeking proximity to Intel and TSMC fabs.
South Korea
Panel manufacturers anchor demand for ultra-fine pitch anisotropic conductive films in display driver IC attachment. The MFDS regulates chemical substances in electronics manufacturing under parallel frameworks to REACH. Seoul's packaging material supplier district concentrates R&D investment for chiplet architecture compatibility.
Japan
Industrial automation OEMs specify extended operating lifetime adhesives for power supply modules in harsh environments. METI's semiconductor revitalization policy subsidizes domestic packaging material development. Kyushu's silicon island hosts specialized die-attach formulation facilities serving automotive customers.
Semiconductor Packaging Adhesives Market Competitive Landscape
Top-tier vendors anchor automotive qualification programs, while mid-tier specialists serve high-volume consumer electronics through cost-optimized formulations. The supplier base stratifies between reliability-focused automotive-grade providers and velocity-driven OSAT suppliers. Three archetypes dominate: diversified chemical conglomerates with modular formulation platforms, regional specialists with captive automotive relationships, and materials science pure-plays targeting heterogeneous integration nodes. Competitive moves center on co-development partnerships with foundry packaging roadmaps and backward integration into specialty resin production.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Dow Inc. exemplify tier-one positioning through their established die-attach portfolios. DuPont occupies a specialist position in thermal management formulations. These three anchors represent distinct strategic postures: European automotive qualification leadership, North American power module packaging focus, and materials science heritage applied to advanced interconnect challenges.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| H.B. Fuller Company |
| Dow Inc. |
| LG Chem Ltd. |
| DuPont |
| BASF SE |
| Hitachi Chemical Company |
| Sumitomo Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Silver sinter paste qualification for 175°C automotive power modules is compressing cost structures for incumbent epoxy formulators while concentrating procurement leverage among Taiwan-based foundries. This technology transition simultaneously elevates raw material exposure to London Bullion Market Association spot volatility and locks in quarterly pricing mechanisms through TSMC's approved vendor list system.
Pricing Analysis
Short lead-time premiums for automotive-grade die-attach formulations command significant markups over spot inventory discounts in consumer electronics channels. Three-tier pricing structure across automotive-certified, industrial-standard, and economy-grade levels differentiates primarily by AEC-Q100 validation status and thermal cycling performance. Cost compression in consumer electronics wire bonding epoxies is intensifying because Chinese OSATs negotiate locked quarterly contracts with volume guarantees. Automotive tier-one suppliers exhibit the lowest price sensitivity due to eighteen-to-thirty-six-month qualification lock-ins, while memory module assemblers in China demonstrate acute sensitivity to silver flake cost movements.
Supply Chain Analysis
Direct-to-foundry channels handle hyperscale demand from TSMC and ASE Group, displacing traditional distributor relationships for critical packaging materials. Raw material production draws from China for bisphenol-A epoxy resins, South Korea for specialty hardeners, and Japan for high-purity silver flake. Distribution runs through approved vendor lists with quarterly business reviews in Taiwan and South Korea, while German and Japanese automotive lines retain fragmented purchasing patterns. Single-source vulnerability in boron nitride thermal filler supply from Chinese manufacturers presents acute tariff exposure risk for Western formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive qualification timelines and REACH-mandated reformulation costs are forcing sub-scale epoxy suppliers toward exit or acquisition, consolidating viable players around modular formulation platforms with captive resin supply.
For Market Incumbents: Acquire specialty hardener production assets in South Korea or Japan to secure supply continuity amid ECHA authorization pressures for boric acid derivatives. Consolidate formulation R&D around chiplet-compatible underfill platforms to defend against sintering technology substitution in power module attachment. Capacity expansion in Arizona's emerging semiconductor cluster captures proximity premiums from Intel and TSMC packaging investments. For New Entrants and Emerging Players: The premium-to-economy pricing gap in halogen-free automotive die-attach creates entry opportunity for phosphorus-nitrogen flame retardant specialists with qualified European formulations. White-space concentration sits with India's PLI scheme for domestic packaging facilities, where greenfield qualification timelines bypass entrenched East Asian supplier relationships. Target telecommunications infrastructure in India through direct engagement with domestic OSATs seeking non-conductive paste alternatives for optical transceiver assembly. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified chemical conglomerates seeking automotive-grade adhesive portfolios. Five-to-ten-year viability favors suppliers with backward integration into specialty epoxy resin production and locked foundry relationships through TSMC's vendor list. The signal to watch is silver sinter paste adoption velocity in German electric vehicle inverter programs, which would accelerate conductive epoxy displacement and compress valuations for non-sintering specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Production | Captive bisphenol-A hardener supply insulates margins from ECHA authorization delays. |
| Automotive Qualification Fast-Track Investment | AEC-Q100 pre-validation services compress eighteen-month timelines for tier-one supplier entry. |
| Chiplet Architecture Co-Development Partnership | TSMC's CoWoS expansion pulls material suppliers into heterogeneous integration roadmaps. |
| India PLI Scheme Localization | Domestic packaging facility incentives bypass entrenched Taiwan procurement concentration. |
| Silver Sinter Paste Platform Acquisition | 175°C continuous operation capability captures electric vehicle inverter specification evolution. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this semiconductor packaging adhesives assessment. Primary interviews with die-attach formulation chemists, OSAT procurement directors, and automotive tier-one supplier quality engineers combined with bottom-up triangulation against SEC 10-K disclosures and ECHA substance authorization databases. Top-down validation referenced semiconductor production equipment utilization rates and packaging material consumption coefficients from foundry capex disclosures.
Data-stream reconciliation across formulation chemistry, assembly method, and thermal-electrical function segments generated volume and value outputs over the projection horizon. Modeled dimensions included epoxy-silicone-polyurethane-acrylic chemistry splits, flip chip versus wire bonding application shares, and automotive-consumer-industrial-telecom end-use distributions. CAGRs derived from adhesive consumption per vehicle trajectories in advanced driver-assistance system proliferation and heterogeneous integration node expansion forecasts.
Inputs from ECHA candidate list updates and TSMC supplier day presentations were available through the study window; gaps in proprietary foundry yield data introduce uncertainty bands around die-attach intensity assumptions. Forecasts reflect modeled adoption curves for silver sintering substitution and REACH-mandated reformulation cost absorption. Practitioners should monitor AEC-Q100 validation completion rates and phosphorus-based flame retardant qualification timelines for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Electronics Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market