
 High Availability Server Market | 2026-2036
High Availability Server Market Size, Share, and Industry Trends Forecast 2026-2036
High Availability Server Market Intelligence
The substitution of proprietary, vertically-integrated hardware with commodity x86 servers, enabled by advanced virtualization software, is repositioning the economic calculus for enterprise IT infrastructure. Hewlett Packard Enterprise leverages its extensive portfolio to offer integrated hardware and software solutions for this environment. IBM Corporation competes by offering high-performance systems for mission-critical workloads, while Stratus Technologies specializes in fault-tolerant server platforms for specific industrial verticals requiring extreme reliability.
A high availability server is an architecture designed to ensure continuous operational uptime, typically aiming for 99.999% availability through component redundancy and automated failover. Its primary purpose is to support mission-critical applications where service interruption leads to significant financial or operational losses. Within the solutions landscape, disaster recovery and data replication are expanding faster than traditional failover clustering. Hybrid deployment models are also gaining share from purely on-premise strategies, offering a balance of control and scalability for enterprises.
Data governance frameworks significantly influence infrastructure design and procurement. Regulations such as HIPAA in the United States for healthcare data and the EU's GDPR for personal data mandate stringent uptime and security protocols. These rules, alongside data residency laws in countries like China, compel investment in compliant high availability systems. Consequently, vendor selection now prioritizes the ability to deliver solutions that can navigate complex, multi-jurisdictional data sovereignty requirements.
Market Dynamics
The fundamental shift from proprietary, vertically-integrated systems to commodity x86 hardware, abstracted by sophisticated virtualization and containerization software, is the central force shaping the high availability server market. This change alters the economic and operational models for delivering resilient enterprise IT.
Growth Catalysts
- Data Governance Mandates:Regulations like the EU's GDPR and the US's HIPAA impose strict uptime and data protection requirements, compelling investment in certified high availability systems to ensure compliance and avoid penalties.
- Financial Services Expansion:The financial sector's demand for zero-downtime environments for algorithmic trading, online banking, and transaction processing continues to be a primary catalyst for market expansion.
- Hyperscale Infrastructure Concentration:The build-out of massive data center clusters in hubs like the United States, Ireland, and Singapore creates concentrated demand for high availability servers to power regional cloud service delivery.
Market Restraints
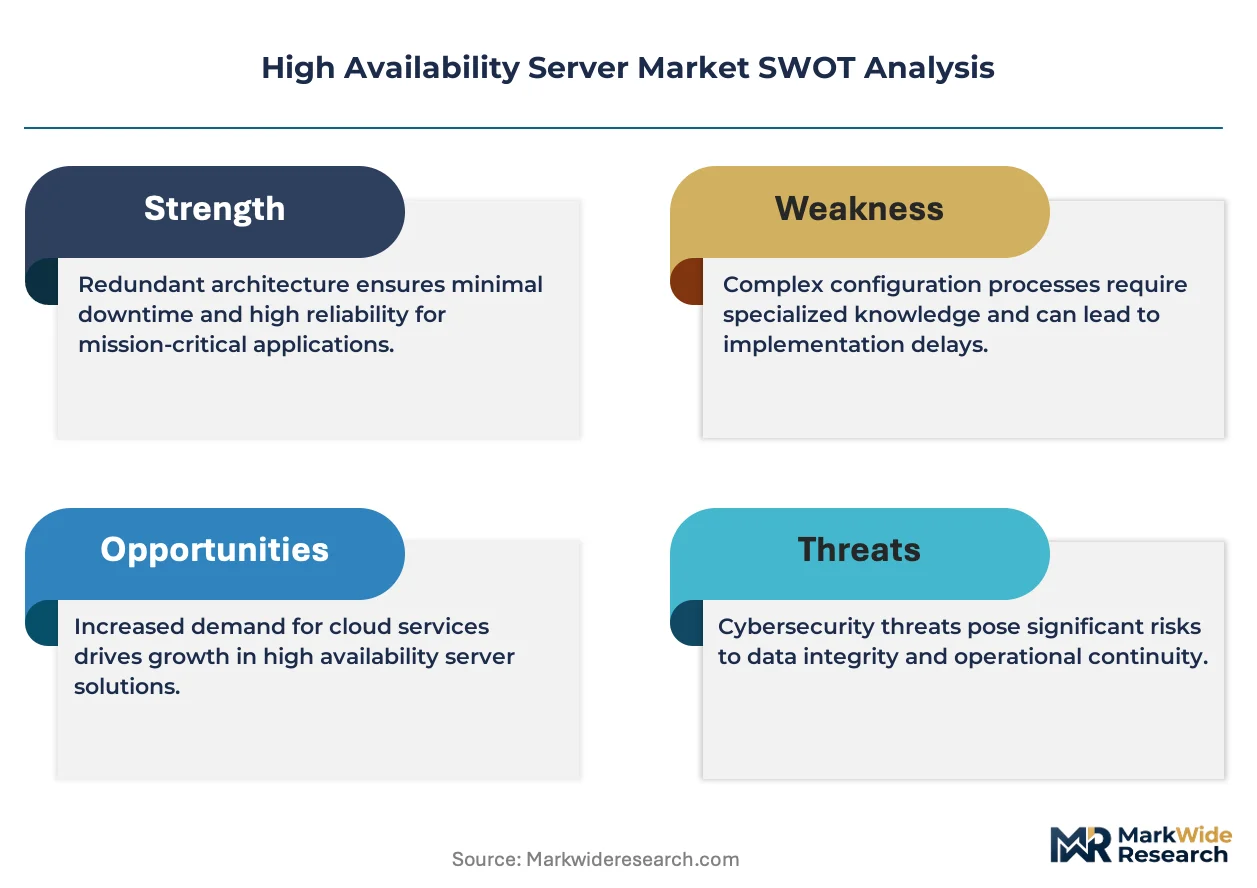
- High Total Cost of Ownership:The significant upfront investment for redundant hardware components, coupled with recurring costs for specialized software licenses and maintenance, presents a substantial barrier for small and medium-sized enterprises.
- Technical Complexity:Designing, implementing, and maintaining fully redundant, automated failover systems requires a high level of specialized IT expertise, which is often in short supply and expensive to retain.
- Cloud Substitution Effect:The increasing reliability and simplified management of infrastructure-as-a-service offerings from major public cloud providers present a viable alternative to building and managing on-premise HA environments.
Strategic Opportunities
- Edge Computing Deployments:The proliferation of IoT devices in industrial and retail settings creates a new frontier for localized high availability servers that can provide low-latency processing and resilience at the network edge.
- AI-Powered Proactive Maintenance:Integrating machine learning algorithms for predictive failure analysis into server management platforms offers an opportunity to shift from reactive failover to proactive fault avoidance, a key value proposition.
- Hybrid Cloud Management Solutions:Enterprises require tools that can orchestrate and manage high availability across a mix of on-premise data centers and multiple public clouds, creating an opportunity for specialized software and services.
Industry Challenges
- Multi-Jurisdictional Compliance:Adhering to a complex and often conflicting web of data sovereignty regulations, such as data residency laws in China and privacy rules in Europe, complicates infrastructure architecture for multinational organizations.
- Legacy System Integration:A persistent challenge involves integrating modern high availability solutions with aging, mission-critical legacy applications that were not designed for distributed, virtualized environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Availability Server Market |
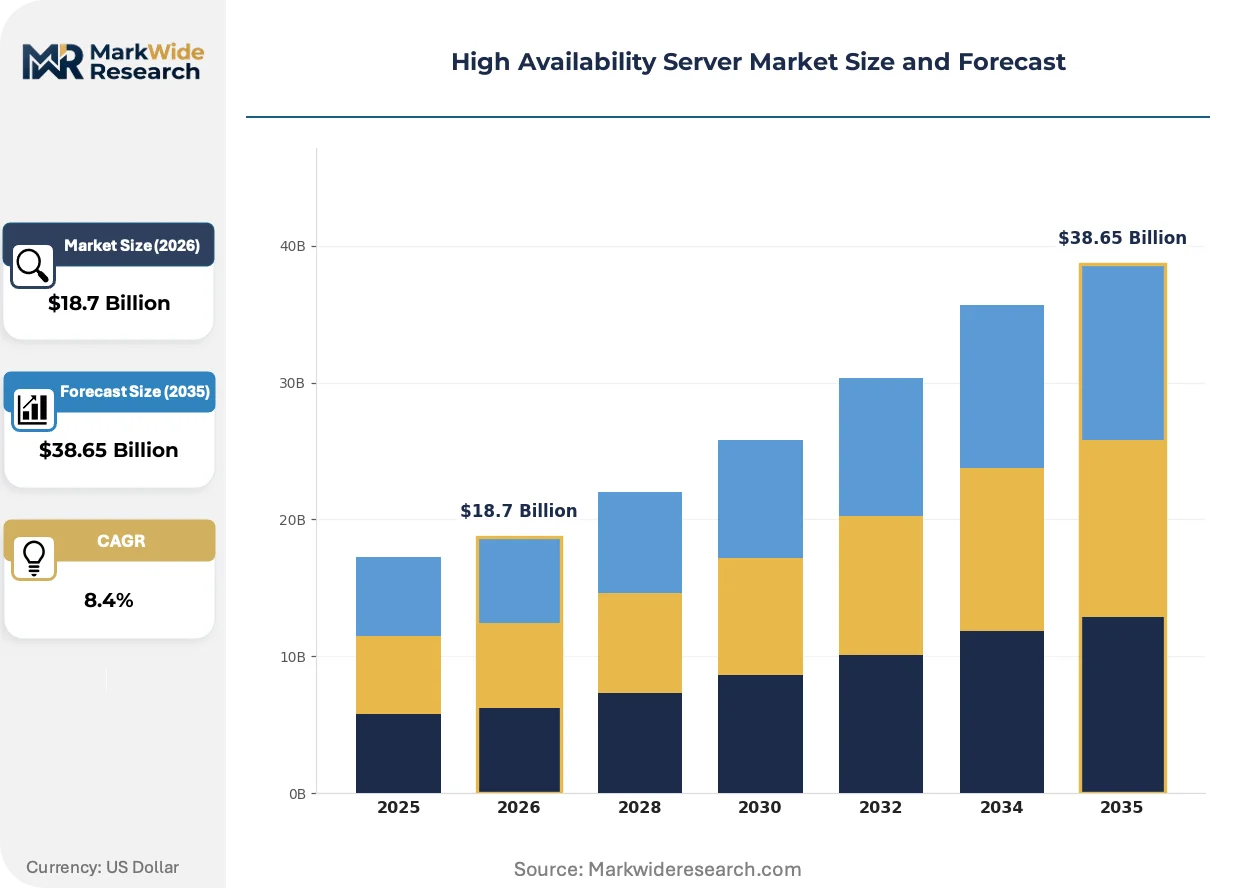
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution/Offering: Failover Clustering, Load Balancing, Data Replication, Disaster Recovery Application: Data Centers, Telecommunications, E-Commerce Platforms, Financial Services End User: Telecom Operators, Banking Institutions, Online Retailers, Government Agencies |
| Companies Covered | IBM Corporation, Dell Inc., Hewlett Packard Enterprise, Cisco Systems, Oracle Corporation, Fujitsu, NEC Corporation, Unisys Corporation, Stratus Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Availability Server Market Strategic Shifts & Innovations
Software-defined resilience is increasingly abstracting availability from the underlying physical hardware, enabling more dynamic and cost-effective failover strategies. This evolution allows enterprises to architect for uptime across hybrid environments, blending private infrastructure with public cloud resources for greater flexibility.
Software-defined networking (SDN) and storage (SDS) technologies provide a programmatic control plane for managing infrastructure resources. Large enterprises and cloud service providers are adopting these solutions to automate the configuration and management of distributed systems. This software-centric model is decentralizing the reliance on purpose-built, proprietary hardware to achieve high levels of system availability.
Data sovereignty regulations like the EU's GDPR are directly influencing infrastructure procurement and design. The framework's stringent rules on data processing and residency compel organizations handling EU citizen data to deploy systems that guarantee both high uptime and compliant data locality. This affects vendor selection, prioritizing suppliers who can demonstrate auditable compliance within their server and software solutions.
A clear shift in procurement is occurring, as enterprises move from perpetual licensing and large capital outlays toward consumption-based models for high availability. This disrupts the traditional sales process, favoring disaster recovery-as-a-service (DRaaS) and subscription-based software that align costs with actual usage. The trend is most visible in North American and European markets, particularly among businesses seeking to convert capital expenses into predictable operating expenses.
High Availability Server Market Segmentation
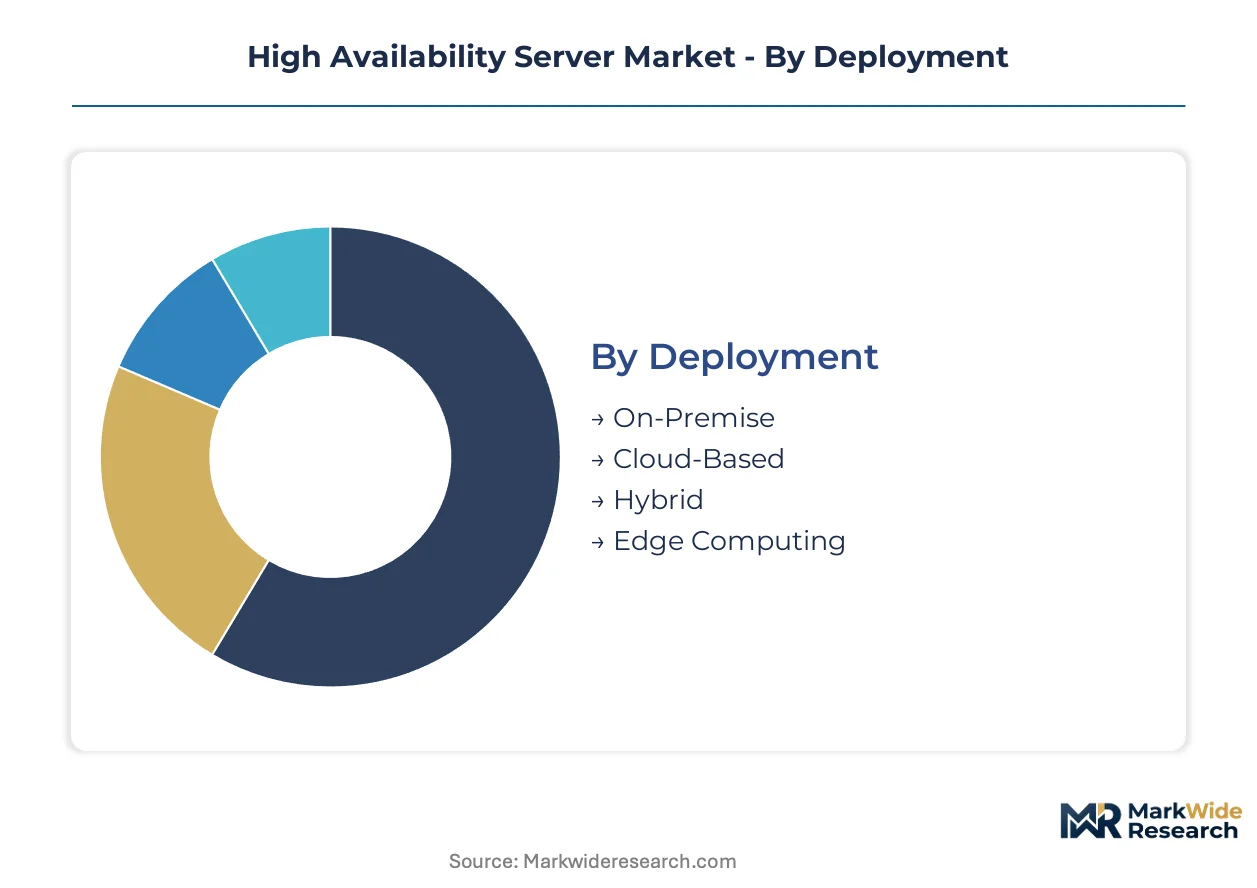
Understanding the High Availability Server Market requires a detailed examination of its constituent segments. Market dynamics vary significantly across different deployment models and solution offerings. This segmentation provides clarity on where investment and innovation are most concentrated within the high availability ecosystem.
Deployment:
Deployment strategies for high availability servers span a spectrum from highly standardized cloud environments to deeply customized on-premise infrastructure.
- Cloud-Based:Cloud-based deployments leverage public cloud infrastructure for high availability services, offering scalability and reduced operational overhead. Demand concentrates in the financial services sector, where rapid elasticity for trading platforms is critical.
- Hybrid:Hybrid deployments integrate on-premise infrastructure with public or private cloud resources, balancing control with scalability. Enterprises in Europe increasingly adopt these models to meet GDPR compliance while optimizing resource utilization.
- On-Premise:On-premise deployments involve installing and managing servers within an organization's own data center, providing full control over data and security.
- Edge Computing:Edge computing places high availability servers closer to data sources, reducing latency for real-time processing in industrial IoT applications.
Leading the category by volume: On-Premise. Growing fastest: Hybrid.
Solution/Offering:
The various solutions within high availability offerings are tailored to specific operational needs and resilience requirements.
- Disaster Recovery:Disaster recovery solutions provide comprehensive strategies for business continuity following catastrophic events, ensuring data integrity and rapid system restoration. Demand is strong among banking institutions in the United States, driven by stringent regulatory mandates from the SEC.
- Data Replication:Data replication involves synchronously or asynchronously copying data to multiple locations, ensuring data availability and consistency across systems. Hyperscale data centers in Singapore utilize this for cross-regional data redundancy.
- Failover Clustering:Failover clustering automatically redirects workloads to a standby server upon primary system failure, maintaining continuous service for critical applications.
- Load Balancing:Load balancing distributes network traffic across multiple servers, optimizing resource utilization and preventing overload for web services.
Disaster Recovery and Data Replication are expanding most quickly, reflecting evolving enterprise resilience strategies.
Application:
Different applications of high availability servers cater to distinct operational requirements and performance benchmarks across various industries.
- Financial Services:Financial services applications demand near-perfect uptime for trading systems, online banking, and transaction processing, where even brief interruptions lead to significant losses. Major banks in Ireland prioritize these systems for their critical payment infrastructure.
- Data Centers:Data centers utilize high availability servers as foundational infrastructure to guarantee continuous operation for hosted applications and cloud services. Hyperscale providers in the United States deploy these extensively for regional cloud hubs.
- Telecommunications:Telecommunications networks rely on high availability servers to ensure uninterrupted voice and data services, supporting critical communication infrastructure.
- E-Commerce Platforms:E-commerce platforms require high availability to handle fluctuating traffic and ensure continuous online sales, preventing revenue loss during peak periods.
Financial Services and E-Commerce Platforms demonstrate the highest growth potential, driven by transaction volume and customer experience demands.
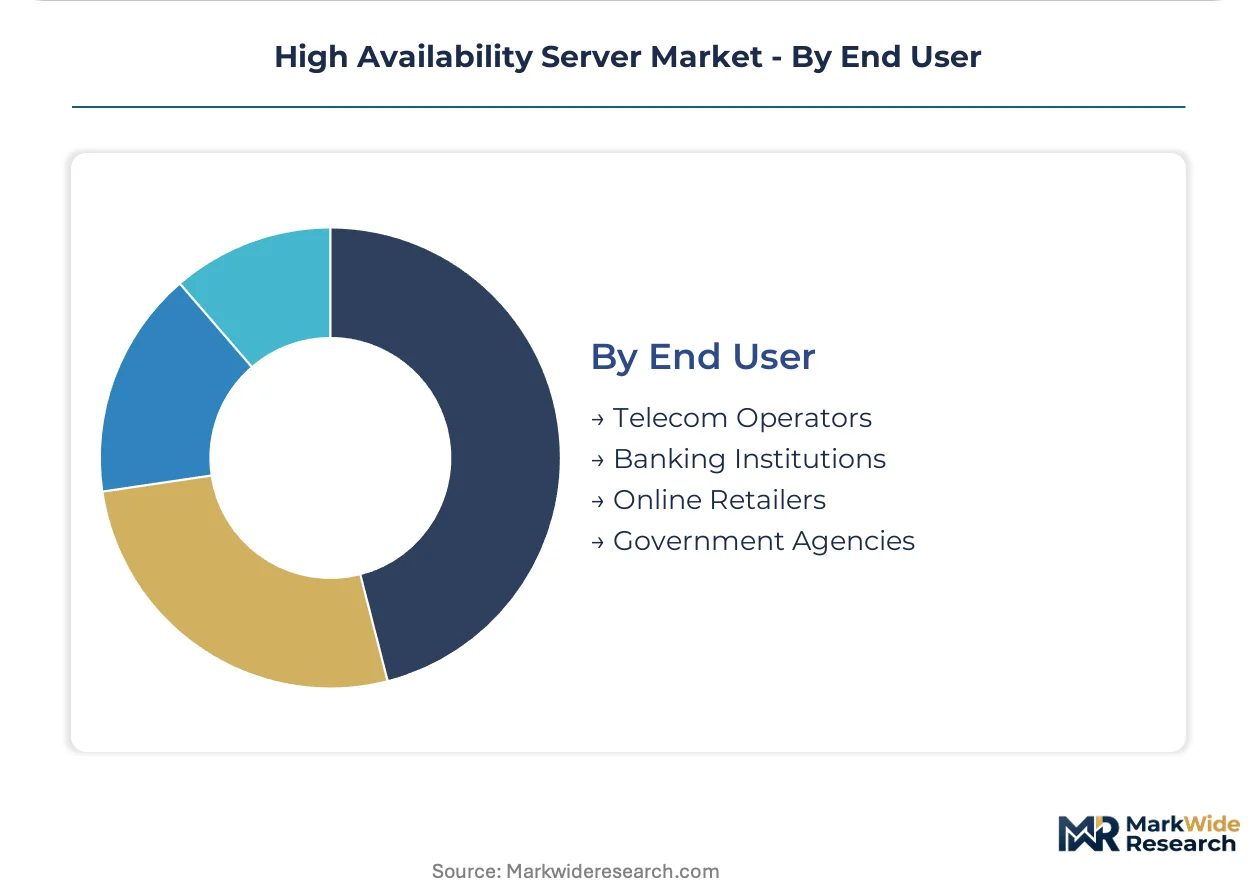
End User:
The diverse end-user base for high availability servers reflects varying scales of operation and specific compliance needs.
- Banking Institutions:Banking institutions deploy high availability servers to secure sensitive financial data and ensure uninterrupted transaction processing, adhering to strict regulatory standards like those from the SEC. European banks prioritize these for compliance with GDPR and continuous service delivery.
- Telecom Operators:Telecom operators depend on high availability servers to maintain continuous network connectivity and service delivery for millions of subscribers. Major operators in China integrate these for robust 5G infrastructure.
- Online Retailers:Online retailers use high availability servers to manage website traffic spikes and ensure consistent e-commerce operations, preventing lost sales.
- Government Agencies:Government agencies leverage high availability servers for critical public services and secure data management, ensuring citizen access to essential information.
Banking Institutions and Telecom Operators are experiencing the steepest expansion trajectory, driven by regulatory compliance and infrastructure demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for high availability servers concentrates heavily in specific global hubs due to critical sector requirements and regulatory mandates. Financial services and hyperscale data centers drive significant investment in regions prioritizing continuous uptime. This concentration shapes infrastructure development and vendor strategies worldwide.
United States
Demand in the United States stems from its expansive financial sector and numerous hyperscale data centers. Regulations like HIPAA and SEC mandates compel investment in resilient systems for data protection and transactional integrity. Silicon Valley and Northern Virginia host extensive data center clusters, powering regional cloud services and critical enterprise applications.
Ireland
Ireland experiences substantial demand from its robust financial services industry and as a key European data center hub. GDPR compliance drives significant investment in resilient infrastructure to ensure personal data protection and uptime for EU operations. Dublin's Silicon Docks area serves as a critical nexus for cloud service providers, supporting vast data replication.
Singapore
Singapore's strategic location positions it as a vital hub for hyperscale data centers and cross-regional data redundancy in Southeast Asia. Strict data residency laws and MAS regulations necessitate robust high availability systems for local and regional operations. Its advanced digital infrastructure facilitates sophisticated data replication strategies for global cloud services.
China
China's vast telecommunications network and burgeoning e-commerce platforms create immense demand for continuous operational uptime. Stringent data residency and cybersecurity laws mandate localized, highly available infrastructure for both domestic and international entities. Major urban centers like Beijing and Shanghai support critical 5G infrastructure and online retail operations.
Germany
German enterprises in industrial IoT and financial services require resilient high availability servers for critical operations. GDPR compliance is a primary driver, ensuring secure and continuously available processing of personal data across the European Union. Frankfurt, a major financial hub, hosts significant data center infrastructure supporting these demanding sectors.
High Availability Server Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the high availability server market. The market structure exhibits a tiered approach, with established technology giants offering integrated solutions alongside niche players providing specialized fault-tolerant systems. Strategic archetypes include diversified IT infrastructure providers, dedicated high-reliability server vendors, and cloud service enablers. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and solution capabilities.
Diversified IT infrastructure providers like Hewlett Packard Enterprise and IBM Corporation exemplify the market's emphasis on integrated hardware and software solutions for mission-critical workloads. Hewlett Packard Enterprise leverages its extensive portfolio to offer comprehensive high availability environments. IBM Corporation competes by providing high-performance systems tailored for demanding enterprise applications. Stratus Technologies, conversely, represents the archetype of a specialized vendor, focusing on fault-tolerant server platforms for specific industrial verticals requiring extreme reliability.
| Leading Market Players |
|---|
| IBM Corporation |
| Dell Inc. |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Oracle Corporation |
| Fujitsu |
| NEC Corporation |
| Unisys Corporation |
| Stratus Technologies |
Cost & Logistics Intelligence
GDPR compliance and other data sovereignty mandates gate access to qualified supply, simultaneously driving demand for premium-tier solutions that can guarantee auditable resilience. The complex interplay between evolving regulatory landscapes and the technical demands of continuous uptime shapes both procurement priorities and vendor investment strategies. This market's pricing and supply chain dynamics are heavily influenced by the specialized nature of high availability components and the need for stringent service level agreements.
Pricing Analysis
Volume sales largely concentrate on commodity x86 hardware, where margins are thinner due to intense competition and virtualization software abstraction. Pricing stratifies across premium, standard, and economy tiers, driven by compliance certifications and customization for complex hybrid environments. Pricing pressure intensifies for basic failover solutions as cloud alternatives offer simplified management and consumption-based models. Financial services and hyperscale providers exhibit the lowest price sensitivity, prioritizing uptime and regulatory adherence over cost, while small and medium-sized enterprises remain highly sensitive to total cost of ownership.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the high availability server supply chain, optimizing delivery for localized data center clusters. Geographic supply concentration for critical components centers on the United States, China, and Taiwan. The industry relies on semiconductor components, specialized cooling systems, and high-speed networking gear. Single-source vulnerability for advanced semiconductor components represents a significant structural risk. Distribution runs through direct sales to hyperscalers and enterprise IT departments, supplemented by value-added resellers offering integration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high availability server market is in a technology-transition phase, with software-defined resilience abstracting availability from legacy proprietary hardware. This shift redefines competitive advantages and demands strategic adaptation from all market participants. Opportunities exist for both established players to consolidate and for new entrants to innovate within specialized niches.
For Market Incumbents: Acquire specialized virtualization software firms to deepen software-defined resilience capabilities and expand integrated solution offerings. Invest heavily in AI-powered predictive maintenance to shift from reactive failover to proactive fault avoidance, mitigating the threat of cloud substitution. Reinforce global compliance expertise to navigate multi-jurisdictional data sovereignty requirements. Leverage existing customer relationships to cross-sell hybrid cloud management solutions.
For New Entrants and Emerging Players: Begin with targeted solutions for edge computing deployments, focusing on industrial IoT applications requiring low-latency processing and localized resilience. Offer consumption-based subscription models for disaster recovery-as-a-service (DRaaS) to appeal to price-sensitive small and medium-sized enterprises. Specialize in multi-cloud orchestration tools that simplify management across diverse public and private cloud environments. Develop pre-integrated solutions for specific industrial verticals to reduce technical complexity for end-users.
For Investors and Strategic Acquirers: Acceleration of hybrid cloud adoption is the leading indicator that signals sustained market expansion for high availability solutions. The market offers sustained long-term viability over the next decade as digital transformation continues across industries. Target niche software providers specializing in data sovereignty compliance or fault-tolerant platform developers for critical industrial applications. Watch for increased investment in multi-cloud orchestration platforms as a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Software-Defined Resilience Startups | Integrates advanced virtualization capabilities, enhancing software-centric availability strategies. |
| Invest in AI-Powered Predictive Maintenance | Shifts operational models from reactive failover to proactive fault avoidance, improving uptime. |
| Develop Multi-Cloud Orchestration Platforms | Addresses enterprise need for seamless high availability management across diverse cloud environments. |
| Expand Edge Computing Solutions | Captures demand for localized, low-latency resilience in industrial and retail IoT applications. |
| Offer Consumption-Based DRaaS Models | Attracts small and medium-sized enterprises by converting capital expenses into predictable operating costs. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and technology whitepapers underwrites the qualitative findings and quantitative projections within this analysis. Primary interviews with IT infrastructure architects, data center managers, compliance officers, and solution integrators provided critical insights. Secondary research from SEC filings, government technology procurement databases, and cloud provider annual reports informed the market sizing and trend identification, triangulating data through both bottom-up and top-down approaches.
The forecast window was anchored to historical reference periods, establishing a baseline for projecting market trajectories across the analysis window. An analytical framework modeled segmentation dimensions including deployment model, solution offering, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived through a rigorous assessment of market drivers and restraints. Key industry-specific forecast inputs included hyperscale data center build-out projections and enterprise IT spending on resilience solutions.
Underlying measurement precision varies by segment; financial services applications and hyperscale data centers carry tighter precision than others due to established reporting. Forecasts reflect assumptions regarding rapid shifts in cloud adoption and evolving data sovereignty regulations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
Composable-Disaggregated Infrastructure Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Data Center IT Asset Disposition Market