
 Composable-Disaggregated Infrastructure Market | 2026-2036
Composable-Disaggregated Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Composable-Disaggregated Infrastructure Market Analysis
Software-defined storage orchestration is decoupling hardware procurement from capacity planning across enterprise data centers. Hewlett Packard Enterprise leverages its Synergy platform to anchor composable rack-scale deployments in Fortune 500 accounts. Dell Technologies competes through PowerEdge MX infrastructure that extends fluid resource pools across compute and storage sleds. Cisco Systems dominates networking-centric disaggregation with its Silicon One architecture, which positions the vendor at the intersection of programmable fabrics and cloud-scale routing.
Composable-disaggregated infrastructure refers to IT architecture that physically separates compute, storage, and networking resources into discrete pools interconnected by high-speed fabric, enabling dynamic allocation via software APIs rather than fixed server configurations. PCIe Gen5 and CXL 2.0 memory pooling specifications now allow sub-microsecond latency between disaggregated components, supporting real-time workload composition for AI training and analytics clusters. Deployment models show hybrid cloud configurations capturing the strongest margin pools as enterprises retain sensitive data on-premises while bursting to public infrastructure. Management software represents the fastest-expanding segment by attach rate, since every hardware pool requires orchestration layers to automate resource discovery, composition, and reclamation across multi-vendor environments.
FCC equipment authorization rules govern radio-frequency emissions from high-speed interconnects deployed in US data centers, while NIST cybersecurity frameworks shape procurement requirements for federal and defense-adjacent composable deployments. The EU F-Gas Regulation and emerging CSRD disclosure mandates push European operators toward liquid-cooled, high-density disaggregated designs that reduce refrigerant dependency and improve power usage effectiveness metrics. Stakeholders must monitor CXL consortium specification roadmaps and regional energy-efficiency rulemakings to time infrastructure transitions before compliance deadlines harden procurement criteria.
Market Dynamics
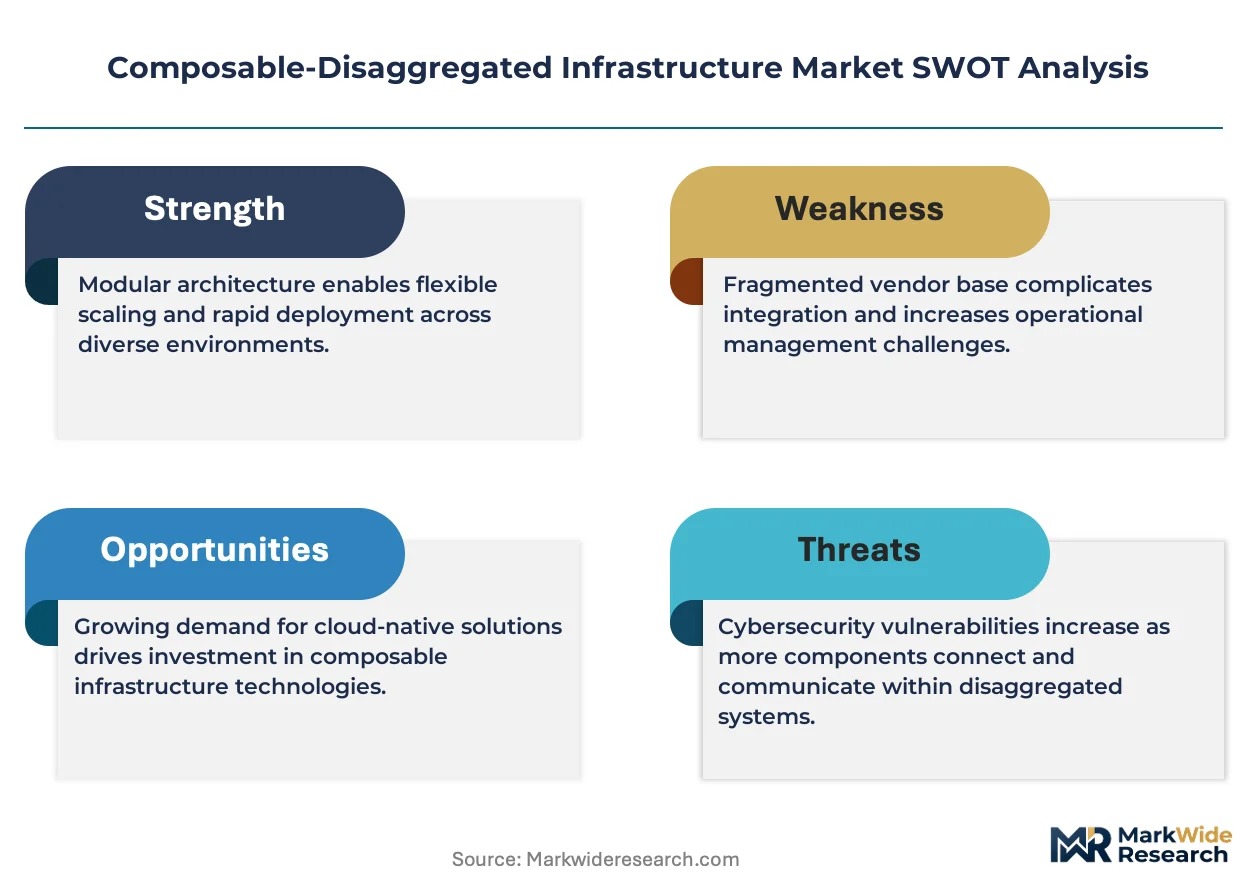
CXL 2.0 memory pooling and PCIe Gen5 fabric standards are compressing hardware refresh cycles as hyperscale operators abandon fixed server configurations for API-composable resource pools.
Growth Catalysts
- EU CSRD disclosure mandates:European data center operators face mandatory power usage effectiveness reporting, accelerating replacement of legacy fixed infrastructure with liquid-cooled, disaggregated designs that improve thermal efficiency metrics.
- AI training cluster procurement:Hyperscale cloud providers in Northern Virginia and Dallas-Fort Worth are deploying rack-scale composable systems to support sub-microsecond latency requirements for large language model training workloads.
- Silicon photonics interconnects:800G optical fabrics are enabling physical separation of compute and memory resources beyond traditional rack boundaries, expanding addressable deployment footprints.
Market Restraints
- High-speed interconnect supply concentration:Advanced PCIe retimers and CXL memory controllers rely on Taiwan-based semiconductor fabrication, creating single-source vulnerability for North American and European system integrators.
- FCC equipment authorization complexity:Radio-frequency emissions testing for 112G SerDes interconnects adds six-to-nine month pre-deployment validation timelines, delaying revenue recognition for federal and defense-adjacent projects.
- Software licensing model friction:Per-socket orchestration pricing from incumbent vendors conflicts with disaggregated pay-per-use consumption models, inflating total cost of ownership during pilot phases.
Strategic Opportunities
- India PLI scheme for servers:Domestic manufacturing incentives are attracting hyperscale investment in Chennai and Hyderabad, creating greenfield demand for composable rack designs without legacy infrastructure drag.
- Memory-centric computing convergence:CXL 3.0 memory expansion devices combined with computational storage drives enable new tiered data placement architectures for real-time analytics.
- ISO/IEC 27001 certification tailwinds:Enterprises pursuing information security management certification favor composable infrastructure for its auditable resource allocation logs and software-defined segmentation capabilities.
Industry Challenges
- Firmware orchestration talent scarcity:Cross-vendor resource composition requires expertise in Redfish APIs, CXL fabric management, and Kubernetes operators that exceeds current supply of platform engineers.
- Multi-generational hardware integration:Enterprises must maintain operational continuity between Gen4 PCIe legacy servers and Gen5/CXL composable pools during multi-year transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composable-Disaggregated Infrastructure Market |
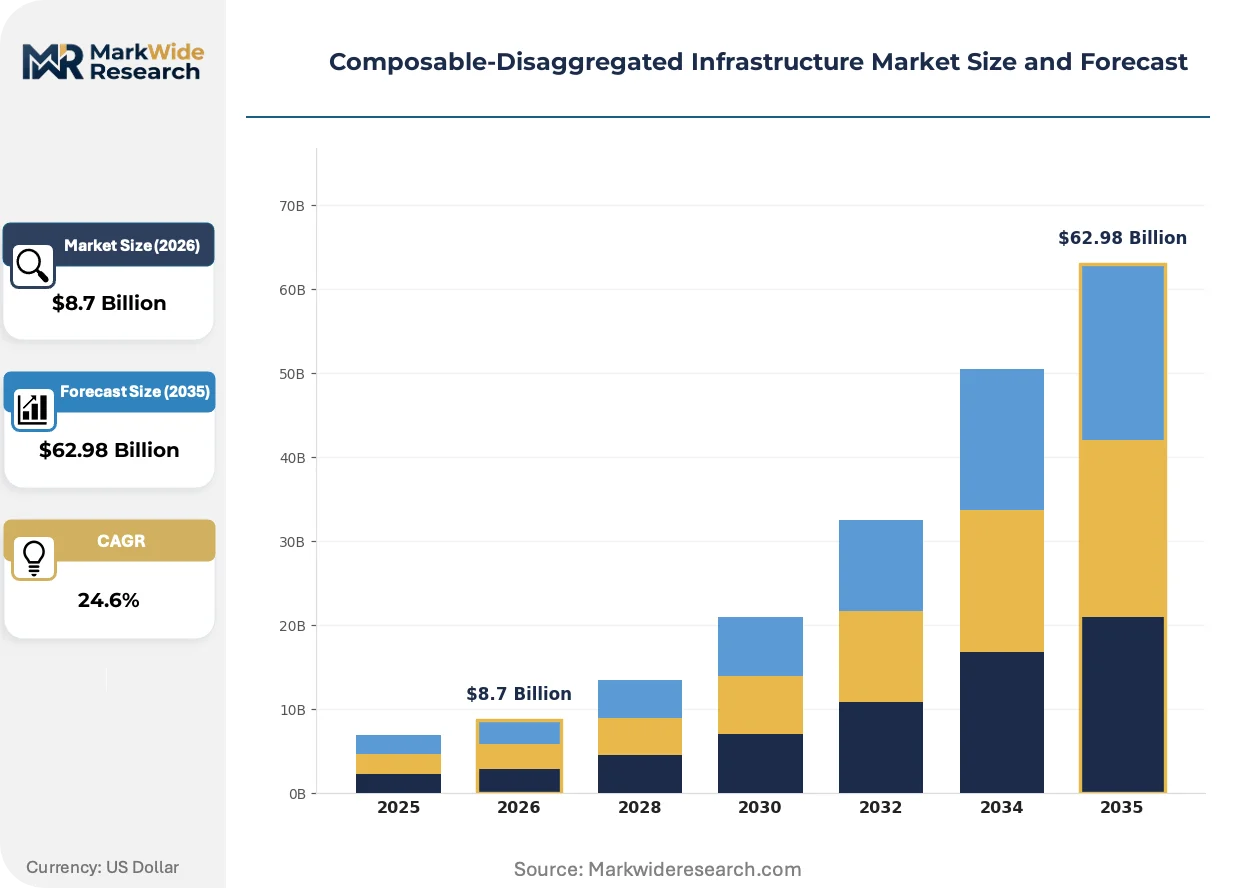
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compute Nodes, Storage Systems, Networking Components, Management Software Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Enterprise, Service Provider, Government, Education Technology: Microservices, Containers, Virtualization, Serverless Computing |
| Companies Covered | Lenovo Group, Ericsson, Hewlett Packard Enterprise, Fungible, Liqid, Dell Technologies, Nutanix, GigaIO Networks, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composable-Disaggregated Infrastructure Market Emerging Trajectories
Software-defined orchestration layers are displacing hardware-centric procurement as the primary value capture point, while energy-efficiency mandates and AI workload requirements reshape physical infrastructure design priorities.
Compute Express Link memory pooling is consolidating server motherboard real estate by enabling DRAM resources to reside in discrete chassis connected via switched fabric rather than socket-adjacent DIMM slots. Hyperscale operators in Northern Virginia are deploying CXL 2.0 memory expansion drawers to support 4TB+ memory configurations per composable node. This topology is compressing traditional server refresh economics by decoupling memory upgrade cycles from CPU replacement.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in data center cooling systems, forcing operators toward liquid-cooled, high-density disaggregated designs. European facility operators are retrofitting existing white space with direct-to-chip cooling manifolds to accommodate 100kW+ composable racks. German and French data center clusters are reporting accelerated hardware procurement timelines to secure compliant infrastructure ahead of 2027 refrigerant quota reductions.
Consumption-based financing models are displacing capital-intensive server purchases among mid-market enterprises wary of fixed asset depreciation. Leasing providers and cloud-adjacent financiers are offering per-hour billing for composable rack capacity, transferring obsolescence risk from balance sheets to infrastructure vendors. This shift is most pronounced in US healthcare and financial services verticals where CFOs prioritize operational expenditure classification for IT assets.
Composable-Disaggregated Infrastructure Market Segmentation
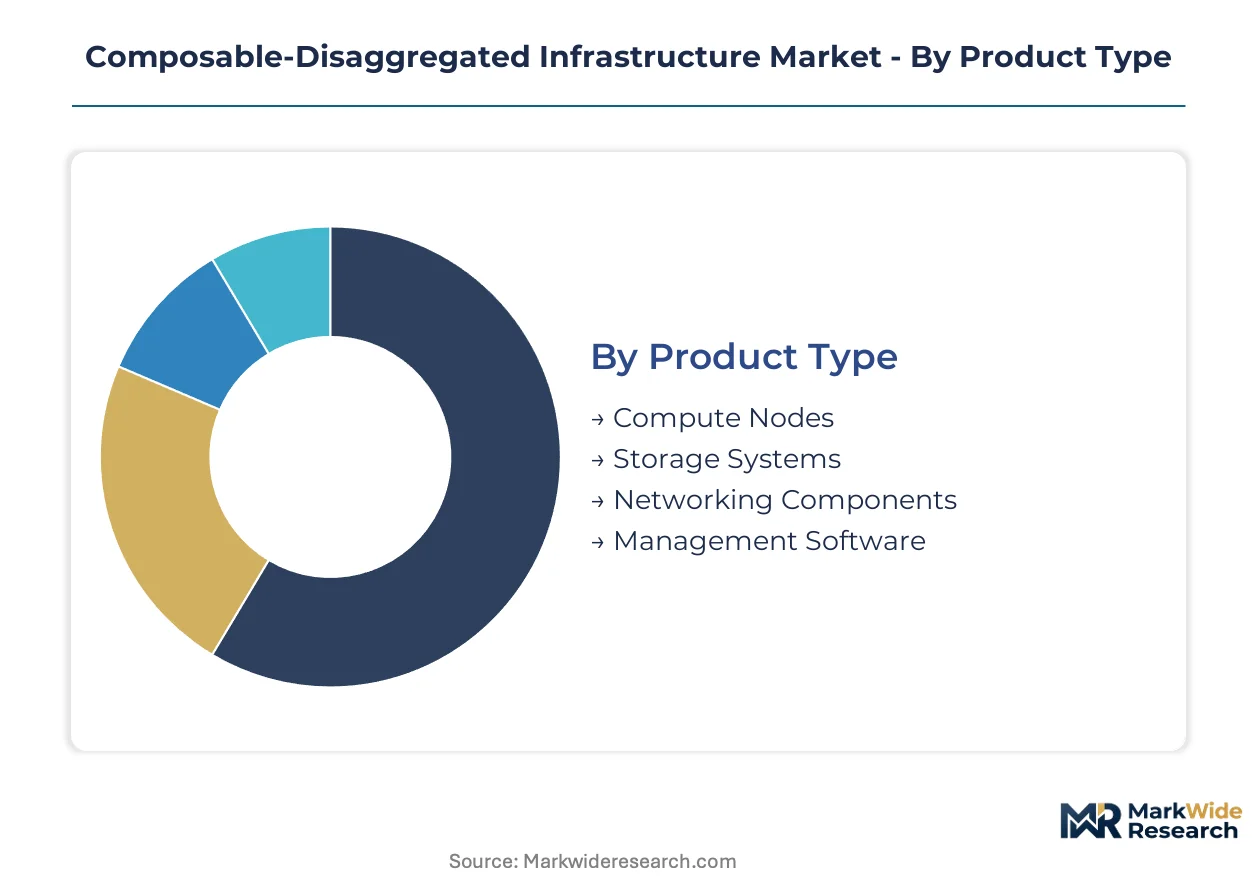
Segmentation in composable-disaggregated infrastructure reveals how software-defined resource pools map to distinct procurement patterns across technology layers, operational models, and buyer archetypes. Understanding these divisions exposes where margin concentrates and which specifications drive replacement cycles.
Product Type:
PCIe Gen5 and CXL fabric specifications now determine hardware form factors and interconnection topologies across all product categories.
- Compute Nodes:Disaggregated CPU and accelerator sleds connect via CXL 2.0 memory fabric, enabling independent refresh cycles. Northern Virginia hyperscale clusters demand 4TB+ memory configurations per composable node for large language model training.
- Management Software:Orchestration layers automate resource discovery, composition, and reclamation across multi-vendor pools. Attach rates climb fastest here as every hardware deployment requires API-driven provisioning.
- Storage Systems:Computational storage drives with embedded processing reduce data movement overhead.
- Networking Components:800G silicon photonics fabrics extend rack-scale disaggregation across data center boundaries.
Compute Nodes lead on scale; Management Software leads on momentum.
Deployment Model:
Financing structures and compliance postures shape how enterprises distribute workloads across infrastructure ownership models.
- Hybrid Cloud:Enterprises retain sensitive data on-premises while bursting to public infrastructure, capturing the strongest margin pools through operational expenditure classification. US healthcare and financial services verticals favor this model for CFO-preferred opex treatment.
- Private Cloud:Single-tenant composable racks serve regulated industries requiring auditable resource allocation logs.
- Public Cloud:Hyperscale operators offer composable instances as managed services.
- On-Premises:Capital-intensive purchases persist in defense-adjacent deployments with NIST cybersecurity framework requirements.
Hybrid Cloud configurations concentrate revenue; Private Cloud deployments show steepest expansion trajectory among regulated sectors.
End User:
Procurement authority and workload sensitivity create distinct technical requirements across buyer categories.
- Service Provider:Telecom and colocation operators deploy rack-scale composable systems to offer flexible infrastructure-as-a-service. India's PLI scheme attracts hyperscale investment in Chennai and Hyderabad for greenfield composable designs.
- Enterprise:Fortune 500 accounts anchor composable adoption through rack-scale deployments with consumption-based financing.
- Government:Federal and defense-adjacent projects face six-to-nine month FCC equipment authorization timelines for 112G SerDes interconnects.
- Education:Research institutions leverage composable pools for shared high-performance computing access.
Service Providers lead on scale; Enterprise accounts lead on momentum.
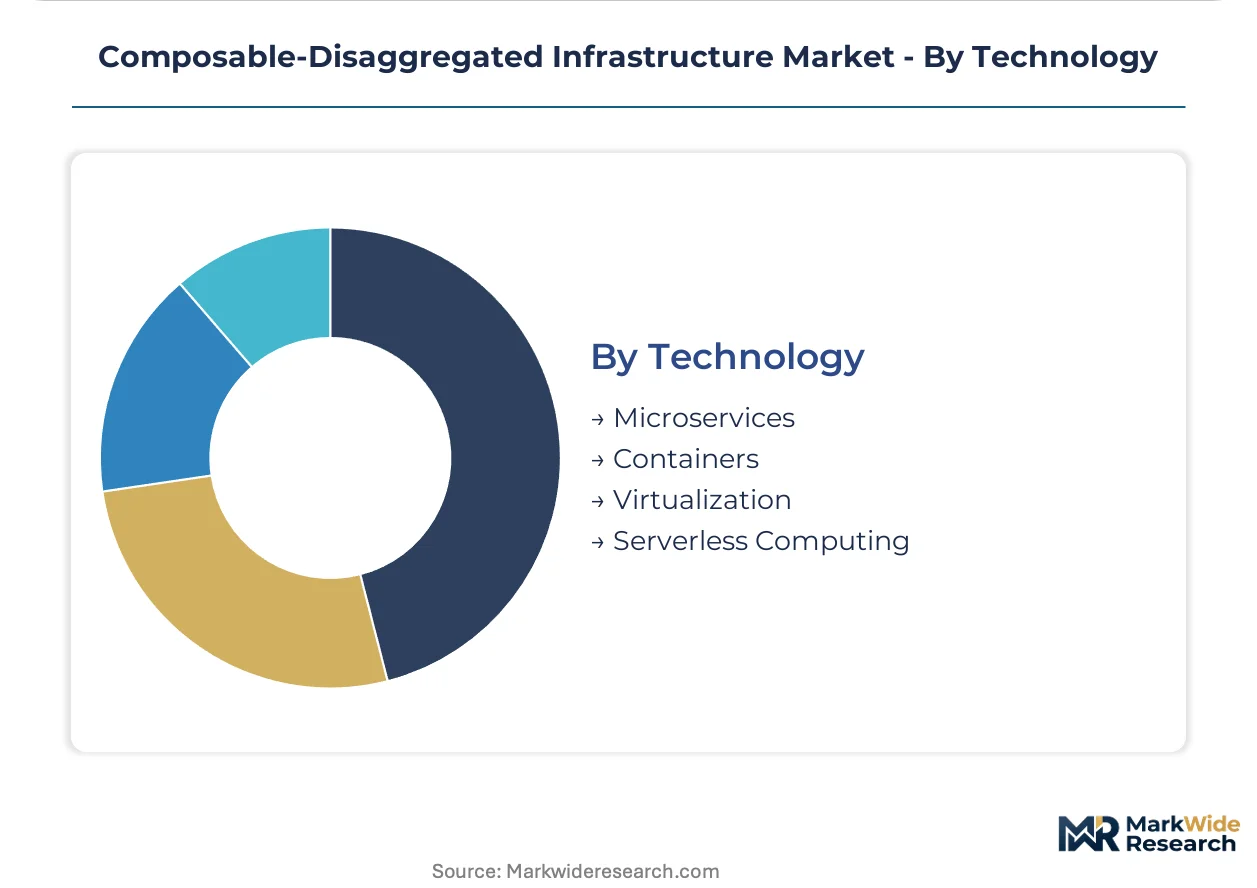
Technology:
Abstraction layers determine how disaggregated hardware resources present to application workloads.
- Containers:Kubernetes operators manage composable resource composition through Redfish APIs, though platform engineering talent scarcity constrains deployment velocity. Containerized workloads dominate AI training cluster orchestration.
- Virtualization:Legacy hypervisor stacks bridge Gen4 PCIe servers and Gen5/CXL composable pools during multi-year transition windows.
- Microservices:Fine-grained service decomposition matches composable infrastructure's dynamic allocation model.
- Serverless Computing:Event-driven execution abstracts hardware composition entirely from developers.
Virtualization leads on installed base; Containers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates hyperscale deployment velocity while Germany drives regulatory-compliant infrastructure refresh, creating divergent procurement timelines across Atlantic markets.
United States
Northern Virginia and Dallas-Fort Worth data center clusters anchor domestic demand for rack-scale composable systems. FCC equipment authorization rules govern 112G SerDes interconnect deployments, adding six-to-nine month validation timelines for federal-adjacent projects. NIST cybersecurity frameworks shape procurement specifications across defense and intelligence community infrastructure.
Germany
Frankfurt and Berlin data center operators face accelerated hardware replacement under EU F-Gas Regulation refrigerant phase-down mandates. The national implementation of CSRD disclosure requirements forces power usage effectiveness reporting that favors liquid-cooled, disaggregated designs. Bavarian industrial computing facilities are retrofitting existing white space with direct-to-chip cooling manifolds ahead of 2027 quota reductions.
India
Chennai and Hyderabad hyperscale campuses attract greenfield investment under the PLI scheme for server manufacturing. The domestic incentive structure enables composable rack deployments without legacy infrastructure drag. CEA efficiency standards for data centers are tightening, pushing operators toward high-density disaggregated architectures that reduce per-workload energy intensity.
United Kingdom
London and Slough data center clusters serve financial services demand for auditable resource allocation logs under GDPR and emerging financial conduct authority guidance. The national net-zero data center roadmap pressures operators toward liquid-cooled infrastructure that improves thermal efficiency metrics. ISO/IEC 27001 certification tailwinds favor composable systems for their software-defined segmentation capabilities.
Japan
Tokyo and Osaka metropolitan areas concentrate enterprise demand for hybrid cloud configurations with on-premises sensitive data retention. METI energy-efficiency standards for data centers are accelerating replacement of fixed server configurations with API-composable resource pools. Kansai region manufacturing facilities are deploying CXL 2.0 memory expansion drawers to support high-memory analytics workloads.
Composable-Disaggregated Infrastructure Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with systems integrators capturing hardware margins while software vendors extract recurring revenue from orchestration layers. The vendor base organizes around three archetypes: legacy server manufacturers extending into composable form factors, networking specialists leveraging programmable fabric expertise, and pure-play orchestration software vendors. Strategic moves concentrate on M&A to secure CXL controller IP and strategic partnerships to bypass Taiwan-based semiconductor fabrication bottlenecks.
Among established systems vendors, Hewlett Packard Enterprise and Dell Technologies exemplify the server-centric archetype, while Cisco Systems anchors the networking-specialist position. These three companies sit within the tier of full-stack infrastructure providers that combine hardware manufacturing with software-defined management layers. Their competitive positioning reflects divergent heritage advantages—compute versus networking DNA—rather than convergent capability sets.
| Leading Market Players |
|---|
| Lenovo Group |
| Ericsson |
| Hewlett Packard Enterprise |
| Fungible |
| Liqid |
| Dell Technologies |
| Nutanix |
| GigaIO Networks |
| Cisco Systems |
| Others |
Supply Flow & Price Mechanics
Firmware orchestration talent scarcity in Taiwan and South Korea compresses labor-cost differentials between premium CXL controller modules and standard PCIe Gen5 interconnects, widening pricing-tier spreads across North American system integrators.
Pricing Analysis
Capacity additions in Taiwan are reshaping price floors for advanced PCIe retimers and CXL memory controllers. Three-tier pricing structure across premium, standard, and economy levels separates liquid-cooled rack-scale deployments from air-cooled configurations and refurbished legacy sleds. Cost compression in standard-tier hardware is intensifying because hyperscale procurement teams negotiate volume-scale discounts for Northern Virginia and Dallas-Fort Worth clusters. Service providers exhibit highest price sensitivity due to thin infrastructure-as-a-service margins, while defense-adjacent buyers prioritize NIST cybersecurity framework compliance over unit cost.
Supply Chain Analysis
Refurbishment flows for Gen4 PCIe servers extend hardware lifecycles and delay composable refresh demand across European enterprise accounts. Taiwan, South Korea, and the United States anchor semiconductor fabrication for high-speed interconnects. Raw material dependencies include silicon photonics substrates, 112G SerDes PHYs, and CXL protocol controllers. Single-source vulnerability for Taiwan-based CXL controller foundries threatens North American system integrator procurement timelines. Distribution runs through direct OEM channels for hyperscale contracts and value-added resellers for mid-market enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder. EU F-Gas Regulation refrigerant phase-down mandates and CSRD disclosure requirements are forcing accelerated hardware replacement cycles across European data center operators.
For Market Incumbents: Hedge against Taiwan-based semiconductor fabrication bottlenecks by securing secondary-source agreements with South Korean foundries for CXL memory controllers. Deepen backward integration into liquid-cooled manifold production to capture margin pools from EU thermal efficiency mandates. Incumbent vendors face margin pressure from pure-play orchestration software vendors extracting recurring revenue without hardware exposure.
For New Entrants and Emerging Players: Capture greenfield demand under India's PLI scheme for servers in Chennai and Hyderabad hyperscale campuses, where legacy infrastructure drag is absent. Target mid-market US healthcare and financial services verticals with consumption-based financing models that transfer obsolescence risk to infrastructure vendors. Lead with ISO/IEC 27001 certification as a go-to-market wedge for enterprises pursuing auditable resource allocation logs.
For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, seeking vertical integration into CXL controller IP and silicon photonics interconnect capabilities. Over the projection horizon, acquisition targets with Redfish API orchestration expertise and Kubernetes operator development capacity offer strongest strategic fit. Monitor CXL consortium specification roadmaps for 3.0 memory expansion device commercialization as an inflection indicator for memory-centric computing convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| CXL Controller IP Acquisition | Secures semiconductor fabrication independence from Taiwan-based single-source vulnerabilities. |
| Liquid-Cooled Rack Deployment | Positions vendors ahead of EU F-Gas Regulation refrigerant quota reductions. |
| Redfish API Orchestration Platform | Captures fastest-expanding software attach rates across multi-vendor environments. |
| India PLI Scheme Manufacturing Footprint | Enables greenfield composable designs without legacy infrastructure transition costs. |
| ISO/IEC 27001 Certification Investment | Unlocks regulated enterprise procurement favoring auditable resource allocation logs. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged data center facility operators, hyperscale cloud procurement executives, CXL consortium technical committee members, and platform engineering leads at Fortune 500 enterprises. Secondary validation drew from hyperscaler capex disclosures, FCC equipment authorization filings, EU CSRD regulatory texts, and CXL specification documentation. Bottom-up deployment modeling and top-down infrastructure spend analysis were triangulated against vendor shipment data.
Segment-weighting approaches distributed value across product type, deployment model, end user, and technology abstraction layers. CAGRs were derived from install-base growth curves and replacement-cycle compression factors. Forecast inputs included CXL 2.0 and 3.0 specification adoption timelines, EU energy-efficiency mandate compliance deadlines, and hyperscale cluster expansion announcements across the analysis window.
Supply chain disruption, regulatory timeline acceleration, and CXL consortium specification delays are the dominant revision risks. Forecasts reflect underlying assumptions about interconnect standardization velocity and regional energy-efficiency rulemaking enforcement. Practitioners should monitor Taiwan semiconductor fabrication capacity utilization, EU F-Gas Regulation implementation pace, and hyperscale capital expenditure guidance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
Data Center Asset Management Market