
 Europe Green Data Center Market | 2026-2036
Europe Green Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Data Center Market Foresight
Multi-source energy procurement is pivoting toward long-term renewable power purchase agreements across European data center operators. Equinix, Inc. leverages its interconnection platform to anchor green energy commitments across 13 European metros. Schneider Electric sustains technology leadership through integrated power and cooling architectures purpose-built for low-PUE environments. NTT Global Data Centers EMEA GmbH competes on geographic density in Frankfurt, London, Amsterdam, and Paris corridors.
Europe green data center denotes a facility engineered to minimize environmental impact through renewable power integration, advanced cooling systems targeting power usage effectiveness below 1.2, and waste heat recovery mechanisms serving district heating networks. Liquid-cooling technology dominates high-performance computing deployments where direct-to-chip cold plates displace air-cooling above 50 kilowatts per rack. Modular infrastructure leads capital deployment by compressing construction timelines and enabling incremental capacity scaling. Colocation providers represent the fastest-growing end user segment as enterprises outsource facility ownership to operators with verified renewable energy supply chains.
EU Green Deal carbon neutrality targets, Ecodesign for Servers regulations, and national building efficiency codes collectively mandate measurable energy performance disclosure and progressive carbon intensity reductions. EMA and national regulators in Germany and France are incorporating embodied carbon criteria into facility permitting processes. Stakeholders must monitor evolving grid interconnection rules and renewable energy certification standards that determine which facilities qualify for green financing instruments.
Market Dynamics
EU Green Deal carbon neutrality mandates and Ecodesign for Servers regulations are compressing deployment timelines as operators race to secure renewable power contracts before grid interconnection queues lengthen.
Growth Catalysts
- EU Green Deal:Binding 2050 climate neutrality targets force facility operators to source verified renewable electricity, accelerating power purchase agreement volumes across German and Dutch grids.
- Liquid cooling:Direct-to-chip cold plate systems enable rack densities above 50 kilowatts, unlocking high-performance computing deployments previously constrained by air-cooling thermal ceilings.
- Financial services:Banking and insurance firms face ESG disclosure pressure under CSRD, driving colocation demand at facilities with certified renewable supply chains and measurable PUE below 1.2.
Market Restraints
- Grid interconnection queues:Connection delays for renewable projects in Ireland and the Netherlands extend facility commissioning timelines by 18-36 months, stranding committed capital.
- Skilled technician scarcity:Specialized labor for liquid-cooling infrastructure installation and maintenance concentrates in Germany and France, creating wage inflation and project bottlenecks.
- Embodied carbon accounting:EMA and national regulators in France now require lifecycle carbon disclosure for steel and concrete inputs, complicating permitting for hyperscale builds.
Strategic Opportunities
- Waste heat recovery:District heating network integration in Nordic markets allows operators to monetize thermal output, transforming energy cost centers into revenue streams.
- Modular prefabrication:Factory-built power and cooling modules compress European construction timelines from 24 months to 12 months, enabling faster market entry in constrained urban zones.
- Green financing eligibility:EU Taxonomy alignment requirements channel institutional capital toward facilities with verified renewable certificates, lowering weighted average cost of capital for qualifying projects.
Industry Challenges
- Legacy facility retrofitting:Existing air-cooled data centers in London and Frankfurt face structural constraints integrating liquid-cooling manifolds without full mechanical system replacement.
- Cross-border certification fragmentation:Divergent national interpretations of renewable energy guarantees of origin between Germany, France, and Ireland complicate pan-European portfolio standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Data Center Market |
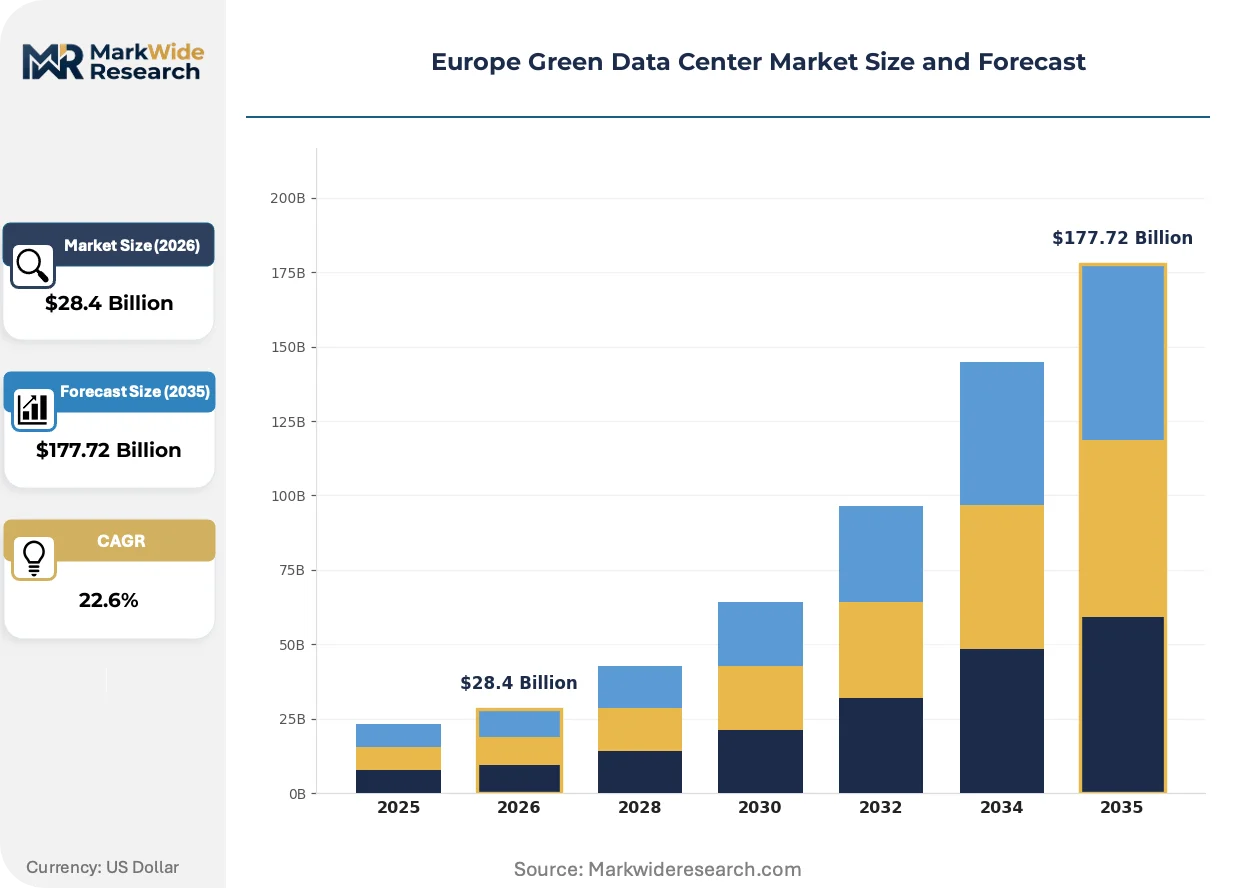
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $177.72 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Modular, Containerized, Hyperconverged, Traditional Cooling Technology: Air-Cooling, Liquid-Cooling, Evaporative, Direct-To-Chip Power Source: Renewable, Solar, Wind, Biomass End User Segment: IT Services, Colocation Providers, Enterprises, Cloud Providers |
| Companies Covered | Equinix, Inc., Digital Realty, Green Mountain AS, Schneider Electric, NTT Global Data Centers EMEA GmbH, OVH Groupe SAS, Interxion Holding N.V., Colt Data Centre Services, Vertiv Holdings Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Data Center Market Shifts & Advancements
Technology convergence between power infrastructure and thermal management is collapsing traditional engineering silos, while regulatory disclosure requirements reshape competitive differentiation around verified carbon intensity metrics.
Immersion cooling using dielectric fluids is consolidating market share in high-performance computing deployments where direct liquid contact eliminates air-handling infrastructure entirely. Hyperscale operators in the Netherlands and Ireland are adopting two-phase immersion systems for AI training clusters above 100 kilowatts per rack. This thermal approach is consolidating supplier relationships around integrated fluid-and-hardware vendors capable of warrantying complete system performance.
CSRD corporate sustainability reporting obligations now mandate Scope 3 emissions disclosure from data center operators serving listed European enterprises. The regulation forces facility providers to audit supply chain carbon intensity and obtain third-party verification of renewable energy claims. German and French operators face the steepest compliance curves as national transpositions impose earlier disclosure deadlines than minimum EU requirements.
Power purchase agreement structures are evolving from virtual to sleeved arrangements as buyers seek direct grid connection to specific renewable assets rather than certificate trading. Large European banks and cloud providers now stipulate physical delivery contracts in RFP criteria, bypassing traditional utility intermediaries. This procurement evolution concentrates contract negotiation leverage with developers holding permitted projects in grid-constrained regions like Ireland and northern Germany.
Europe Green Data Center Market Segmentation
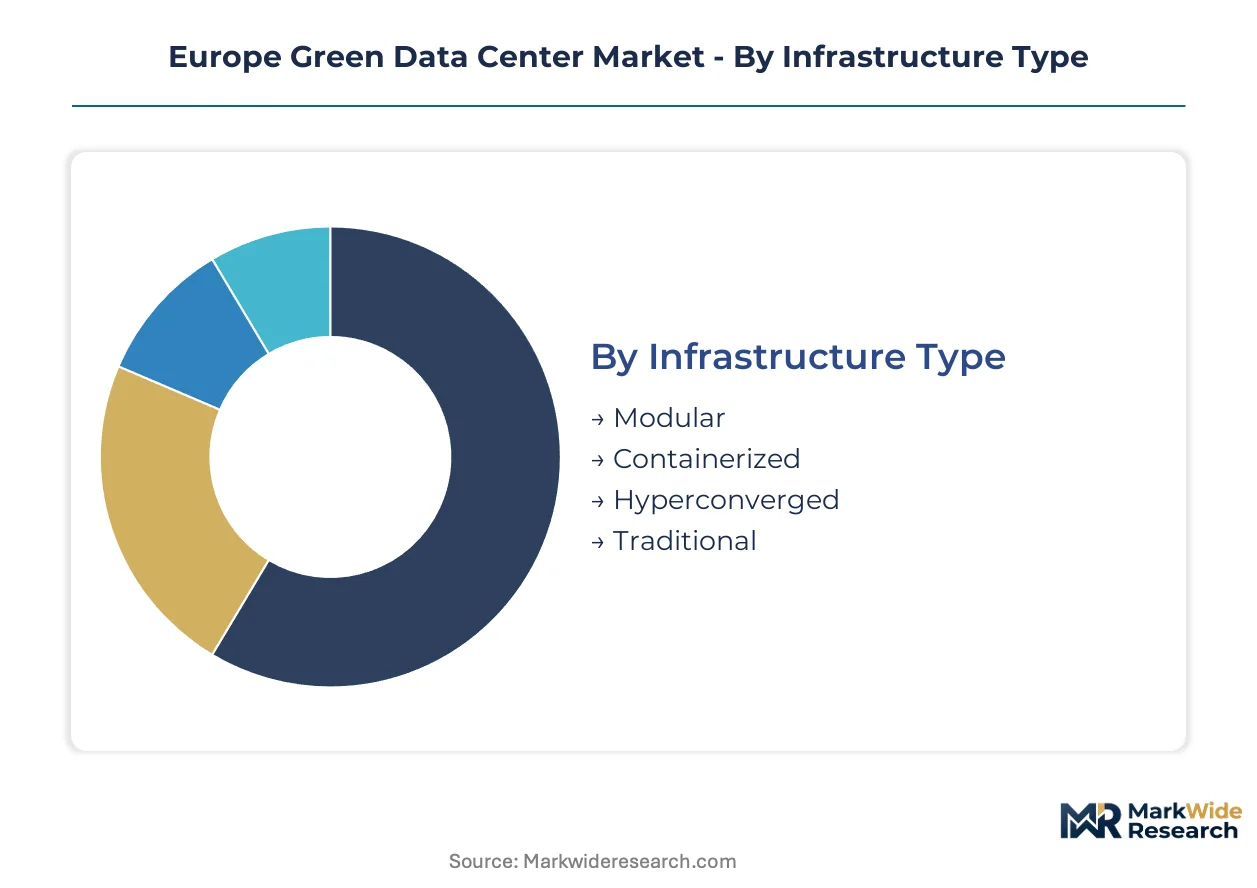
Green data center procurement decisions in Europe hinge on distinct technical and commercial trade-offs. Infrastructure modularity, cooling density thresholds, renewable verification standards, and tenancy models each create separate competitive arenas with divergent margin structures and capital intensity requirements.
Infrastructure Type:
Capital deployment velocity and site constraints determine infrastructure selection across German, Dutch, and Irish development corridors.
- Modular:Factory-built power and cooling modules compress construction timelines from 24 months to 12 months. Colocation providers in Amsterdam and Frankfurt favor this approach for constrained urban infill sites where phased capacity expansion reduces stranded asset risk.
- Containerized:Standardized shipping-container footprints enable rapid deployment at edge locations and temporary compute clusters. Irish hyperscale developments use containerized units to bypass lengthy building permits while awaiting permanent facility completion.
- Hyperconverged:Tightly integrated compute-storage-networking stacks reduce physical footprint and cabling complexity. Financial services firms in London and Paris deploy hyperconverged infrastructure to minimize facility space requirements under strict urban planning restrictions.
- Traditional:Purpose-built concrete and steel structures with custom mechanical systems remain standard for large-scale cloud campuses. German operators continue specifying traditional builds where 15-20 year asset lifecycles justify higher upfront construction costs.
Traditional infrastructure leads on scale; modular leads on momentum.
Cooling Technology:
Rack power density thresholds and ambient climate conditions drive cooling technology selection across European facility portfolios.
- Liquid-Cooling:Direct-to-chip cold plate systems enable rack densities above 50 kilowatts, unlocking high-performance computing deployments previously constrained by air-cooling thermal ceilings. Dutch and Irish hyperscale operators specify liquid-cooling for AI training clusters where heat rejection requirements exceed conventional HVAC capacity.
- Direct-To-Chip:Refrigerant-based microchannel cold plates attach directly to processor packages, eliminating intermediate heat transfer loops. German high-performance computing facilities favor this approach for sub-1.2 PUE targets under national building efficiency codes.
- Air-Cooling:Conventional raised-floor designs with computer room air handlers dominate legacy facility retrofits. London and Frankfurt operators face structural constraints integrating liquid-cooling manifolds without full mechanical system replacement.
- Evaporative:Adiabatic cooling towers leverage low wet-bulb temperatures in Nordic markets to reduce mechanical refrigeration load. Swedish and Finnish data centers achieve sub-1.1 PUE using evaporative systems combined with free cooling economizers.
Air-cooling leads on installed base; liquid-cooling leads on expansion trajectory.
Power Source:
Renewable verification standards and grid interconnection availability shape power procurement strategies.
- Renewable:Verified renewable electricity through power purchase agreements satisfies EU Green Deal mandates and CSRD disclosure requirements. German and Dutch operators now stipulate physical delivery contracts rather than certificate trading to secure green financing eligibility.
- Wind:Onshore and offshore wind farms in northern Germany and the Netherlands provide baseload renewable supply with high capacity factors. Irish hyperscale developments cluster near western coast wind resources to minimize grid transmission constraints.
- Solar:Photovoltaic installations pair with battery storage to reduce grid dependency during peak pricing periods. Southern European facilities in Spain and Italy exploit higher solar irradiance for behind-the-meter generation.
- Biomass:Anaerobic digestion and forestry residue plants offer dispatchable renewable output independent of weather variability. Nordic district heating networks increasingly source data center waste heat through biomass-integrated energy systems.
Wind leads on contracted volume; solar leads on project pipeline growth.
End User Segment:
Tenancy models and compliance obligations differentiate customer requirements across the European market.
- Colocation Providers:Multi-tenant facilities with certified renewable supply chains and measurable PUE below 1.2 attract enterprises outsourcing facility ownership. Banking and insurance firms facing ESG disclosure pressure under CSRD drive demand concentration in Frankfurt, London, Amsterdam, and Paris corridors.
- Cloud Providers:Hyperscale operators require scalable renewable capacity with direct grid connection to specific assets. Large European banks and cloud providers now stipulate sleeved power purchase agreements bypassing traditional utility intermediaries.
- IT Services:Systems integrators and managed service providers seek flexible capacity with short-term contracts and rapid provisioning. Modular infrastructure deployments in urban edge locations serve IT services firms with unpredictable workload scaling requirements.
- Enterprises:Single-tenant facilities for manufacturing, healthcare, and retail operators prioritize security isolation and custom compliance certifications. German automotive and pharmaceutical enterprises maintain captive data centers with direct renewable power contracts to satisfy supply chain audit requirements.
Colocation providers lead on revenue concentration; cloud providers lead on capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main corridor anchors European green data center deployment through renewable energy access and dense fiber interconnectivity. National regulatory frameworks and grid infrastructure quality determine facility location decisions across the continent.
Germany
Frankfurt's concentration of financial services firms drives colocation demand with strict PUE requirements under national building efficiency codes. The Ecodesign for Servers regulations mandate progressive energy performance disclosure for all new facilities. Bavarian hyperscale developments near Munich leverage direct grid connections to Alpine hydroelectric resources.
Netherlands
Amsterdam's submarine cable landing points attract cloud providers seeking low-latency transatlantic connectivity. National regulators impose embodied carbon criteria in facility permitting processes under EU Green Deal transposition. Dutch operators lead two-phase immersion cooling adoption for AI training clusters above 100 kilowatts per rack.
Ireland
Dublin's favorable corporate tax regime concentrates hyperscale campus development despite grid interconnection queue delays. The country's national building regulator now requires lifecycle carbon disclosure for steel and concrete inputs. Western coast wind resources supply direct renewable power to facilities clustered near Galway and Limerick.
France
Parisian financial institutions under CSRD disclosure pressure seek certified renewable supply chains with measurable carbon intensity. ANSM and national regulators incorporate embodied carbon criteria into facility permitting earlier than minimum EU requirements. Ile-de-France operators face the steepest compliance curves for third-party verification of renewable energy claims.
Sweden
Nordic free cooling economics enable sub-1.1 PUE operations without mechanical refrigeration load. National district heating network integration allows operators to monetize waste heat output as revenue streams. Stockholm facilities serve as thermal anchors for municipal energy systems while delivering compute capacity to continental European enterprises.
Europe Green Data Center Market Competitive Landscape
Global majors compete with regional champions across interconnection density and renewable verification standards. The market structures around three tiers: hyperscale operators with captive renewable portfolios, colocation specialists with multi-tenant sustainability certifications, and infrastructure technology vendors with integrated power-cooling architectures. Strategic moves concentrate on sleeved power purchase agreement negotiations and modular prefabrication partnerships that compress construction timelines.
Among infrastructure technology specialists, Schneider Electric exemplifies integrated power and cooling system leadership. Within the colocation tier, Equinix, Inc. and NTT Global Data Centers EMEA GmbH occupy positions defined by metropolitan density across Frankfurt, London, Amsterdam, and Paris corridors. These operators represent divergent geographic strategies: one anchors interconnection platforms across thirteen European metros, while the other concentrates capacity within specific high-demand corridors.
| Leading Market Players |
|---|
| Equinix, Inc. |
| Digital Realty |
| Green Mountain AS |
| Schneider Electric |
| NTT Global Data Centers EMEA GmbH |
| OVH Groupe SAS |
| Interxion Holding N.V. |
| Colt Data Centre Services |
| Vertiv Holdings Co. |
| Others |
Supply & Pricing Matrix
Sleeved power purchase agreement mandates from large European banks and cloud providers are forcing facility operators to bypass traditional utility intermediaries, compressing supplier margins and restructuring procurement costs around direct grid connection premiums.
Pricing Analysis
Steel and concrete input costs pass through directly to facility construction quotes under new embodied carbon disclosure requirements from EMA and French regulators. Pricing stratifies across Tier III+ certified premium facilities, standard renewable-verified builds, and economy-tier legacy retrofits lacking CSRD-aligned certification. Cost compression in the economy tier intensifies as stranded air-cooled assets face obsolescence risk from liquid-cooling mandates. Cloud providers exhibit lowest price sensitivity due to captive renewable financing access; IT services firms face highest sensitivity from unpredictable workload scaling.
Supply Chain Analysis
Regional distribution centers for liquid-cooling infrastructure concentrate in Germany and the Netherlands, with hub-and-spoke patterns radiating to Irish and Nordic deployment sites. Manufacturing draws from Taiwanese semiconductor foundries for direct-to-chip cold plates, German precision engineering for power distribution units, and Chinese steel fabrication for modular container frames. Single-source vulnerability concentrates in specialized refrigerant microchannel production. Distribution runs through colocation operator procurement consortiums that aggregate demand across Frankfurt, Amsterdam, and London corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on modular prefabrication compressing construction timelines from 24 months to 12 months, enabling faster capital turnover and premium pricing for rapid-deploy capacity.
For Market Incumbents: Anchor renewable verification leadership through third-party PUE auditing investments that satisfy CSRD disclosure deadlines ahead of competitors. Consolidate supplier relationships around integrated fluid-and-hardware vendors capable of warranting complete liquid-cooling system performance. Threat substitution from two-phase immersion cooling vendors demands defensive patent positioning in dielectric fluid thermal management. For New Entrants and Emerging Players: Launch via district heating network partnerships in Nordic markets where waste heat monetization transforms energy cost centers into revenue streams. Target Swedish and Finnish urban edge zones with municipal thermal anchor contracts as the most penetrable geography. Go-to-market angle: factory-built modular units enabling 12-month deployment timelines versus 24-month traditional construction. For Investors and Strategic Acquirers: Asymmetric upside sits with colocation specialists holding verified renewable supply chains and sub-1.2 PUE certifications in Frankfurt-Rhine-Main and Amsterdam corridors. Long-term viability over the next decade hinges on sleeved power purchase agreement portfolios securing direct grid connection to specific wind and hydro assets. Signal to watch: grid interconnection queue clearance rates in Ireland and northern Germany as inflection indicator for stranded capital risk.| Strategic Initiative | Industry Significance |
|---|---|
| Sleeved Power Purchase Agreement | Direct grid connection to specific renewable assets satisfies EU Green Deal mandates and unlocks green financing eligibility. |
| Modular Prefabrication Partnership | Factory-built power and cooling modules compress European construction timelines from 24 months to 12 months. |
| District Heating Network Integration | Nordic operators monetize waste heat output through municipal thermal anchor contracts in Stockholm and Helsinki. |
| Liquid-Cooling Infrastructure Certification | Third-party PUE verification below 1.2 satisfies CSRD disclosure pressure from banking and insurance colocation clients. |
| Embodied Carbon Disclosure Compliance | Lifecycle steel and concrete accounting satisfies EMA and French permitting requirements ahead of minimum EU deadlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility operators, renewable energy procurement officers, EPC contractors, and colocation tenancy managers with secondary validation from EU Green Deal regulatory filings, EMA permitting databases, national building efficiency code transpositions, and hyperscaler capital expenditure disclosures. Bottom-up facility deployment counts triangulated against top-down renewable power contract volumes across German, Dutch, and Irish grid zones.
Segment-weighting across infrastructure type, cooling technology, power source verification standard, and end-user tenancy model shaped analytical framework construction over the projection horizon. CAGRs derived from capacity deployment trajectories, renewable interconnection queue clearance rates, and PUE improvement curves modeled through the forecast period. Industry-specific inputs included liquid-cooling adoption rates in AI training clusters and CSRD compliance timeline acceleration across French and German national transpositions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under grid interconnection queue extension scenarios and skilled technician wage inflation in liquid-cooling installation trades. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Retail Colocation Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
Virtual Infrastructure Manager Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Norway Data Center Power Market