
 Global Terminal Management System Market | 2026-2036
Global Terminal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Terminal Management System Market Outlook
Aftermarket service revenue is narrowing as a distinct margin pool, with software subscription and remote diagnostics bundling into core platform contracts. ABB Ltd. leverages its electrification portfolio to anchor integrated terminal automation offerings across European and Middle Eastern ports. Emerson Electric Co. sustains differentiation through its DeltaV distributed control systems tailored for liquid bulk terminal operations. Honeywell International Inc. competes on the strength of its Experion platform, which dominates safety instrumented system integrations at North American refineries and storage terminals.
A terminal management system orchestrates the real-time monitoring, control, and optimization of bulk liquid and container terminal operations through supervisory control and data acquisition (SCADA) architectures, tank gauging networks, and automated gate systems managing vessel-to-truck throughput. The primary industrial purpose centers on inventory reconciliation, berth scheduling, and regulatory emissions tracking across oil, chemical, and LNG storage facilities. Cloud-based deployment leads in new installations among logistics providers seeking elastic compute for peak cargo seasons, while edge computing configurations are gaining fastest among oil and gas firms requiring sub-50 millisecond response times for emergency shutdown systems. AI Integration sits at the core of margin expansion, with predictive maintenance modules commanding premium pricing over baseline IoT Connectivity offerings.
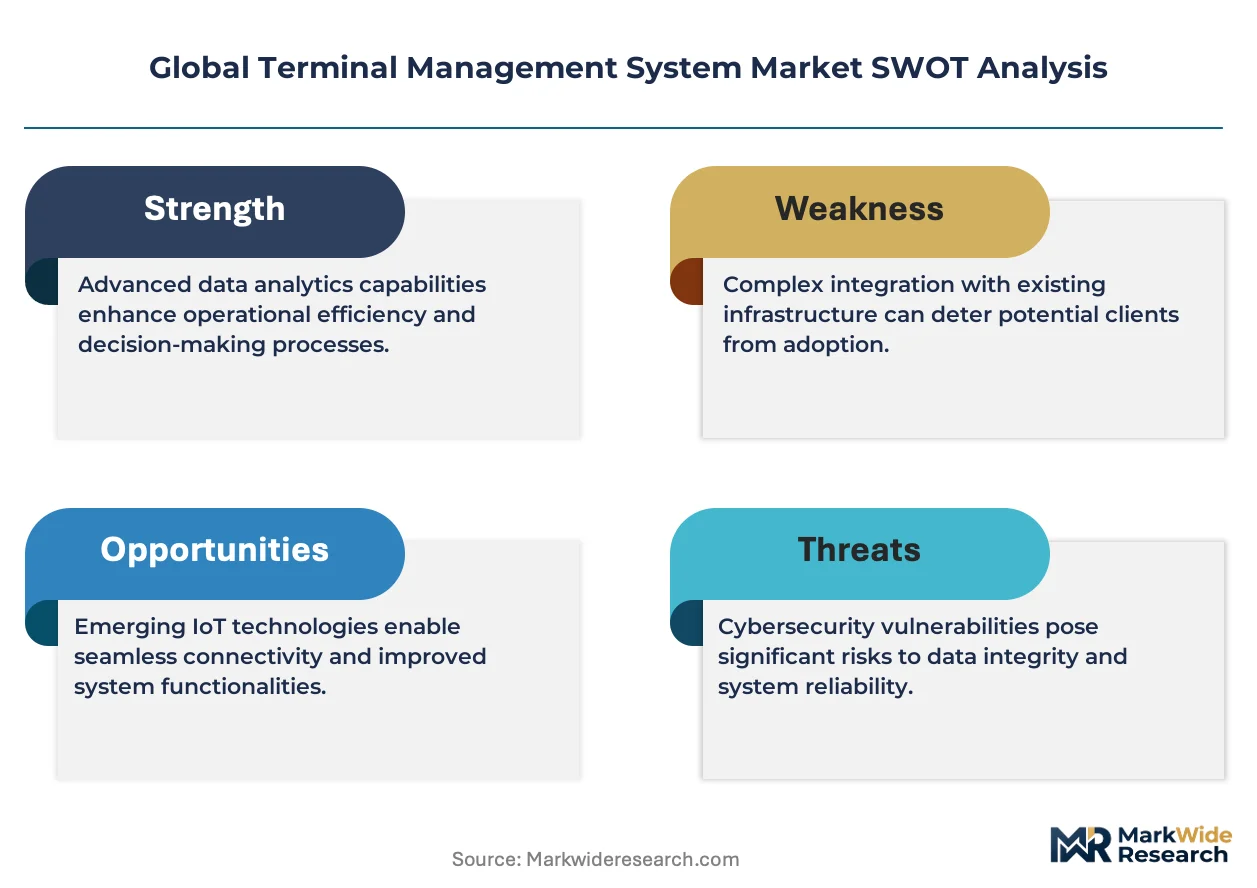
The EPA enforces Clean Air Act standards that mandate vapor recovery and leak detection systems at US petroleum terminals, directly shaping sensor and control hardware procurement specifications. ECHA's REACH framework and the EU F-Gas Regulation impose chemical handling transparency and refrigerant containment protocols that European terminal operators must embed into management system workflows. Stakeholders should monitor how IEC 62443 cybersecurity standards for industrial automation networks reshape vendor certification requirements and procurement gatekeeping across critical infrastructure bids.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for terminal management systems, forcing legacy SCADA vendors to reprice perpetual licenses against subscription-based competitors offering elastic compute for seasonal cargo peaks.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant containment mandates at European LNG terminals are accelerating sensor network upgrades and automated leak detection procurement.
- LNG export terminal expansions:United States Gulf Coast facilities are driving demand for integrated berth scheduling and vapor recovery control systems.
- Predictive maintenance modules:AI-driven anomaly detection is commanding premium pricing over baseline IoT connectivity in oil and gas storage operations.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fab capacity constraints are extending lead times for industrial control hardware.
- IEC 62443 certification costs:Cybersecurity compliance for critical infrastructure bids is adding eighteen-month qualification periods for new vendors.
- Edge computing capex intensity:Sub-50 millisecond emergency shutdown systems require redundant on-premise server deployments that cloud-native alternatives cannot satisfy.
Strategic Opportunities
- India port modernization:Sagarmala infrastructure investments are creating first-mover advantages for automation vendors at minor ports lacking legacy system baggage.
- Carbon accounting integration:EU Green Deal emissions reporting requirements are opening workflow modules that bundle terminal operations with Scope 1-3 tracking.
- Digital twin convergence:Real-time tank gauging fused with simulation software is enabling virtual commissioning that reduces physical testing downtime.
Industry Challenges
- OT-IT integration complexity:Converging operational technology networks with enterprise IT systems is exposing skills gaps in industrial cybersecurity architecture.
- Legacy protocol fragmentation:Proprietary fieldbus standards from 1990s tank farm installations are resisting standardization into OPC UA unified architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Terminal Management System Market |
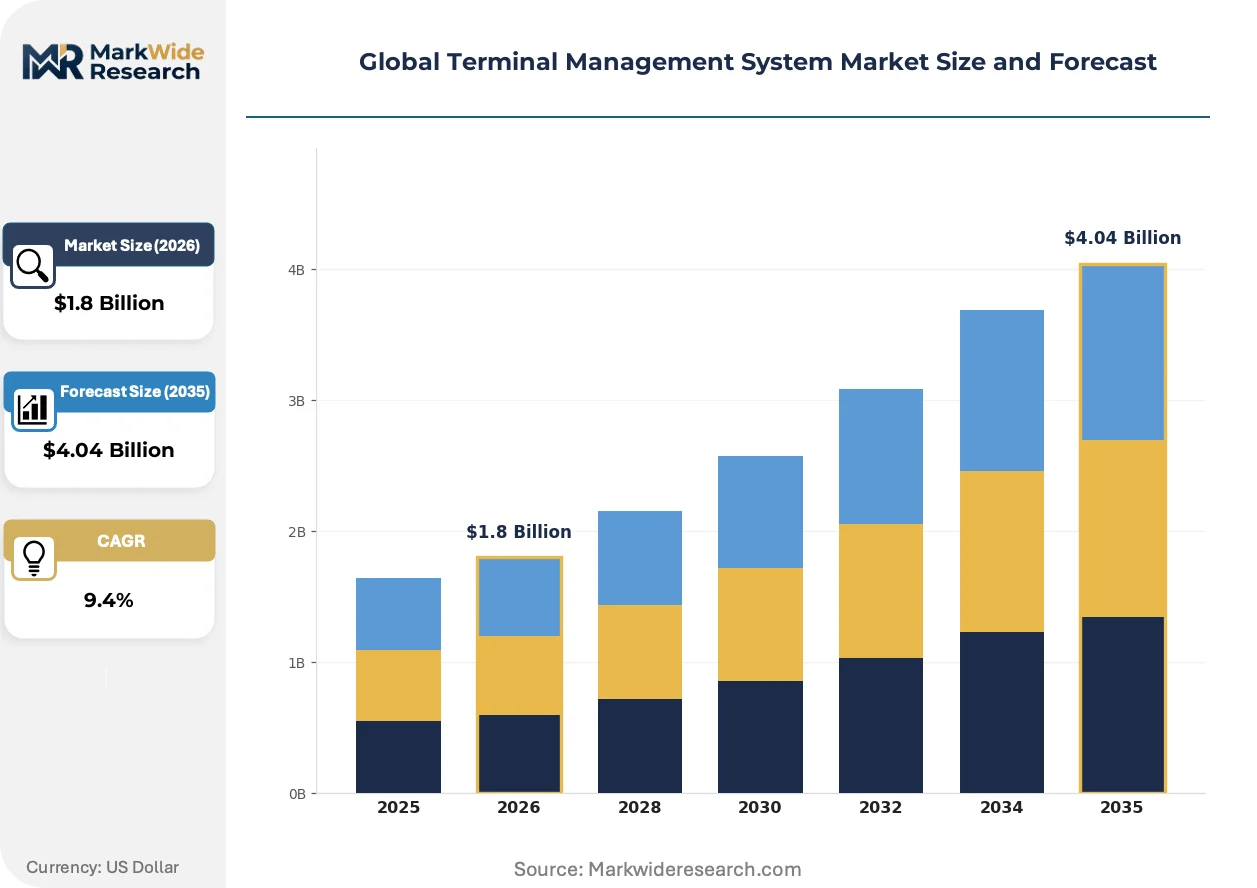
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Mobile End User: Logistics Providers, Shipping Companies, Oil & Gas Firms, Port Authorities Deployment: Public Cloud, Private Cloud, Multi-cloud, Edge Computing Technology: AI Integration, IoT Connectivity, Blockchain Solutions, Data Analytics |
| Companies Covered | ABB Ltd., Emerson Electric Co., Siemens AG, Yokogawa Electric Corporation, Rockwell Automation Inc., Schneider Electric SE, DP World Limited, Endress+Hauser Group Services AG, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Terminal Management System Market Strategic Shifts
Terminal automation is pivoting from hardware-centric control toward software-defined orchestration, with AI inference at the edge and API-first integration layers displacing monolithic SCADA deployments.
Digital twin technology is digitizing physical tank farm operations through real-time sensor fusion and physics-based simulation. Major oil and gas operators in the United States and Middle East are deploying these systems for virtual leak testing and emergency response training. The technology is digitizing capital planning cycles by reducing commissioning time and enabling scenario modeling without production disruption.
EPA Clean Air Act enforcement is tightening vapor recovery and leak detection specifications at petroleum terminals nationwide. The regulation is mandating continuous monitoring hardware upgrades and automated reporting workflows that integrate directly with terminal management system databases. Storage operators in California and Texas are responding by procuring sensor-software bundles that satisfy both operational and compliance requirements in single-vendor contracts.
Aftermarket service unbundling is compressing as software subscription and remote diagnostics merge into core platform contracts. Logistics providers are demanding outcome-based pricing that ties vendor fees to uptime guarantees rather than maintenance hours. This shift is most visible among European chemical terminals where total cost of ownership calculations now dominate procurement scorecards over upfront license fees.
Global Terminal Management System Market Segmentation
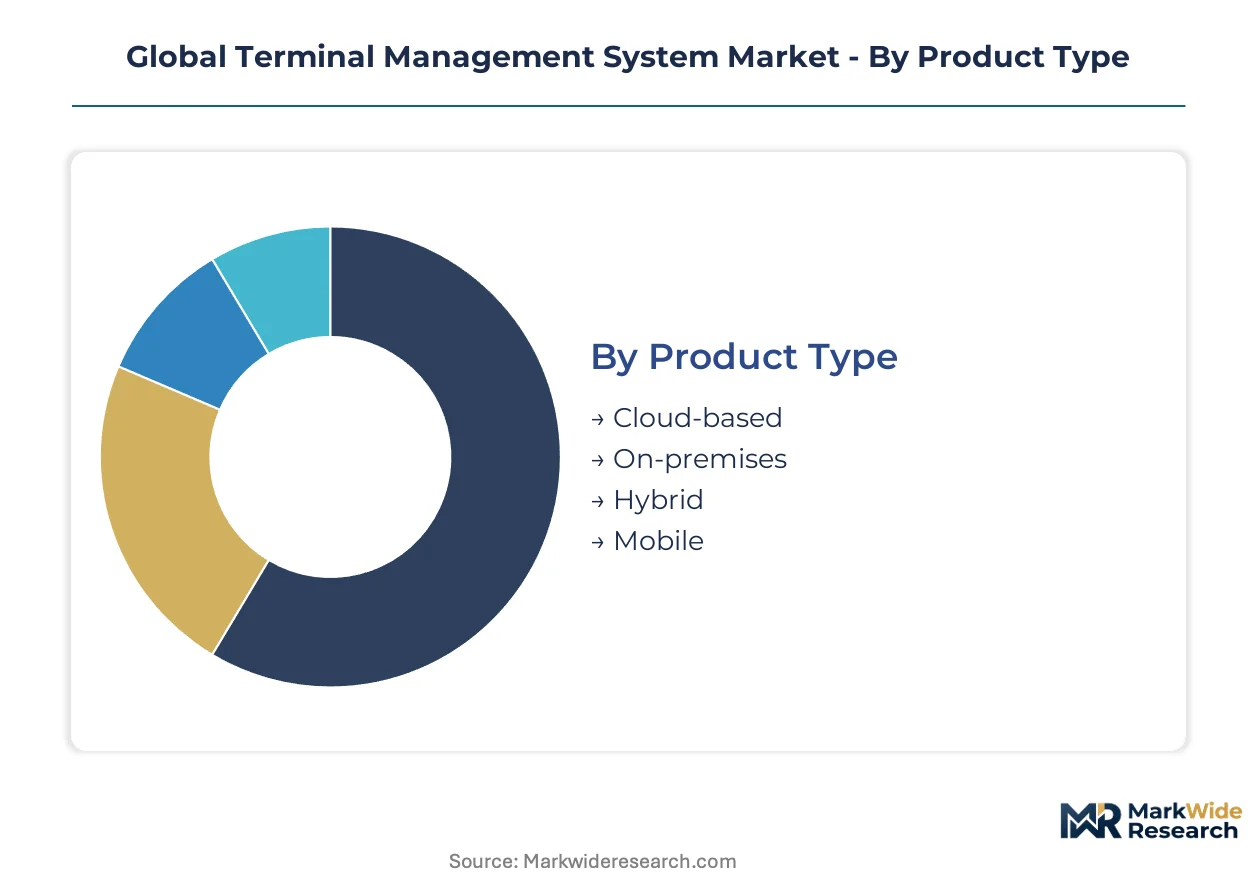
Terminal management system procurement patterns diverge sharply across deployment architectures and operational maturity levels. Understanding these segment boundaries clarifies why cloud-native vendors capture logistics contracts while edge-heavy configurations dominate safety-critical oil and gas installations.
Product Type:
Mature perpetual-license installations coexist with emerging subscription platforms across terminal portfolios worldwide.
- Cloud-based:Elastic compute architectures enable seasonal capacity scaling without capital-intensive server procurement. Logistics providers at Rotterdam and Singapore hubs favor this model for peak cargo handling flexibility.
- On-premises:Dedicated server installations maintain air-gapped security for critical infrastructure compliance. Oil and gas terminals along the US Gulf Coast specify these deployments for sub-50 millisecond emergency shutdown response requirements.
- Hybrid:Split workloads balance sensitive control functions on local infrastructure with analytics in hosted environments.
- Mobile:Tablet and smartphone interfaces extend supervisory visibility to field operators during tank inspections and truck loading operations.
Cloud-based systems handle the majority of new contract value; mobile is expanding most quickly on feature penetration.
End User:
Customer procurement sophistication spans from commodity logistics tenders to vertically integrated operator specifications.
- Oil & Gas Firms:Integrated majors demand unified platforms merging terminal automation with enterprise resource planning and regulatory emissions databases. These operators specify predictive maintenance modules and digital twin compatibility in procurement criteria.
- Logistics Providers:Third-party terminal operators prioritize API-first architectures enabling rapid customer onboarding and multi-tenant data segregation. Elastic pricing models align vendor costs with cargo volume volatility.
- Shipping Companies:Container line investments concentrate on berth scheduling optimization and automated gate systems reducing vessel turnaround times.
- Port Authorities:Public infrastructure mandates emphasize interoperability standards and cybersecurity certification compliance over feature depth.
Oil and gas firms command the deepest per-site spending; logistics providers are climbing the fastest on contract volume.
Deployment:
Infrastructure location choices reflect latency tolerance, data sovereignty requirements, and capital availability tradeoffs.
- Edge Computing:Distributed processing nodes at tank farm sites execute AI inference for leak detection without cloud round-trip delays. LNG export terminals in Texas and Louisiana deploy redundant edge clusters for safety instrumented system independence.
- Private Cloud:Single-tenant hosted environments satisfy European chemical operators under GDPR data residency constraints and IEC 62443 network segmentation requirements.
- Public Cloud:Shared infrastructure delivers lowest unit compute costs for analytics workloads without real-time control dependencies.
- Multi-cloud:Redundant provider configurations mitigate vendor lock-in risks for critical national infrastructure operators.
Edge computing anchors safety-critical throughput; private cloud is gaining share fastest among European regulatory-sensitive installations.
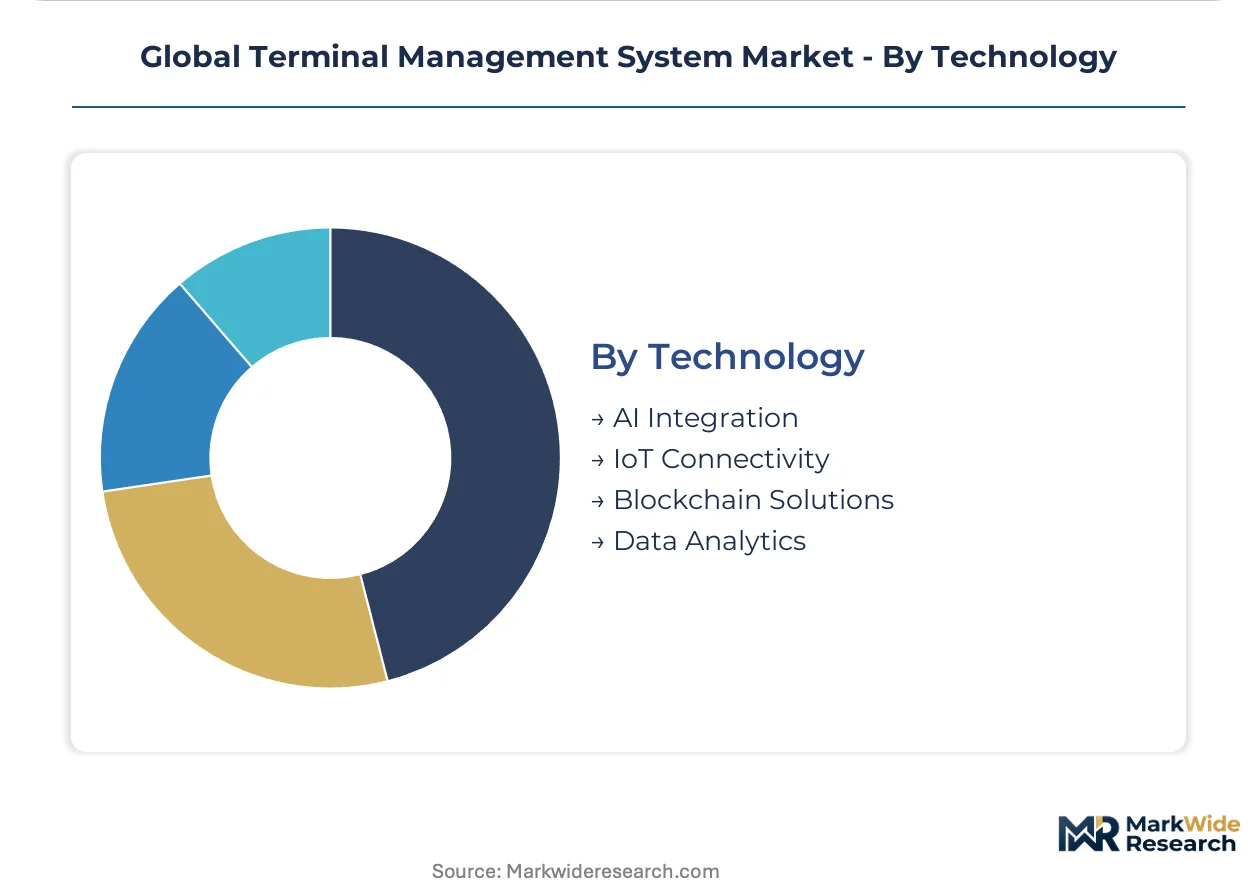
Technology:
Functional module adoption curves separate baseline connectivity investments from premium analytics capabilities.
- AI Integration:Machine learning models for predictive maintenance and anomaly detection command pricing premiums over standard monitoring dashboards. These modules require structured historical data and skilled calibration to avoid false alarm fatigue.
- IoT Connectivity:Sensor network foundations including tank gauging, flow meters, and environmental monitors constitute the baseline installation layer. Deployment concentrates at brownfield terminals retrofitting analog instrumentation.
- Data Analytics:Business intelligence layers transform operational data into berth utilization and inventory turnover metrics for commercial decision support.
- Blockchain Solutions:Distributed ledger pilots address custody transfer documentation and emissions certificate trading, though production deployment remains limited.
IoT Connectivity carries the widest installed base; AI Integration shows the steepest expansion trajectory on new contract pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the least price sensitivity as LNG export terminal expansions drive premium system specifications, while logistics operators in India negotiate aggressively on total cost of ownership during port modernization tenders. European chemical terminals occupy a middle tier where regulatory compliance costs override upfront license considerations.
United States
Gulf Coast LNG export facilities and petroleum storage terminals along the Houston Ship Channel are driving integrated berth scheduling and vapor recovery control system procurement. The EPA enforces Clean Air Act standards that mandate continuous leak detection hardware upgrades and automated emissions reporting workflows. Texas and Louisiana terminal operators are consolidating sensor-software bundles under single-vendor contracts to satisfy both operational and compliance requirements simultaneously.
Germany
Integrated chemical majors operating along the Rhine corridor demand unified platforms merging terminal automation with enterprise resource planning and regulatory emissions databases. ECHA's REACH framework and the EU F-Gas Regulation impose chemical handling transparency and refrigerant containment protocols that operators must embed into management system workflows. The Port of Rotterdam's influence extends to German chemical terminals adopting API-first architectures for rapid customer onboarding and multi-tenant data segregation.
India
Sagarmala infrastructure investments are creating first-mover advantages for automation vendors at minor ports lacking legacy system baggage. The country's national port regulator mandates interoperability standards and cybersecurity certification compliance that emphasize outcome-based pricing tied to uptime guarantees. Gujarat and Maharashtra port authorities are procuring cloud-native architectures with elastic compute for seasonal cargo peaks rather than capital-intensive on-premise deployments.
United Arab Emirates
Jebel Ali and Khalifa Port expansions are driving demand for AI-driven predictive maintenance modules and digital twin compatibility in procurement criteria. The country's national cybersecurity authority enforces critical infrastructure protection standards that extend vendor qualification periods for industrial control hardware. Abu Dhabi National Oil Company terminals are specifying edge computing configurations with sub-50 millisecond response times for emergency shutdown system independence.
Singapore
Third-party logistics operators at the Tuas mega-port prioritize elastic pricing models that align vendor costs with cargo volume volatility. The Maritime and Port Authority mandates emissions monitoring integration that bundles terminal operations with Scope 1-3 carbon accounting workflows. PSA International terminals are deploying hybrid architectures that balance sensitive control functions on local infrastructure with analytics in hosted environments.
Global Terminal Management System Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where specialized automation vendors compete against diversified industrial conglomerates. The vendor base segments into three strategic archetypes: electrification-anchored integrators, distributed control system specialists, and safety instrumented system platform providers. Dominant competitive moves include portfolio diversification through software subscription bundling and geographic expansion via port modernization partnerships in emerging markets.
Within the diversified industrial tier, ABB Ltd. and Siemens AG exemplify electrification-anchored integrators leveraging broad automation portfolios across European and Middle Eastern port installations. Emerson Electric Co. occupies a specialist position emphasizing distributed control architectures for liquid bulk terminal operations. Honeywell International Inc. anchors the safety-critical segment through platform dominance at North American refineries and storage terminals requiring instrumented system integrations.
| Leading Market Players |
|---|
| ABB Ltd. |
| Emerson Electric Co. |
| Siemens AG |
| Yokogawa Electric Corporation |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| DP World Limited |
| Endress+Hauser Group Services AG |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Taiwan fab undercapacity extending lead times for industrial control hardware is compressing vendor margins while simultaneously hardening pricing power among semiconductor-anchored suppliers serving safety-critical terminal automation deployments.
Pricing Analysis
Aftermarket service contracts bundling remote diagnostics and predictive maintenance modules now drive lifetime value capture exceeding initial platform licenses. Three-tier pricing structure across premium AI-integrated, standard IoT-connected, and economy sensor-only levels stratifies by certification grade and customization depth. Cost compression in cloud-native subscription tiers is intensifying because logistics providers demand outcome-based uptime guarantees. Logistics providers at Rotterdam and Singapore demonstrate highest price sensitivity; Gulf Coast LNG terminals show least sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Contract manufacturing for industrial control hardware concentrates among Taiwan Semiconductor Manufacturing and Samsung Foundry capacity allocations. Taiwan, South Korea, and Germany anchor geographic supply concentration for sensor networks and distributed control systems. Raw material dependencies include silicon wafers, rare earth magnets for actuators, and specialized industrial-grade enclosures. Single-source vulnerability around Taiwan fab capacity presents structural risk. Distribution runs through authorized system integrators and direct OEM relationships with terminal operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native software vendors displacing monolithic SCADA architectures with API-first platforms, requiring defensive positioning around safety-critical certification moats.
For Market Incumbents: Pre-empt cloud-native displacement by embedding predictive maintenance modules into core platform contracts before logistics providers complete vendor consolidation. Anchor defensive positioning through IEC 62443 certification investments that extend eighteen-month qualification barriers against unproven entrants. Prioritize backward integration into edge computing hardware to capture margin pools escaping to semiconductor suppliers.
For New Entrants and Emerging Players: India's Sagarmala minor ports lacking legacy system baggage offer the most penetrable geographic entry point for cloud-native automation vendors. Target outcome-based pricing contracts at Gujarat and Maharashtra port authorities seeking elastic compute without capital-intensive server procurement. Pursue API-first integration partnerships with third-party logistics operators at Singapore's Tuas mega-port to establish reference architectures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrification-anchored integrators bundling software subscriptions with hardware maintenance contracts. Long-term viability over the coming decade favors vendors with demonstrated safety instrumented system integrations at North American refineries. Monitor IEC 62443 certification completion rates as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable rapid customer onboarding at Rotterdam and Singapore logistics hubs. |
| Geographic Expansion | Port modernization partnerships in India leverage Sagarmala infrastructure investments without legacy displacement costs. |
| Acquisition of Specialist Firm | Predictive maintenance module specialists command premium pricing over baseline IoT connectivity offerings. |
| Strategic Partnership | Sensor-software bundles with EPA compliance integration satisfy Texas and Louisiana terminal procurement requirements. |
| Product Launch | Digital twin compatibility addresses ADNOC specifications for virtual commissioning and emergency response training. |
Study Parameters
A spread of perspectives from terminal operations managers, industrial cybersecurity architects, procurement leads at oil majors, and automation system integrators converged on the working assumptions underlying demand projections. Primary interviews combined with secondary validation against EIA terminal construction databases, EPA enforcement records, EU F-Gas Regulation implementation reports, and SEC filings from listed automation vendors. Bottom-up project pipeline analysis triangulated against top-down market sizing across deployment architecture segments.
Demand-supply balance modeling anchored projections across the analysis window through capacity utilization tracking at Taiwan and South Korea fab facilities. Segmentation dimensions included deployment model, end-user vertical, technology module tier, and regional regulatory cluster. CAGRs derived from historical contract value trajectories and announced terminal automation procurement timelines. Industry-specific forecast inputs incorporated LNG export terminal expansion announcements along the US Gulf Coast and EU Green Deal emissions reporting implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform investments by diversified industrial conglomerates would shift outcomes beyond modeled parameters. Quarterly review of IEC 62443 certification completion rates and Taiwan fab capacity allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Hyperscale Data Center Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Norway Data Center Construction Market