
 Hybrid Cloud Computing Market | 2026-2036
Hybrid Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Cloud Computing Market Outlook
Container orchestration across heterogeneous infrastructure is fragmenting traditional monolithic cloud procurement into modular, workload-specific decisions. Amazon Web Services leverages its Graviton processor ecosystem to anchor compute-intensive hybrid workloads inside customer data centers. Microsoft Azure competes through Azure Arc, which extends consistent management APIs across on-premises servers and rival cloud platforms. VMware specializes in virtualization layers that bridge legacy enterprise systems with Kubernetes-native cloud environments.
Hybrid cloud computing denotes an IT architecture integrating private cloud, public cloud, and on-premises infrastructure through unified orchestration platforms, typically employing Kubernetes for container scheduling, software-defined networking for traffic management, and API gateways for service mesh connectivity. Its primary purpose enables organizations to place workloads according to latency, compliance, and cost constraints without sacrificing operational consistency. Infrastructure-as-a-Service dominates value capture because enterprises retain capital control over bare-metal resources while consuming elastic public capacity. Disaster-Recovery-as-a-Service represents the fastest-expanding service type as regulated industries mandate geographically separated failover systems with sub-hour recovery objectives. Large enterprises occupy the deepest margin pools due to complex multi-vendor integration requirements and dedicated professional services engagements.
The EU AI Act and GDPR impose strict data residency and algorithmic transparency obligations that shape hybrid deployment patterns across European enterprises. In the United States, NIST cybersecurity frameworks and SEC disclosure rules for material cloud incidents drive demand for auditable private infrastructure components. Stakeholders must evaluate sovereign cloud certifications and cross-border data transfer mechanisms before committing to platform-specific edge extensions.
Market Dynamics
Container orchestration is fragmenting monolithic cloud procurement into workload-specific infrastructure decisions, forcing enterprises to reassemble operational consistency across disaggregated compute layers.
Growth Catalysts
- EU AI Act data residency mandates:European financial institutions must maintain algorithmic training data within sovereign boundaries, accelerating demand for localized private infrastructure tethered to hyperscale capacity.
- Industrial edge processing in Germany:Automotive and precision manufacturing clusters require sub-10 millisecond latency for quality control systems, driving deployment of factory-floor Kubernetes nodes synchronized with public cloud analytics.
- Disaster recovery automation:Healthcare and banking regulators now require geographically separated failover systems with sub-hour recovery objectives, expanding consumption of orchestrated multi-site replication services.
Market Restraints
- Specialized talent scarcity:Kubernetes platform engineering and software-defined networking expertise commands premium compensation, inflating operational costs for mid-market enterprises lacking dedicated cloud centers of excellence.
- Hyperscale concentration risk:Three vendors control the majority of Graviton-class ARM processor supply and proprietary management API ecosystems, creating vendor lock-in exposure for compute-intensive hybrid workloads.
- Cross-border data transfer friction:Schrems II rulings invalidate EU-US Privacy Shield mechanisms, complicating lawful international replication for multinational corporations operating transatlantic hybrid architectures.
Strategic Opportunities
- Sovereign cloud certification gaps in France and Spain:National cloud frameworks lag German and Dutch maturity, creating first-mover advantage for providers achieving ANSM and CNIL-compliant edge extensions.
- Convergence of confidential computing with Kubernetes:Hardware-based trusted execution environments enable encrypted-in-use processing for regulated workloads, opening new deployment patterns for healthcare and government segments.
- FinOps-driven procurement restructuring:Finance teams now mandate granular workload cost attribution, displacing blanket enterprise licensing with consumption-based contracts that reward multi-cloud arbitrage capabilities.
Industry Challenges
- Mainframe integration complexity:Fortune 500 enterprises struggle to containerize COBOL-dependent core banking and insurance systems without disrupting decades-old batch processing schedules.
- Multi-cloud security certification timelines:Achieving FedRAMP and ISO 27001 compliance across simultaneously operated AWS, Azure, and on-premises environments extends sales cycles by 8-14 months for government contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Cloud Computing Market |
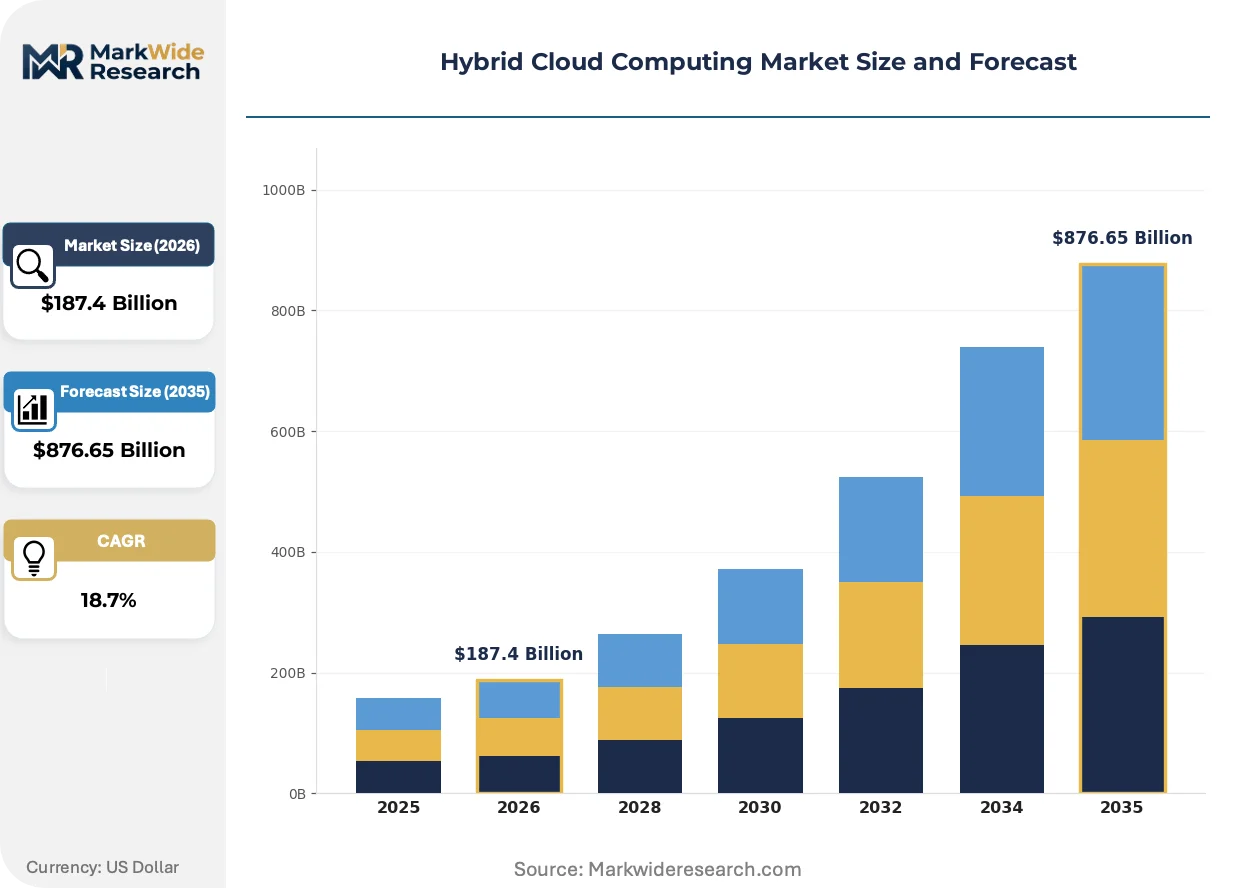
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $876.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, On-Premises, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DRaaS End User: SMEs, Large Enterprises, Government, Educational Institutions Integration Level: Fully Integrated, Partially Integrated, Standalone, Hybrid |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM, Hewlett Packard Enterprise, VMware, Cisco Systems, Dell Technologies, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Cloud Computing Market Strategic Shifts
Artificial intelligence inference workloads are redistributing compute gravity toward edge locations, compressing the traditional boundary between centralized training and distributed execution.
Kubernetes-native confidential computing is hybridizing security architectures for regulated industries. Hardware-based trusted execution environments from Intel TDX and AMD SEV-SNP enable encrypted-in-use processing for healthcare records and financial transactions. German automotive manufacturers and Dutch pharmaceutical distributors are piloting these configurations for GDPR-sensitive workloads. The technology is hybridizing compliance postures by allowing sensitive data processing at edge locations previously restricted to air-gapped private data centers.
The EU AI Act's risk-based classification system imposes algorithmic transparency obligations on high-risk automated decision systems. Financial services institutions deploying credit scoring and insurance underwriting models must maintain comprehensive documentation and human oversight mechanisms. German and French banking regulators are interpreting these requirements to mandate sovereign cloud infrastructure for model training data, redirecting procurement toward EU-certified providers.
Platform engineering teams are consolidating vendor relationships to reduce operational complexity. Mid-market enterprises previously operating three or more cloud environments are standardizing on single hyperscale platforms augmented by consistent management APIs. This concentration is most visible in Nordic manufacturing clusters, where IT headcount constraints favor simplified operational models over multi-cloud arbitrage strategies.
Hybrid Cloud Computing Market Segmentation
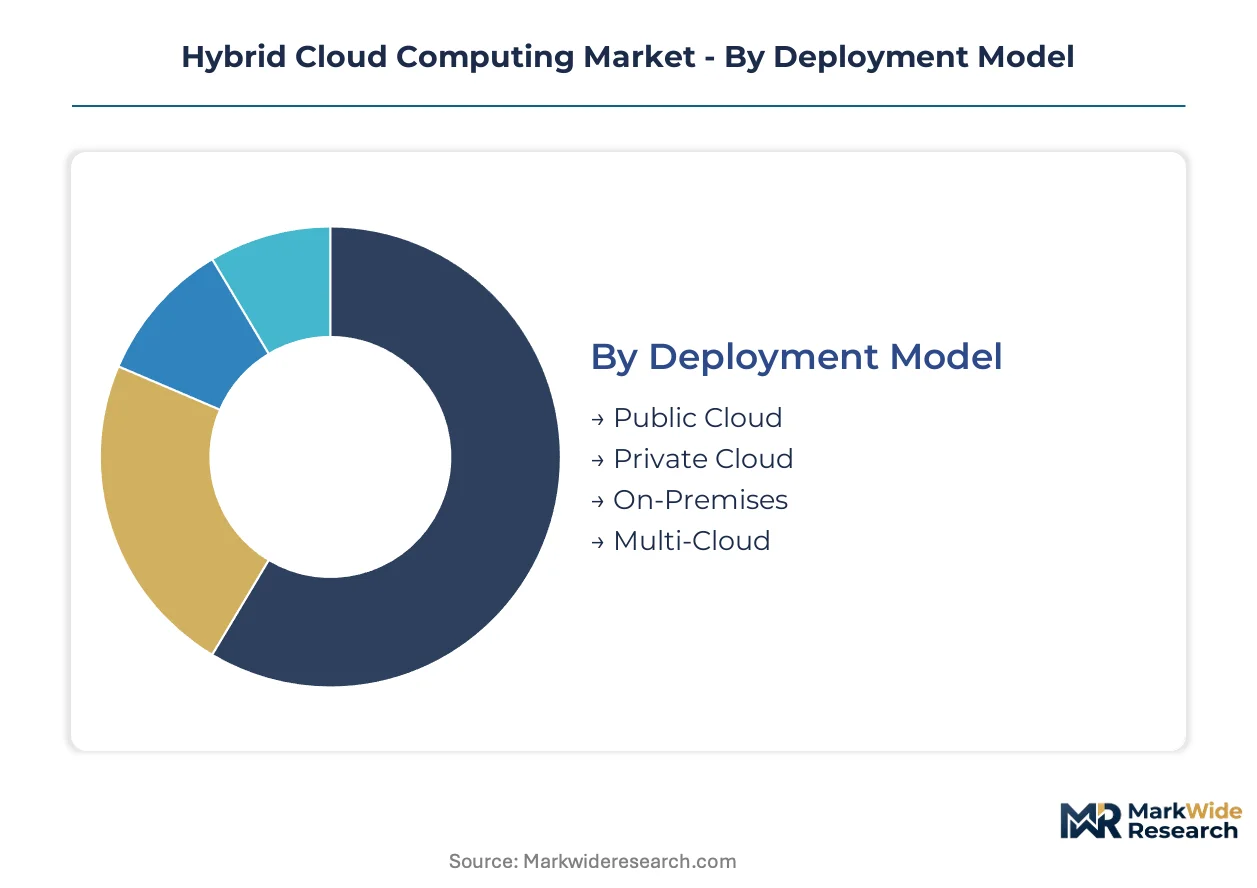
Workload placement decisions in hybrid environments fragment procurement across four distinct dimensions, each imposing different technical and commercial constraints on infrastructure buyers.
Deployment Model:
Refresh cycles vary dramatically across deployment architectures, with public cloud resources turning over in months while on-premises infrastructure persists for years.
- Public Cloud:Elastic compute and storage services consumed on-demand from hyperscale providers. German automotive manufacturers leverage public cloud for burst rendering and simulation workloads that exceed factory-floor edge capacity.
- Private Cloud:Dedicated infrastructure operated within organizational boundaries or through single-tenant hosted arrangements. EU financial institutions under GDPR and EU AI Act mandates concentrate procurement here for algorithmic training data residency.
- On-Premises:Traditional data center assets owned and operated directly by the enterprise. Legacy COBOL-dependent core banking systems in the United States and continental Europe remain anchored here due to containerization complexity.
- Multi-Cloud:Orchestrated distribution of workloads across two or more distinct cloud providers. Mid-market enterprises in Nordic manufacturing clusters are consolidating away from this model toward simplified single-platform architectures.
Private cloud dominates installed base among regulated industries. Public cloud is where expansion concentrates for compute-intensive analytics workloads.
Service Type:
Commercial terms harden fastest at the infrastructure layer while software licensing retains flexibility.
- IaaS:Bare-metal compute, storage, and networking resources delivered as metered services. Enterprises retain capital control over physical assets while consuming elastic capacity, capturing the deepest value pools in hybrid procurement.
- DRaaS:Orchestrated replication and failover services spanning geographically separated sites. Healthcare and banking regulators in the United States and European Union now mandate sub-hour recovery objectives, accelerating adoption.
- PaaS:Managed runtime environments abstracting underlying infrastructure complexity. Application development teams in French pharmaceutical distributors leverage PaaS for rapid deployment of GDPR-compliant analytics pipelines.
- SaaS:Fully managed applications accessed via subscription without infrastructure management. Procurement teams increasingly demand granular cost attribution, displacing blanket enterprise licensing.
IaaS commands the largest revenue share. DRaaS is climbing the fastest as compliance mandates tighten recovery requirements.
End User:
Contract complexity scales with organizational size, from standardized terms for smaller buyers to bespoke professional services engagements for the largest accounts.
- Large Enterprises:Complex multi-vendor integration requirements with dedicated cloud centers of excellence. Fortune 500 manufacturers in Germany and the United States drive demand for Kubernetes platform engineering expertise at premium compensation levels.
- Government:FedRAMP, ISO 27001, and sovereign cloud certification requirements extending sales cycles. Contractors face 8-14 month compliance timelines across simultaneously operated environments.
- SMEs:Constrained IT headcount favoring simplified operational models over multi-cloud arbitrage. Platform engineering teams in this segment are consolidating vendor relationships to reduce operational complexity.
- Educational Institutions:Research computing and student service delivery with fluctuating seasonal demand patterns. Budget constraints favor consumption-based contracts with multi-cloud arbitrage capabilities.
Large enterprises anchor professional services revenue. SMEs represent the steepest expansion trajectory for standardized management APIs.
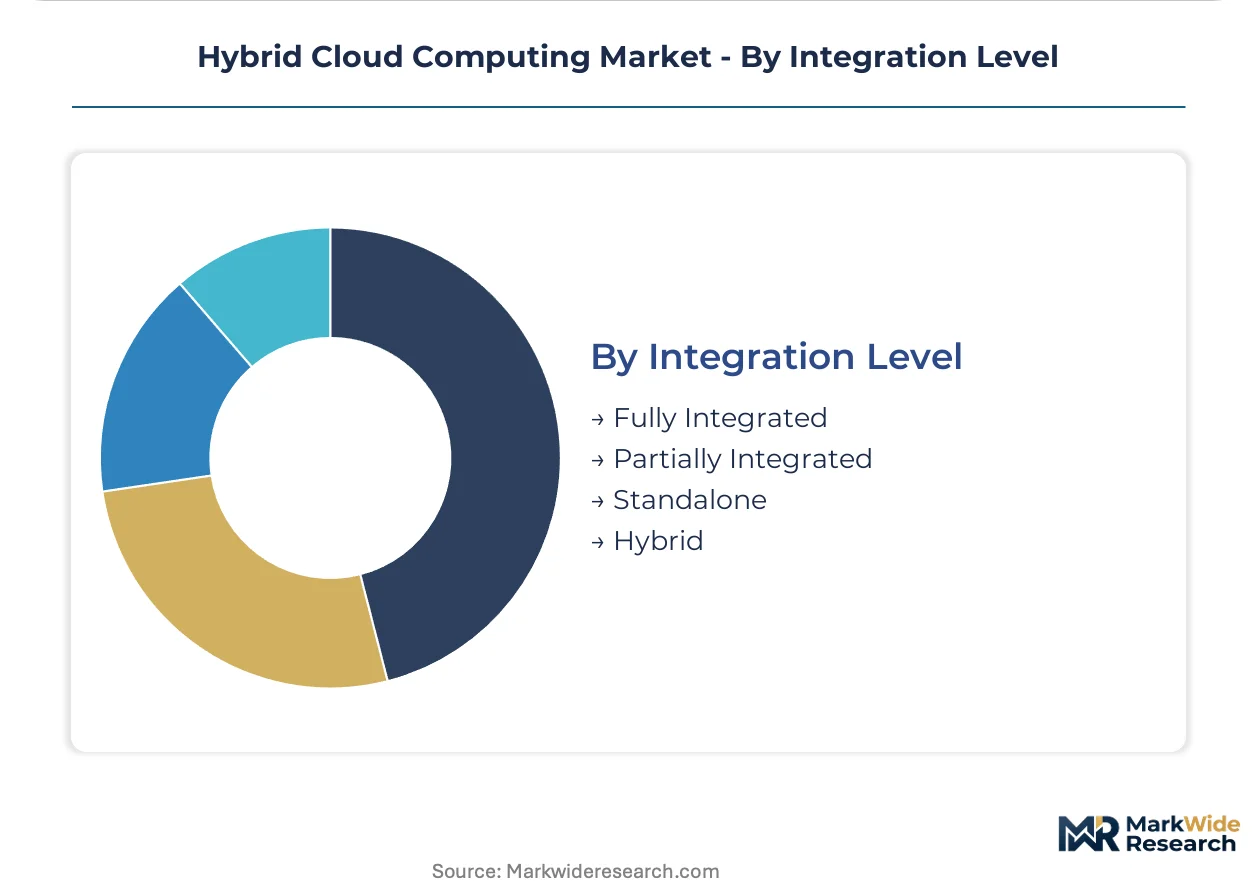
Integration Level:
Architectural maturity determines operational overhead, with fully integrated environments demanding upfront investment but reducing long-term management burden.
- Fully Integrated:Unified orchestration platforms spanning private, public, and edge infrastructure through consistent Kubernetes control planes. German precision manufacturers deploy these configurations for factory-floor quality control systems requiring sub-10 millisecond latency.
- Partially Integrated:Selective workload portability with manual intervention for cross-environment migration. Transatlantic corporations navigate Schrems II complexities through deliberate architectural boundaries between EU and US data zones.
- Hybrid:Deliberate separation of sensitive and general-purpose workloads across air-gapped and connected environments. Dutch pharmaceutical distributors pilot confidential computing configurations here for GDPR-sensitive processing.
- Standalone:Isolated infrastructure stacks without orchestrated connectivity to external resources. Legacy mainframe batch processing in insurance and banking sectors persists in this configuration.
Standalone systems retain substantial legacy footprint. Fully integrated architectures are gaining share fastest as container orchestration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports industrial automation expertise to automotive manufacturers across Eastern Europe and Asia, while the United States ships cloud infrastructure software to enterprises in Latin America and the Middle East.
United States
Financial services institutions and healthcare systems drive hybrid adoption to balance latency-sensitive workloads with regulatory audit trails. SEC disclosure rules for material cloud incidents and NIST cybersecurity frameworks mandate auditable private infrastructure components. Silicon Valley technology clusters and New York financial centers deploy Kubernetes-native edge nodes synchronized with hyperscale analytics.
Germany
Automotive and precision manufacturing clusters require sub-10 millisecond latency for quality control systems and predictive maintenance algorithms. The EU AI Act and GDPR impose strict data residency obligations for algorithmic training data used in automated decision systems. Bavarian industrial zones and Baden-Württemberg manufacturing corridors anchor factory-floor Kubernetes deployments tethered to public cloud resources.
France
Banking regulators interpret EU AI Act requirements to mandate sovereign cloud infrastructure for credit scoring and insurance underwriting model training. ANSM and CNIL certification frameworks lag German maturity, creating compliance complexity for pharmaceutical distributors. Paris financial centers and Lyon industrial clusters pilot confidential computing configurations for GDPR-sensitive healthcare analytics.
United Kingdom
Post-Brexit data transfer arrangements complicate transatlantic hybrid architectures for multinational corporations operating EU-UK-US infrastructure. The Information Commissioner's Office enforces UK GDPR alignment with evolving European standards. London financial services and Cambridge technology clusters navigate deliberate architectural boundaries between European and British data zones.
Netherlands
Rotterdam logistics hubs and Amsterdam data center clusters serve as continental interchange points for cross-border workload orchestration. Dutch pharmaceutical distributors pilot hardware-based trusted execution environments for encrypted-in-use processing of sensitive patient records. National cloud framework maturity exceeds French and Spanish levels, attracting EU-certified provider expansion.
Hybrid Cloud Computing Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement decisions. Hyperscale providers anchor compute-intensive workloads through proprietary processor ecosystems and consistent management APIs. Virtualization specialists bridge legacy enterprise systems with container-native environments. Infrastructure hardware vendors and systems integrators round out a tiered competitive structure. Dominant competitive moves include strategic partnerships for sovereign cloud certifications and portfolio diversification into confidential computing hardware.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by their management API ecosystems and edge extension capabilities. Amazon Web Services exemplifies the compute-anchoring archetype through Graviton-class ARM processor supply. Microsoft Azure represents the multi-platform orchestration approach with unified control planes spanning rival environments. Google Cloud sits within the data-analytics specialization vector for machine learning workload distribution.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM |
| Hewlett Packard Enterprise |
| VMware |
| Cisco Systems |
| Dell Technologies |
| Oracle |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Amsterdam freight corridors carry specialized server hardware and confidential computing modules from Taiwanese foundries to European data center clusters, with logistics cost volatility feeding directly into IaaS contract indexation clauses and downstream price stratification between sovereign-certified and standard-tier deployments.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked indexation dominate long-term IaaS agreements for bare-metal compute resources. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic data residency compliance. Cost compression in mid-market SaaS tiers is intensifying because hyperscale providers are absorbing Kubernetes platform engineering premiums to capture consolidation-driven accounts. SMEs exhibit highest price sensitivity due to constrained IT procurement budgets, while government contractors demonstrate lowest sensitivity given FedRAMP and sovereign cloud certification requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Wistron, and Quanta Computer for hyperscale server assembly and edge device production. Taiwan, China, and Vietnam anchor component fabrication for Graviton-class ARM processors and software-defined networking hardware. Supply chains draw from specialized silicon substrates, high-bandwidth memory modules, and precision cooling systems. Single-source vulnerability concentrates in EUV lithography equipment for advanced node production. Distribution runs through direct hyperscale procurement channels and tier-one systems integrators serving regulated enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid cloud infrastructure sits in early-cycle expansion as EU AI Act data residency mandates force algorithmic training workloads into sovereign-certified private environments, accelerating procurement beyond traditional cloud migration timelines.
For Market Incumbents: Harden sovereign cloud certification portfolios against emerging EU member state frameworks in France and Spain. Defensive consolidation of confidential computing hardware partnerships with Intel and AMD offsets margin pressure from Kubernetes talent scarcity. Channel control through professional services engagements with Fortune 500 manufacturers preserves pricing power against mid-market SaaS commoditization. For New Entrants and Emerging Players: Pursue sovereign cloud certification gaps in French pharmaceutical distribution and Spanish telecommunications verticals. White-space concentration sits in hardware-based trusted execution environments for GDPR-sensitive healthcare analytics. Go-to-market execution through Dutch cloud interchange partnerships accelerates EU market entry without direct hyperscale competition. For Investors and Strategic Acquirers: Kubernetes-native platform engineering boutiques with established German automotive manufacturing relationships represent priority acquisition archetypes. Long-term viability hinges on container orchestration expertise displacement of legacy virtualization specialists. Monitor confidential computing pilot conversion rates at Dutch pharmaceutical distributors as inflection signal for regulated workload deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | ANSM and CNIL compliance unlocks French pharmaceutical algorithmic training data residency contracts. |
| Confidential Computing Integration | Intel TDX and AMD SEV-SNP enablement captures GDPR-sensitive healthcare edge processing pilots. |
| Kubernetes Platform Engineering | Factory-floor container orchestration expertise commands premium compensation from German automotive manufacturers. |
| Multi-Cloud Management Consolidation | Azure Arc-style API unification displaces fragmented three-vendor operational models in Nordic manufacturing. |
| Disaster Recovery Automation | Sub-hour recovery objective compliance satisfies SEC and EU banking regulator mandates for geographically separated failover. |
Study Parameters
A spread of perspectives from cloud platform engineers, IT procurement officers at financial institutions, sovereign cloud compliance consultants, and Kubernetes DevOps specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through hyperscaler capex disclosures, EU regulatory filings, SEC 10-K infrastructure segments, and trade data for server hardware imports. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against service type revenue pools anchored value estimates.
Demand-supply-balance framing modeled workload placement decisions across private cloud, public cloud, on-premises, and multi-cloud architectures throughout the forecast period. Segmentation dimensions included service type, organization size tier, integration complexity level, and regional regulatory cluster. CAGRs derived from S-curve penetration modeling for confidential computing and sovereign cloud configurations, cross-referenced against EU AI Act implementation timelines and German industrial edge deployment velocity.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT capex cycles, ARM processor supply availability, or transatlantic data transfer legal frameworks would shift the trajectory. Forecasts incorporate documented assumptions regarding Kubernetes maturation curves and regulatory enforcement intensity. Quarterly review of sovereign cloud certification announcements, confidential computing pilot expansions, and hyperscale edge location buildouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
France Cloud Computing Market
Cloud Computing
India Cloud Computing Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
Web Service Cloud Market
Cloud Computing
Cloud Based Information Governance Market
Cloud Computing
Automotive Cloud Based System Market
Cloud Computing
Cloud Based Backup Services Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Cloudifier Market
Cloud Computing
Application Hosting Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Serverless Computing Market
Cloud Computing
Bare Metal Cloud Market