
 Brazil Data Center Server Market | 2026-2036
Brazil Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Server Market Insights
LGPD enforcement is recalibrating the cost-of-entry calculus for foreign server vendors seeking Brazilian contracts. Cisco Systems leverages its established channel partnerships to sustain dominance in enterprise networking-integrated server deployments. Dell Technologies anchors its position through direct-to-hyperscale relationships and localized assembly capabilities. NVIDIA Corporation differentiates via GPU-accelerated systems targeting AI training workloads at Brazilian financial institutions.
A data center server is a high-performance computing device engineered with multi-socket processors, ECC memory, and redundant power supplies, designed to process, store, and distribute data across networked environments for enterprise and cloud applications. Rack servers occupy the largest volume position due to standardized density requirements at facilities like Ascenty and Oi Datacenters, while blade server configurations command premium positioning in space-constrained metropolitan deployments. Edge computing represents the fastest-growing technology dimension as telecommunications providers deploy micro data centers for 5G latency reduction across state capitals.
ANATEL certification requirements govern telecommunications infrastructure equipment, while ANVISA regulates healthcare data handling systems, and the Brazilian Internet Steering Committee (CGI.br) shapes technical standards for national connectivity. These frameworks collectively mandate local data residency and hardware traceability, elevating compliance costs for non-domestic suppliers. Stakeholders must monitor evolving LGPD enforcement thresholds and federal incentives for domestic semiconductor assembly to anticipate procurement preference shifts.
Market Dynamics
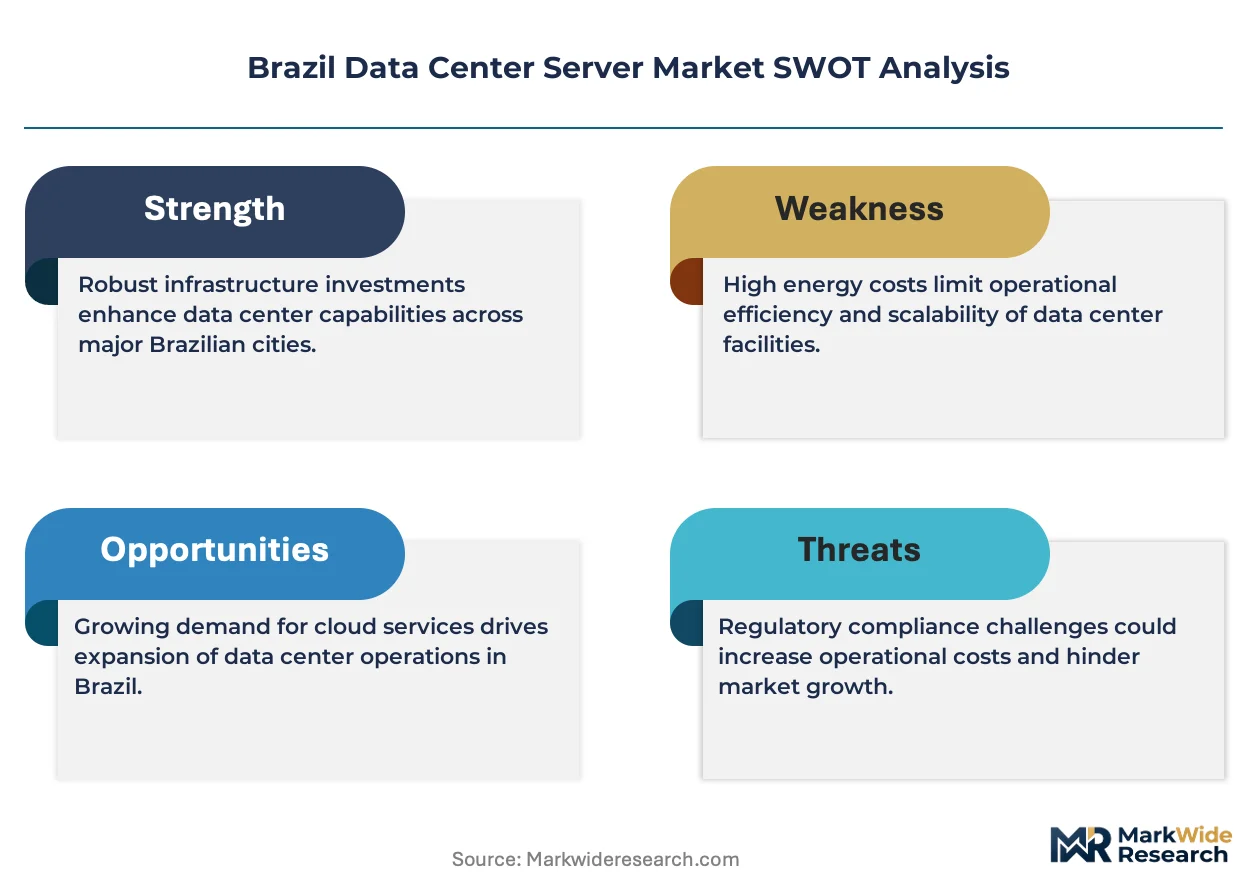
LGPD data sovereignty mandates are compressing procurement timelines for foreign server vendors while elevating domestic assembly requirements across São Paulo and Rio de Janeiro hyperscale corridors.
Growth Catalysts
- Cloud migration in financial services:Brazilian banking institutions are consolidating legacy infrastructure into unified platforms, driving rack server procurement at facilities like Ascenty.
- ANATEL telecommunications certification:5G network expansion mandates hardware traceability standards that favor localized server assembly and component sourcing.
- GPU-accelerated AI workloads:National AI strategy funding is channeling investment toward high-density computing clusters for training large language models.
Market Restraints
- Semiconductor import dependency:Brazil lacks domestic foundry capacity for advanced processors, exposing procurement to dollar-denominated volatility and extended lead times.
- LGPD compliance cost escalation:Data localization requirements impose redundant infrastructure duplication, inflating total cost of ownership for multi-national operators.
- Power grid instability in northern states:Unreliable electricity supply outside southeastern industrial corridors limits edge data center viability in Amazonas and Pará.
Strategic Opportunities
- Northeast corridor underpenetration:Recife and Salvador offer latent demand from offshore oil services and port logistics digitization with minimal incumbent hyperscale presence.
- Edge micro data centers:Telecommunications providers are deploying containerized facilities for 5G latency reduction across state capitals beyond São Paulo.
- Federal semiconductor assembly incentives:Proposed tax abatements for domestic component manufacturing could reshape supplier economics for foreign OEMs.
Industry Challenges
- Certification timeline compression:ANATEL and ANVISA parallel approval processes for healthcare-financial hybrid workloads extend deployment cycles by 8-14 months.
- Legacy mainframe integration:Core banking systems at established institutions resist virtualization, forcing hybrid architectures that complicate rack density optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Server Market |
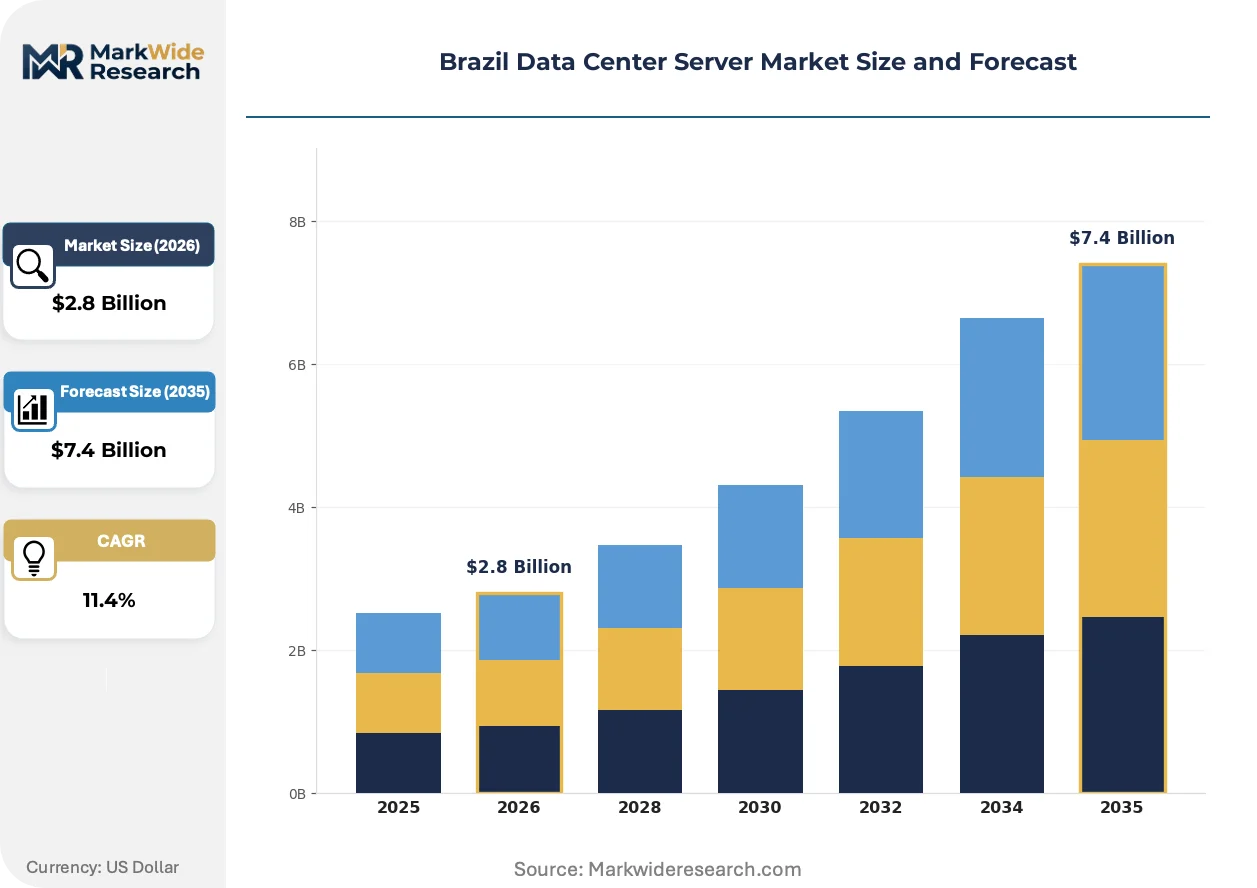
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Micro Servers Technology: Cloud Computing, Virtualization, Edge Computing, Artificial Intelligence End User: Telecommunications, Financial Services, Government, Healthcare Deployment Model: On-Premises, Colocation, Hybrid Cloud, Multi-Cloud |
| Companies Covered | Cisco Systems Inc., NVIDIA Corporation, Hewlett Packard Enterprise, Intel Corporation, Lenovo Group, Super Micro Computer Inc., IBM Corporation, Advanced Micro Devices (AMD), Dell Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Server Market Trends and Innovations
Server architecture is fragmenting into workload-optimized configurations as Brazilian operators prioritize density and thermal efficiency over generic compute scalability.
Immersion cooling systems are modularizing deployment patterns for high-performance GPU clusters. Financial institutions in São Paulo are piloting dielectric fluid-based thermal management for AI training racks. This approach is modularizing facility design by eliminating raised-floor requirements and compressing power usage effectiveness ratios.
ANVISA healthcare data handling regulations are mandating air-gapped infrastructure for patient records. Hospital networks and health insurance operators must deploy physically isolated server environments with biometric access controls. Pharmaceutical logistics providers in Rio de Janeiro and Campinas are retrofitting existing facilities to satisfy these containment specifications.
Hyperscale buyers are consolidating vendor relationships around direct OEM contracts rather than distributor-mediated procurement. Large banking and telecommunications groups are negotiating frame agreements with manufacturers for multi-year server refresh cycles. This concentration is most pronounced among the three largest facility operators in the southeastern corridor, who now account for the majority of rack server volume.
Brazil Data Center Server Market Segmentation
Server procurement patterns in Brazil diverge sharply between standalone infrastructure investments and integrated platform deployments. Understanding these integration depths reveals why hyperscale operators and enterprise buyers source through entirely different channel structures despite purchasing identical hardware categories.
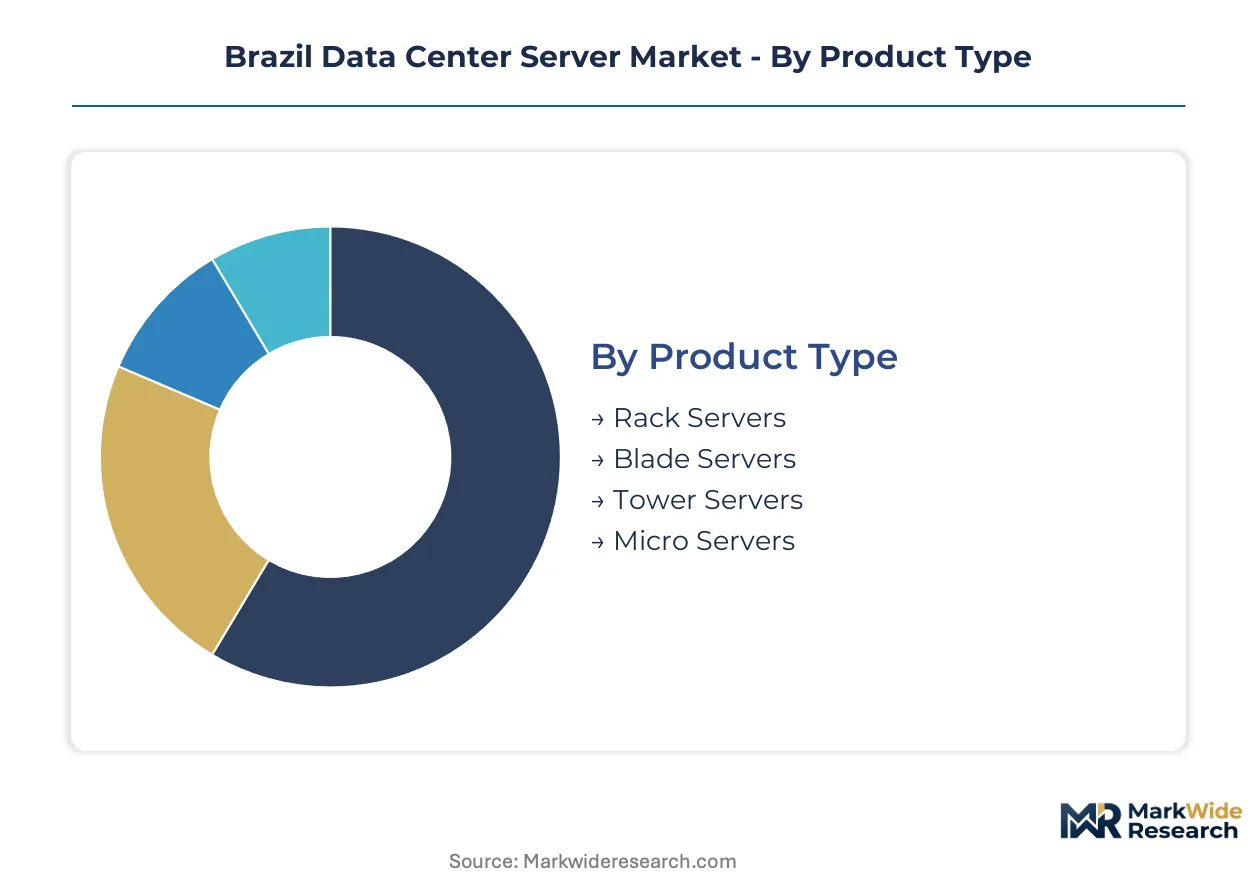
Product Type:
Rack configurations dominate standalone procurement for facility-scale density, while blade and micro form factors embed into telecommunications and edge-integrated systems.
- Rack Servers:Standardized 1U to 4U enclosures with multi-socket Intel Xeon or AMD EPYC processors populate hyperscale halls at Ascenty and Oi Datacenters. São Paulo banking consortia specify these for core transaction processing clusters where horizontal scaling trumps space constraints.
- Blade Servers:High-density shared infrastructure chassis accommodate hot-swappable compute nodes for metropolitan deployments where real estate costs command premium positioning. Rio de Janeiro financial institutions deploy these in space-constrained facilities near the city center.
- Tower Servers:Standalone vertical enclosures serve branch office and small datacenter environments without rack infrastructure.
- Micro Servers:Compact single-socket systems address lightweight workloads and distributed edge locations.
Rack servers lead volumes today; micro servers are gaining share fastest.
Technology:
Cost tiering separates commodity virtualization from premium AI workloads, with cloud computing anchoring mid-market procurement.
- Cloud Computing:Unified resource pools with software-defined networking underpin Banco do Brasil and Itaú Unibanco infrastructure consolidation programs. These platforms abstract physical server boundaries, compressing hardware refresh cycles.
- Artificial Intelligence:GPU-accelerated NVIDIA H100 and AMD MI300X configurations target training workloads for large language models at Bradesco and Santander Brasil innovation labs. ANATEL certification delays for imported accelerators extend deployment timelines.
- Virtualization:Hypervisor-based server abstraction remains standard for legacy application consolidation.
- Edge Computing:Containerized micro data centers reduce latency for 5G network functions across state capitals.
Cloud computing leads volumes today; artificial intelligence is climbing the fastest.
End User:
Customer type determines certification burden and procurement channel, with regulated industries mandating domestic assembly traceability.
- Telecommunications:Vivo, Claro, and TIM deploy edge-integrated servers for 5G core network functions. ANATEL hardware traceability mandates favor localized assembly partnerships with Dell and Cisco.
- Financial Services:Banking institutions concentrate procurement in São Paulo hyperscale corridors. LGPD data sovereignty requirements force redundant infrastructure duplication, elevating total cost of ownership.
- Government:Federal and state agencies source through ComprasNet procurement portals with domestic content preferences.
- Healthcare:Hospital networks and insurers face ANVISA air-gap mandates for patient record systems.
Telecommunications leads volumes today; healthcare is expanding most quickly.
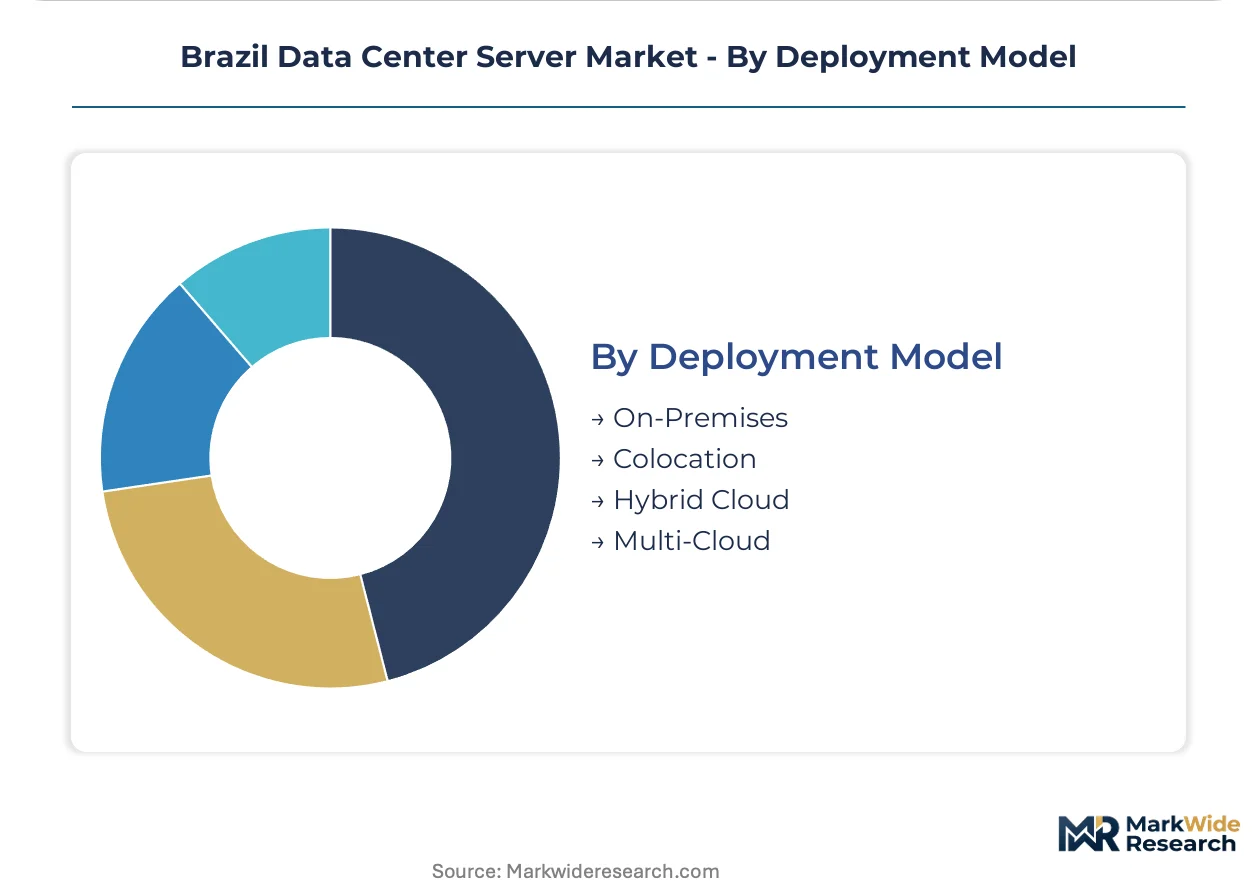
Deployment Model:
Geography shapes infrastructure topology, with southeastern state concentration enabling colocation economics unavailable in northern territories.
- Colocation:Third-party facility operators provide power, cooling, and physical security for tenant-owned servers. Ascenty, Oi Datacenters, and UOL Diveo dominate the southeastern corridor where grid stability supports density.
- On-Premises:Enterprise-owned facilities persist at established institutions with legacy mainframe integration requirements. Core banking systems at Banco do Brasil resist virtualization, forcing hybrid architectures.
- Hybrid Cloud:Split workload distribution between private infrastructure and public cloud platforms.
- Multi-Cloud:Orchestration across AWS, Azure, and Google Cloud regions with local presence.
Colocation leads volumes today; hybrid cloud is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's engineering workforce concentration anchors Brazilian data center infrastructure deployment, with technical talent pools concentrated in Campinas and Sorocaba corridors driving facility operations and server integration capabilities.
São Paulo
Banking consortia and telecommunications groups drive rack server procurement across the São Paulo metropolitan corridor. ANATEL certification requirements mandate hardware traceability standards that favor localized assembly partnerships. Ascenty and Oi Datacenters operate hyperscale halls in Barueri and Santana de Parnaíba where horizontal scaling dominates facility design.
Rio de Janeiro
Petroleum sector digitization and port logistics automation generate blade server demand for space-constrained metropolitan deployments. LGPD data sovereignty enforcement compresses procurement timelines for foreign vendors. Facilities near the city center accommodate financial institutions requiring proximity to commodity trading floors.
Minas Gerais
Belo Horizonte's emerging technology park attracts edge computing investments from telecommunications providers. Federal semiconductor assembly incentives under consideration would reshape supplier economics for equipment deployers. The state's grid stability supports medium-density colocation facilities serving regional banking networks.
Bahia
Salvador's offshore oil services sector generates latent demand for specialized computing infrastructure with minimal incumbent hyperscale presence. CGI.br technical standards shape connectivity requirements for national data residency compliance. Port logistics digitization initiatives in the metropolitan area drive containerized micro data center pilots.
Rio Grande do Sul
Porto Alegre's manufacturing automation sector sustains on-premises server deployments for industrial control systems. ANVISA healthcare data handling regulations extend to pharmaceutical distribution networks in the region. Legacy mainframe integration requirements at established institutions force hybrid architectures complicating density optimization.
Brazil Data Center Server Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Brazilian server procurement landscape. Enterprise networking-integrated deployments favor established channel partnerships, while GPU-accelerated AI workloads reward specialized component suppliers. Three archetypes dominate: full-stack infrastructure vendors, semiconductor component specialists, and telecommunications-integrated systems providers. Strategic consolidation centers on direct OEM contracting and localized assembly partnerships.
Among US-based technology conglomerates, Cisco Systems Inc. and Dell Technologies occupy positions anchoring enterprise networking-integrated and direct-to-hyperscale supply relationships respectively. NVIDIA Corporation exemplifies the semiconductor specialist archetype targeting GPU-accelerated workloads. Hewlett Packard Enterprise and Lenovo Group represent diversified infrastructure vendors with broad portfolio coverage. Super Micro Computer Inc. sits within the focused systems specialist tier.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| NVIDIA Corporation |
| Hewlett Packard Enterprise |
| Intel Corporation |
| Lenovo Group |
| Super Micro Computer Inc. |
| IBM Corporation |
| Advanced Micro Devices (AMD) |
| Dell Technologies |
| Others |
Pricing and Supply Chain Analysis
DRAM spot price indices cascading through motherboard and processor procurement channels compress margin structures for rack server assemblers while amplifying cost pass-through pressures across São Paulo hyperscale corridors. ANATEL certification delays extend inventory carrying costs, forcing distributors to absorb working capital strain or escalate tiered pricing premiums for expedited delivery timelines.
Pricing Analysis
Bundled installation-and-certification packages command 15-25% premiums over bare-metal server transactions, with ANATEL traceability documentation and LGPD compliance consulting embedded in enterprise contracts. Price differentiation separates domestically assembled configurations with full component provenance from direct-import alternatives subject to extended customs clearance. Pricing pressure stems from hyperscale buyers consolidating vendor relationships around frame agreements that compress aftermarket service margins. Financial institutions exhibit lowest price sensitivity due to regulatory compliance mandates, while regional colocation operators face acute cost compression from dollar-denominated component exposure.
Supply Chain Analysis
Reverse-logistics flows for server refurbishment and component recovery are gaining traction as hyperscale operators extend refresh cycles amid semiconductor import bottlenecks. Manufacturing concentration centers on Taiwan, South Korea, and the United States for advanced processors and memory modules, with Brazilian assembly facilities dependent on these upstream nodes. The supply chain rests on GPU accelerators, high-bandwidth memory stacks, and specialized power distribution units as critical inputs. Single-source vulnerability for NVIDIA H100 and AMD MI300X accelerators exposes deployment timelines to allocation rationing. Distribution runs through authorized distributor networks with direct OEM bypass emerging among the three largest facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's data center server market functions as a regulatory compounder where LGPD enforcement thresholds and ANATEL certification mandates continuously elevate compliance-driven replacement demand.
For Market Incumbents: Anchor market position through backward integration into domestic assembly partnerships that satisfy ANATEL hardware traceability requirements. Cisco Systems and Dell Technologies should deepen channel control over telecommunications-integrated deployments as emerging GPU specialists threaten enterprise networking-integrated server margins. Certification investment in parallel ANATEL-ANVISA approval pathways defends against timeline compression risks for healthcare-financial hybrid workloads. For New Entrants and Emerging Players: Capture latent demand in Recife and Salvador's offshore oil services corridor where hyperscale presence remains minimal and port logistics digitization accelerates. The northeast region offers the most penetrable geography for containerized micro data center deployments. A go-to-market angle emphasizing edge-integrated 5G latency reduction with localized assembly partnerships bypasses incumbent distributor lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor component specialists possessing ANATEL certification pathways and established hyperscale relationships. Long-term viability favors suppliers with GPU-accelerated AI workload positioning as national strategy funding channels investment toward training clusters. The signal to watch is federal semiconductor assembly incentive legislation that would reshape supplier economics for foreign OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | ANATEL traceability mandates favor localized component sourcing and shorten procurement cycles. |
| GPU-Accelerated AI Cluster Deployment | National AI strategy funding channels investment toward Bradesco and Santander training workloads. |
| Edge Micro Data Center Expansion | Telecommunications providers deploy containerized facilities for 5G latency reduction beyond São Paulo. |
| Immersive Cooling System Pilot | Dielectric fluid thermal management eliminates raised-floor requirements at São Paulo financial facilities. |
| Direct OEM Frame Agreement | Hyperscale buyers consolidate vendor relationships around multi-year server refresh cycles. |
Research Methodology
Bottom-up financial services and telecommunications procurement modeling reconciled against top-down server shipment tracking forms the analytical core of this study. Primary interviews with data center facility operators, OEM regional sales directors, ANATEL certification consultants, and hyperscale procurement officers combined with secondary validation from customs import records, ANATEL equipment registration databases, and CGI.br connectivity infrastructure reports. Triangulation between demand-side deployment timelines and supply-side manufacturing allocation data ensures consistency across volume estimates.
Historical trendline analysis of server procurement patterns by rack density configuration and GPU acceleration tier informs the projection framework. Segmentation dimensions modeled include product type, technology deployment, end-user industry, and facility geography across the analysis window. CAGRs derive from regression analysis of capital expenditure disclosures by Ascenty, Oi Datacenters, and UOL Diveo, cross-referenced with Banco do Brasil and Itaú Unibanco infrastructure consolidation program announcements. Forecast inputs incorporate ANATEL certification queue lengths and federal semiconductor incentive policy trajectories.
Underlying measurement precision varies by segment; rack server volumes at established hyperscale facilities carry tighter precision than emerging edge micro data center deployments. Forecasts reflect assumptions regarding LGPD enforcement intensity and ANATEL staffing capacity for equipment approvals. Periodic stress-testing of base assumptions is recommended given exposure to dollar-denominated component volatility and federal incentive policy uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Germany Data Center Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Hyperscale Data Center Market
Data Center Infrastructure
Data Center Blade Server Market