
 Spain Data Center Market | 2026-2036
Spain Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Data Center Market Insights
Software-defined power management is broadening what operators bundle into base contracts, shifting revenue from pure space rental to guaranteed energy performance tiers. Equinix leverages its interconnection fabric to anchor premium pricing in Madrid's carrier-neutral zones. Digital Realty sustains scale advantages through pre-built shell capacity in key logistics corridors. Merlin Properties competes on real estate cost structures, converting industrial warehouses into data halls at speed.
A data center is a purpose-built facility housing servers, storage systems, and network equipment with controlled environmental parameters—typically maintaining temperatures between 18°C and 27°C and achieving power usage effectiveness ratios below 1.4 for modern builds—designed to deliver continuous compute, storage, and connectivity services for enterprise and consumer applications. Colocation services capture the largest revenue share as enterprises exit owned facilities, while edge computing deployments within the technology segment are expanding fastest due to latency requirements from autonomous systems and industrial IoT. The delivery model dimension shows hybrid architectures dominating new commitments as organizations balance sovereignty requirements against cloud elasticity.
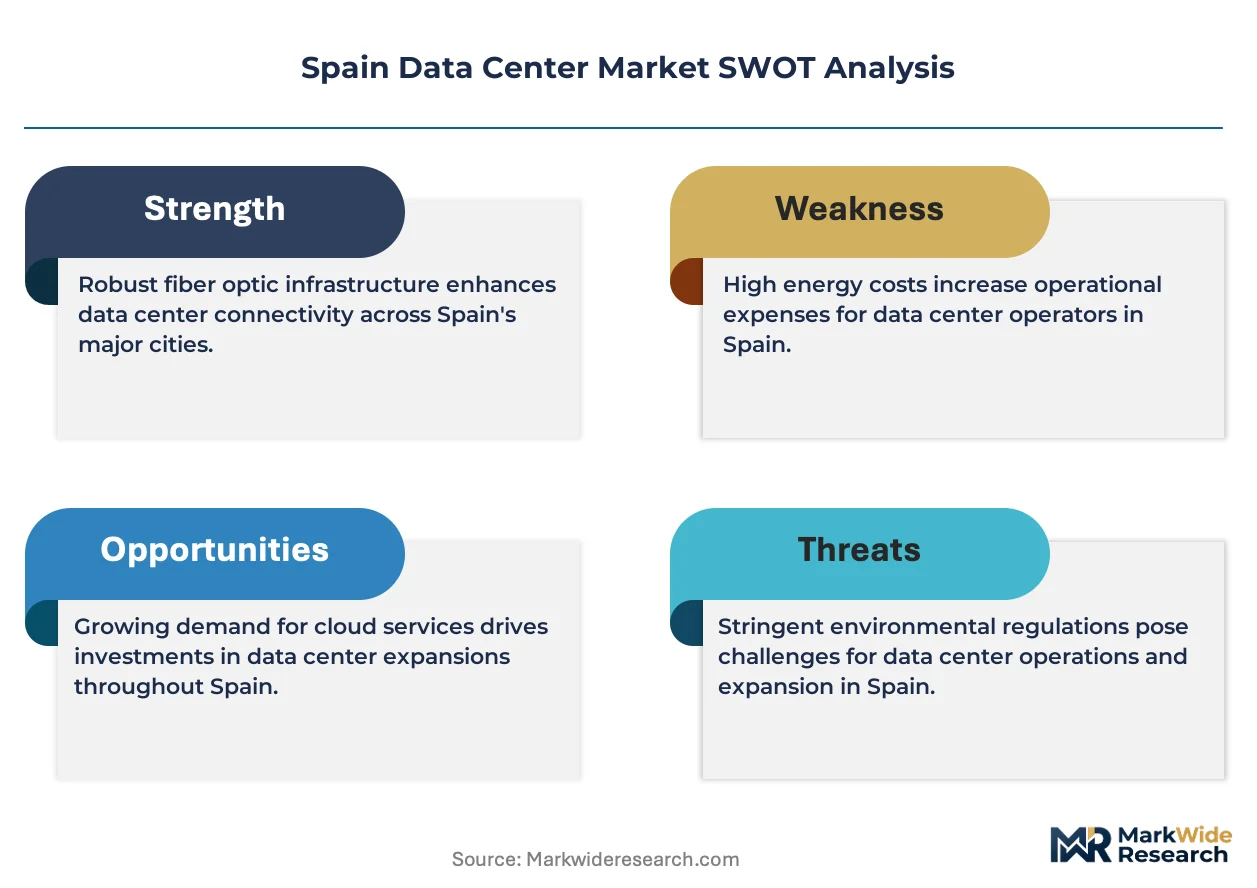
Spain's data center operators must comply with EU Green Deal emissions reporting, national building codes enforced by the Ministry of Transport and Sustainable Mobility, and BIS-aligned electrical safety certifications for critical infrastructure equipment. These frameworks raise capital requirements for new builds while advantaging operators with existing efficient footprints. Stakeholders must monitor whether proposed EU-wide sustainability disclosure rules expand to cover Scope 3 supply chain emissions from construction materials and backup generator fuel cycles.
Market Dynamics
Spanish data center operators face tightening operational standards from the EU AI Act and national energy efficiency codes, forcing capital-intensive retrofits while BFSI institutions accelerate colocation migrations to satisfy digital banking resilience mandates.
Growth Catalysts
- EU AI Act certification requirements:Financial institutions under BFSI must demonstrate algorithmic audit trails and data sovereignty controls, driving demand for carrier-neutral facilities with dedicated compliance zones.
- Hyperscale edge deployments:Autonomous vehicle testing corridors and industrial IoT networks in Madrid's metropolitan corridor require sub-10ms latency infrastructure, pulling compute closer to fiber-dense interconnection points.
- Renewable energy access:Iberian solar and wind generation capacity allows operators to meet EU Green Deal emissions reporting thresholds without purchasing offsets, lowering long-term power cost structures.
Market Restraints
- Grid interconnection bottlenecks:Spain's transmission infrastructure limits power delivery to proposed hyperscale sites in Castilla-La Mancha, extending commissioning timelines by 18-24 months.
- Specialized construction labor scarcity:European electrical safety certifications for critical infrastructure equipment require BIS-aligned technician credentials that outpace vocational training program output.
- Liquid cooling supply concentration:Precision cooling component manufacturing concentrates in German and Dutch industrial clusters, exposing Spanish projects to euro-denominated input cost volatility.
Strategic Opportunities
- Andalusian port corridor expansion:Submarine cable landing stations in Algeciras and Málaga offer alternative interconnection routes to Madrid-centric fiber topology, enabling disaster recovery site diversification.
- Heat reuse district heating integration:Municipal utilities in Bilbao and Barcelona pilot waste heat capture from data halls for residential warming, unlocking EU Green Deal subsidy eligibility.
- Quantum-safe cryptography retrofit services:Post-quantum encryption hardware deployment creates service revenue layers for operators managing BFSI tenant migrations before NIS2 directive deadlines.
Industry Challenges
- Commissioning engineer shortage:Spain produces fewer than 200 certified critical facility technicians annually against hyperscale construction schedules requiring 50+ per project.
- Legacy building stock thermal limitations:Industrial warehouse conversions by real estate investors often lack slab load capacity for liquid cooling infrastructure, forcing structural reinforcement cost overruns.
- Multi-tenant compliance segmentation:Shared facilities must maintain physically isolated audit trails for EU AI Act high-risk system deployments, complicating space planning and access control architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Data Center Market |
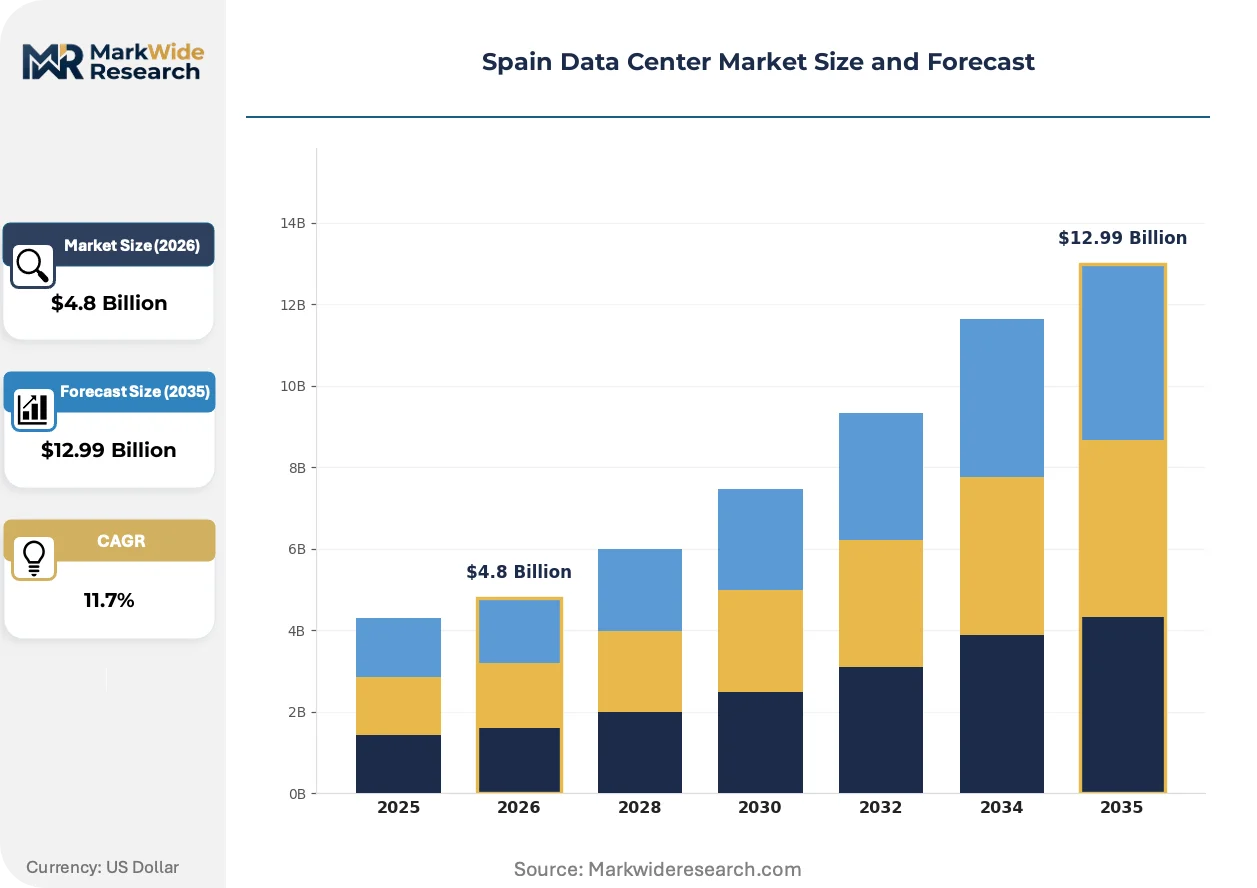
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Disaster Recovery Technology: Virtualization, Blockchain, AI, Edge Computing End User: BFSI, Healthcare, Retail, Government Delivery Model: Cloud, On-Premise, Hybrid, Outsourced |
| Companies Covered | Equinix, Digital Realty, Merlin Properties, Colt Data Centre Services, NTT DATA, Iron Mountain, Schneider Electric, Eaton Corporation, Vertiv Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Data Center Market Trends and Innovations
Software-defined infrastructure is compressing traditional hardware refresh cycles while regulatory pressure on embodied carbon forces design-phase material choices that were previously procurement afterthoughts.
Immersion cooling is rewriting thermal management economics for high-density AI training clusters. Hyperscale tenants in Madrid's carrier-neutral zones specify single-phase dielectric fluid systems for racks exceeding 50kW per cabinet, eliminating mechanical refrigeration in favor of dry cooler heat rejection. This shift is compressing power usage effectiveness ratios below 1.15 for new builds while disqualifying legacy raised-floor facilities from premium contract tiers.
The EU Green Deal emissions reporting framework now mandates Scope 1 and 2 disclosure for facilities above 500kW installed capacity. Spanish operators must submit verified carbon intensity metrics to the Ministry of Transport and Sustainable Mobility biannually, with non-compliance risking exclusion from public sector cloud procurement frameworks. BFSI tenants prioritize landlords with third-party validated environmental product declarations for structural steel and concrete.
Consumption-based power contracting is displacing flat-rate colocation agreements. Enterprise buyers in Barcelona and Valencia negotiate kWh-indexed pricing that transfers renewable energy certificate ownership and real-time carbon accounting liability to operators. This restructuring is most visible among pharmaceutical and semiconductor manufacturers with Science Based Targets initiative commitments requiring supply chain emission transparency.
Spain Data Center Market Segmentation
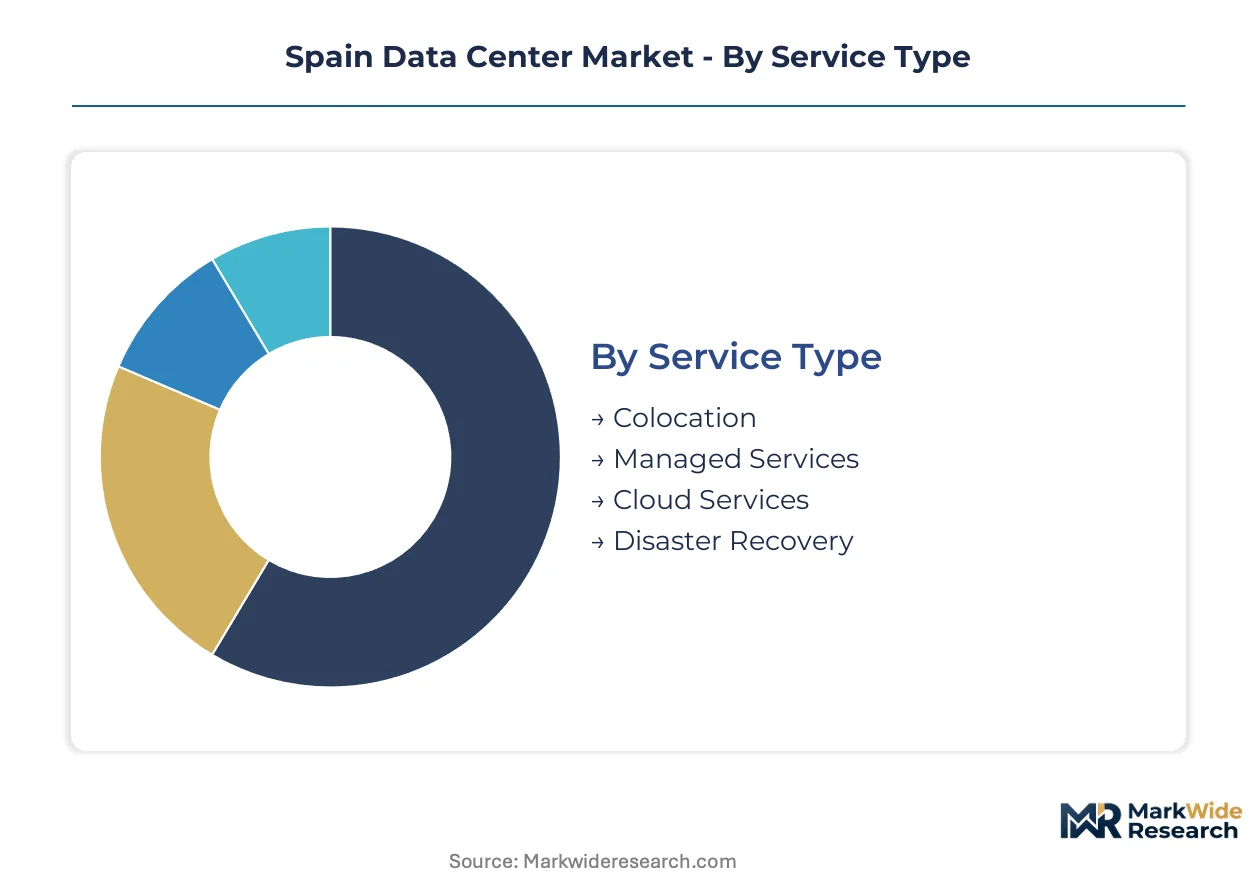
Spain's data center market segments along four distinct dimensions that shape operator investment priorities and tenant procurement patterns. Each category reflects divergent cost structures, compliance burdens, and infrastructure requirements that determine competitive positioning across Madrid's carrier-neutral zones and secondary regional markets.
Service Type:
Supply concentration among hyperscale operators in Madrid's metropolitan corridor favors colocation providers with pre-certified energy performance tiers and direct renewable energy contracting capabilities.
- Colocation:Physical space rental with power, cooling, and physical security bundled under standardized service level agreements. Spanish BFSI institutions dominate demand in Madrid's carrier-neutral facilities as EU AI Act compliance mandates drive migrations from owned infrastructure. The segment commands premium pricing where operators offer verified renewable energy certificates and sub-1.2 PUE guarantees.
- Managed Services:Operational responsibility transfer covering server administration, patch management, and performance monitoring through remote hands agreements. Mid-market enterprises in Barcelona and Valencia favor this model to address commissioning engineer scarcity without building internal critical facility expertise. Providers differentiate through response time guarantees and specialized pharmaceutical manufacturing compliance support.
- Cloud Services:Consumption-based compute and storage provisioning through hyperscale platforms with local presence zones.
- Disaster Recovery:Secondary site replication and failover orchestration for business continuity assurance.
Today's leader: Colocation. Tomorrow's challenger: Managed Services.
Technology:
Application intensity varies sharply across Spanish end-users, with latency-sensitive deployments clustering in fiber-dense corridors while batch processing workloads distribute to lower-cost hinterland sites.
- Virtualization:Server consolidation through hypervisor abstraction enabling multi-tenant resource pooling. Legacy enterprise workloads in Madrid's financial district rely on this foundation, though containerization is displacing pure virtualization for cloud-native application migrations.
- Edge Computing:Distributed compute nodes positioned within 10 milliseconds of data generation sources. Autonomous vehicle testing corridors and industrial IoT networks in Castilla-La Mancha and the Basque Country pull infrastructure investment away from centralized hyperscale concentration, expanding most quickly among all technology segments as latency requirements harden.
- AI:GPU-intensive training and inference clusters with liquid cooling infrastructure requirements.
- Blockchain:Distributed ledger validation nodes with energy-intensive proof-of-work or proof-of-stake consensus mechanisms.
Virtualization retains installed base dominance. Edge computing claims the steepest expansion trajectory.
End User:
Customer type segmentation reveals divergent procurement sophistication, with regulated industries demanding audit-grade compliance infrastructure while commercial sectors prioritize cost-per-watt optimization.
- BFSI:Banking, financial services, and insurance institutions with algorithmic audit trail mandates under EU AI Act and NIS2 directive timelines. These tenants occupy premium Madrid colocation space with physically isolated compliance zones and quantum-safe cryptography migration services.
- Healthcare:Hospital systems, pharmaceutical manufacturers, and medical device companies with patient data sovereignty requirements. Barcelona's research hospitals and Bilbao's medical technology cluster drive demand for consumption-based power contracting with real-time carbon accounting.
- Retail:E-commerce platforms and omnichannel merchants with seasonal traffic volatility.
- Government:Public sector cloud procurement frameworks with EU Green Deal emissions reporting prerequisites.
BFSI tenants anchor revenue stability. Healthcare procurement is climbing the fastest on sustainability-linked contracting.
Delivery Model:
Margin structures compress where delivery standardizes, while hybrid architectures sustain premium pricing through integration complexity and sovereignty assurance.
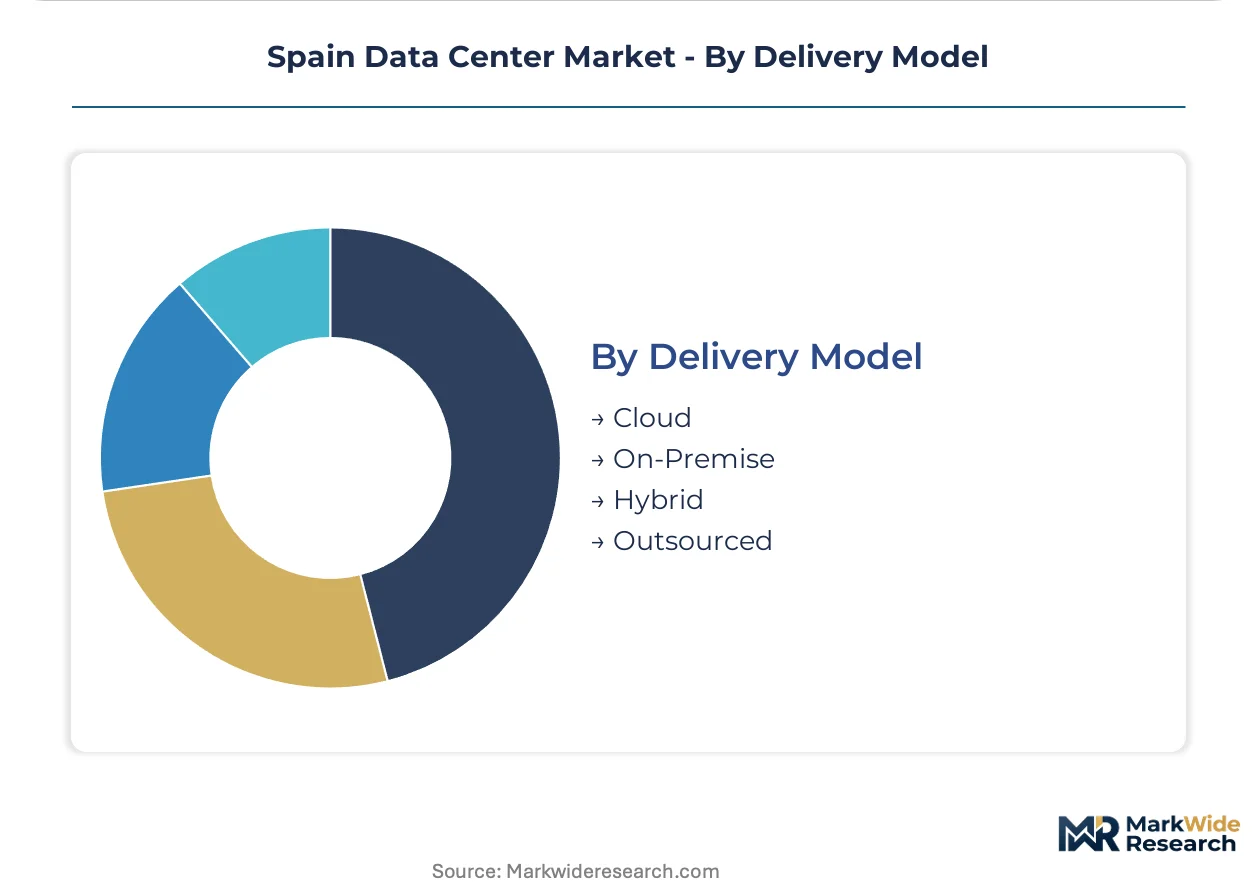
- Hybrid:Orchestrated workload distribution across on-premise, colocation, and public cloud resources with unified management planes. Spanish enterprises with Science Based Targets initiative commitments favor this model to balance supply chain emission transparency against cloud elasticity, representing the dominant commitment pattern for new infrastructure decisions.
- Cloud:Full workload migration to hyperscale provider infrastructure with shared responsibility security models.
- On-Premise:Enterprise-owned and operated facilities with direct capital deployment and operational control.
- Outsourced:Complete IT infrastructure delegation to managed service providers with outcome-based service level agreements.
Hybrid architectures define current procurement. Pure cloud commitments are gaining share fastest among SME segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's data center pipeline exceeds Spain's commissioned capacity, yet Madrid's renewable energy pricing undercuts Frankfurt's grid tariffs by margins that attract hyperscale tenants seeking carbon-neutral compute.
Madrid
Spain's capital commands the national data center inventory through carrier-neutral interconnection density and direct fiber routes to submarine cable landing stations. The Ministry of Transport and Sustainable Mobility enforces national building codes that mandate power usage effectiveness thresholds for new certifications. Alcobendas and San Sebastián de los Reyes host the majority of hyperscale deployments, where operators pre-lease shell capacity before construction completion.
Catalonia
Barcelona's metropolitan area attracts pharmaceutical and semiconductor manufacturers with Science Based Targets initiative commitments requiring supply chain emission transparency. EU Green Deal emissions reporting frameworks apply to facilities above 500kW installed capacity throughout the autonomous community. The Zona Franca industrial district pilots waste heat capture integrations with municipal district heating networks, unlocking subsidy eligibility under decarbonization programs.
Basque Country
Bilbao's port infrastructure and submarine cable connectivity position the region as a disaster recovery alternative to Madrid-centric topology. BIS-aligned electrical safety certifications for critical infrastructure equipment govern technician credentialing requirements. The metropolitan area's medical technology cluster drives consumption-based power contracting with real-time carbon accounting for hospital system data sovereignty.
Andalusia
Algeciras and Málaga offer alternative interconnection routes through submarine cable landing stations that bypass Madrid's fiber concentration. The EU AI Act certification requirements for algorithmic audit trails apply to financial institutions establishing secondary processing sites. Port corridor expansion projects enable latency-sensitive edge deployments for autonomous vehicle testing corridors connecting to North African markets.
Valencia
The metropolitan area captures mid-market enterprise demand from manufacturing and logistics sectors seeking lower real estate cost structures than Madrid. National energy efficiency codes enforced by the Ministry of Transport and Sustainable Mobility raise capital requirements for new builds. The port city's industrial zones attract industrial IoT network deployments requiring sub-10ms latency infrastructure for predictive maintenance systems.
Spain Data Center Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with carrier-neutral facility operators commanding premium pricing against real estate conversion specialists competing on construction speed. The market structure concentrates around three strategic archetypes: interconnection fabric owners leveraging network density, hyperscale shell developers with pre-built capacity, and industrial real estate converters repurposing warehouse stock. Competitive moves center on renewable energy contracting and liquid cooling infrastructure partnerships that disqualify legacy facilities from premium tenant tiers.
Within the interconnection-focused tier, Equinix and Digital Realty exemplify carriers leveraging Madrid's fiber density for premium colocation positioning. Merlin Properties represents the real estate conversion archetype, accelerating data hall delivery through industrial warehouse adaptations. NTT DATA occupies a position bridging managed services and infrastructure ownership, serving BFSI tenants with compliance zone requirements.
| Leading Market Players |
|---|
| Equinix |
| Digital Realty |
| Merlin Properties |
| Colt Data Centre Services |
| NTT DATA |
| Iron Mountain |
| Schneider Electric |
| Eaton Corporation |
| Vertiv Group |
| Others |
Pricing and Supply Chain Analysis
BFSI procurement mandates for EU AI Act compliance are forcing Spanish operators to source certified electrical components and liquid cooling infrastructure, compressing margins on standard colocation tiers while widening spreads between premium certified and uncertified capacity.
Pricing Analysis
Capacity additions in Madrid's metropolitan corridor are reshaping price floors for standard colocation tiers, while certified premium space with sub-1.2 PUE guarantees commands widening spreads. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-compliant zones with quantum-safe cryptography support from basic raised-floor capacity. Pricing pressure stems from hyperscale pre-leasing commitments that lock in renewable energy certificates at fixed rates. Mid-market pharmaceutical manufacturers exhibit highest price sensitivity due to Science Based Targets initiative compliance costs, whereas BFSI tenants prioritize audit-grade infrastructure over per-kilowatt economics.
Supply Chain Analysis
BIS-aligned electrical safety certifications for critical infrastructure equipment gate technician availability and component sourcing across Spanish projects. Precision cooling manufacturing concentrates in Germany and the Netherlands, while electrical switchgear production centers on France and Italy. Spanish operators draw from Taiwanese server assembly, Chinese cable infrastructure, and domestic renewable energy generation. Single-source vulnerability runs through German-Dutch liquid cooling component clusters exposed to euro-denominated input volatility. Distribution runs through Madrid-based system integrators with direct relationships to hyperscale tenant engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's data center market functions as a geographic-arbitrage play where Iberian solar and wind pricing undercuts German grid tariffs, attracting carbon-neutral compute demand from Frankfurt-constrained tenants.
For Market Incumbents: Deepen renewable energy contracting capabilities through direct power purchase agreements with Spanish utility-scale solar developers, locking in cost advantages against grid-tied competitors. Fortify liquid cooling infrastructure partnerships with German and Dutch precision cooling specialists before supply bottlenecks intensify. Commissioning engineer scarcity threatens expansion timelines; captive training programs with Basque Country vocational institutes address credential pipeline gaps. For New Entrants and Emerging Players: Enter via Andalusian port corridor submarine cable landing stations, where Algeciras and Málaga offer disaster recovery diversification outside Madrid's fiber concentration with lower land acquisition costs. Target pharmaceutical and semiconductor manufacturers in Barcelona's Zona Franca district seeking consumption-based power contracting with real-time carbon accounting. Position around heat reuse district heating integrations with municipal utilities as a differentiated sustainability service layer. For Investors and Strategic Acquirers: Asymmetric upside sits with industrial real estate converters possessing warehouse stock in Valencia and Bilbao logistics corridors, where structural reinforcement for liquid cooling capacity creates value-accretive retrofit opportunities. Five-to-ten-year viability hinges on EU Green Deal emissions reporting enforcement expanding to Scope 3 supply chain disclosures. Monitor proposed EU-wide sustainability disclosure rules covering construction materials and backup generator fuel cycles as inflection trigger for certified facility premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Partnership | Secures access to German-Dutch precision cooling components for AI training clusters exceeding 50kW per cabinet. |
| Renewable Energy Certificate Lock-in | Direct Iberian solar and wind contracting meets EU Green Deal thresholds without offset purchases. |
| Heat Reuse District Heating Integration | Bilbao and Barcelona municipal utility pilots unlock EU Green Deal subsidy eligibility for waste heat capture. |
| Quantum-Safe Cryptography Retrofit Service | BFSI tenant migration revenue layer addresses NIS2 directive deadlines before post-quantum hardware deployment. |
| Andalusian Port Corridor Expansion | Algeciras submarine cable landing stations enable disaster recovery site diversification outside Madrid topology. |
Research Methodology
Multiple input streams — hyperscale tenant engineering directors, Spanish BFSI infrastructure procurement leads, critical facility commissioning engineers, and renewable energy project developers — were reconciled against secondary validation from EU Green Deal emissions filings, Ministry of Transport and Sustainable Mobility building code certifications, and hyperscaler capex disclosures. Bottom-up capacity tracking across Madrid, Catalonia, Basque Country, Andalusia, and Valencia was triangulated with top-down demand modeling from enterprise cloud migration surveys.
Data-stream reconciliation anchored analytical framework construction across the projection horizon, modeling service type, technology deployment, end-user industry, and delivery model dimensions. CAGRs were derived from installed capacity pipelines against demand absorption rates from BFSI colocation migrations and edge computing latency requirements. Forecast inputs incorporated grid interconnection timelines from Spain's transmission infrastructure operator and liquid cooling supply lead times from German-Dutch manufacturing clusters.
Inputs from hyperscale tenant engineering teams and Spanish utility renewable energy developers were available through the study window; gaps in proprietary hyperscaler deployment schedules introduce uncertainty bands around capacity absorption timing. Forecasts reflect assumptions on EU AI Act enforcement timelines and national energy efficiency code expansion. A model refresh is warranted upon material change in grid interconnection bottlenecks or liquid cooling supply concentration dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
North America Hyperscale Data Center Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Converged Data Center Infrastructure Market