
 Global Online Survey Software Market | 2026-2036
Global Online Survey Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Survey Software Market Outlook
Asset-light SaaS subscription models are reshaping competitive entry in online survey software, allowing niche vendors to challenge incumbents without heavy infrastructure. Qualtrics leverages enterprise-grade experience management integrations to sustain premium positioning. SurveyMonkey anchors the self-serve segment through freemium conversion mechanics. Zoho Corporation competes by bundling survey tools within broader business software suites.
Online survey software encompasses cloud-hosted and on-premise platforms that design, distribute, collect, and analyze structured questionnaires through web interfaces, typically supporting multi-channel distribution via email, SMS, and embedded links. The primary commercial purpose centers on systematic voice-of-customer capture, employee engagement measurement, and market research data collection at scale. Cloud-based deployment leads the architecture mix due to elastic scaling and reduced IT overhead for distributed teams. Academic institutions represent a fast-growing end-user category as remote learning normalizes institutional feedback loops. API integration capabilities increasingly determine platform stickiness within enterprise technology stacks.
The EU AI Act imposes algorithmic transparency obligations on automated survey analysis tools deployed across European member states. The US FDA regulates patient-reported outcome instruments used in clinical trials, directly shaping healthcare survey software specifications. ISO 27001 certification requirements govern data handling practices for cross-border SaaS providers. Stakeholders must monitor evolving consent frameworks and interoperability mandates as jurisdictions diverge on data localization rules.
Market Dynamics
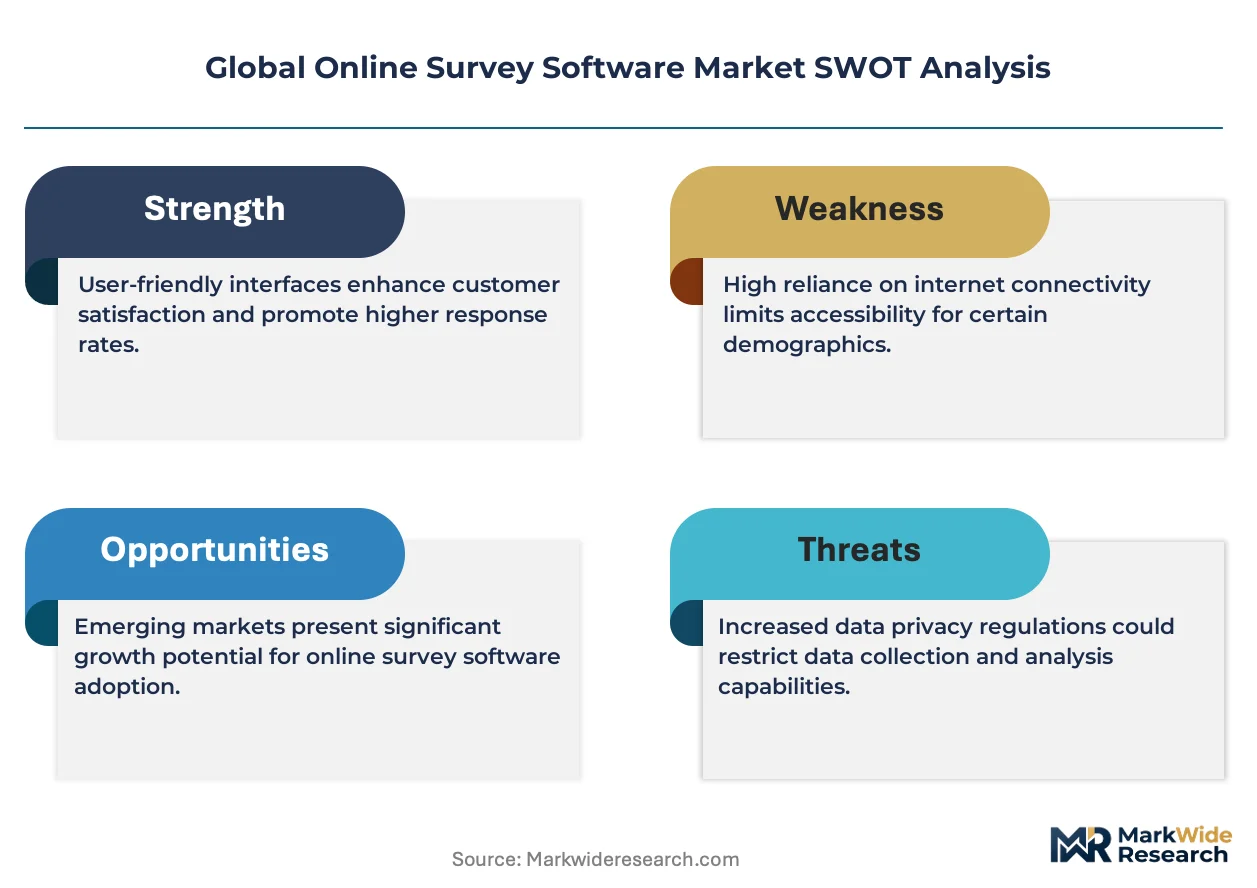
The EU AI Act's algorithmic transparency mandates are forcing survey platforms to reengineer automated sentiment analysis pipelines, while healthcare providers scale patient-reported outcome systems under FDA guidance. These dual regulatory pressures are compressing vendor R&D cycles and reshaping competitive moats around compliance infrastructure.
Growth Catalysts
- Healthcare digitization:FDA-regulated patient-reported outcome instruments now drive clinical trial software procurement, expanding specialized survey modules across pharmaceutical research organizations.
- EU AI Act consent frameworks:Automated analysis tools deployed across European member states must implement explainable AI disclosures, creating upgrade demand for legacy platforms.
- Academic remote learning normalization:Institutional feedback loops at universities now require continuous course evaluation systems, accelerating semesterly licensing cycles.
Market Restraints
- Cross-border data localization:Divergent sovereignty rules between Germany's BSI standards and China's PIPL compliance fragment cloud architecture decisions for multinational deployments.
- API standardization gaps:Lack of unified interoperability protocols forces expensive custom integration work for enterprise technology stack embedding.
- Freemium conversion ceilings:Self-serve pricing floors limit revenue extraction from small business segments with sub-fifty-employee headcounts.
Strategic Opportunities
- India's PLI scheme for SaaS:Production-linked incentives for software exports create cost-advantaged development centers serving Asia-Pacific healthcare and education verticals.
- Voice-response convergence:Natural language processing integration with interactive voice response systems opens accessibility-compliant channels for elderly and disabled respondent populations.
- CSRD mandate expansion:Corporate Sustainability Reporting Directive requirements for stakeholder sentiment tracking drive ESG-focused survey module adoption across EU-headquartered multinationals.
Industry Challenges
- ISO 27001 certification timelines:Information security management system audits create six-to-twelve-month go-to-market delays for cross-border SaaS entrants.
- Legacy on-premise migration friction:Government and defense sector customers with air-gapped requirements resist cloud-native feature parity, forcing dual-codebase maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Survey Software Market |
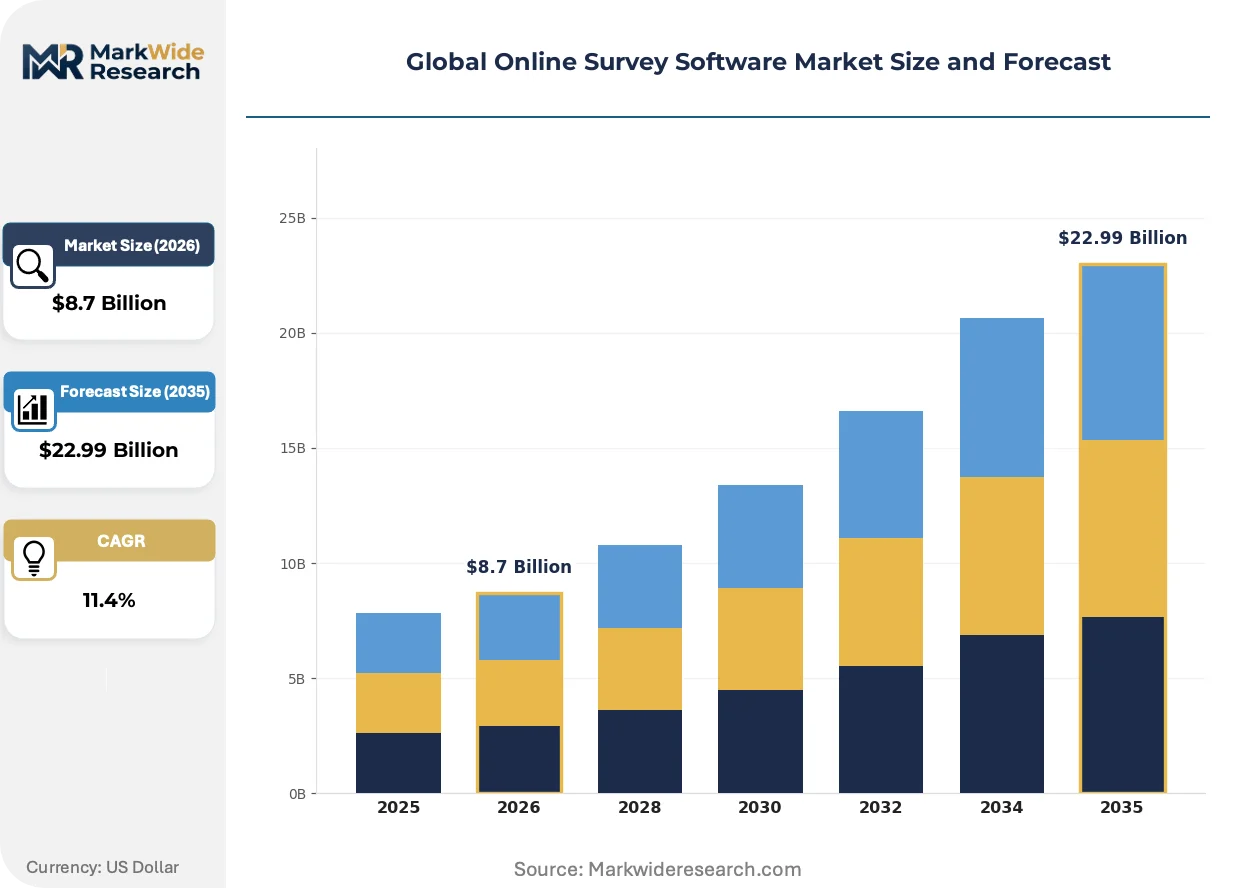
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Enterprises, Academic Institutions, Government Agencies, Market Research Firms Solution: Survey Creation, Data Analysis, Reporting Tools, Panel Management Integration Level: API Integration, Custom Integrations, Plugins, Standalone Solutions |
| Companies Covered | Qualtrics, SurveyMonkey, Medallia, Zoho Corporation, Alchemer, Typeform, Google Forms, QuestionPro, SurveySparrow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Survey Software Market Strategic Shifts
Multimodal data capture is reshaping how survey platforms collect respondent input, moving beyond discrete questionnaires toward continuous behavioral signal integration. This shift is compressing the distinction between structured research instruments and ambient analytics infrastructure.
Generative AI is hybridizing survey design workflows by automating questionnaire drafting and adaptive branching logic. Mid-market research agencies now deploy these tools to compress study launch timelines from weeks to days. The technology is hybridizing the traditional services layer, enabling software vendors to capture consulting value previously held by research firms.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes automated decision systems. Survey platforms deploying predictive respondent scoring must maintain algorithmic audit trails. Healthcare and financial services segments in France and Germany are front-loading compliance investments ahead of enforcement deadlines.
Enterprise buyers now unbundle implementation services from software licenses, demanding API-first architectures that internal data science teams can configure independently. This procurement pattern displaces traditional managed services relationships. Technology and professional services verticals in the United States exhibit the most aggressive self-service orientation.
Global Online Survey Software Market Segmentation
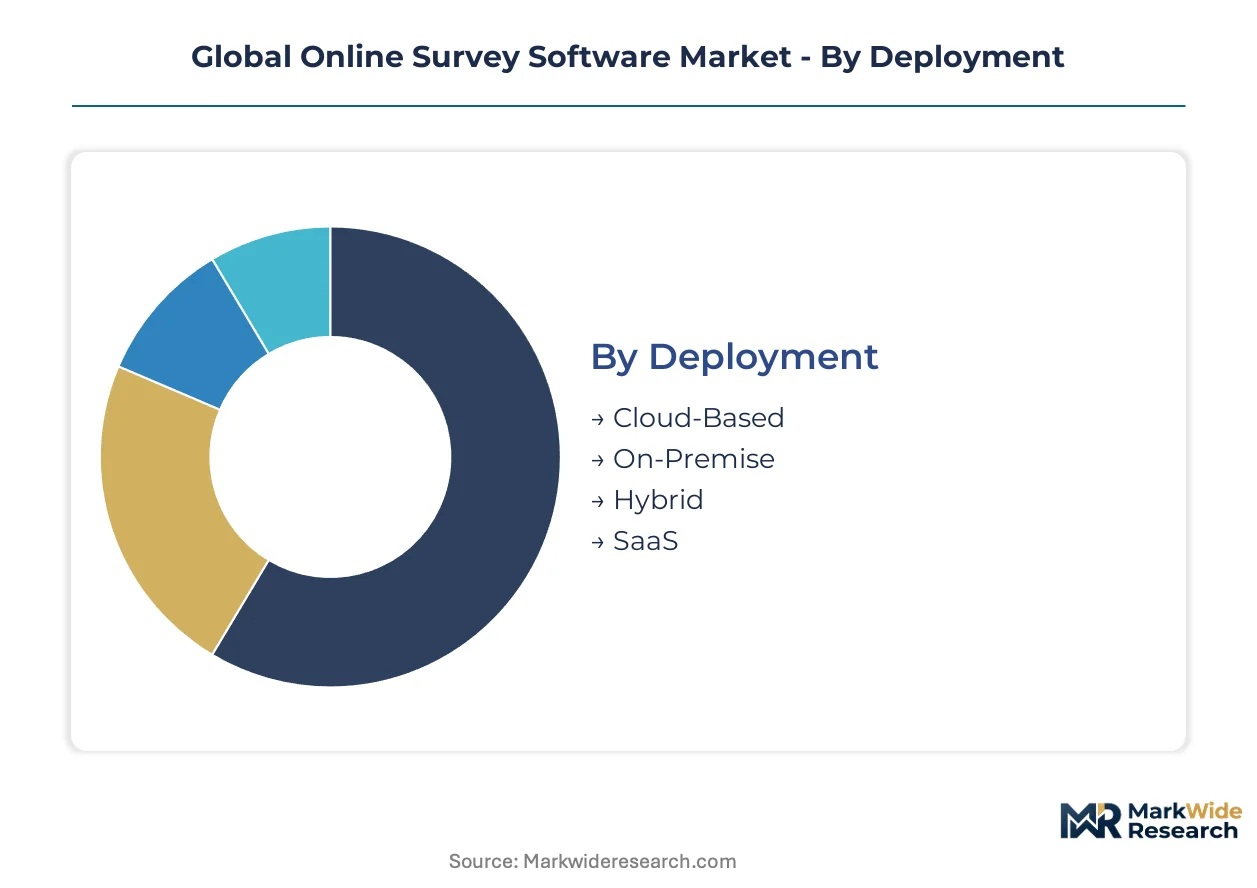
Segmentation reveals how online survey software vendors allocate R&D resources across divergent technical requirements. Cloud-native architectures demand continuous DevOps investment while on-premise solutions require legacy compatibility maintenance. The four-dimensional structure below maps where procurement budgets concentrate and where compliance obligations fragment vendor strategies.
Deployment:
After-sales service intensity varies sharply across deployment modes, with on-premise installations requiring sustained field engineering support and cloud deployments relying on automated ticketing systems.
- Cloud-Based:Multi-tenant architectures with elastic compute scaling eliminate infrastructure ownership for distributed teams. Demand concentrates among United States enterprises with decentralized workforces, driven by IT overhead reduction mandates and SOC 2 compliance automation.
- On-Premise:Single-tenant installations within customer-controlled data centers support air-gapped security requirements. German government agencies and French defense contractors anchor this segment, constrained by BSI and ANSSI certification timelines that extend sales cycles.
- Hybrid:Split architectures process sensitive data on-premise while leveraging cloud analytics for non-critical workloads.
- SaaS:Fully managed subscription tiers with automatic feature updates and shared infrastructure economics.
By volume, Cloud-Based leads. By growth pace, Hybrid is gaining share fastest as sovereignty-sensitive sectors seek compromise architectures.
End User:
Customer acquisition costs stratify sharply across end-user categories, with enterprise accounts demanding multi-quarter proof-of-concept cycles and academic segments converting on semesterly procurement calendars.
- Enterprises:Multi-divisional deployments with role-based access controls and SSO federation requirements. United States technology and financial services firms drive procurement, prioritizing API extensibility for CRM and ERP stack embedding.
- Academic Institutions:Course evaluation and institutional research applications with seasonal usage spikes. Indian universities and Brazilian federal institutions are expanding most quickly as remote learning infrastructure normalizes.
- Government Agencies:Public sector procurement with strict accessibility and Section 508 compliance mandates.
- Market Research Firms:High-volume fieldwork operations requiring panelist incentives and fraud detection systems.
Enterprises dominate revenue contribution. Academic Institutions show the steepest expansion trajectory as learning management system integrations deepen.
Solution:
Margin structures diverge across solution components, with raw survey creation tools commoditizing while advanced analytics modules sustain premium pricing.
- Survey Creation:Drag-and-drop questionnaire builders with template libraries and logic branching. Demand concentrates in self-serve small business segments in the United Kingdom and Australia, constrained by freemium conversion ceilings.
- Data Analysis:Statistical computing engines with automated significance testing and cross-tabulation. Healthcare providers in the United States and pharmaceutical sponsors in Switzerland anchor demand, driven by FDA and Swissmedic patient-reported outcome validation requirements.
- Reporting Tools:Dashboard visualization and executive summary automation for stakeholder distribution.
- Panel Management:Respondent database operations with demographic screening and incentive fulfillment.
Survey Creation leads by deployment volume. Data Analysis commands the highest growth multiple as regulated sectors invest in compliant analytics infrastructure.
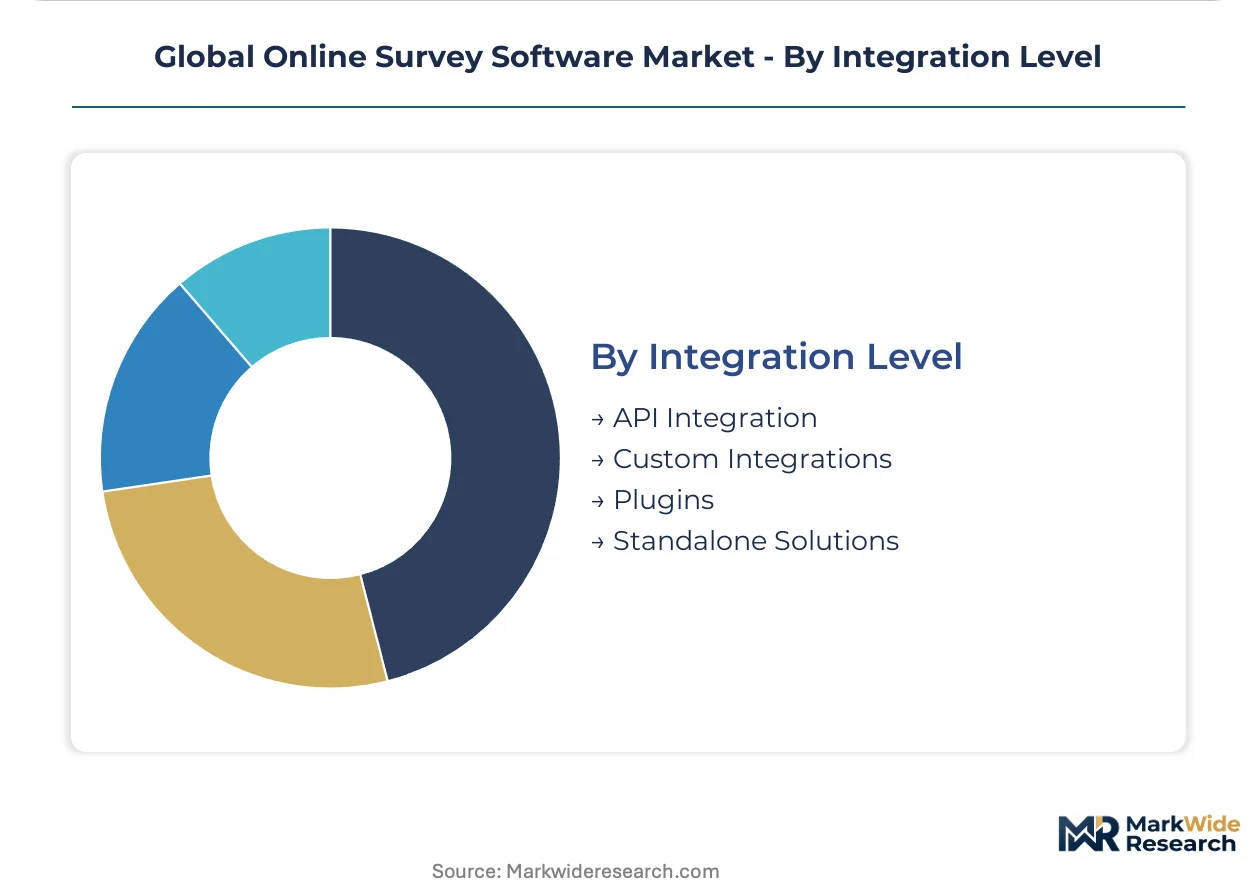
Integration Level:
Technical stickiness correlates directly with integration depth, where API-first architectures embed vendors within customer technology stacks and standalone solutions face higher churn risk.
- API Integration:RESTful and GraphQL endpoints enabling custom data flows between survey platforms and enterprise systems. United States technology companies and Japanese automotive firms prioritize this tier, driven by data science team autonomy demands and METI digital transformation guidelines.
- Custom Integrations:Bespoke connector development for legacy on-premise systems. German manufacturing conglomerates and South Korean chaebols anchor this segment, constrained by ISO 27001 certification requirements for cross-border data handling.
- Plugins:Pre-built extensions for popular productivity and collaboration platforms.
- Standalone Solutions:Self-contained deployments with minimal external system dependencies.
API Integration leads by new contract value. Custom Integrations are climbing the fastest as industrial conglomerates modernize legacy quality management systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in SaaS survey platforms favor net exporters in the United States and India against net importers in Germany and Japan. Cross-border data flows concentrate procurement decisions in jurisdictions with clear certification frameworks. Regulatory fragmentation now shapes where vendors establish primary development centers versus sales subsidiaries.
United States
Enterprise SaaS procurement runs deepest among technology and financial services firms in California and New York. FDA guidance on patient-reported outcome instruments directly shapes healthcare survey software specifications for pharmaceutical sponsors. The Boston-Cambridge corridor anchors specialized clinical trial platform development under HIPAA compliance mandates.
Germany
Industrial conglomerates in Bavaria and North Rhine-Westphalia drive demand for ISO 27001-certified survey infrastructure. BSI standards and the EU AI Act impose algorithmic transparency obligations on automated sentiment analysis tools deployed across member states. Stuttgart-based automotive groups now require explainable AI disclosures for employee feedback systems.
India
Academic institutions in Karnataka and Maharashtra accelerate semesterly licensing for remote learning feedback platforms. The PLI scheme for SaaS exports creates cost-advantaged development centers serving Asia-Pacific healthcare verticals. Hyderabad and Bengaluru clusters specialize in voice-response accessibility features for elderly respondent populations.
Japan
Automotive and electronics manufacturers under METI digital transformation guidelines prioritize API-first survey architectures. Domestic data localization preferences resist pure cloud deployments, sustaining hybrid infrastructure demand. The Nagoya-Chubu industrial corridor leads quality management system integrations with legacy enterprise resource planning stacks.
United Kingdom
Self-serve small business segments in London and the Southeast constrain vendor pricing floors through freemium conversion mechanics. GDPR compliance requirements intersect with post-Brexit data adequacy negotiations, fragmenting cross-border SaaS procurement. Edinburgh and Manchester clusters specialize in academic research platform customization for institutional review board workflows.
Global Online Survey Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in analytics and panel management modules. The vendor base stratifies across three tiers: enterprise experience management suites, mid-market self-serve tools, and vertical-specific compliance platforms. Strategic archetypes include bundlers embedding survey functions within broader business software, pure-play specialists defending premium analytics pricing, and API-first infrastructure providers. Competitive moves concentrate on M&A for data science capabilities and geographic expansion through localized certification investments.
Within the enterprise tier, Qualtrics and Medallia exemplify experience management platform consolidation. SurveyMonkey occupies a position anchoring the self-serve segment through freemium conversion mechanics. Zoho Corporation represents the bundler archetype, sitting within broader business software suites that distribute survey tools through existing customer relationships.
| Leading Market Players |
|---|
| Qualtrics |
| SurveyMonkey |
| Medallia |
| Zoho Corporation |
| Alchemer |
| Typeform |
| Google Forms |
| QuestionPro |
| SurveySparrow |
| Others |
Value Chain & Pricing Dynamics
Bengaluru and Hyderabad development clusters feed cost-advantaged engineering capacity into global SaaS pricing structures, compressing development cost bases for cloud-native survey platforms while amplifying margin pressure on legacy on-premise vendors with higher fixed-cost footprints.
Pricing Analysis
Industrial OEM buyers anchor SaaS-tiered subscription structures across the market. Pricing stratifies across enterprise experience management suites, mid-market self-serve tiers, and freemium entry points based on integration depth and compliance certification levels. Cost compression in the self-serve segment intensifies as SurveyMonkey and Typeform compete for small business conversion, while FDA-validated healthcare modules sustain premium positioning with minimal price sensitivity among pharmaceutical sponsors.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for survey infrastructure hardware dependencies. Software development concentrates in India, the United States, and Ireland, with cloud compute capacity drawing from AWS, Azure, and Google Cloud regions. Single-source vulnerability in natural language processing model providers creates downstream concentration risk. Distribution runs through direct enterprise sales teams, self-serve web funnels, and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in early-cycle expansion as EU AI Act compliance deadlines force enterprise upgrade cycles across legacy sentiment analysis installations, creating sustained replacement demand through the projection horizon.
For Market Incumbents: Harden compliance infrastructure investments against EU AI Act enforcement timelines to defend enterprise renewal rates. Deepen ISO 27001 certification coverage across secondary European markets before BSI audit backlogs extend. Acquire voice-response accessibility specialists to preempt regulatory mandates for elderly and disabled respondent channels.
For New Entrants and Emerging Players: Establish a beachhead in India's academic remote learning segment where semesterly procurement cycles and PLI scheme cost advantages reduce customer acquisition costs. Target voice-response convergence features for healthcare accessibility compliance as a differentiated entry vector against established cloud-native platforms.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-anchored SaaS play because regulatory fragmentation across FDA, EU AI Act, and BSI jurisdictions creates durable moats around certified analytics infrastructure. Target acquisition candidates with validated patient-reported outcome modules and existing FDA 21 CFR Part 11 documentation. Watch CSRD mandate expansion across EU-headquartered multinationals as the signal for ESG-focused survey module demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Upgrade | Forces algorithmic transparency investments ahead of enforcement deadlines in France and Germany. |
| Healthcare Vertical Acquisition | Captures FDA-validated patient-reported outcome modules for pharmaceutical sponsor procurement. |
| Voice-Response Feature Development | Opens accessibility-compliant channels for elderly respondents under METI and EU disability mandates. |
| API-First Architecture Migration | Enables enterprise data science teams to self-configure integrations, displacing managed services. |
| India PLI Scheme Expansion | Creates cost-advantaged development centers serving Asia-Pacific healthcare and education verticals. |
Study Parameters
Operator-level perspectives from CTOs at enterprise technology firms, IT procurement officers in healthcare systems, platform engineers at academic institutions, and integration specialists at systems integrators anchored the qualitative base. Secondary validation drew from SEC SaaS company filings, EU AI Act implementation guidance documents, FDA patient-reported outcome guidance, and hyperscaler capex disclosures. Bottom-up deployment volume estimates triangulated against top-down addressable market calculations across cloud, on-premise, and hybrid architectures.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling deployment mode, organization size, vertical end-use, integration complexity, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from historical licensing velocity patterns and forward procurement pipeline indicators, with specific inputs including EU AI Act compliance investment schedules and academic semesterly procurement calendars.
Sensitivities concentrate around EU AI Act enforcement timing, FDA guidance revisions on clinical trial instruments, and cross-border data localization rule changes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Construction Suites Software Market
Software & Services
MCAD Software Market
Software & Services
Global Data Warehouse Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
North America Automotive Software Market
Software & Services
Agile Application Life-Cycle Management Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Compositing Software Market
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Global Android Kiosk Software Market