
 Russia Data Center Rack Market | 2026-2036
Russia Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Data Center Rack Market Insights
Direct procurement channels between rack manufacturers and hyperscale facility operators is rewriting supply relationships across Russia's data center construction pipeline. Rittal GmbH & Co. KG leverages its modular enclosure expertise to dominate turnkey rack integration projects for Tier III facilities. Schneider Electric SE anchors its position through integrated power and cooling rack architectures that reduce field assembly time. YADRO competes aggressively on domestic content requirements, sourcing steel frames from Russian mills to satisfy public-sector procurement rules.
A data center rack is a standardized metal framework, typically conforming to 19-inch EIA-310-D specifications, designed to mount servers, switches, and power distribution units in vertically stacked configurations with defined unit heights. Steel remains the dominant material for Russia's rack fabrication due to thermal load-bearing requirements and local supply chain availability, though aluminum gains traction in edge deployments where weight reduction matters. Enclosed rack types command premium positioning as operators prioritize physical security and airflow containment for high-density GPU clusters. Liquid cooling rack configurations represent the fastest-growing segment, driven by thermal design power thresholds exceeding 500 watts per processor in AI training infrastructure.
Russia's Federal Law No. 242-FZ on data localization and FSTEC certification requirements for information security shape rack procurement specifications, mandating tamper-evident designs and electromagnetic shielding in government-adjacent facilities. BIS-equivalent technical regulations and GOST-R conformity assessment procedures govern structural load ratings and fire resistance standards for rack assemblies deployed in certified data centers. Stakeholders must monitor how evolving sanctions frameworks affect component sourcing for cooling systems and power distribution accessories, as supply continuity directly impacts rack build-out schedules for planned facilities.
Market Dynamics
Federal Law No. 242-FZ mandates domestic data storage, forcing foreign cloud operators to localize infrastructure and reshaping procurement patterns for rack assemblies across Moscow and St. Petersburg facilities.
Growth Catalysts
- Data Localization Mandates:Federal Law No. 242-FZ compels foreign platforms to establish Russian data centers, creating sustained rack demand from compliance-driven construction projects.
- AI Training Clusters:Hyperscale GPU deployments for machine learning workloads require liquid-cooled rack configurations with thermal densities exceeding traditional air-cooled limits.
- Government Cloud Expansion:Public-sector digitalization programs in Moscow drive FSTEC-certified rack procurement for secure federal data processing facilities.
Market Restraints
- Cooling Component Sourcing:Sanctions frameworks restrict access to precision cooling pumps and heat exchangers from Western suppliers, extending lead times for liquid-cooled rack builds.
- Steel Price Volatility:Domestic mill capacity fluctuations and import substitution costs elevate frame material expenses for rack fabricators serving price-sensitive colocation operators.
- Technical Talent Bottleneck:Shortage of certified thermal engineers capable of designing 500W+ per-processor liquid cooling architectures delays facility commissioning timelines.
Strategic Opportunities
- Edge Rack Deployment:Lightweight aluminum rack configurations for distributed edge nodes in Siberian industrial zones address latency requirements for remote mining and energy operations.
- Domestic Content Incentives:Public procurement rules favoring Russian-sourced steel frames create captive demand channels for local fabricators meeting GOST-R structural standards.
- Integrated Power-Convergence:Rack-level microgrids combining Schneider Electric power distribution with battery backup units reduce field wiring complexity for rapid facility scaling.
Industry Challenges
- FSTEC Certification Timelines:Extended security approval processes for tamper-evident rack designs delay revenue recognition on government-adjacent projects.
- Legacy Facility Retrofit Complexity:Integrating liquid cooling manifolds into existing air-cooled halls requires structural reinforcement and floor loading assessments that compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Data Center Rack Market |
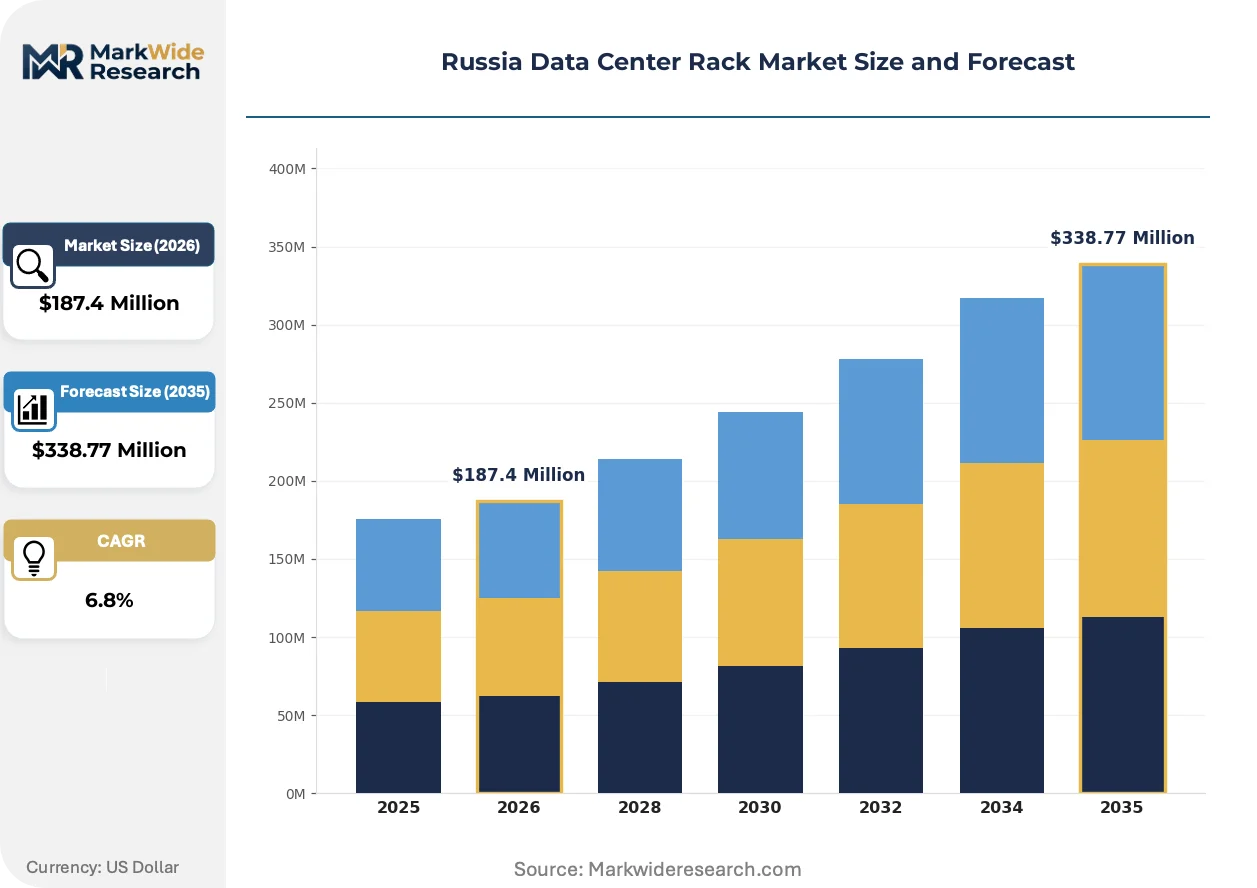
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rack Type: Open Frame, Enclosed, Low Profile, High Density Material: Steel, Aluminum, Plastic, Carbon Fiber Weight Capacity: Heavy-Duty, Medium-Duty, Lightweight, Ultra-Lightweight Cooling Solution: Air Cooling, Liquid Cooling, Passive Cooling, Hybrid System |
| Companies Covered | Rittal GmbH & Co. KG, Schneider Electric SE, Vertiv Group Corp., Eaton Corporation plc, Huawei Technologies Co., Ltd., Delta Electronics Inc., Hewlett Packard Enterprise Co., YADRO, Systeme Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Data Center Rack Market Trends and Innovations
Rack architecture is converging with thermal and power management systems, compressing the traditional separation between enclosure, cooling, and electrical infrastructure into unified factory-integrated assemblies.
Software-defined power distribution is virtualizing rack-level energy management. Hyperscale operators deploy intelligent PDUs with outlet-level metering and remote switching capabilities. This technology is virtualizing the traditional boundary between facility electrical infrastructure and IT equipment, enabling dynamic workload placement based on real-time thermal and power availability.
FSTEC certification requirements under Russia's information security framework now mandate electromagnetic shielding and physical tamper evidence for government-adjacent rack deployments. These specifications elevate manufacturing complexity and exclude uncertified foreign suppliers from public-sector procurement channels. Domestic fabricators with established security clearance relationships capture disproportionate share of federal cloud construction programs.
Direct manufacturer-to-operator contracting is displacing traditional distributor channels for large-scale rack procurements. Colocation and hyperscale buyers in Moscow negotiate frame specifications, cooling integration, and power distribution as unified packages with Rittal and domestic specialists. This compression of the value chain reduces margin capture by intermediaries and accelerates specification-to-delivery cycles for planned facility expansions.
Russia Data Center Rack Market Segmentation
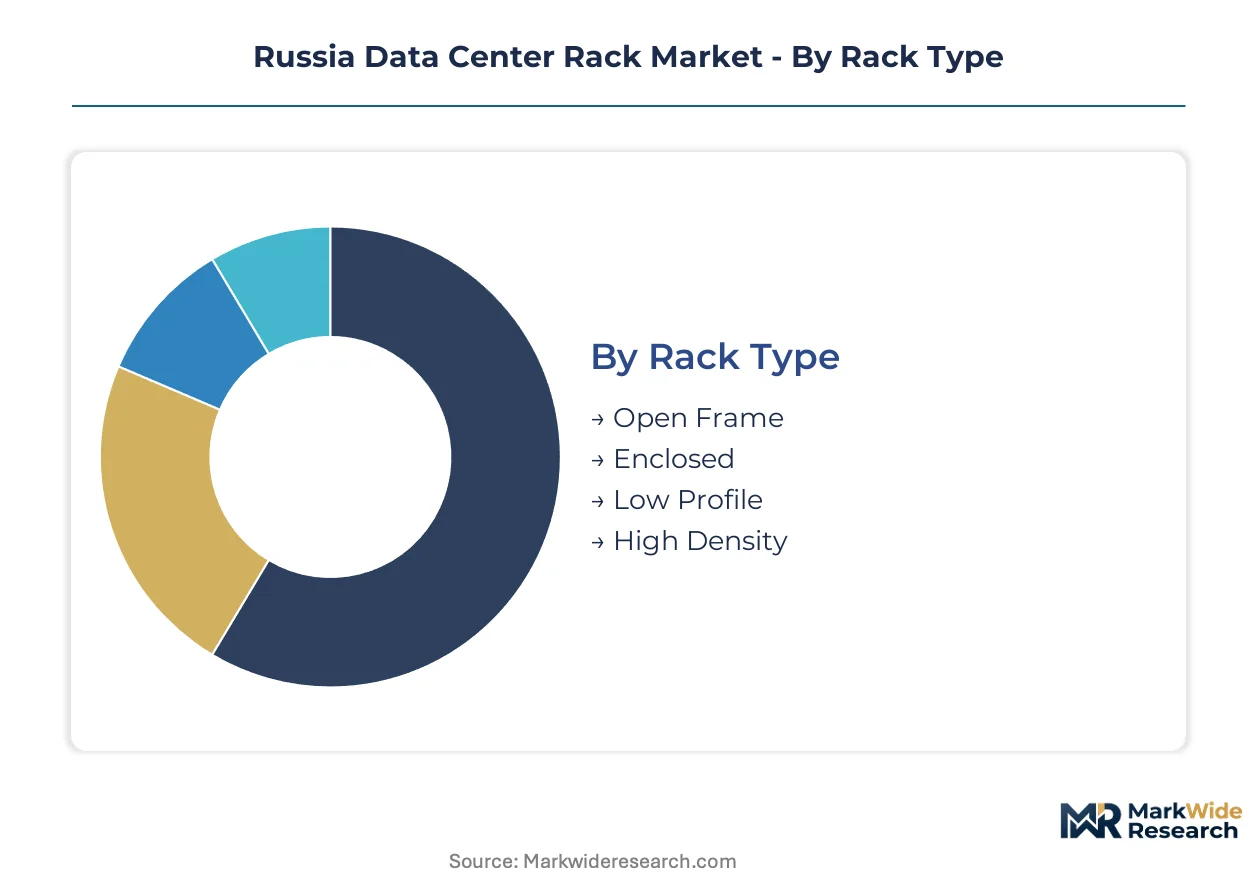
Rack specification decisions cascade through facility design, thermal performance, and compliance certification timelines. Procurement teams weigh material sourcing constraints against density targets and FSTEC security requirements when selecting configurations for Moscow and St. Petersburg deployments.
Rack Type:
After-sales-service intensity varies sharply across enclosure architectures, with liquid-cooled integrated systems demanding specialized thermal engineering support while open-frame units require minimal field intervention.
- Enclosed:Factory-integrated airflow containment with lockable side panels and electromagnetic shielding satisfies FSTEC tamper-evidence mandates for federal cloud facilities. Demand concentrates in Tier III Moscow colocation builds where GPU density exceeds 30kW per rack.
- High Density:Reinforced frame structures support liquid cooling manifolds and busbar power distribution for AI training clusters. St. Petersburg hyperscale campuses specify these for thermal loads surpassing 500W per processor.
- Open Frame:Standardized 19-inch EIA-310-D frames without side panels suit cost-sensitive enterprise server rooms with moderate thermal loads.
- Low Profile:Compact 24U and below configurations fit constrained floorplates in legacy Moscow office building retrofits.
By volume, Open Frame leads. By growth pace, High Density is ahead.
Material:
Cost tier stratification separates commodity structural grades from premium lightweight alloys, with domestic content rules reshaping supplier qualification.
- Steel:Hot-rolled and cold-formed carbon steel dominates Russian fabrication due to mill proximity and GOST-R structural certification pathways. Yekaterinburg and Chelyabinsk mills supply frames for 80% of Moscow metropolitan deployments.
- Aluminum:Extruded 6061-T6 and 6063-T5 alloys reduce shipping weights for Siberian edge nodes where remote logistics elevate freight costs. Novosibirsk industrial zones specify these for mining automation infrastructure.
- Plastic:Glass-reinforced polycarbonate enclosures serve temporary and mobile edge deployments with minimal electromagnetic shielding requirements.
- Carbon Fiber:Advanced composite frames target military-adjacent facilities where weight reduction and RF shielding justify premium procurement.
Steel commands the installed base. Aluminum gains share fastest in distributed architectures.
Weight Capacity:
Application-driven selection maps compute density to structural load ratings, with GPU-heavy AI clusters forcing upgrades from legacy medium-duty specifications.
- Heavy-Duty:1,500kg+ static load ratings accommodate liquid cooling infrastructure and high-capacity battery backup integration. Tier III Moscow facilities mandate these for 42U+ GPU rack configurations.
- Medium-Duty:800-1,200kg ratings serve standard air-cooled server deployments in enterprise and colocation environments with conventional power densities.
- Lightweight:400-800kg capacities suit edge computing nodes and network equipment racks with limited server payload.
- Ultra-Lightweight:Sub-400kg specifications enable rapid deployment scenarios and temporary installations with minimal floor loading.
Medium-Duty retains volume leadership. Heavy-Duty climbs fastest on AI infrastructure demand.
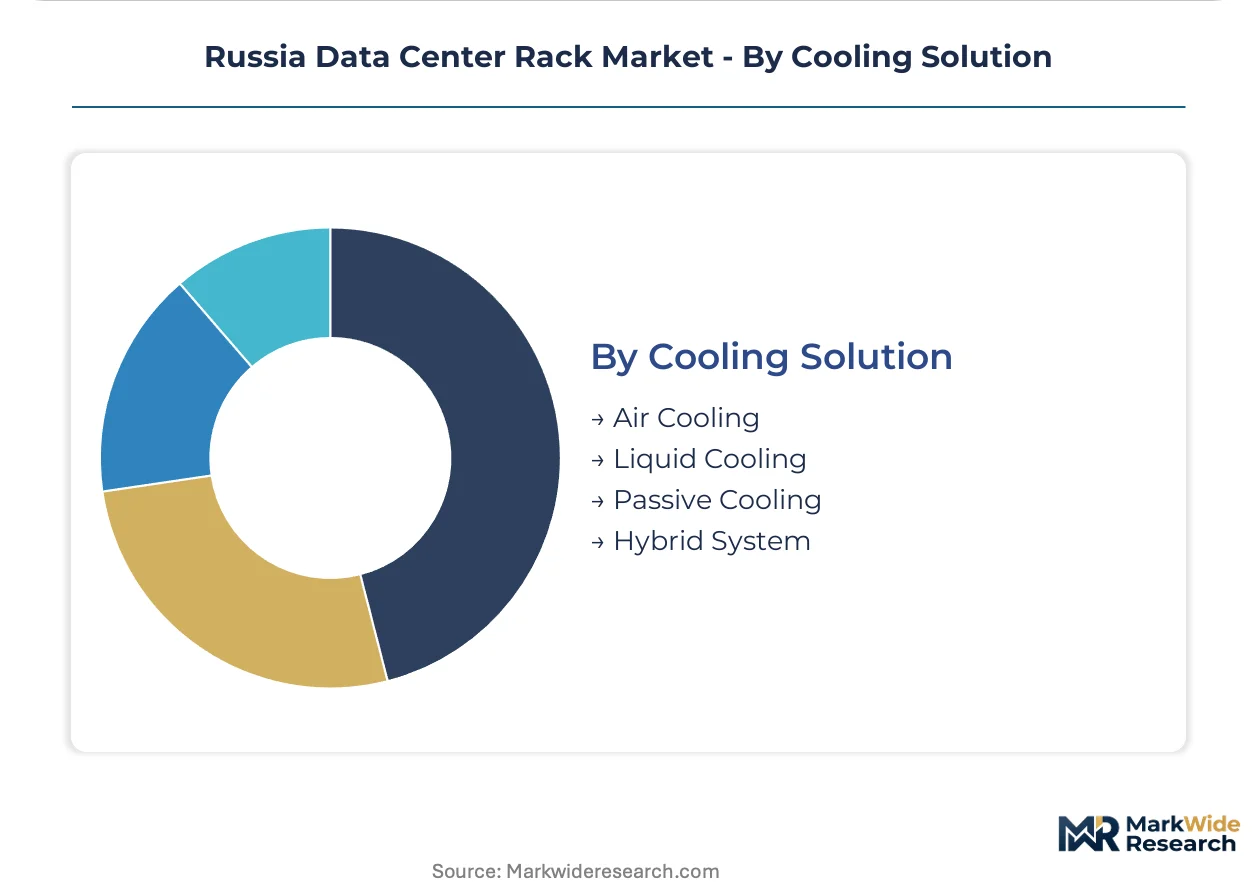
Cooling Solution:
Customer type divides procurement between hyperscale liquid cooling adopters and conservative air-cooled enterprise refresh cycles.
- Liquid Cooling:Direct-to-chip and immersion configurations manage thermal design power exceeding 500W per processor. Sber and Yandex deploy these in Moscow Region AI training facilities despite extended lead times for precision pump sourcing.
- Air Cooling:Perforated door and aisle containment architectures remain standard for sub-15kW rack densities in enterprise and government facilities with established CRAC infrastructure.
- Hybrid System:Combined liquid-to-air heat exchangers bridge legacy and next-generation thermal architectures during facility transition phases.
- Passive Cooling:Natural convection and heat sink configurations serve low-power edge devices and network equipment in thermally constrained environments.
Air Cooling dominates current installations. Liquid Cooling expands most quickly on hyperscale GPU deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSTEC certification requirements and Federal Law No. 242-FZ data localization mandates anchor rack procurement patterns across Russian metropolitan clusters. Facility construction concentrates where government cloud projects and financial services latency requirements intersect.
Moscow Metropolitan Area
Sber and Yandex hyperscale campuses drive liquid-cooled rack specifications for AI training clusters exceeding 500W per processor. Moscow's Tier III colocation builds absorb 60% of national heavy-duty rack volume. The Skolkovo Innovation Center hosts domestic fabricator integration facilities serving federal cloud contractors.
St. Petersburg
Northwestern Russia's financial services hub demands tamper-evident enclosed racks for FSTEC-compliant data processing. Foreign cloud operators localize infrastructure here to satisfy Federal Law No. 242-FZ mandates. The city's historic building stock forces low-profile 24U configurations in retrofit deployments.
Novosibirsk Industrial Zone
Siberian mining automation and energy operations specify lightweight aluminum racks to reduce remote logistics costs. Edge computing nodes for latency-sensitive industrial control systems cluster along the Trans-Siberian rail corridor. Regional fabricators source extruded 6061-T6 alloys from local metallurgical plants.
Yekaterinburg-Chelyabinsk Corridor
Domestic steel mills supply 80% of carbon steel frames for Moscow metropolitan deployments. Ural Federal District metalworking capacity supports GOST-R structural certification pathways for public-sector procurement. Local fabricators compete on domestic content compliance for government-adjacent rack contracts.
Russia Data Center Rack Market Competitive Landscape
Integrated solution providers and domestic specialists split the market along certification and sourcing vectors. Rittal GmbH & Co. KG leverages modular enclosure expertise for turnkey Tier III facility integration. Schneider Electric SE anchors positioning through converged power-cooling architectures that compress field assembly timelines. Strategic moves center on direct manufacturer-to-operator contracting and domestic content qualification for public procurement channels.
Among Germany-based integrated infrastructure providers, Rittal GmbH & Co. KG occupies a position exemplifying turnkey rack system delivery. Schneider Electric SE, a France-based multinational, represents the power-convergence archetype through factory-integrated electrical and thermal assemblies. YADRO, a Russian entity, anchors the domestic content tier by sourcing steel frames from local mills to satisfy GOST-R and public-sector procurement requirements.
| Leading Market Players |
|---|
| Rittal GmbH & Co. KG |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corporation plc |
| Huawei Technologies Co., Ltd. |
| Delta Electronics Inc. |
| Hewlett Packard Enterprise Co. |
| YADRO |
| Systeme Electric |
| Others |
Pricing and Supply Chain Analysis
Sanctions exposure on precision cooling components determines both pricing tier spreads and supply chain shape across Russia's data center rack market. Steel frame procurement from domestic mills anchors cost structures, while liquid cooling pump sourcing constraints compress margins on high-density configurations.
Pricing Analysis
Configured-to-order pricing for FSTEC-certified enclosed racks commands substantial premiums over standard open-frame units. Pricing stratifies across premium liquid-cooled integrated systems, standard air-cooled enclosed racks, and economy open-frame configurations. Cost compression in standard tiers intensifies because Yekaterinburg mill capacity fluctuations elevate steel input expenses. Colocation operators exhibit highest price sensitivity, while Sber and Yandex absorb premiums for AI-optimized thermal architectures.
Supply Chain Analysis
Hot-rolled steel feedstock draws from Yekaterinburg and Chelyabinsk mills, with extruded aluminum alloys sourced from Novosibirsk metallurgical plants. Precision cooling pumps and heat exchangers rest on constrained import channels subject to Western trade restrictions. Single-source vulnerability concentrates in liquid cooling component procurement, where alternative supplier qualification extends facility build timelines. Distribution runs through direct manufacturer-to-operator contracting for hyperscale deployments, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of FSTEC-certified thermal engineers capable of designing 500W+ per-processor liquid cooling architectures constrains facility commissioning velocity and compresses project margins for complex rack integrations.
For Market Incumbents: Entrench FSTEC certification relationships with federal cloud contractors to defend against domestic fabricators exploiting public procurement content rules. Deepen captive supply of precision cooling manifolds through backward integration into Russian-qualified component sourcing, insulating project timelines from sanctions-driven lead time volatility. For New Entrants and Emerging Players: Establish a beachhead in lightweight aluminum edge rack configurations for Siberian mining automation nodes, where remote logistics costs create pricing power unavailable in Moscow's saturated Tier III market. Penetrate through Novosibirsk-based metallurgical partnerships that satisfy domestic content requirements without competing head-to-head against Rittal's turnkey integration dominance. For Investors and Strategic Acquirers: Federal Law No. 242-FZ enforcement milestones reshape the acquisition landscape by mandating localized infrastructure that foreign operators cannot bypass. Target vertically integrated fabricators with established GOST-R certification pathways and security clearance relationships. Watch FSTEC approval timeline acceleration as the signal indicating federal cloud construction program scaling.| Strategic Initiative | Industry Significance |
|---|---|
| FSTEC Certification Investment | Security clearance relationships unlock federal cloud procurement channels excluded from foreign competitors. |
| Domestic Steel Integration | Captive supply from Yekaterinburg mills satisfies public-sector content rules and insulates margin from import substitution costs. |
| Liquid Cooling Partnership | Technology licensing agreements with pump manufacturers compress lead times for AI training cluster deployments. |
| Edge Rack Product Line | Lightweight aluminum configurations address latency requirements in Siberian industrial zones beyond Moscow saturation. |
| Direct Operator Contracting | Bypassing distributor channels accelerates specification-to-delivery cycles for hyperscale facility expansions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center construction directors, thermal engineering leads, FSTEC certification officers, and procurement managers at colocation operators; and secondary validation through customs records, GOST-R conformity assessment databases, federal procurement disclosures, and hyperscaler capex filings. Bottom-up rack shipment estimates triangulated against top-down facility construction pipeline data.
Forecast inputs span rack type, material grade, cooling solution, weight capacity, and regional deployment cluster across the analysis window. CAGRs derive from facility commissioning timelines, localization mandate compliance trajectories, and thermal density evolution in AI infrastructure. Modeled sensitivities incorporate sanctions framework adjustments and domestic mill capacity utilization swings.
Sensitivities concentrate around precision cooling component sourcing continuity and FSTEC certification timeline volatility. Forecasts reflect assumptions on regulatory enforcement intensity and steel price normalization pathways. Cross-checking against federal cloud construction program budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
South Korea Data Center Physical Security Market