
 France Data Center Storage Market | 2026-2036
France Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Storage Market Insights
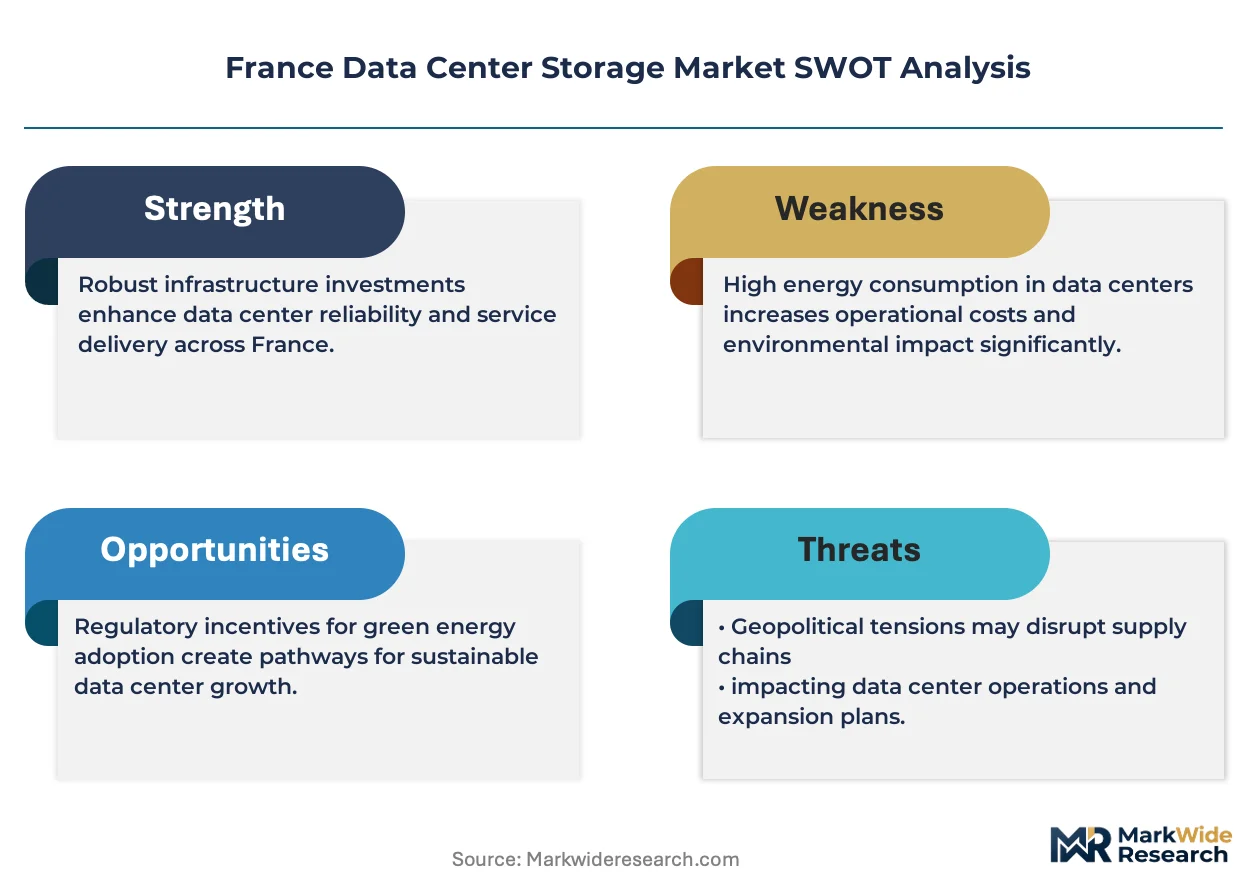
Power-purchase agreements and green leasing structures are reconfiguring capital deployment in French data center storage. Dell Technologies leverages its direct sales force and on-premises integration capabilities to anchor enterprise accounts in Île-de-France. OVHcloud sustains its domestic cloud sovereignty positioning through vertically integrated server and storage operations. Huawei Technologies competes on price-performance in flash arrays despite facing procurement scrutiny under EU cybersecurity frameworks.
France data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention, typically measured in IOPS, latency under five milliseconds, and petabyte-scale rack density. These systems serve transactional databases, AI training corpora, and regulatory archives across cloud and enterprise environments. Flash storage commands premium positioning for latency-sensitive workloads, while hybrid storage architectures bridge on-premises compliance requirements with cloud elasticity. Object storage underpins unstructured data growth in telecommunications and healthcare, where retention mandates stretch across decades.
ANSM cybersecurity guidelines for health data, CSRD sustainability disclosure rules, and GDPR localization requirements collectively shape procurement specifications and facility certification in France. The national regulator for digital infrastructure enforces energy efficiency standards that favor liquid-cooled, high-density storage deployments. Stakeholders must weigh sovereign cloud obligations against total cost of ownership when selecting between domestic colocation and hyperscale off-premises alternatives.
Market Dynamics
France's data center storage sector is reconfiguring around sovereign infrastructure mandates and AI workload density requirements. The EU AI Act and national cloud strategy are forcing procurement decisions that privilege domestic colocation over hyperscale alternatives, while liquid-cooled flash arrays absorb capital previously allocated to legacy disk expansion.
Growth Catalysts
- GDPR Localization:Data residency requirements under French CNIL enforcement are compelling financial services and healthcare providers to expand on-premises and domestic colocation storage capacity rather than rely on cross-border cloud infrastructure.
- AI Training Corpora:Generative AI development pipelines in Paris-Saclay and Sophia Antipolis clusters are generating petabyte-scale unstructured data retention needs that favor high-IOPS flash and object storage architectures.
- CSRD Disclosure Mandates:Corporate sustainability reporting rules are accelerating replacement of energy-intensive legacy disk arrays with liquid-cooled, high-density solid-state systems in Île-de-France facilities.
Market Restraints
- NAND Flash Supply Concentration:French buyers remain exposed to Asian semiconductor fabrication bottlenecks, with Samsung, SK Hynix, and Kioxia controlling wafer output and dictating quarterly pricing volatility for enterprise SSD procurement.
- EU Cybersecurity Certification Friction:The Cybersecurity Act's Common Criteria evaluation timelines add 12-18 months to storage array approval cycles, delaying deployment of non-EU equipment in defense and critical infrastructure sectors.
- Power Grid Density Limits:RTE grid interconnection constraints in Greater Paris prevent rapid expansion of high-wattage storage facilities, forcing developers toward secondary cities with available substation capacity.
Strategic Opportunities
- Secondary City Colocation:Lyon, Marseille, and Lille offer undeveloped power substations and lower land costs for edge storage deployments serving latency-sensitive manufacturing and autonomous vehicle data processing.
- Healthcare Archive Modernization:ANSM mandates for 30-year pharmaceutical trial retention are driving replacement of tape-based archives with compliant object storage systems featuring WORM immutability and audit logging.
- Heat Reuse Integration:District heating network partnerships in Paris and Grenoble enable storage facilities to monetize waste heat from high-density arrays, transforming energy cost centers into revenue streams.
Industry Challenges
- Liquid Cooling Technician Scarcity:The specialized plumbing, coolant chemistry, and leak-detection expertise required for direct-to-chip storage cooling exceeds current French vocational training output, inflating installation costs and maintenance response times.
- Legacy SAN Migration Complexity:Financial institutions running 15-20 year-old Fibre Channel infrastructures face multi-year parallel operation periods during flash array cutover, doubling capital exposure and operational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Storage Market |
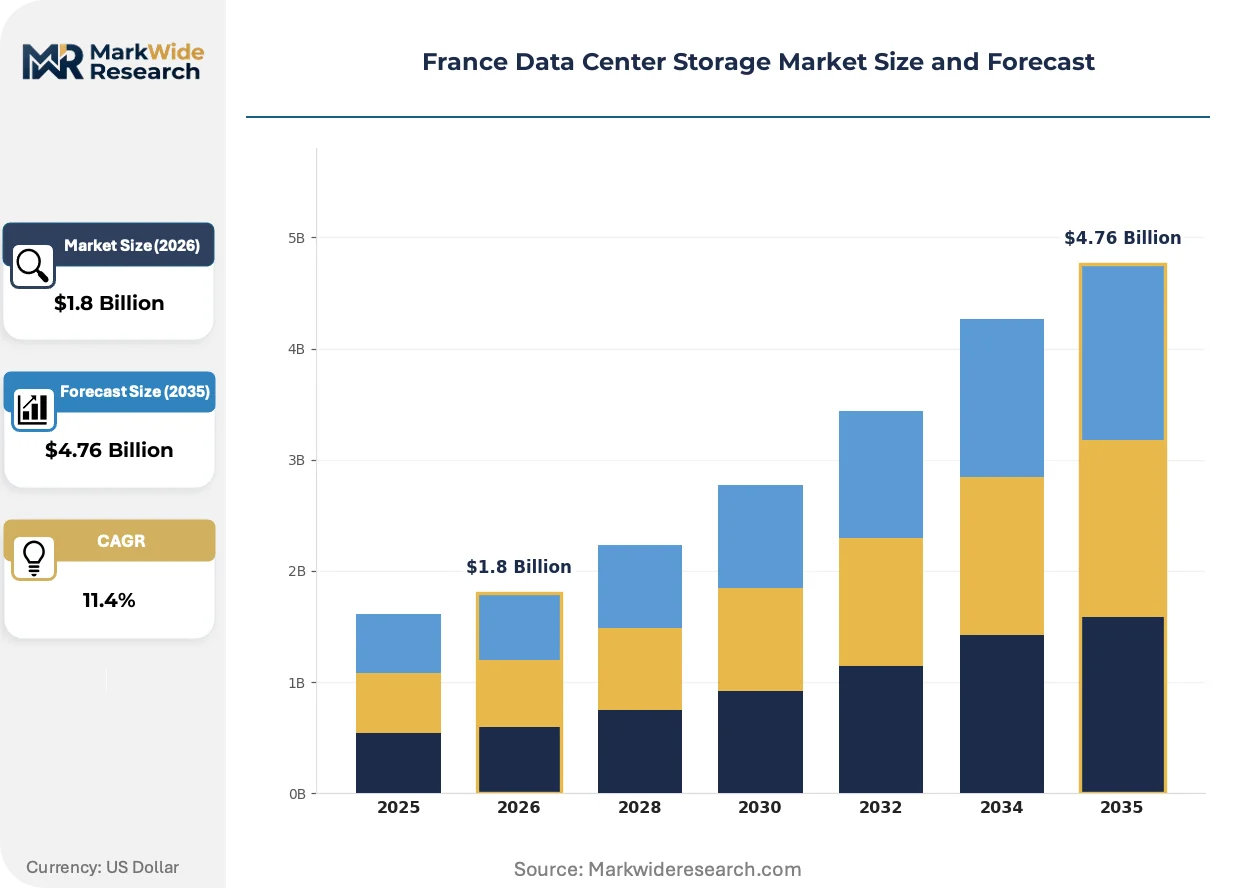
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk Storage, Tape Storage, Cloud Storage, Flash Storage Technology: NAS, SAN, Object Storage, Hybrid Storage Deployment: On-Premises, Off-Premises, Cloud-based, Colocation End User: IT Services, BFSI, Healthcare, Telecommunications |
| Companies Covered | NetApp, Atos, Dell Technologies, Huawei Technologies, Seagate Technology, Hewlett Packard Enterprise, OVHcloud, Orange Business Services, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Storage Market Trends and Innovations
Storage virtualization and software-defined architectures are dissolving hardware boundaries in French enterprise deployments. Regulatory pressure on data sovereignty and energy efficiency is accelerating architectural decisions that were previously deferred across budget cycles.
Computational storage drives with onboard processing capability are virtualizing data reduction and encryption functions that previously consumed host CPU cycles. Telecommunications operators in France are deploying these devices at scale for 5G core network analytics, compressing rack footprints by eliminating separate server tiers for data-intensive workloads. This consolidation is virtualizing the traditional separation between compute and storage infrastructure in edge locations.
France's transposition of the EU AI Act creates mandatory risk classification for storage systems handling high-risk AI training data, with CNIL oversight extending to model weights and intermediate checkpoints. Equipment vendors must now document data lineage capabilities and explainability audit trails in product specifications. Healthcare and public sector procurement is responding by mandating EU-manufactured or certified arrays with verifiable supply chain documentation.
Buyers are consolidating vendor relationships and demanding unified management platforms across on-premises and sovereign cloud storage tiers. Large French enterprises previously running 8-12 separate storage silos are reducing to 2-3 strategic supplier agreements with API-integrated orchestration layers. This concentration is most visible in banking and insurance, where procurement teams prioritize operational simplicity over best-of-breed point solutions.
France Data Center Storage Market Segmentation
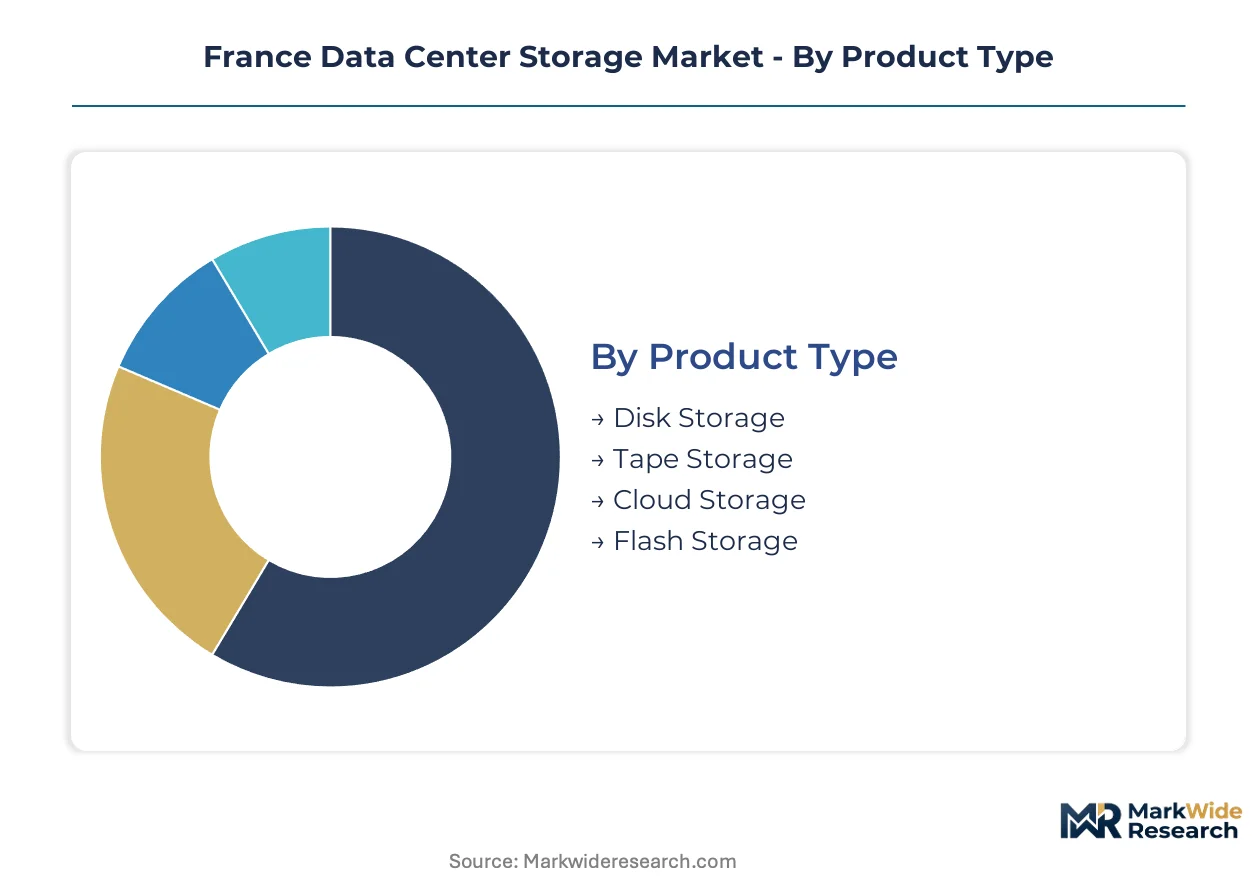
Storage procurement in France fragments across multiple technical and operational dimensions. Buyers weigh sovereignty mandates against performance requirements, while deployment location decisions increasingly involve CNIL compliance and CSRD energy disclosure obligations.
Product Type:
After-sales service intensity varies dramatically across storage media, with flash arrays demanding specialized firmware support and tape systems requiring periodic drive maintenance contracts.
- Flash Storage:Solid-state arrays built on NAND technology deliver sub-millisecond latency for transactional databases and AI inference workloads. Paris-Saclay research clusters and Île-de-France financial clearinghouses are absorbing petabyte-scale deployments despite NAND supply concentration among Korean and Japanese fabricators.
- Cloud Storage:Hyperscale object and block services accessed via API enable elasticity for unpredictable workload spikes. French enterprises under GDPR Article 44 restrictions are migrating toward OVHcloud and domestic sovereign cloud alternatives rather than US-based providers.
- Disk Storage:Rotating media retains cost advantages for warm archival tiers in healthcare and telecommunications retention pools.
- Tape Storage:Linear tape-open systems persist for ANSM-mandated pharmaceutical trial archives requiring 30-year immutability.
Flash storage holds the largest share; momentum sits with cloud storage.
Technology:
Architectural choices in French data centers increasingly hinge on API interoperability and unified management plane availability.
- Object Storage:Flat namespace architectures scale to exabyte capacity for unstructured data lakes and 5G network analytics. Marseille and Lyon edge facilities are deploying these systems for autonomous vehicle data ingestion pipelines.
- Hybrid Storage:Tiered architectures automate data placement across flash, disk, and cloud layers based on access patterns. CSRD disclosure pressures are accelerating replacement of homogeneous disk farms with these energy-optimized configurations in Greater Paris facilities.
- NAS:File-level access protocols serve departmental shares and media rendering workflows.
- SAN:Block-level Fibre Channel fabrics persist in legacy banking core systems undergoing multi-year migration timelines.
Object storage dominates new capacity additions; hybrid architectures are climbing the fastest.
Deployment:
Facility location decisions in France now incorporate RTE grid interconnection availability and district heating partnership potential.
- Colocation:Third-party data centers in Lyon, Lille, and Marseille offer undeveloped substation capacity unavailable in Paris. Manufacturing firms and autonomous vehicle operators are targeting these secondary cities for latency-sensitive edge storage.
- On-Premises:Captive facilities within enterprise campuses maintain direct control over physical security and audit access. ANSM-regulated pharmaceutical laboratories and defense contractors mandate these deployments for controlled substance trial data.
- Cloud-based:Fully managed consumption models abstract infrastructure management to hyperscale operators.
- Off-Premises:Dedicated leased space in carrier-neutral facilities splits operational responsibility.
Colocation is expanding most quickly in secondary cities; on-premises retains dominance in regulated sectors.
End User:
Sector-specific retention mandates and latency requirements drive divergent procurement specifications across French industries.
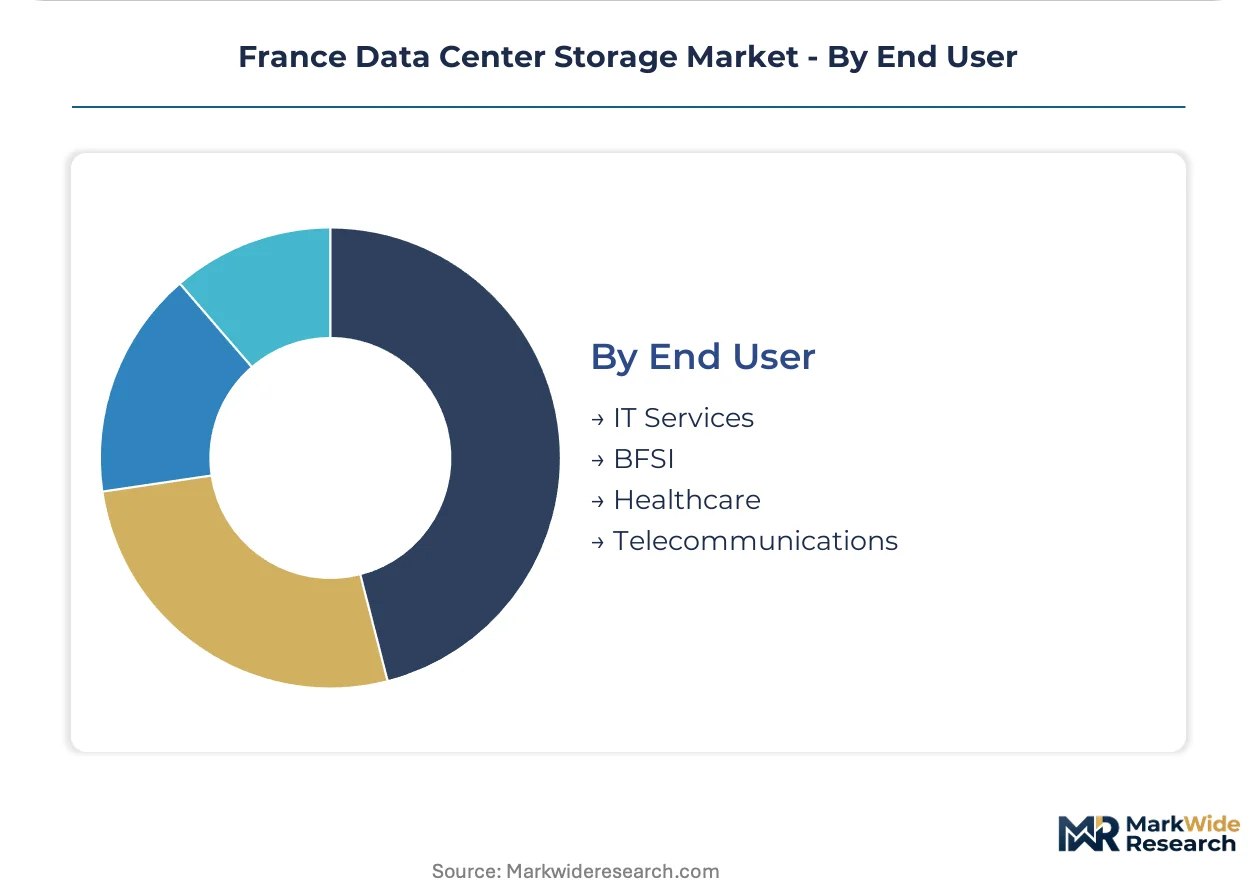
- BFSI:Payment card industry compliance and real-time fraud detection demand millisecond-class response from all-flash primary storage. ACPR oversight combined with GDPR localization is blocking cross-border cloud migration for core banking systems.
- Healthcare:Electronic patient records, medical imaging archives, and pharmaceutical trial data span performance tiers from flash to tape. ANSM cybersecurity guidelines and 30-year retention rules are modernizing hospital storage infrastructure toward compliant object systems.
- IT Services:Managed service providers aggregate multi-tenant workloads across heterogeneous client requirements.
- Telecommunications:5G core network functions and subscriber data management generate petabyte-scale unstructured retention needs.
BFSI commands premium pricing tiers; healthcare shows the steepest modernization trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France data center storage infrastructure draws heavily on semiconductor imports from Asian fabricators, while domestic colocation services and sovereign cloud platforms represent growing exportable expertise within the European single market.
Île-de-France
Paris-Saclay research clusters and La Défense financial clearinghouses absorb petabyte-scale flash deployments for AI training and real-time fraud detection. CNIL enforcement of GDPR Article 44 restricts cross-border data flows, compelling BFSI institutions toward domestic colocation expansion. RTE grid interconnection constraints in Greater Paris now push developers toward liquid-cooled, high-density configurations rather than footprint expansion.
Auvergne-Rhône-Alpes
Lyon's undeveloped power substations attract edge storage deployments serving autonomous vehicle data processing and manufacturing IoT streams. The region's district heating network partnerships enable waste heat monetization from high-density arrays, transforming energy costs into revenue. Saint-Étienne and Grenoble technical institutes supply specialized liquid cooling technicians scarce elsewhere in France.
Provence-Alpes-Côte d'Azur
Sophia Antipolis technology clusters generate substantial unstructured data retention needs for generative AI development pipelines. ANSM cybersecurity guidelines for pharmaceutical trial data drive compliant object storage modernization in Marseille's healthcare research facilities. The Aix-Marseille metropolitan area offers lower land costs and available substation capacity absent from Paris.
Hauts-de-France
Lille's proximity to Benelux markets positions the region for cross-border colocation serving latency-sensitive European financial networks. CSRD sustainability disclosure rules accelerate replacement of legacy disk farms with energy-optimized hybrid architectures. The former industrial basin's redundant power infrastructure accommodates high-wattage storage facilities constrained elsewhere.
France Data Center Storage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in flash memory and disk media fabrication. The France data center storage sector exhibits tiered concentration, with multinational equipment vendors anchoring enterprise accounts alongside domestic cloud operators capturing sovereign workloads. Three archetypes dominate: vertically integrated infrastructure platforms, component-centric storage media suppliers, and sovereign cloud service providers. Competitive dynamics center on strategic partnerships for liquid cooling integration and portfolio diversification into computational storage architectures.
Among US-based platform vendors, Dell Technologies and NetApp occupy positions anchoring enterprise flash and hybrid storage deployments across Île-de-France financial institutions. Huawei Technologies exemplifies price-performance competition in solid-state arrays despite facing procurement friction under EU cybersecurity certification frameworks. Domestic operator OVHcloud represents the sovereign cloud archetype, leveraging vertically integrated server and storage operations to capture GDPR-constrained workloads from public sector and healthcare clients.
| Leading Market Players |
|---|
| NetApp |
| Atos |
| Dell Technologies |
| Huawei Technologies |
| Seagate Technology |
| Hewlett Packard Enterprise |
| OVHcloud |
| Orange Business Services |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Seoul-Incheon NAND fabrication clusters dictate quarterly pricing volatility for French enterprise SSD procurement, with Samsung, SK Hynix, and Kioxia controlling wafer output and compressing margin negotiation space for domestic system integrators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in France data center storage. Price differentiation rests on certification grade under EU Cybersecurity Act Common Criteria and volume scale commitments from hyperscale operators. Cost compression in mid-tier flash arrays is intensifying because NAND supply concentration among Korean and Japanese fabricators limits procurement leverage. Healthcare and defense contractors show least price sensitivity due to ANSM and GDPR compliance mandates, while regional colocation providers face acute margin pressure from grid interconnection cost inflation.
Supply Chain Analysis
Foundry capacity concentrates with Samsung, SK Hynix, and Kioxia in South Korea and Japan, with secondary controller fabrication in Taiwan. French storage system assembly draws from NAND wafers, DRAM modules, and specialized cooling components sourced from Asian semiconductor hubs. Single-source vulnerability in advanced node NAND production creates exposure to geopolitical disruption and export control friction. Distribution runs through direct vendor relationships with enterprise accounts and channel partners serving mid-market colocation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France data center storage represents a high-growth disruption as EU AI Act risk classification mandates and liquid-cooling density requirements force architectural replacement cycles previously deferred across multiple budget periods.
For Market Incumbents: Insulate enterprise flash array margins by deepening captive supply relationships with certified Asian NAND fabricators, while accelerating liquid-cooling technician certification programs through Auvergne-Rhône-Alpes technical institutes to offset skills scarcity. Defend against OVHcloud's sovereign cloud capture by embedding API-native orchestration layers that bridge on-premises and domestic colocation tiers for GDPR-constrained financial services clients. For New Entrants and Emerging Players: Establish a beachhead in secondary city edge storage deployments across Lyon, Marseille, and Lille, where RTE grid constraints in Paris have shifted manufacturing IoT and autonomous vehicle data processing demand toward undeveloped substation capacity. Target heat reuse integration partnerships with district heating networks in Grenoble and Paris as a differentiated sustainability positioning against incumbent hardware vendors. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure sovereignty play because CNIL enforcement of GDPR Article 44 and national cloud strategy mandates structurally privilege domestic operators over hyperscale alternatives regardless of price-performance metrics. Acquisition candidates with vertically integrated server-storage operations and existing CNIL certification pathways command scarcity premia. Monitor EU Cybersecurity Act Common Criteria evaluation timeline acceleration as the signal for procurement friction normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration Partnership | Addresses technician scarcity in Île-de-France while enabling RTE grid-constrained density expansion. |
| Sovereign Cloud Certification Pathway | Captures GDPR-constrained healthcare and public sector procurement under CNIL oversight. |
| Secondary City Edge Deployment | Exploits Lyon and Marseille substation availability for latency-sensitive manufacturing workloads. |
| Heat Reuse Network Integration | Transforms Paris and Grenoble storage facilities from cost centers to district heating revenue contributors. |
| Computational Storage Architecture Launch | Eliminates separate server tiers for 5G core analytics at Orange and Bouygues Telecom edge locations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, CNIL regulatory guidance documents, and RTE grid interconnection databases. Conversations with data center facility managers, storage procurement officers at BFSI institutions, liquid cooling system integrators, and OVHcloud infrastructure planners informed demand-side validation. SEC filings from Dell Technologies and NetApp, alongside EU Cybersecurity Act implementation notices, provided supply-side triangulation. Bottom-up capacity installation tracking across Île-de-France, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur converged with top-down addressable market sizing.
Forecast inputs incorporate deployment model segmentation across on-premises, colocation, and cloud-based storage; technology tiers spanning flash, hybrid, object, and tape architectures; and end-use verticals including BFSI, healthcare, and telecommunications. CAGRs were derived from installed base replacement cycles, AI training corpus growth trajectories in Paris-Saclay and Sophia Antipolis clusters, and CSRD-mandated energy efficiency upgrade timelines across the analysis window. RTE grid constraint modeling and ANSM retention mandate compliance deadlines shaped regional adoption curve assumptions.
Sensitivities concentrate around NAND flash supply disruption from Korean-Japanese geopolitical friction, EU Cybersecurity Act certification timeline delays, and RTE grid interconnection approval backlogs in Greater Paris. Cross-checking against RTE's published substation capacity maps and CNIL enforcement action databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Global Data Colocation Market