
 New Jersey Data Center Market | 2026-2036
New Jersey Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
New Jersey Data Center Market Insights
Hyperscale certification tiers is bifurcating the New Jersey data center landscape into premium and standard offerings. Equinix Inc. anchors its position through interconnection density at its Secaucus campus, while Digital Realty Trust Inc. leverages powered shell developments to capture pre-leasing momentum. CoreWeave differentiates through GPU-dense deployments targeting generative AI training clusters.
A data center constitutes a purpose-built facility housing servers, storage systems, and networking equipment with redundant power distribution, precision cooling maintaining 18-27°C, and fiber cross-connects to multiple carriers. Colocation services command the deepest margin pools in New Jersey given constrained land and power availability near fiber-rich corridors. Edge computing deployments represent the fastest-expanding technology segment as financial services and healthcare end users push latency-sensitive workloads closer to population centers.
New Jersey's Board of Public Utilities and the state's Economic Development Authority shape facility economics through energy tax exemptions and sales tax relief on equipment. Local zoning boards and the New Jersey Department of Environmental Protection regulate noise, water usage, and diesel generator emissions that constrain expansion timelines. Stakeholders must monitor interconnection agreements with New York-area carriers and evolving state carbon disclosure rules that will reshape power procurement strategies.
Market Dynamics
AI training clusters are compressing power density requirements while New Jersey's constrained transmission infrastructure struggles to match hyperscale deployment timelines. Financial services firms now pre-lease capacity three years ahead of occupancy, fundamentally altering colocation economics.
Growth Catalysts
- State energy tax exemptions:New Jersey's Economic Development Authority waives sales tax on data center equipment purchases, reducing upfront capital burdens for hyperscale entrants. The incentive applies specifically to facilities exceeding 20 megawatts of critical load.
- Financial services AI adoption:Manhattan-based asset managers and trading firms are deploying GPU clusters for real-time risk modeling, driving demand for sub-10 millisecond latency to exchange matching engines.
- Submarine cable landings:Transatlantic fiber systems terminating in Wall Township and Manasquan provide diverse connectivity paths that bypass New York City congestion points entirely.
Market Restraints
- Transmission interconnection queues:PJM Interconnection's backlog for new substations extends 36-48 months in northern New Jersey, forcing developers to acquire existing industrial sites with spare utility capacity.
- Diesel generator emissions caps:New Jersey Department of Environmental Protection regulations limit annual runtime for backup generators, constraining Tier III and Tier IV certification pathways for new builds.
- Liquid cooling retrofit costs:Legacy facilities designed for 8-12 kilowatts per rack face prohibitive infrastructure overhauls to support 40+ kilowatt AI server densities.
Strategic Opportunities
- Edge computing at healthcare nodes:New Jersey's hospital network in Camden and Newark corridors requires localized processing for imaging AI and patient monitoring, creating distributed deployment points outside traditional colocation hubs.
- Renewable energy procurement aggregation:The state's community solar program allows data center operators to contract directly with solar developers, bypassing utility green tariff limitations.
- Cross-river fiber diversity:New cable builds under the Hudson River offer physically separated paths from Manhattan, enabling disaster recovery sites that satisfy financial regulator geographic separation mandates.
Industry Challenges
- Electrical trades specialization:Medium-voltage switchgear installation and commissioning for 34.5 kilovolt utility interconnections requires certified technicians that command premium wages in the tristate labor market.
- Hyperscale contract terms:Cloud providers demand 15-20 year lease structures with expansion rights and early termination clauses that compress developer equity returns and complicate project financing.
Report Scope
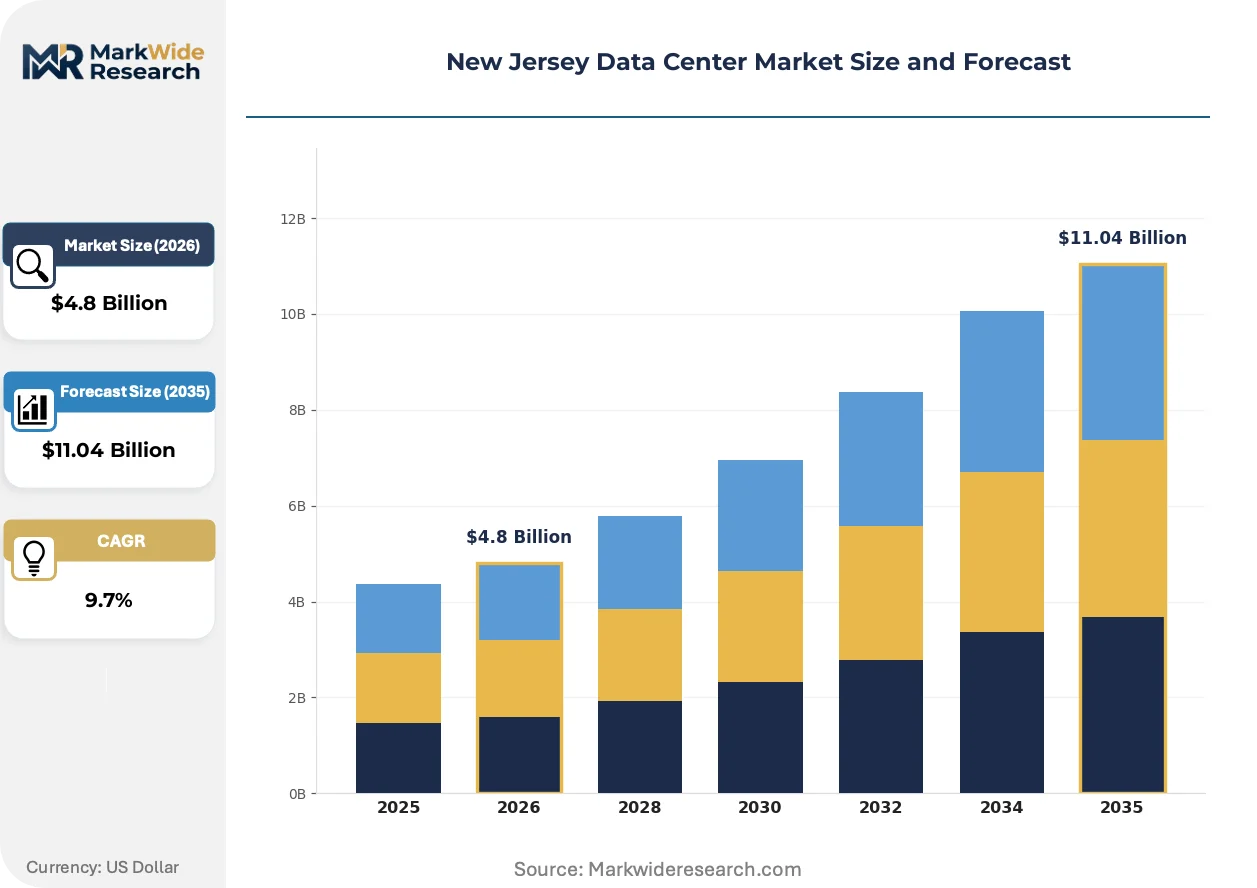
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Jersey Data Center Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Disaster Recovery, Cloud Services Deployment Model: On-Premises, Off-Premises, Hybrid, Multi-Cloud End User: Telecommunications, Financial Services, Healthcare, Retail Technology: AI Integration, Edge Computing, Virtualization, Networking |
| Companies Covered | Equinix Inc., Digital Realty Trust Inc., CoreSite Realty Corp., CyrusOne LLC, DataBank Holdings Ltd., Nebius Group NV, QTS Data Centers, CoreWeave, Iron Mountain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Jersey Data Center Market Trends and Innovations
Power architecture and cooling topology are diverging as AI workloads force facility designs to abandon legacy assumptions about rack density and redundancy tiers.
Direct liquid cooling is bifurcating the New Jersey data center landscape into premium and standard offerings. Cold plate and immersion systems enable 50-100 kilowatt rack densities required for NVIDIA H100 clusters. Financial services and research computing buyers are pre-committing to liquid-cooled suites at 40% lease premiums over air-cooled alternatives. This technology is bifurcating developer strategies between retrofit-constrained urban sites and greenfield campuses with purpose-built mechanical infrastructure.
New Jersey's Economic Development Authority sales tax relief on equipment shapes facility economics through multi-million dollar exemptions on generator sets, switchgear, and cooling plant investments. The program requires minimum capital expenditure thresholds that favor hyperscale deployments over mid-tier colocation builds. Developers are responding by consolidating multiple projects into single campus phases to trigger incentive eligibility.
Pre-leasing commitments now precede construction financing by 18-24 months as Manhattan financial firms secure capacity ahead of AI infrastructure rollouts. Traditional build-to-suit arrangements are displacing speculative development in the Meadowlands corridor. This pattern concentrates most visible in Secaucus and Piscataway, where fiber-rich utility corridors intersect with favorable zoning for heavy industrial power loads.
New Jersey Data Center Market Segmentation
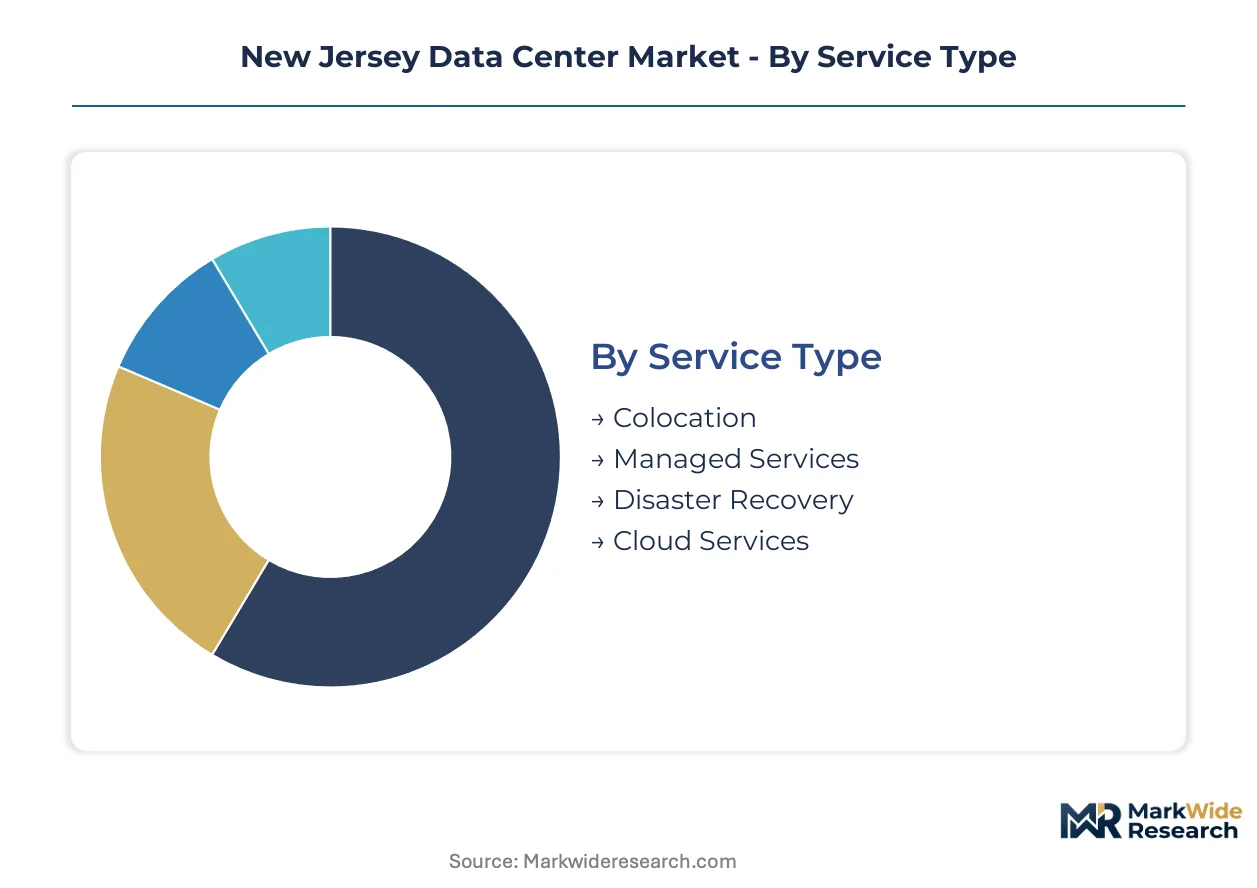
Segmentation reveals how AI workloads and regulatory constraints reshape procurement patterns across New Jersey's data center landscape. Distinct service tiers and deployment models command divergent margin structures based on power density requirements and interconnection complexity.
Service Type:
Colocation faces acute substitution pressure from hyperscale cloud providers building captive facilities, while managed services and disaster recovery retain stickier customer relationships through operational complexity.
- Colocation:Wholesale and retail space leasing with power densities spanning 5-50 kilowatts per rack. Financial services firms in Manhattan and Jersey City pre-lease capacity three years ahead to secure sub-10 millisecond latency to exchange matching engines, though hyperscale self-builds erode pricing power for standard air-cooled offerings.
- Managed Services:Remote hands, smart hands, and infrastructure monitoring delivered through 24/7 network operations centers. Healthcare systems in Newark and Camden corridors contract these services to address HIPAA-compliant workload management without internal specialized staffing.
- Disaster Recovery:Secondary site replication and failover orchestration leveraging cross-river fiber diversity. The New Jersey Department of Environmental Protection's diesel generator runtime caps constrain Tier IV certification pathways for facilities targeting financial regulator mandates.
- Cloud Services:Direct connectivity to hyperscale platforms through dedicated cloud exchange ports. Demand concentrates in Secaucus and Piscataway where fiber-rich utility corridors intersect with state sales tax relief on equipment purchases exceeding 20 megawatts critical load.
Colocation anchors the volume base while cloud services gain share at the steepest rate.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational-expense-driven off-premises alternatives, with hybrid architectures capturing mid-market budget flexibility.
- On-Premises:Enterprise-owned facilities with captive power infrastructure. Pharmaceutical and research computing buyers in the Piscataway cluster favor this model for GPU-dense AI training clusters requiring 40+ kilowatt rack densities.
- Off-Premises:Third-party facility utilization eliminating real estate and utility capital exposure. Retail and mid-market financial services adopt this model to bypass PJM Interconnection's 36-48 month substation backlog.
- Hybrid:Split workload placement across owned and leased infrastructure. Healthcare networks deploy imaging AI at edge nodes while retaining patient records in compliant colocation suites, balancing latency against regulatory control.
- Multi-Cloud:Orchestration across AWS, Azure, and Google Cloud through dedicated interconnects. Submarine cable landings at Wall Township and Manasquan provide diverse connectivity paths that bypass New York City congestion.
Off-premises deployments dominate new capacity absorption while hybrid architectures expand most quickly among regulated industries.
End User:
Customer type determines power density requirements, with financial services and telecommunications driving premium liquid-cooled deployments while healthcare and retail anchor standard offerings.
- Telecommunications:5G core network functions and edge caching infrastructure. Carriers deploy in Meadowlands corridor facilities to minimize backhaul costs to Manhattan subscriber bases.
- Financial Services:Real-time risk modeling and algorithmic trading infrastructure. Asset managers pre-commit to liquid-cooled suites at 40% lease premiums over air-cooled alternatives to support NVIDIA H100 clusters.
- Healthcare:Electronic health record hosting and imaging AI processing. New Jersey's hospital network requires localized edge deployments in Camden and Newark corridors for patient monitoring latency.
- Retail:E-commerce transaction processing and inventory management systems. Seasonal demand spikes favor multi-cloud orchestration over fixed colocation commitments.
Financial services anchors the volume base while healthcare gains share at the steepest rate.
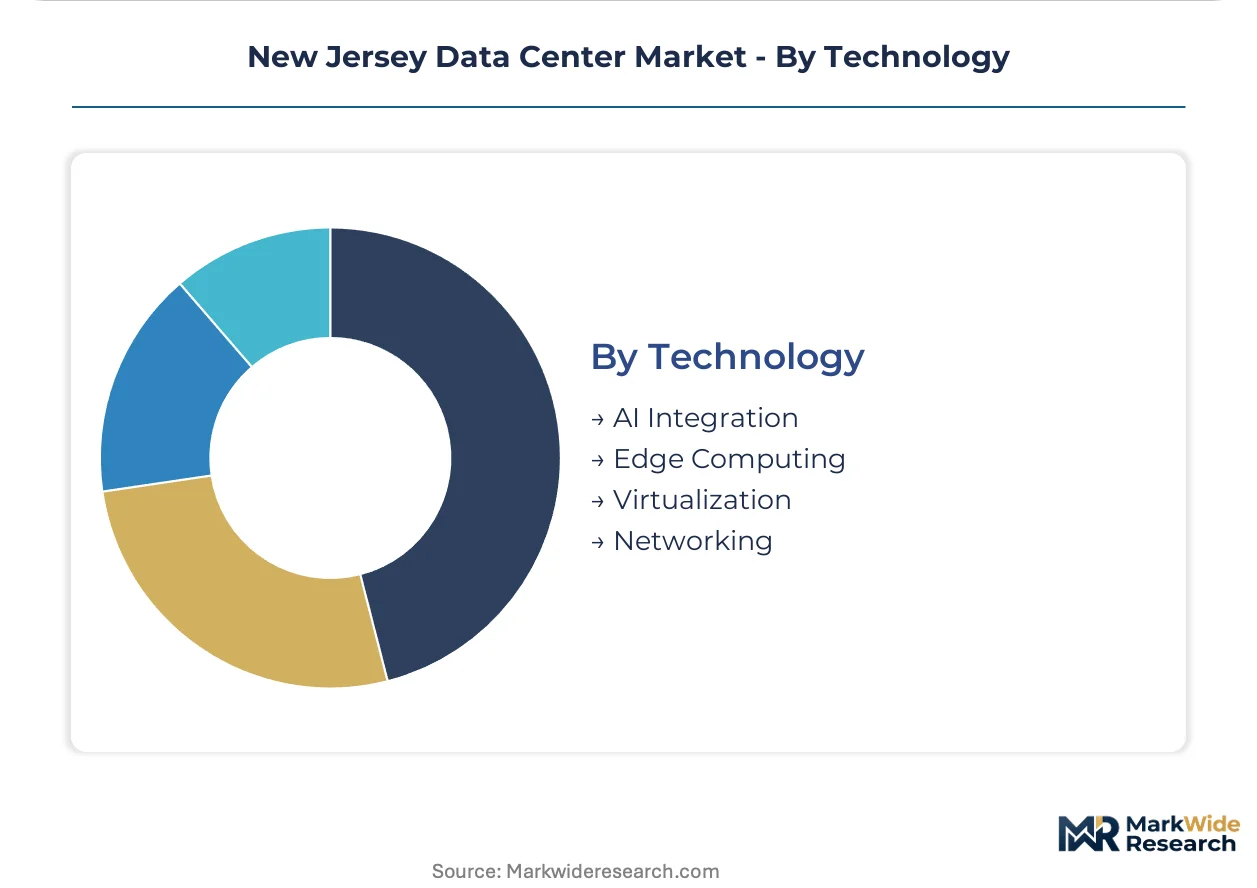
Technology:
Maturity curves separate established virtualization and networking stacks from emerging AI integration and edge computing layers commanding implementation premiums.
- AI Integration:GPU cluster orchestration and machine learning pipeline infrastructure. Cold plate and immersion cooling systems enable 50-100 kilowatt rack densities that bifurcate developer strategies between retrofit-constrained urban sites and greenfield campuses.
- Edge Computing:Distributed processing nodes within 10 milliseconds of population centers. Fastest-expanding technology segment as latency-sensitive workloads displace centralized cloud architectures.
- Virtualization:Server consolidation and workload abstraction through VMware and KVM hypervisors. Mature technology with compressed margins, now table stakes for standard colocation offerings.
- Networking:Software-defined wide area networking and fiber cross-connects. Equinix's Secaucus campus leverages interconnection density to anchor premium pricing for financial services buyers requiring carrier diversity.
Virtualization anchors the volume base while AI integration gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Jersey's data center capacity functions as a net service export to Manhattan financial markets, with cross-river fiber infrastructure creating trade-like flows of compute capacity that bypass domestic transmission constraints.
Meadowlands Corridor
Secaucus and North Bergen absorb hyperscale pre-leasing commitments from asset managers deploying GPU clusters for real-time risk modeling. New Jersey's Economic Development Authority waives sales tax on equipment purchases exceeding 20 megawatts critical load, accelerating capital deployment. The Secaucus campus anchors interconnection density that commands lease premiums for sub-10 millisecond latency to exchange matching engines.
Piscataway Cluster
Pharmaceutical and research computing buyers favor on-premises builds for AI training clusters requiring 40+ kilowatt rack densities. PJM Interconnection's 36-48 month substation backlog forces developers to acquire existing industrial sites with spare utility capacity. The cluster concentrates GPU-dense deployments targeting generative AI infrastructure.
Camden-Newark Healthcare Corridor
Hospital networks deploy imaging AI and patient monitoring at edge nodes requiring localized processing. New Jersey Department of Environmental Protection diesel generator runtime caps constrain Tier IV certification pathways for facilities targeting geographic separation mandates. Camden and Newark sub-markets bifurcate between compliant colocation suites and distributed edge deployments.
Wall Township-Manasquan
Submarine cable landings provide transatlantic fiber diversity that bypasses New York City congestion points entirely. Telecommunications carriers deploy 5G core network functions to minimize backhaul costs to Manhattan subscriber bases. The corridor enables disaster recovery sites that satisfy financial regulator geographic separation requirements.
New Jersey Data Center Market Competitive Landscape
Concentration sits with interconnection-dense platform operators and hyperscale-oriented developers. The New Jersey market exhibits tiered structure with premium liquid-cooled offerings commanding 40% lease premiums over standard air-cooled alternatives. Three archetypes dominate: fiber-rich campus developers leveraging state tax incentives, GPU-specialized compute providers targeting AI training clusters, and diversified REITs with powered shell capabilities. Competitive moves center on pre-leasing commitments preceding construction financing by 18-24 months, and consolidation of multiple projects into single campus phases to trigger incentive eligibility thresholds.
Within the interconnection-tier, Equinix Inc. anchors premium positioning through Secaucus campus density. Digital Realty Trust Inc. and CoreWeave occupy distinct vectors—Digital Realty through powered shell developments capturing pre-leasing momentum, CoreWeave through GPU-dense deployments exemplifying the AI-specialist archetype. These three represent the structural fault lines between legacy colocation economics and next-generation compute infrastructure.
| Leading Market Players |
|---|
| Equinix Inc. |
| Digital Realty Trust Inc. |
| CoreSite Realty Corp. |
| CyrusOne LLC |
| DataBank Holdings Ltd. |
| Nebius Group NV |
| QTS Data Centers |
| CoreWeave |
| Iron Mountain |
| Others |
Pricing and Supply Chain Analysis
Liquid cooling infrastructure displacing air-cooled legacy systems simultaneously concentrates supply geography among specialized mechanical contractors and bifurcates pricing economics between retrofit-constrained urban sites and greenfield campuses with purpose-built thermal infrastructure.
Pricing Analysis
Financial services firms anchor New Jersey's colocation pricing structure through pre-leasing commitments for GPU-dense deployments. Pricing stratifies across liquid-cooled premium suites, standard air-cooled wholesale space, and economy retail tiers differentiated by power density certification and latency performance to Manhattan exchanges. Cost compression in standard air-cooled tiers intensifies because hyperscale self-builds erode third-party pricing power. Mid-market healthcare buyers exhibit highest price sensitivity while algorithmic trading firms show least elasticity for sub-10 millisecond connectivity.
Supply Chain Analysis
Extended lead times for medium-voltage switchgear and precision cooling equipment now stretch 18-24 months across New Jersey project pipelines. Equipment sourcing draws from domestic electrical component manufacturers, German precision cooling OEMs, and Taiwanese power distribution suppliers. Single-source vulnerability concentrates in 34.5 kilovolt switchgear where certified commissioning technicians command premium wages across the tristate labor market. Distribution runs through direct developer-procurement relationships with bypass of traditional distribution channels for hyperscale campus builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Jersey's data center market sits at a platform-economics inflection where interconnection density and GPU cluster orchestration interoperability determine competitive survival. The shift from colocation rental to AI compute platform economics rewards ecosystem orchestrators over pure real estate plays.
For Market Incumbents: Consolidate interconnection assets through fiber cross-connect densification at Secaucus and Piscataway campuses to defend against GPU-specialized entrants capturing AI training workloads. Prioritize backward integration into liquid cooling mechanical infrastructure to preserve margin on 50-100 kilowatt rack deployments. Secure long-term renewable energy offtakes through New Jersey's community solar aggregation program ahead of carbon disclosure rule tightening. For New Entrants and Emerging Players: Tier III certification fast-tracks through acquisition of existing industrial sites with spared utility capacity bypass PJM Interconnection's substation backlog. Target Camden-Newark healthcare corridor edge nodes where imaging AI latency requirements outstrip incumbent colocation footprint. Pursue hospital system partnerships with HIPAA-compliant managed service bundling as primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hyperscale developers holding pre-leased Meadowlands corridor capacity with 15-20 year lease structures. Long-term viability hinges on power procurement flexibility and interconnection agreement renewals with New York-area carriers. Watch New Jersey Department of Environmental Protection diesel generator runtime rulemaking as signal for Tier IV certification pathway viability and disaster recovery site premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables 50-100 kilowatt rack densities for NVIDIA H100 clusters at 40% lease premiums. |
| Pre-Leasing Commitment Acceleration | Financial services firms now secure capacity 18-24 months ahead of construction financing. |
| Community Solar Aggregation | Bypasses utility green tariff limitations through direct developer contracting under state program. |
| Cross-River Fiber Diversity Build | Satisfies SEC geographic separation mandates for Manhattan trading firm disaster recovery. |
| Powered Shell Development | Captures hyperscale pre-leasing momentum while deferring tenant-specific mechanical investment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of PJM Interconnection queue filings, New Jersey Economic Development Authority incentive disclosures, and hyperscaler capital expenditure reports. Primary interviews engaged data center development executives, electrical contracting specialists, financial services infrastructure procurement leads, and New Jersey Department of Environmental Protection regulatory affairs officers. Secondary validation drew from SEC 10-K facility disclosures, state utility commission dockets, and submarine cable landing registration data. Bottom-up project pipeline tracking triangulates against top-down market sizing from power demand forecasts and land use permits.
Segmentation dimensions modeled span service type, deployment model, end user vertical, and technology layer across the projection horizon. The analytical framework incorporates power density tier, latency sensitivity band, and certification grade as industry-specific forecast inputs. CAGRs derive from capacity absorption rates against constrained transmission infrastructure expansion timelines. Scenario weighting reflects pre-leasing commitment velocity and state incentive program utilization rates.
Decision-makers should treat outputs as directional under assumptions of sustained AI workload growth and stable New Jersey tax incentive continuity; material deviation in PJM queue clearing times or diesel generator regulatory tightening would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Spain Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Retail Colocation Market
Data Center Infrastructure
Spain Data Center Power Market