
 Sweden Data Center Market | 2026-2036
Sweden Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Market Insights
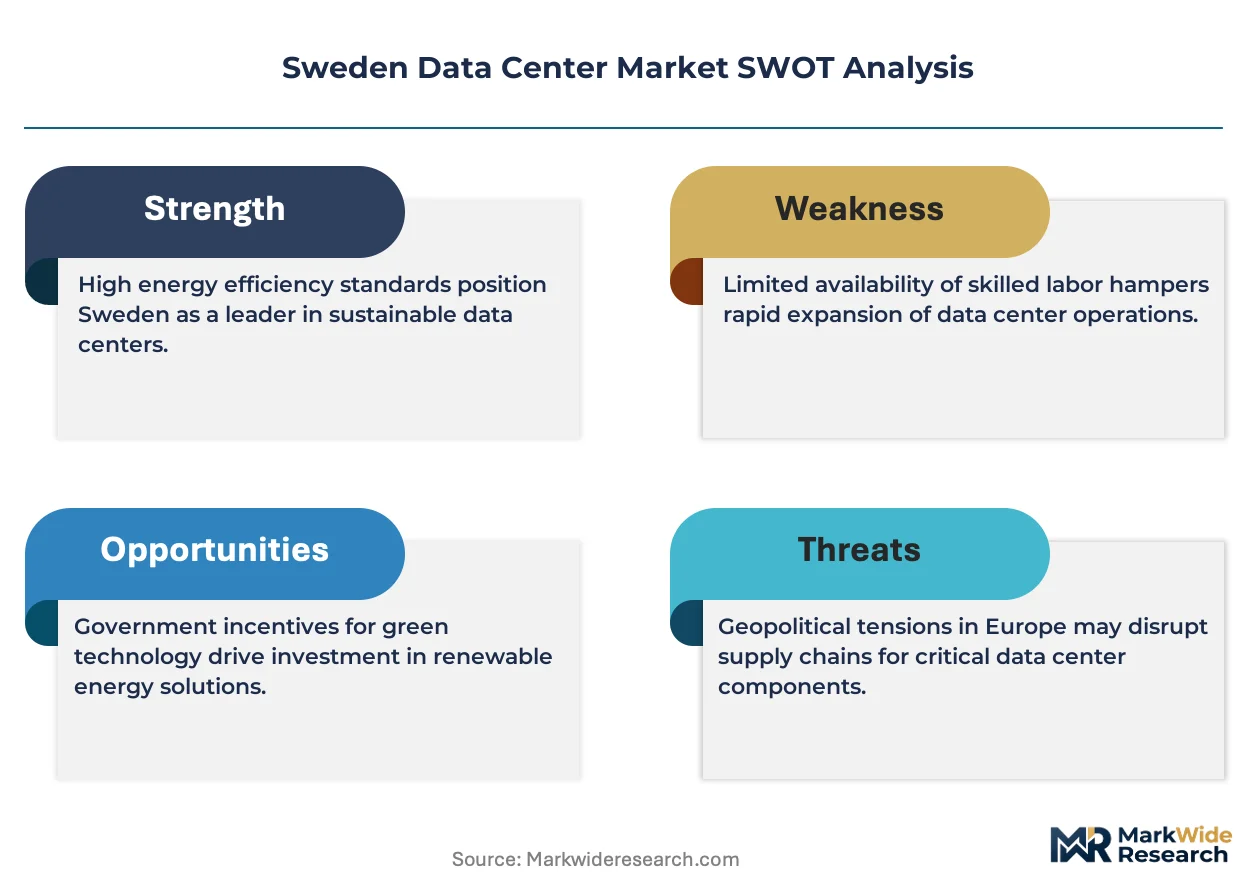
Tier-III reliability certification is bifurcating the Sweden data center landscape into premium and standard strata. EcoDataCenter AB leverages its fossil-free energy positioning to anchor sustainable capacity in Falun. atNorth AB sustains competitive density through liquid-cooled designs optimized for Nordic climates. Microsoft Corporation dominates cloud region expansion with three active availability zones across the country.
A data center constitutes a dedicated facility housing computing infrastructure—servers, storage systems, and networking hardware—typically maintained within temperature ranges of 18°C to 27°C and supported by redundant power distribution units with minimum N+1 resilience. Hyperscale deployment leads capital allocation as cloud providers commission facilities exceeding 50 megawatts each. Edge infrastructure represents the fastest-growing structural segment, driven by latency-sensitive manufacturing and autonomous vehicle testing in northern Sweden. Managed services command stronger margin pools than raw hosting as operators bundle cybersecurity and compliance tooling.
The Swedish Energy Agency enforces efficiency standards that shape facility design, while Boverket building codes mandate fire suppression and structural resilience for critical infrastructure. The EU CSRD requires sustainability disclosure from data center operators above defined thresholds, pressuring smaller colocation providers toward consolidation. Stakeholders must monitor grid interconnection queues and municipal zoning decisions as Stockholm's power reservation backlog extends into surrounding counties.
Market Dynamics
The EU AI Act's digital sovereignty mandates are forcing Swedish financial institutions to localize data processing, redirecting colocation demand toward certified domestic facilities and away from cross-border cloud arbitrage.
Growth Catalysts
- EU AI Act compliance:Swedish banks and insurers must maintain data residency for algorithmic decision systems, accelerating domestic facility buildouts.
- Hydroelectric power arbitrage:Developers exploit Sweden's 100% renewable grid to attract carbon-conscious hyperscale tenants from continental Europe.
- Subarctic free cooling:Northern municipalities leverage annual mean temperatures below 5°C to slash mechanical refrigeration energy intensity.
Market Restraints
- Grid interconnection queues:Stockholm's power reservation backlog now extends into surrounding Södermanland and Uppsala counties, delaying project energization.
- Copper and transformer scarcity:Lead times for medium-voltage switchgear exceed 18 months, constraining power distribution scaling.
- Boverket seismic codes:Updated structural resilience requirements for critical infrastructure add 8-12% to facility hard costs.
Strategic Opportunities
- Norrbotten edge expansion:Autonomous vehicle testing corridors around Luleå and Kiruna demand sub-10ms latency infrastructure.
- Liquid cooling convergence:Direct-to-chip thermal management paired with district heating recovery opens municipal revenue streams.
- CSRD disclosure services:Smaller colocation operators face consolidation pressure, creating acquisition targets for compliance-integrated platforms.
Industry Challenges
- Tier-III certification timelines:Uptime Institute audits now average 14 months, compressing revenue recognition windows for new builds.
- Legacy facility retrofitting:Pre-2020 Stockholm facilities require €400-600 per kW in electrical upgrades to meet current density standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Market |
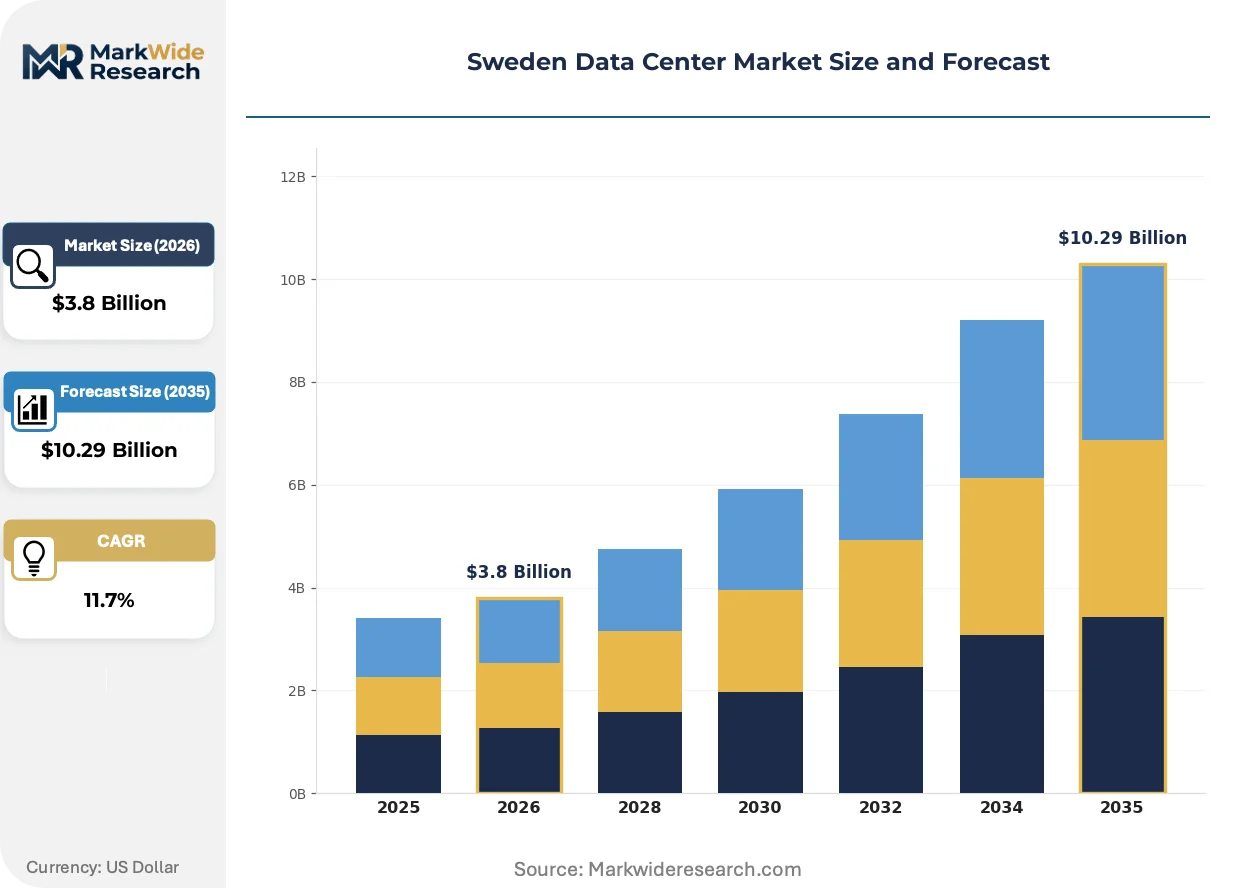
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Colocation, Hyperscale, Edge Service Type: Managed Services, Cloud Services, Disaster Recovery, Hosting Infrastructure: Cooling Systems, Power Supply, Racks, Network Equipment End User: IT Companies, Financial Services, Telecom, Retail |
| Companies Covered | atNorth AB, Bahnhof AB, EcoDataCenter AB, Amazon Web Services, Inc., Microsoft Corporation, Equinix, Digital Realty, Conapto, Meta Platforms, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Market Trends and Innovations
Swedish operators are weaponizing climatic and regulatory advantages to capture workloads displaced from continental Europe's power-constrained markets.
Immersion cooling systems are miniaturizing thermal management footprints while enabling 100kW+ rack densities. AtNorth AB deploys single-phase dielectric fluid baths across its Stockholm and Reykjavik-adjacent sites, cutting mechanical infrastructure by 40%. This compression is eliminating raised-floor designs from new Nordic builds.
The EU CSRD mandates granular sustainability disclosure from data center operators above 500 employees or €150 million turnover. Swedish facilities must now report Scope 3 embodied carbon from steel and concrete. Colocation providers are responding by sourcing low-carbon structural materials and procuring third-party verification.
Financial services buyers are consolidating vendor relationships around integrated compliance-security bundles. Swedish banks now require colocation contracts to include SOC 2 Type II attestation and EU AI Act risk assessments as standard terms. This bundling is squeezing pure-play hosting margins across the Stockholm metro.
Sweden Data Center Market Segmentation
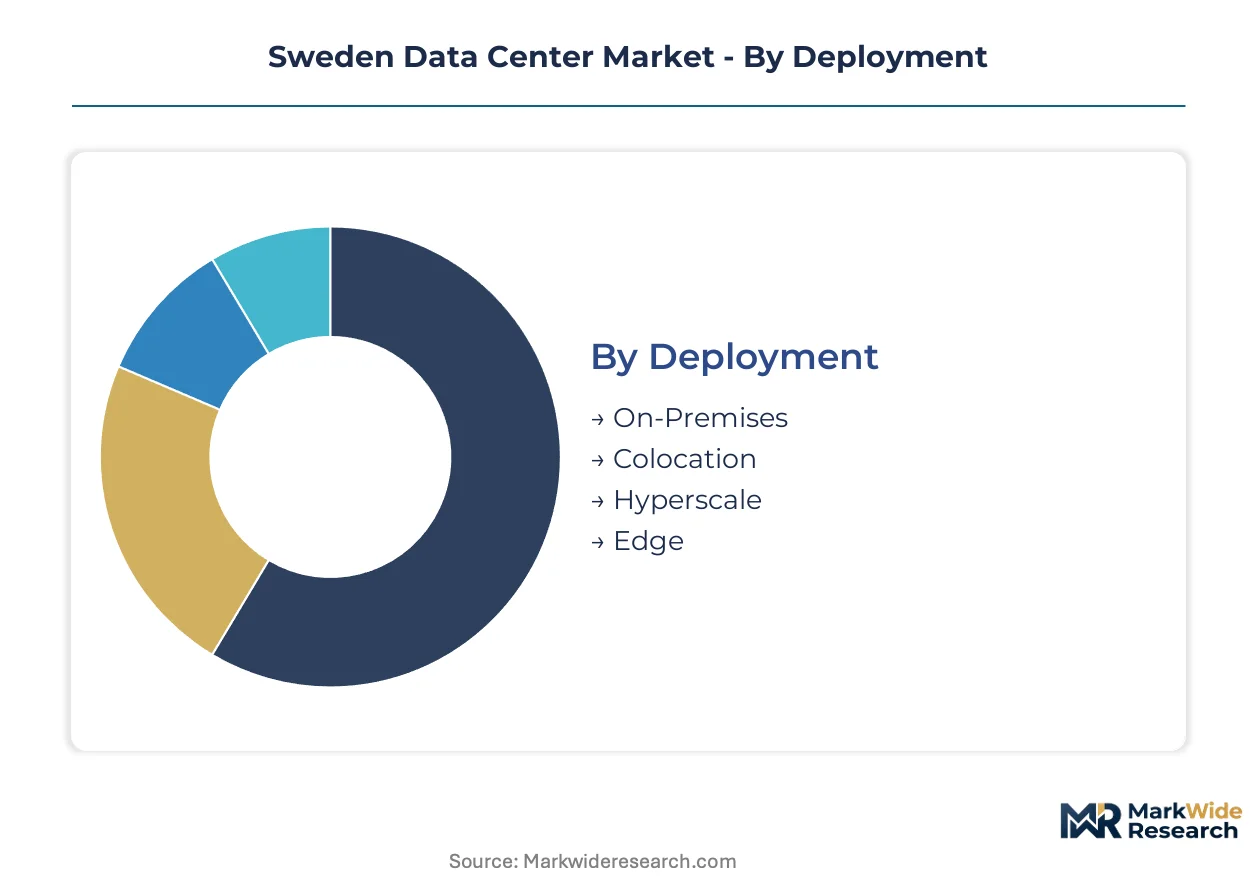
Segmentation reveals how Sweden's climatic advantages and regulatory pressures distribute demand across facility types and customer verticals. Each dimension exposes distinct margin structures, certification requirements, and geographic clustering within the Nordic data center corridor.
Deployment:
Hyperscale deployments concentrate in Stockholm and Falun municipalities, while edge infrastructure spreads northward toward Luleå and Kiruna autonomous vehicle testing zones.
- On-Premises:Enterprise-owned facilities within financial services headquarters maintain algorithmic trading systems requiring sub-millisecond latency. Swedish banks under EU AI Act mandates retain domestic control over sensitive customer scoring models, insulating this segment from cloud migration pressures.
- Colocation:Third-party facilities offer Tier-III certified space with redundant power and cooling for mid-market tenants. Financial services procurement teams now bundle SOC 2 Type II attestation and EU AI Act risk assessments as standard contract terms, squeezing pure-play hosting margins.
- Hyperscale:Cloud provider facilities exceeding 50 megawatts each dominate capital allocation, exploiting Sweden's 100% renewable hydroelectric grid to attract carbon-conscious tenants from continental Europe.
- Edge:Sub-10ms latency infrastructure clusters around northern Sweden's autonomous vehicle testing corridors, with liquid-cooled designs optimized for subarctic climates enabling dense compute at distributed points.
Hyperscale commands the established base. The steepest expansion runs through Edge.
Service Type:
Margin pools deepen as operators bundle compliance tooling and security layers atop raw infrastructure, with managed services capturing premium pricing over commodity hosting.
- Managed Services:Operators integrate cybersecurity monitoring, patch management, and EU CSRD sustainability disclosure support. Swedish colocation contracts increasingly embed compliance-technical bundles as non-negotiable terms.
- Cloud Services:Public and private cloud consumption through domestic availability zones accelerates as Microsoft Corporation expands three active zones nationwide.
- Disaster Recovery:Geographically separated backup sites leverage Sweden's political stability and distance from continental European risk corridors for financial services continuity planning.
- Hosting:Raw space-and-power offerings face commoditization as Tier-III certification bifurcates the landscape into premium and standard strata.
Managed Services commands the established base. Cloud Services climbs the fastest.
Infrastructure:
Component selection determines facility efficiency ratings under Swedish Energy Agency standards, with thermal and power systems attracting the dominant share of capital expenditure.
- Cooling Systems:Direct-to-chip liquid cooling and single-phase dielectric fluid baths enable 100kW+ rack densities while eliminating raised-floor designs. AtNorth AB deploys these systems across Stockholm sites, cutting mechanical infrastructure by 40%.
- Power Supply:Medium-voltage switchgear lead times now exceed 18 months, constraining power distribution scaling and extending project energization timelines.
- Racks:High-density enclosures accommodate liquid cooling manifolds and cable management for AI training clusters.
- Network Equipment:Low-latency switching fabric supports financial services algorithmic trading and northern edge autonomous vehicle telemetry.
Cooling Systems commands the established base. Power Supply faces the tightest supply constraints.
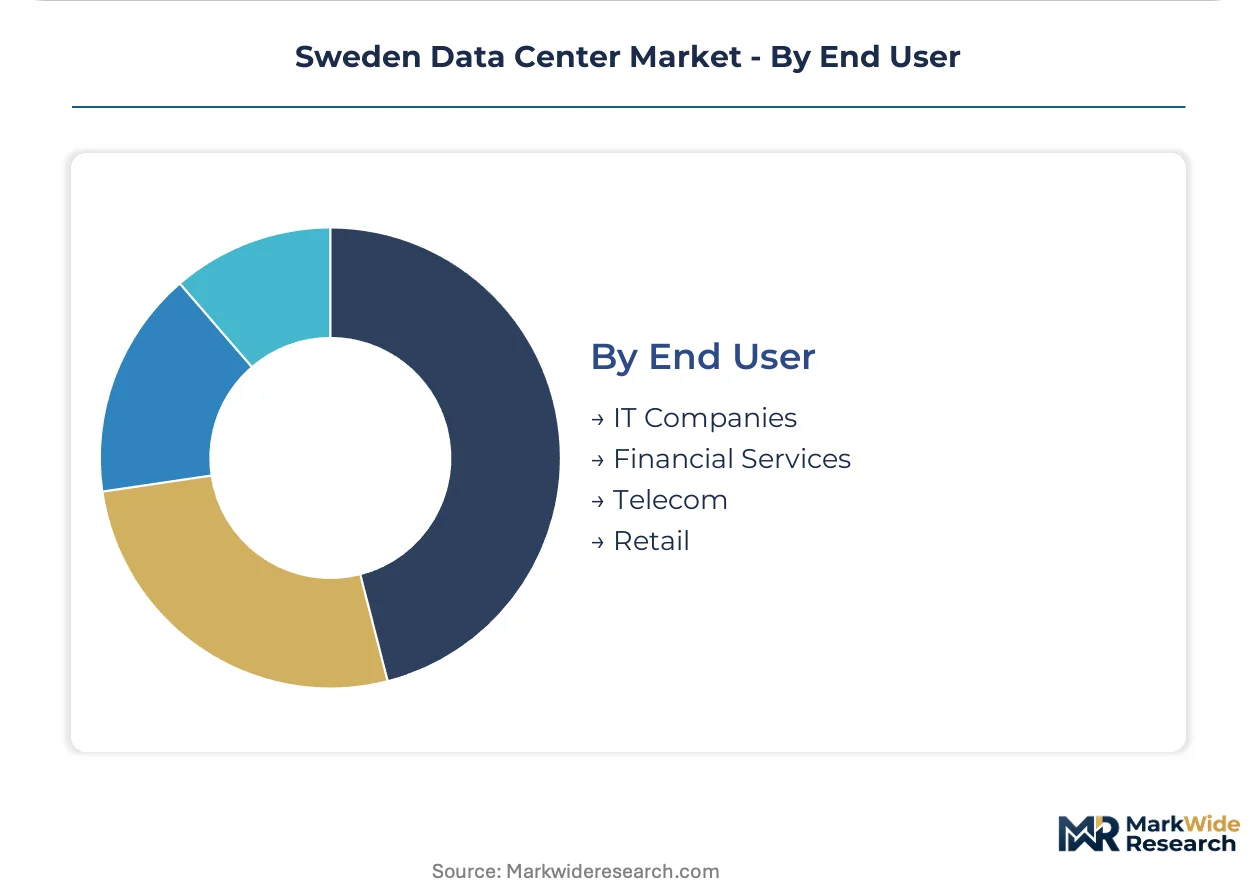
End User:
Financial services procurement drives certification requirements across all facility tiers, while telecom operators anchor interconnection density in Stockholm metro sites.
- IT Companies:Software developers and SaaS providers consume hyperscale capacity for application hosting and AI model training workloads.
- Financial Services:Banks and insurers under EU AI Act digital sovereignty mandates redirect colocation demand toward certified domestic facilities, accelerating Stockholm facility buildouts for algorithmic decision system residency.
- Telecom:Mobile network operators deploy edge infrastructure for 5G core functions and low-latency content delivery.
- Retail:E-commerce platforms and omnichannel operators utilize disaster recovery and cloud bursting for seasonal demand spikes.
Financial Services commands the established base. IT Companies gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale facility construction clusters where renewable power availability intersects with subarctic cooling economics. Developers site megawatt-scale deployments across Nordic municipalities exploiting hydroelectric baseload and free-air cooling advantages.
Stockholm Metropolitan Area
Swedish banks under EU AI Act mandates drive Tier-III certified colocation demand for algorithmic decision system residency. Boverket building codes enforce seismic resilience standards adding hard cost premiums. Microsoft Corporation operates three availability zones across Stockholm County, absorbing the majority of new hyperscale capacity.
Falun Municipality
EcoDataCenter AB anchors sustainable capacity through fossil-free energy positioning and district heating integration. The Swedish Energy Agency enforces efficiency standards shaping facility thermal design. Falun's proximity to Dalarna hydroelectric infrastructure attracts carbon-conscious tenants from continental Europe.
Luleå and Norrbotten County
Autonomous vehicle testing corridors generate sub-10ms latency infrastructure demand across northern Sweden. Facebook (Meta Platforms, Inc.) established early hyperscale presence exploiting the region's annual mean temperatures below 5°C. Edge compute clusters now deploy liquid-cooled designs optimized for AI training workloads.
Gävle and Södermanland County
Stockholm's power reservation backlog extends grid interconnection queues into surrounding counties. Copper and transformer scarcity stretches medium-voltage switchgear lead times beyond 18 months. Developers target Gävleborg for secondary hyperscale sites with available grid capacity and municipal zoning flexibility.
Uppsala County
Academic and research computing demand from Uppsala University drives specialized HPC colocation requirements. The EU CSRD mandates granular sustainability disclosure pressuring facility operators toward third-party verification. Conapto and Bahnhof AB maintain presence serving public sector and enterprise hybrid cloud deployments.
Sweden Data Center Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Swedish data center landscape. International hyperscale cloud operators dominate capital allocation through facilities exceeding 50 megawatts each. Domestic specialists occupy sustainable positioning and edge latency segments. Competitive dynamics center on renewable energy contracting and municipal zoning capture rather than direct price competition.
Among Nordic-origin operators, atNorth AB exemplifies liquid-cooled density specialization, while EcoDataCenter AB anchors fossil-free sustainability positioning. International cloud platforms including Microsoft Corporation and Amazon Web Services, Inc. represent the scale-driven archetype with multi-availability-zone national coverage. These three anchors illustrate the market's tripartite structure: domestic climate-optimized specialists, domestic sustainability-focused developers, and global hyperscale integrators.
| Leading Market Players |
|---|
| atNorth AB |
| Bahnhof AB |
| EcoDataCenter AB |
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Equinix |
| Digital Realty |
| Conapto |
| Meta Platforms, Inc. |
| Others |
Pricing and Supply Chain Analysis
The EU AI Act's digital sovereignty mandates gate both facility qualification and price differentiation simultaneously. Swedish financial institutions now require Tier-III certification and SOC 2 Type II attestation as non-negotiable contract terms, compressing margins for uncertified operators while enabling premium pricing for compliant domestic facilities.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across the Swedish data center landscape. Three-tier pricing structure across premium, standard, and economy levels segments the market, with Tier-III certified facilities commanding substantial premiums over uncertified alternatives. Price differentiation rests on certification grade and geographic delivery cost, as Stockholm metro sites face power reservation backlogs that extend premiums to surrounding counties. Cost compression in standard-tier colocation is intensifying because pure-play hosting providers cannot bundle compliance tooling. Financial services buyers exhibit the least price sensitivity due to regulatory mandates, while retail and mid-market SaaS operators drive commoditization pressure in uncertified segments.
Supply Chain Analysis
China and Germany anchor electrical infrastructure manufacturing for Swedish data center builds. Medium-voltage switchgear and copper winding assemblies draw from Chinese foundries and German precision component suppliers, with transformer cores sourced from Japanese electrical steel producers. Single-source vulnerability concentrates in medium-voltage switchgear, where lead times now extend beyond eighteen months due to copper scarcity and foundry capacity constraints. Distribution runs through Stockholm-based systems integrators and direct hyperscale procurement channels, with secondary routing via Gothenburg port logistics for northern edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of liquid-cooled thermal engineering talent and certified project management capacity constrains execution velocity across the Swedish data center pipeline. Operators who secure these specialized capabilities before competitors will capture disproportionate share of EU AI Act-driven financial services demand.
For Market Incumbents: Compound renewable energy contracting advantages by securing long-term hydroelectric power purchase agreements before grid interconnection queues lengthen further. Prioritize vertical integration into district heating recovery systems to monetize thermal output through municipal revenue streams. Defend against hyperscale cloud encroachment by embedding EU CSRD disclosure services into managed service bundles, creating switching costs for compliance-dependent financial services tenants. For New Entrants and Emerging Players: Anchor in Norrbotten County's autonomous vehicle testing corridors, where sub-10ms latency requirements outstrip current edge infrastructure supply. Target liquid-cooled density specialization as the most penetrable technical wedge, as atNorth AB's deployment model remains unreplicated across northern Sweden. Pursue municipal zoning capture in Gävleborg and Södermanland counties, where Stockholm's power reservation backlog has created development appetite with available grid capacity. For Investors and Strategic Acquirers: The EU CSRD disclosure mandate reshapes the acquisition landscape by pressuring sub-500-employee colocation operators toward consolidation. Long-term viability centers on platforms with integrated compliance-technical bundles rather than pure-play hosting assets. Target acquisition archetypes include Tier-III certified regional operators with existing financial services contracts and undeveloped land positions in Tier-2 Swedish municipalities. Monitor municipal zoning approval velocity in Uppsala and Gävleborg counties as the critical inflection signal for pipeline expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables 100kW+ rack densities while eliminating mechanical refrigeration energy intensity in subarctic climates. |
| Renewable Power Purchase Agreement | Secures fossil-free hydroelectric baseload to attract carbon-conscious hyperscale tenants from continental Europe. |
| Tier-III Certification Investment | Gates access to EU AI Act-mandated financial services colocation demand with premium pricing power. |
| District Heating Integration | Opens municipal revenue streams through thermal energy recovery from direct-to-chip cooling systems. |
| CSRD Disclosure Service Bundling | Creates compliance-integrated platform differentiation against pure-play hosting competitors. |
Research Methodology
Operator-level perspectives from data center facility managers, hyperscale cloud procurement officers, Swedish Energy Agency regulators, municipal zoning officials, and financial services infrastructure architects anchored the qualitative base. These primary interviews combined with secondary validation from SEC hyperscaler capex disclosures, Swedish Energy Agency efficiency standard filings, Boverket building code updates, EU CSRD regulatory texts, and Nordic grid operator interconnection queue data. Bottom-up facility-level capacity modeling and top-down market sizing triangulated volume estimates across deployment types.
Sensitivity analysis framed the analytical approach across the projection horizon. Segmentation dimensions modeled include deployment type, service tier, infrastructure component category, and end-user vertical, with geographic clustering by municipality and grid zone. CAGRs derived from facility pipeline tracking, power reservation timelines, and tenant contract duration analysis. Industry-specific forecast inputs encompassed hydroelectric power availability curves and Uptime Institute certification audit completion rates.
Underlying assumptions cover sustained EU AI Act enforcement trajectory, stable Swedish hydroelectric generation capacity, and continued hyperscale cloud expansion commitment, with deviation risk concentrated in grid interconnection queue extensions beyond current county-level backlogs and copper transformer supply constraints. Recalibration cycles align with material shifts in EU CSRD disclosure thresholds, Boverket seismic code amendments, and municipal zoning policy changes in Stockholm-adjacent counties.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Data Center Power Solutions Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market