
 Japan Data Center Power Market | 2026-2036
Japan Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Power Market Insights
Hyperscale cloud deployments is broadening the end-user base beyond traditional enterprise colocation. Mitsubishi Electric leverages its domestic manufacturing scale to dominate high-voltage alternating current infrastructure for Tokyo Bay facilities. Schneider Electric SE anchors its position through integrated power management software that competes with local system integrators. Hitachi Energy differentiates via grid-interactive UPS platforms that sustain uptime during Japan's seismic grid events.
Japan data center power encompasses the generation, conditioning, distribution, and backup systems that deliver continuous electrical supply to server halls, typically operating at 400V AC or 48V DC with redundancy tiers from N+1 to 2N. Its primary purpose is eliminating downtime for digital infrastructure where interruption costs exceed millions of dollars per hour. UPS and generator segments remain the revenue backbone due to mandatory seismic-grade resilience requirements, while fuel cell installations represent the fastest-growing power type as hydrogen supply chains mature in Kanto and Kansai industrial corridors. Energy storage technology captures expanding margin pools as lithium-ion and emerging solid-state batteries buffer intermittent renewable input for off-grid edge facilities.
METI enforces efficiency benchmarks under the Act on Rationalizing Energy Use, compelling operators to report PUE metrics and adopt renewable power ratios. JIS standards and PMDA guidelines for pharmaceutical data integrity indirectly shape backup power specifications in Osaka's life sciences cluster. Stakeholders must monitor grid decarbonization timelines and hydrogen infrastructure buildout to calibrate long-term fuel cell procurement against conventional diesel generator refresh cycles.
Market Dynamics
Seismic-grade resilience mandates and hydrogen infrastructure maturation are restructuring Japan's data center power procurement calculus, forcing operators to reweight capital allocation between conventional diesel backup and emerging fuel cell architectures.
Growth Catalysts
- METI Efficiency Benchmarks:The Act on Rationalizing Energy Use compels PUE reporting and renewable integration, accelerating fuel cell procurement cycles among hyperscale operators in the Greater Tokyo Area.
- AI Training Cluster Expansion:Hyperscale cloud providers are broadening facility footprints across Tokyo and Osaka, driving demand for compact, high-density power solutions that maximize compute per square meter.
- Grid Decarbonization Timelines:Kanto and Kansai industrial corridors are maturing hydrogen supply chains, enabling fuel cell installations to displace conventional generator refresh cycles in edge facilities.
Market Restraints
- Land Scarcity Premiums:The Greater Tokyo Area faces acute land constraints that inflate site acquisition costs and compress feasible power infrastructure footprints for new builds.
- Grid Interconnection Queues:Tokyo Electric Power and Kansai Electric Power face transmission capacity saturation, delaying utility-scale renewable interconnections for large data center campuses.
- Liquid Hydrogen Supply Gaps:Domestic hydrogen production remains concentrated in industrial corridors, creating logistics bottlenecks for fuel cell deployments in secondary markets.
Strategic Opportunities
- Osaka Life Sciences Cluster:PMDA pharmaceutical data integrity guidelines are shaping backup power specifications, creating specialized demand for uninterrupted power quality in biologics manufacturing adjacencies.
- Solid-State Battery Integration:Emerging solid-state energy storage technology converges with lithium-ion cost curves, offering margin expansion for off-grid edge facilities in Tohoku and Kyushu.
- Grid-Interactive UPS Platforms:Seismic grid event resilience is opening procurement channels for bi-directional power conditioning systems that monetize frequency regulation services.
Industry Challenges
- Seismic Engineering Certification:JIS standards for earthquake-resistant electrical infrastructure extend equipment qualification timelines and compress vendor qualification pools.
- Legacy Diesel Asset Stranding:Operators face complex integration paths for hybrid fuel cell-diesel architectures that preserve N+1 redundancy during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Power Market |
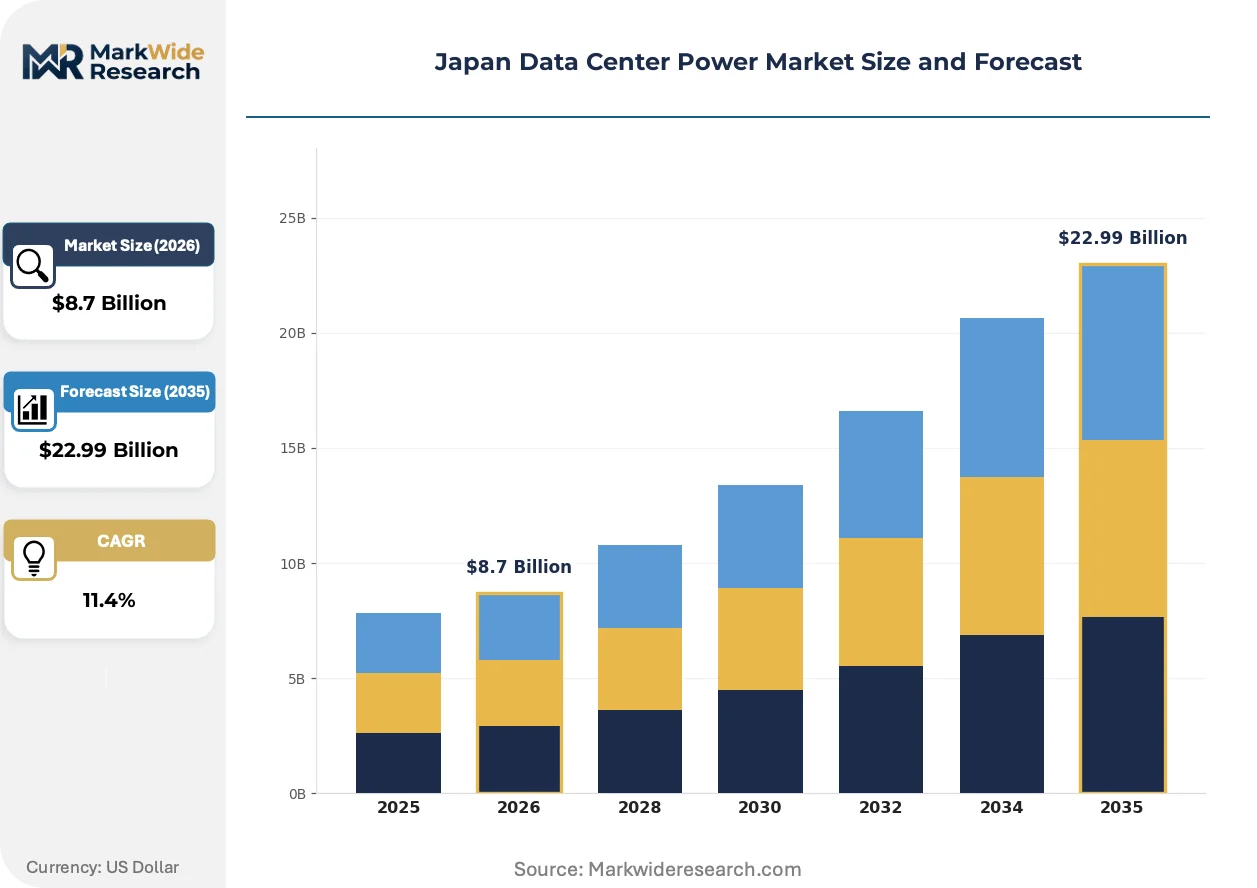
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: UPS, Generator, Renewable Energy, Fuel Cell End User: Hyperscale Providers, Colocation Facilities, Enterprises, Telecom Companies Service Type: Managed Services, Consulting, Maintenance, Installation Technology: Direct Current, High Voltage Alternating Current, Inverters, Energy Storage |
| Companies Covered | Eaton Corporation, Mitsubishi Electric, ABB Ltd, Fujitsu, Hitachi Energy, Schneider Electric SE, Caterpillar Inc., NTT Global Data Centers, Vertiv Group Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Power Market Trends and Innovations
Hydrogen-ready power architectures and grid-interactive conditioning systems are reshaping procurement specifications, while seismic resilience engineering is becoming a non-negotiable design parameter rather than a premium add-on.
High-voltage direct current distribution is consolidating rack-level power delivery for AI training clusters. Hyperscale operators in Tokyo Bay facilities are adopting 400V DC bus architectures to eliminate conversion losses. This voltage standardization is consolidating vendor ecosystems around integrated power shelf designs that compress data hall footprints.
METI's revised energy efficiency standards are tightening PUE disclosure requirements for facilities above 1,500 square meters. The regulation mandates annual third-party verification and public benchmarking, forcing operators to accelerate renewable power purchase agreements. Osaka's pharmaceutical data centers are responding earliest, driven by PMDA audit exposure for temperature excursion liability.
Buyers are unbundling power infrastructure procurement from general construction contracts, creating direct vendor relationships with specialized UPS and fuel cell manufacturers. Systems integrators in the Greater Tokyo Area are losing margin to factory-direct service models. This disintermediation is most visible among cloud operators with standardized global specifications who can bypass local engineering intermediaries.
Japan Data Center Power Market Segmentation
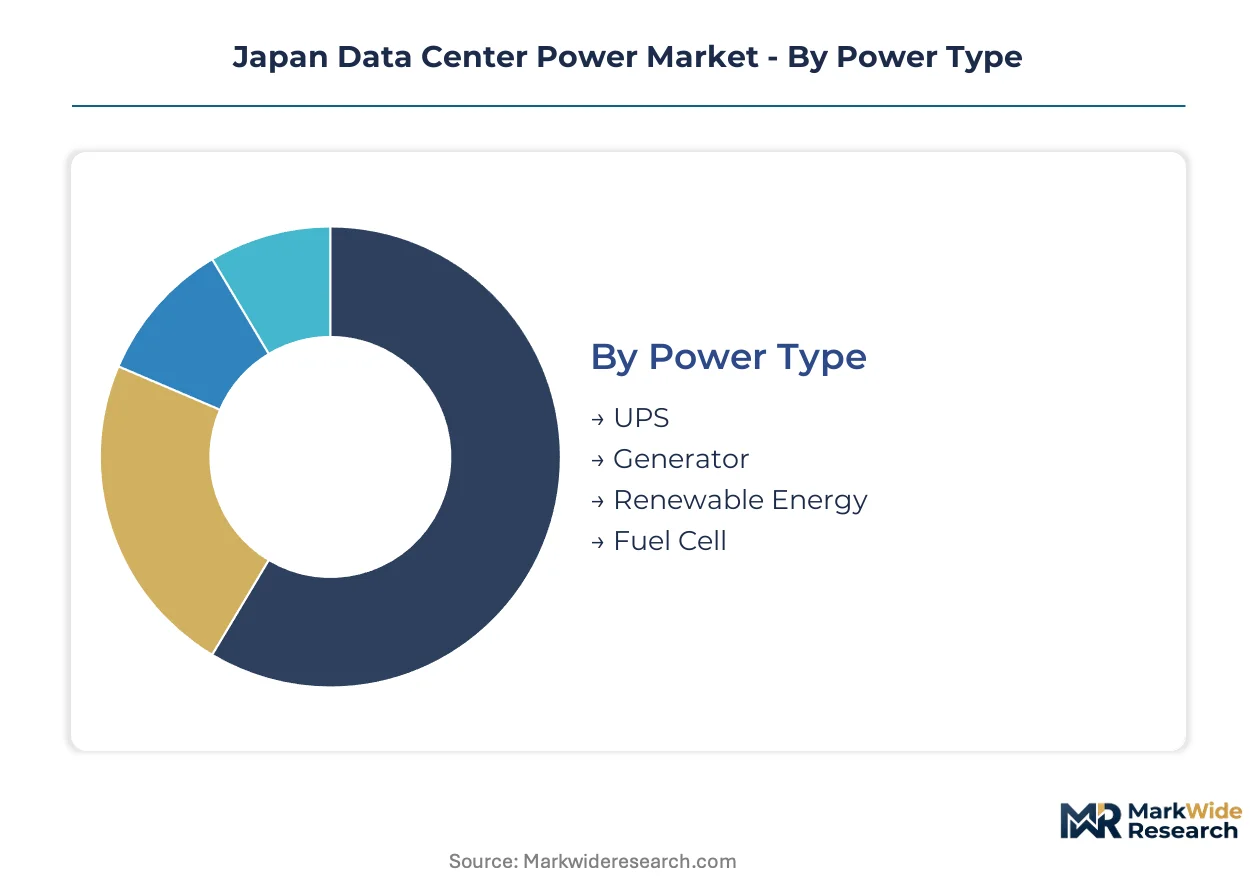
Power infrastructure segmentation in Japan reflects distinct procurement cycles between hyperscale cloud expansions and legacy enterprise refreshes. Each dimension captures different decision-making hierarchies—from capital-intensive fuel cell investments to recurring maintenance contracts.
Power Type:
Upgrade and replacement cycles vary dramatically across power architectures, with seismic resilience mandates forcing premature diesel generator retirements in Tokyo Bay facilities.
- UPS:Double-conversion online systems dominate rack-level protection with 400V DC compatibility for AI clusters. Demand concentrates in Osaka's pharmaceutical corridor where PMDA audit requirements mandate sub-4ms transfer times for biologics cold chain integrity.
- Generator:Diesel rotary uninterruptible power supplies retain installed base dominance despite METI decarbonization pressure. Hyperscale operators in Greater Tokyo face compressed replacement windows as hydrogen infrastructure matures, creating hybrid procurement strategies.
- Renewable Energy:Behind-the-meter solar and wind installations buffer grid dependency for edge facilities in Tohoku.
- Fuel Cell:Solid oxide and proton exchange membrane systems displace conventional backup in Kanto hydrogen corridor deployments.
Volume placements concentrate in Generator; the faster expansion belongs to Fuel Cell.
End User:
Customer scale determines power architecture standardization versus customization trade-offs.
- Hyperscale Providers:Standardized 400V DC bus designs with factory-integrated power shelves compress deployment timelines. These operators bypass local systems integrators through direct manufacturer relationships, reshaping procurement channels in Tokyo and Osaka.
- Colocation Facilities:Multi-tenant redundancy requirements drive N+1 to 2N tier differentiation. Greater Tokyo land scarcity forces vertical density strategies with compact modular UPS configurations.
- Enterprises:In-house data centers prioritize legacy 208V AC compatibility over efficiency gains.
- Telecom Companies:Edge computing deployments in Kyushu and Hokkaido favor lithium-ion buffered microgrids.
Revenue concentration sits with Hyperscale Providers; margin expansion favors Colocation Facilities.
Service Type:
Service attach rates diverge between capital-intensive installations and recurring maintenance streams.
- Managed Services:Remote monitoring and predictive analytics contracts extend vendor relationships beyond equipment sale. Hyperscale operators in Tokyo Bay standardize these arrangements to reduce in-house electrical engineering headcount.
- Consulting:Power infrastructure unbundling from general construction contracts creates specialized advisory demand. METI efficiency verification requirements drive third-party PUE assessment procurement.
- Maintenance:Seismic-grade certification renewal cycles sustain recurring revenue for domestic service organizations.
- Installation:Factory-direct commissioning models displace local integrator margins among global cloud operators.
Contract value peaks in Managed Services; growth velocity favors Consulting.
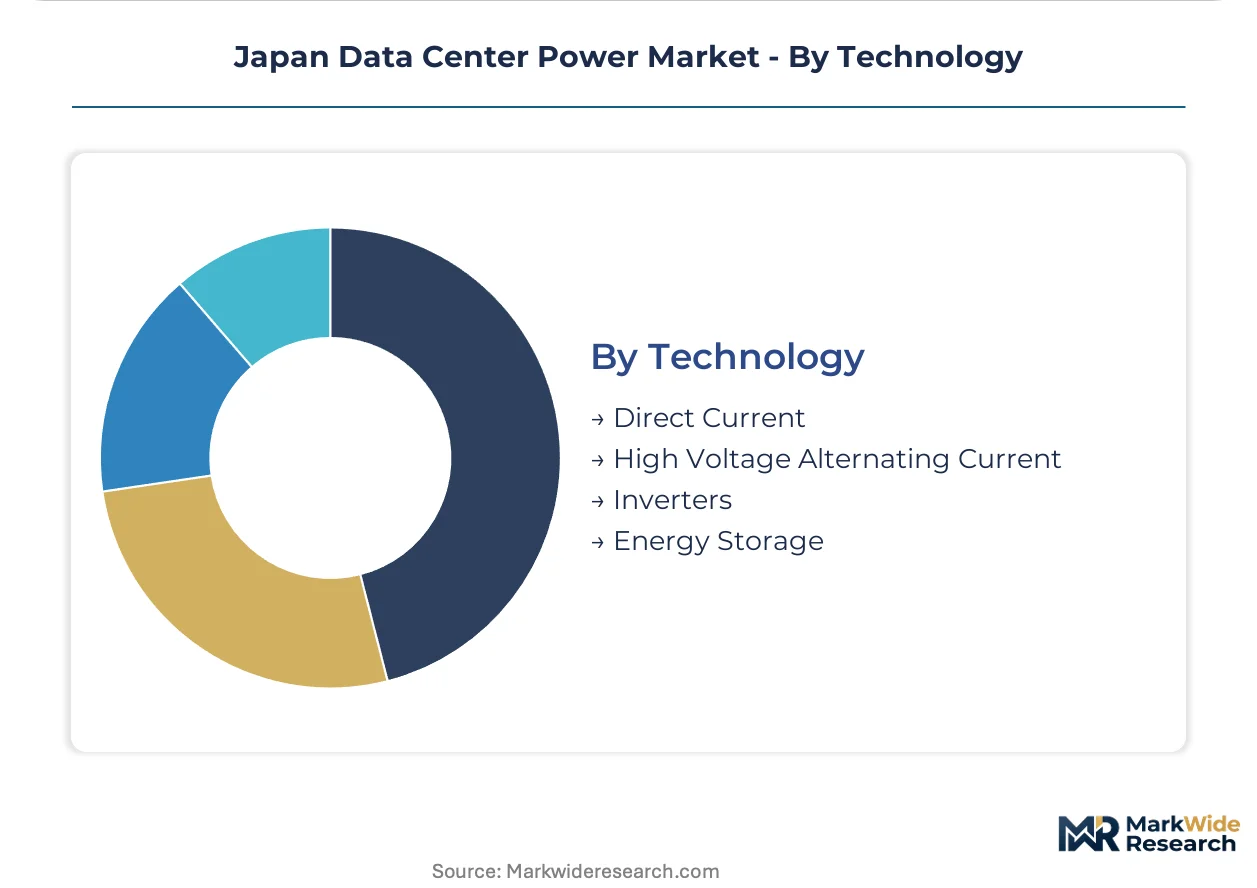
Technology:
Voltage standardization battles reshape component supplier ecosystems.
- Direct Current:400V DC distribution eliminates conversion losses for AI training clusters. Adoption concentrates in hyperscale Tokyo facilities where rack power densities exceed 30kW.
- High Voltage Alternating Current:13.8kV incoming service with step-down transformation retains dominance in enterprise and colocation builds. Osaka's established electrical infrastructure favors this architecture for brownfield expansions.
- Inverters:Bidirectional grid-interactive models enable frequency regulation revenue streams.
- Energy Storage:Lithium-ion and emerging solid-state batteries buffer renewable intermittency for off-grid edge sites.
Installed base dominance remains with High Voltage Alternating Current; share gains accrue fastest to Direct Current.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's data center power infrastructure concentrates in coastal metropolitan zones where electricity demand outstrips domestic generation capacity. The Greater Tokyo Area absorbs nearly half of national data center power investment despite grid constraints and seismic vulnerability. Regional development patterns reflect hydrogen corridor maturation and pharmaceutical cluster specialization.
Kanto/Tokyo
Hyperscale cloud expansions and AI training clusters drive 400V DC power architecture adoption across Tokyo Bay facilities. METI's Act on Rationalizing Energy Use mandates PUE reporting for campuses exceeding 1,500 square meters. The Inzai and Fuchu submarkets anchor fuel cell procurement as Kanto hydrogen supply chains reach commercial scale.
Kansai/Osaka
Pharmaceutical manufacturing adjacencies create specialized demand for sub-4ms UPS transfer times under PMDA cold chain integrity guidelines. Osaka Prefecture's established electrical infrastructure favors 13.8kV high-voltage AC for brownfield expansions. The Sakai industrial corridor hosts the nation's densest concentration of biologics-grade backup power specifications.
Chubu/Nagoya
Automotive and aerospace electronics manufacturing generates steady demand for seismic-grade power conditioning systems. JIS earthquake-resistant certification requirements extend equipment qualification timelines for Nagoya-based operators. The Tokai region's proximity to industrial hydrogen production supports early fuel cell pilot deployments.
Kyushu
Edge computing facilities leverage lithium-ion buffered microgrids to offset grid intermittency in renewable-rich southern zones. TEPCO transmission capacity saturation affects northern Kyushu less severely than Kanto. Fukuoka's emerging data center cluster prioritizes compact modular UPS configurations amid land constraints.
Tohoku
Post-Fukushima grid diversification policies accelerate behind-the-meter renewable integration for off-grid edge sites. Solid-state battery trials buffer wind power variability in Aomori and Iwate prefectures. Sendai's disaster-resilient infrastructure mandates shape procurement specifications for regional colocation facilities.
Japan Data Center Power Market Competitive Landscape
Top-tier vendors anchor hyperscale procurement channels, while domestic specialists capture seismic certification niches. The market structure reflects a bifurcation between global power infrastructure conglomerates and Japan-specific system integrators. Three archetypes dominate: multinational electrical equipment manufacturers with integrated software platforms, domestic heavy electrical conglomerates leveraging manufacturing scale, and specialized UPS fabricators with seismic engineering expertise. Competitive moves center on factory-direct service models that displace local integrators, and hydrogen-ready product line transitions that anticipate METI decarbonization timelines.
Among Japan-based electrical conglomerates, Mitsubishi Electric and Hitachi Energy occupy positions that exemplify domestic manufacturing scale advantages. Schneider Electric SE and Eaton Corporation represent the multinational tier with standardized global specifications that enable direct procurement bypassing regional intermediaries. Vertiv Group Corp. anchors the specialized infrastructure segment.
| Leading Market Players |
|---|
| Eaton Corporation |
| Mitsubishi Electric |
| ABB Ltd |
| Fujitsu |
| Hitachi Energy |
| Schneider Electric SE |
| Caterpillar Inc. |
| NTT Global Data Centers |
| Vertiv Group Corp. |
| Others |
Pricing and Supply Chain Analysis
Copper and silicon steel price indices cascade through Japan's data center power equipment supply chain, compressing margins for domestic UPS fabricators while hyperscale buyers leverage volume scale to lock in long-term contract tiers. This commodity-cost transmission forces pricing stratification across seismic-grade certification levels, with JIS-certified suppliers commanding premiums over uncertified alternatives.
Pricing Analysis
Margin tightening in modular UPS tiers reflects lithium-ion battery cost volatility and yen depreciation against dollar-denominated semiconductor imports. Three-tier pricing structure across premium JIS-certified, standard IEC-compliant, and economy non-seismic tiers differentiates procurement channels, with certification grade and after-sales service bundling as primary drivers. Cost-down pressure on generator sets accelerates because METI decarbonization timelines compress diesel replacement windows. Colocation facilities exhibit highest price sensitivity due to multi-tenant cost allocation complexity, while hyperscale operators absorb premiums for factory-direct commissioning.
Supply Chain Analysis
Refurbishment flows for retired diesel rotary UPS units create secondary component streams that feed domestic remanufacturing operations in Osaka and Nagoya. Manufacturing concentration rests on Japan, China, and South Korea for power conversion equipment, with domestic producers anchoring high-voltage AC infrastructure and Chinese suppliers dominating lithium-ion cell supply. IGBT modules and rare-earth magnets for inverters draw from concentrated East Asian foundries, exposing procurement to single-source vulnerability in semiconductor-grade silicon. Distribution runs through factory-direct channels for hyperscale accounts and regional systems integrators for enterprise and colocation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
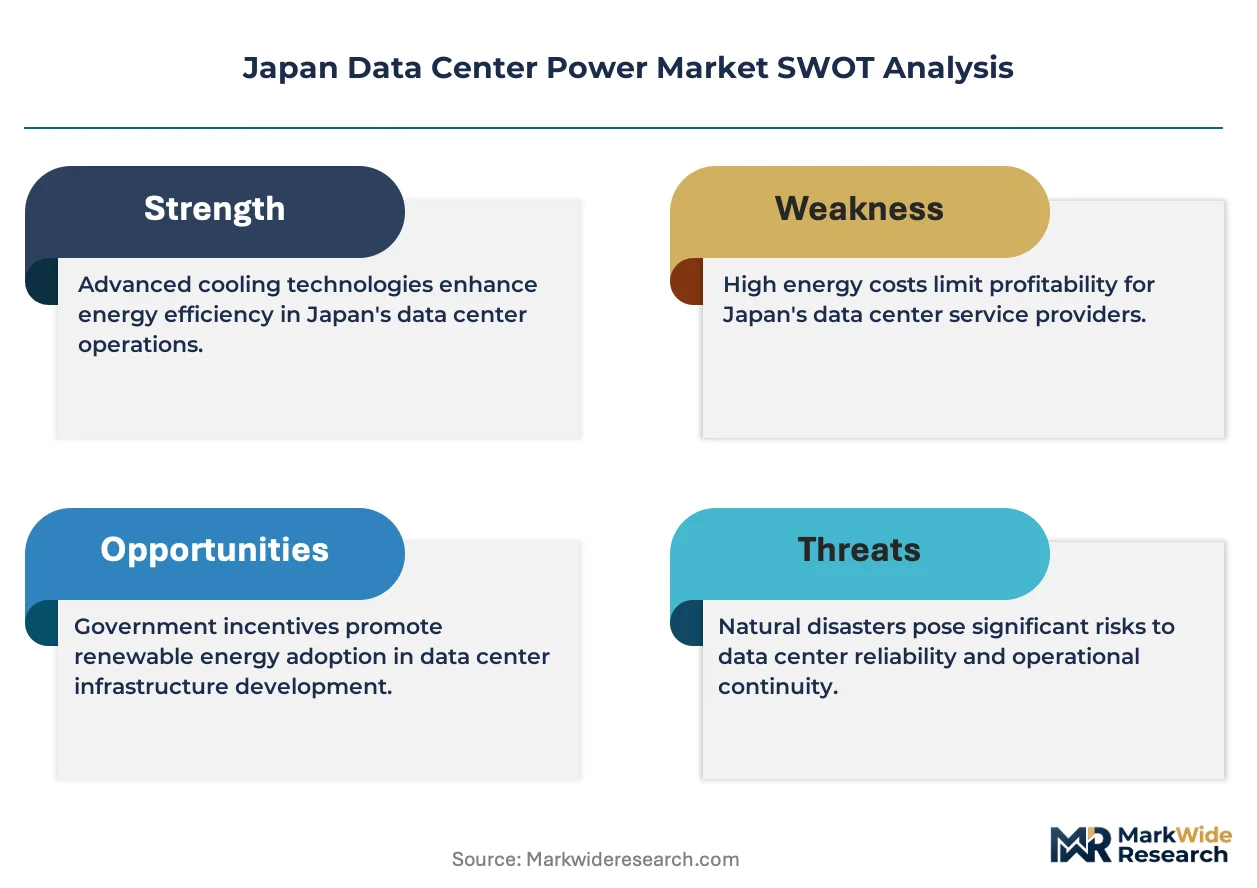
Japan's data center power market operates under acute supply constraints, with seismic engineering certification bottlenecks limiting qualified vendor pools and propping pricing premiums for JIS-grade equipment.
For Market Incumbents: To counter factory-direct disintermediation by global hyperscale operators, Mitsubishi Electric and Hitachi Energy should deepen captive supply of IGBT modules through backward integration into power semiconductor fabrication. Channel control investments in predictive maintenance software platforms can extend service attach rates beyond equipment sale, preserving margin pools as hardware commoditization accelerates. For New Entrants and Emerging Players: Capture white-space opportunity in solid-state battery integration for Tohoku edge facilities, where post-Fukushima grid diversification policies create procurement appetite for novel storage architectures. Kyushu's emerging Fukuoka cluster offers penetrable geography with less severe TEPCO transmission saturation than Kanto. A go-to-market angle anchored in lithium-ion buffered microgrid turnkey solutions bypasses incumbent dominance in conventional UPS. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized UPS fabricators with seismic engineering expertise in Greater Tokyo Area, where land scarcity premiums sustain equipment pricing power. Long-term viability hinges on hydrogen-ready product line transitions aligned with METI decarbonization enforcement. Practitioners should monitor Kanto hydrogen corridor commercialization timelines and fuel cell deployment ramp rates as inflection indicators for conventional generator asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Product Line Transition | Positions vendors ahead of METI-mandated diesel displacement in Tokyo Bay facilities. |
| Factory-Direct Service Model Expansion | Bypasses local integrator margins and captures hyperscale procurement standardization. |
| Solid-State Battery Pilot Deployment | Opens margin expansion in Tohoku edge facilities buffering renewable intermittency. |
| Grid-Interactive UPS Platform Development | Monetizes frequency regulation services during seismic grid events in Kanto. |
| Seismic Certification Renewal Investment | Preserves vendor qualification pools under tightening JIS earthquake-resistant standards. |
Research Methodology
Multi-period observation of METI efficiency benchmark compliance, PUE disclosure filings, and hydrogen infrastructure buildout timelines anchored the trend analysis, supplemented by interviews with data center engineering directors, electrical infrastructure procurement managers, utility interconnection planners, and fuel cell system integrators. Secondary validation drew from METI annual reports, TEPCO transmission capacity disclosures, JIS standards documentation, and hyperscaler capex announcements. Bottom-up equipment shipment tracking and top-down facility investment aggregation enabled triangulation across independent analytical paths.
Segment-weighting approaches distributed value estimates across power type, end user scale, service attach rate, and voltage architecture dimensions throughout the forecast period. CAGRs were derived from fitted growth curves against historical deployment trajectories, with AI training cluster power density requirements and fuel cell commercialization curves as industry-specific demand inputs. Modeling incorporated grid interconnection queue durations and seismic certification qualification timelines as supply-side constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen supply chain maturation rates and METI enforcement intensity for renewable power ratios. Practitioners should monitor Kanto hydrogen corridor commercialization milestones and hyperscale fuel cell procurement announcements for early signals of diesel generator displacement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
APAC Data Center Server Market