
 Industrial IoT Platform Market | 2026-2036
Industrial IoT Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial IoT Platform Market Outlook
Multi-source platform procurement is expanding as industrial buyers diversify away from single-vendor lock-in. Siemens AG leverages its automation hardware heritage to anchor integrated edge-to-cloud offerings across European manufacturing. Microsoft Corporation competes through Azure IoT's developer ecosystem and enterprise software integration. Amazon Web Services, Inc. controls hyperscale infrastructure economics while extending industrial-specific data services through partner networks.
An industrial IoT platform is a software layer that ingests telemetry from sensors, PLCs, and SCADA systems to enable real-time analytics, device management, and application development across distributed operations. These platforms typically support millisecond-latency edge processing alongside cloud-based model training to balance responsiveness with computational depth. Predictive maintenance applications command the deepest margin pools due to measurable downtime reduction and high switching costs once algorithms are trained on asset-specific failure patterns. Cloud-based deployments lead in new customer acquisition because they eliminate capital infrastructure, though hybrid architectures are gaining traction among oil and gas operators with intermittent connectivity and stringent data residency requirements.
The EU AI Act classifies certain industrial IoT analytics as high-risk systems, mandating conformity assessments that reshape product roadmaps for vendors serving European manufacturing. In the United States, NIST cybersecurity frameworks and SEC climate disclosure rules push platform providers to embed audit trails and emissions tracking into core architectures. China's MIIT GB standards and data security law impose localization requirements that fragment platform architectures for multinational deployments. Stakeholders must evaluate whether their platform stack can adapt to diverging regulatory jurisdictions without multiplying engineering overhead.
Market Dynamics
Platform procurement patterns are fragmenting as industrial buyers reject single-vendor dependency, forcing architecture redesigns around interoperability standards and multi-cloud orchestration layers.
Growth Catalysts
- EU AI Act compliance mandates:High-risk system classifications for predictive maintenance algorithms drive platform upgrades across German automotive and French aerospace supply chains.
- Edge computing maturation:Sub-10ms latency requirements in oil and gas upstream operations accelerate hybrid deployment architectures balancing local inference with cloud model refinement.
- China MIIT localization rules:Data residency requirements under GB standards fragment multinational platform stacks, creating dedicated engineering roadmaps for domestic manufacturing deployments.
Market Restraints
- Semiconductor supply concentration:Edge gateway chip dependency on Taiwanese foundries exposes platform hardware roadmaps to geopolitical disruption and allocation volatility.
- OT-IT integration complexity:Legacy SCADA protocol fragmentation across brownfield manufacturing sites inflates deployment timelines and professional services intensity.
- EU NIS2 cybersecurity scope expansion:Extended liability for critical infrastructure operators tightens vendor qualification requirements and extends sales cycles.
Strategic Opportunities
- India PLI manufacturing incentives:Electronics and automotive component production subsidies create greenfield factory automation demand requiring integrated platform stacks.
- Digital twin convergence:Physics-based simulation merging with real-time telemetry opens new pricing models for asset-intensive process industries.
- US SEC climate disclosure rules:Emissions tracking mandates position industrial IoT platforms as mandatory compliance infrastructure for Scope 1-3 reporting.
Industry Challenges
- Embedded systems security expertise scarcity:Shortage of engineers fluent in both operational technology protocols and modern zero-trust architectures constrains platform feature velocity.
- Multi-jurisdiction certification parallelism:Divergent conformity assessment requirements across EU AI Act, US FDA software-as-medical-device pathways, and China GB standards multiply quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial IoT Platform Market |
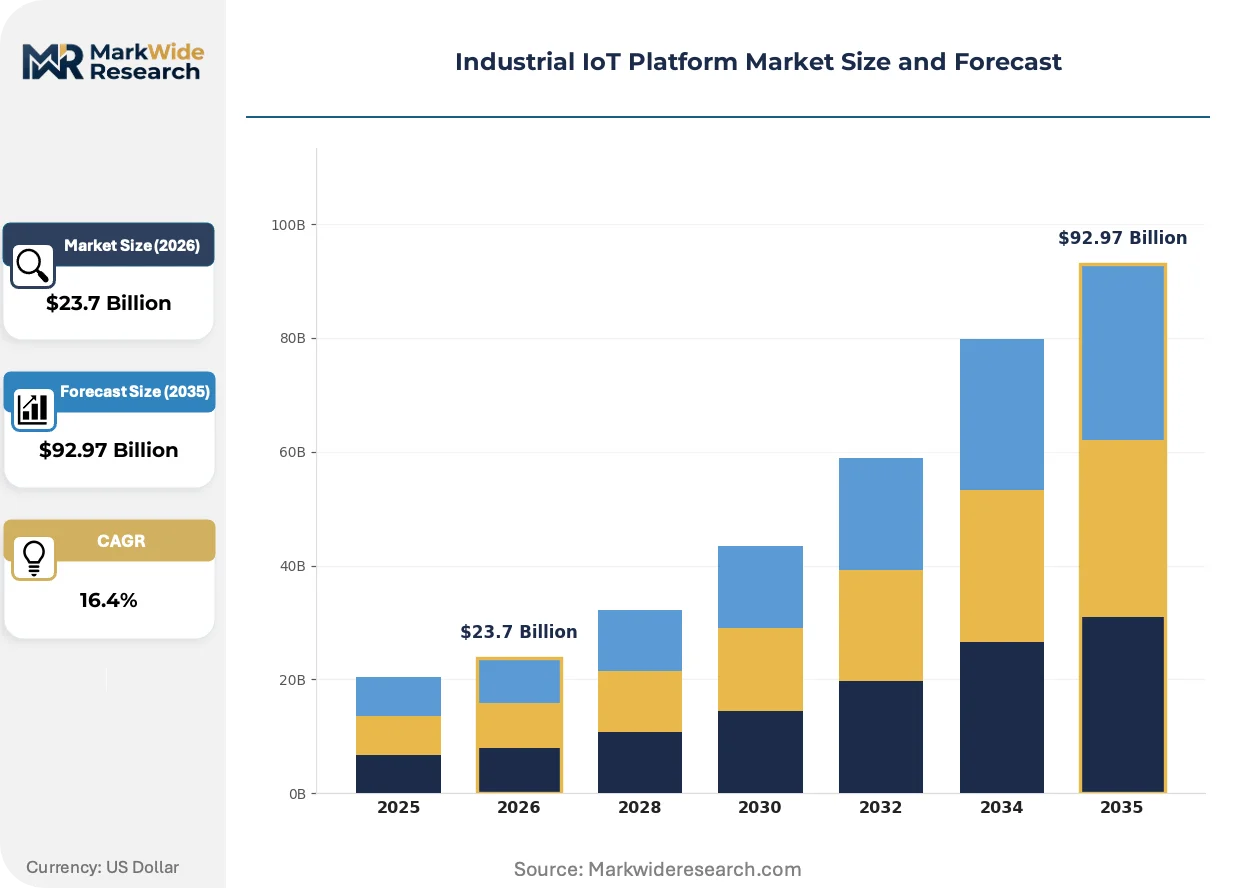
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $92.97 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Predictive Maintenance, Remote Monitoring, Asset Tracking, Supply Chain Optimization Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Manufacturing, Oil & Gas, Utilities, Smart Buildings Technology: Machine Learning, Big Data Analytics, Blockchain, RFID |
| Companies Covered | IBM Corporation, Microsoft Corporation, Siemens AG, PTC Inc., Amazon Web Services, Inc., Cisco Systems Inc, General Electric Company, Rockwell Automation Inc., ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial IoT Platform Market Strategic Shifts
Industrial platform architectures are rebalancing from cloud-centric to edge-distributed topologies as latency-sensitive applications and data sovereignty requirements reshape deployment patterns.
Time-sensitive networking is converging with 5G private cellular to enable deterministic wireless control loops in motion-intensive manufacturing cells. Automotive and semiconductor fabs are piloting these unified connectivity fabrics for synchronized robotics coordination. This convergence is compressing the traditional separation between machine-level fieldbus systems and enterprise Ethernet backbones.
The EU AI Act's high-risk system classification is mandating algorithmic audit trails and human-in-the-loop overrides for predictive maintenance modules deployed in energy and transport infrastructure. Platform vendors must embed explainability interfaces and conformity documentation into core product architectures. European manufacturing buyers are now prioritizing these compliance-native features in procurement evaluations.
Industrial buyers are consolidating vendor relationships around platform-agnostic system integrators capable of orchestrating multi-cloud telemetry pipelines. Oil and gas operators in the US Gulf Coast and North Sea clusters increasingly specify integrator-led deployments over direct platform licensing. This channel shift is reallocating margin pools from pure software vendors toward implementation and managed services specialists.
Industrial IoT Platform Market Segmentation
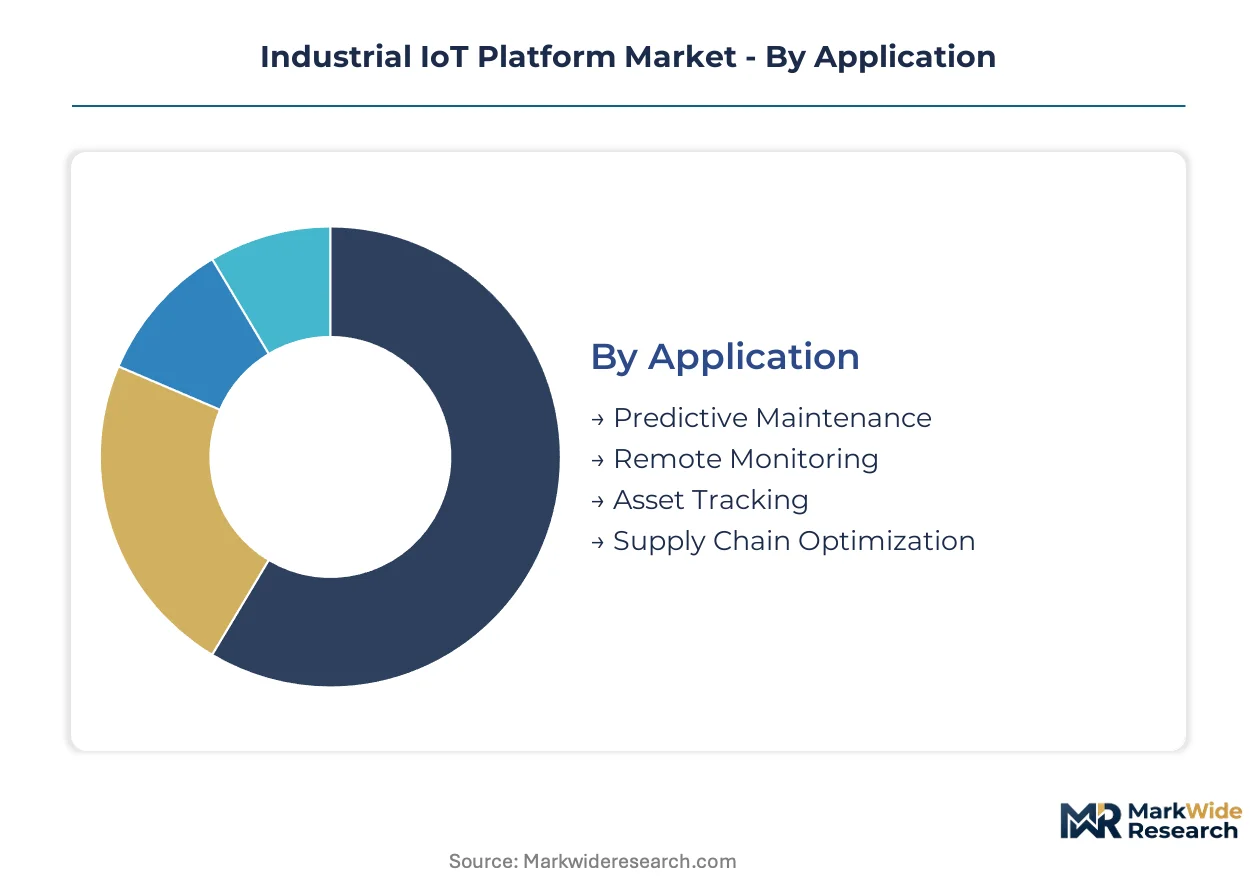
Industrial IoT platform buyers segment procurement across application criticality, deployment topology, and operational technology maturity. Vendors architect modular pricing and integration pathways around these fracture lines to capture diverse factory automation budgets and compliance postures.
Application:
Customization intensity varies sharply across this category, from standardized telemetry dashboards to bespoke failure-mode algorithms requiring months of asset-specific training.
- Predictive Maintenance:Platforms ingest vibration, thermal, and electrical signature data to train asset-specific failure models. German automotive suppliers and French aerospace manufacturers dominate procurement as EU AI Act conformity assessments mandate explainable anomaly detection for high-risk machinery.
- Remote Monitoring:Real-time visibility into distributed equipment fleets via centralized dashboards. Oil and gas operators in the US Gulf Coast deploy these modules for offshore platform oversight where crew rotation costs exceed sensor infrastructure investment.
- Asset Tracking:Location and condition monitoring for mobile industrial equipment. Mining operations in Western Australia and Chilean copper belts drive uptake for fleet utilization optimization.
- Supply Chain Optimization:Inventory synchronization and logistics orchestration across tiered supplier networks. Electronics manufacturers in Vietnam and Mexico leverage these capabilities for just-in-time component flow management.
Most installed capacity flows through Predictive Maintenance. Expansion is steepest in Supply Chain Optimization.
Deployment:
Cost tier stratification shapes procurement, with capital-constrained mid-market manufacturers favoring subscription models while regulated industries absorb higher upfront expenditure for data sovereignty.
- Cloud-Based:Multi-tenant SaaS architectures eliminating on-site infrastructure. Small and medium manufacturers in India and Brazil adopt these deployments fastest where IT staffing scarcity favors outsourced operations.
- On-Premises:Dedicated hardware stacks within facility firewalls. China's MIIT data localization requirements and EU GDPR processing constraints compel this topology for semiconductor fabs and pharmaceutical packaging lines handling sensitive telemetry.
- Hybrid:Orchestrated edge-cloud pipelines with selective data gravity. Oil and gas upstream operators in Norway and Saudi Arabia specify hybrid architectures for intermittent offshore connectivity and reservoir data residency compliance.
- Edge Computing:Sub-10ms latency processing at the source. Motion-intensive robotics cells in Japanese automotive plants and German machine tool factories deploy edge nodes for deterministic control loop closure.
Cloud-Based deployments hold the largest installed base. Edge Computing is climbing the fastest as latency requirements harden.
End User:
Customer type determines integration complexity, with brownfield manufacturing sites demanding extensive protocol translation versus greenfield smart building deployments.
- Manufacturing:Discrete and process automation spanning automotive, electronics, and food processing. German Industrie 4.0 programs and US reshoring incentives accelerate platform procurement for factory digitization.
- Oil & Gas:Upstream exploration, midstream pipeline monitoring, and downstream refining optimization. North Sea operators and Permian Basin producers drive demand for hazardous-area-certified edge hardware.
- Utilities:Grid modernization and distributed energy resource management. Italian and Spanish utilities deploy platforms for renewable intermittency balancing and substation automation.
- Smart Buildings:HVAC, lighting, and occupancy optimization across commercial portfolios. Singapore and UAE commercial real estate developers specify these systems for green building certification compliance.
Manufacturing accounts for the dominant share of deployed nodes. Smart Buildings is gaining share fastest as ESG reporting mandates tighten.
Technology:
Supply concentration in enabling components—GPU accelerators, specialized ASICs, and protocol stacks—shapes vendor margin structures and roadmap velocity.
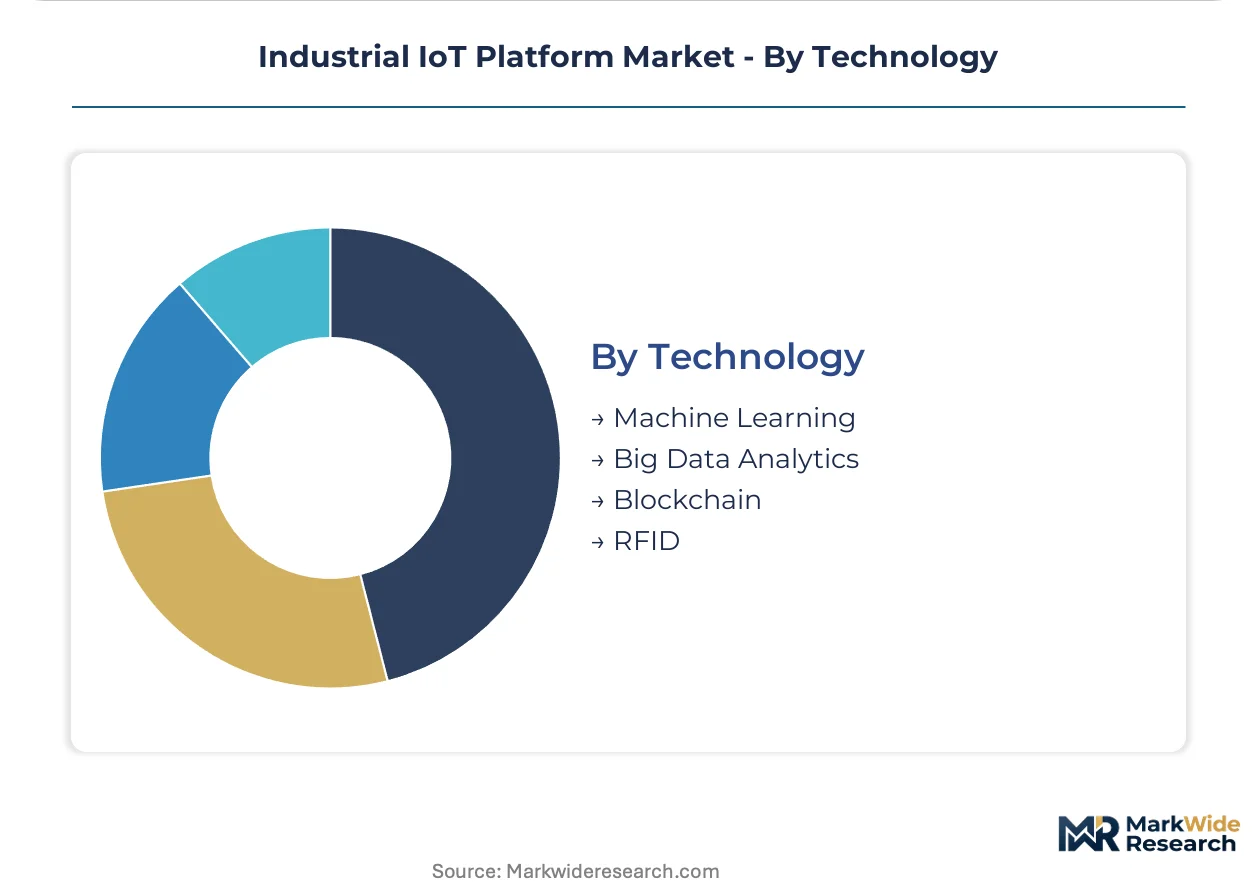
- Machine Learning:Supervised and unsupervised model training for pattern recognition and anomaly detection. Predictive maintenance modules rely on these capabilities for failure prediction accuracy.
- Big Data Analytics:Time-series aggregation and correlation across high-velocity sensor streams. Utilities and process manufacturers deploy these engines for operational efficiency benchmarking.
- Blockchain:Immutable audit trails for supply chain provenance and regulatory compliance. Pharmaceutical serialization and conflict mineral tracking drive niche adoption.
- RFID:Passive and active tag systems for asset identification and location. Warehouse automation and retail distribution centers leverage these for inventory accuracy.
Big Data Analytics infrastructure underpins the majority of deployed platforms. Machine Learning is expanding most quickly as EU AI Act explainability requirements mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial clusters anchor platform procurement intensity, with German automotive suppliers and French aerospace manufacturers driving compliance-heavy deployments across European manufacturing belts.
Germany
Automotive component factories in Stuttgart and Wolfsburg deploy predictive maintenance platforms to satisfy EU AI Act high-risk system classifications for critical machinery. The Bundesamt für Sicherheit in der Informationstechnik enforces NIS2 cybersecurity scope expansions that tighten vendor qualification requirements. Siemens AG leverages its automation heritage to anchor integrated edge-to-cloud offerings across Bavarian and North Rhine-Westphalian production networks.
United States
Oil and gas operators in the Permian Basin and Gulf Coast specify hybrid architectures for intermittent offshore connectivity and reservoir data residency compliance. The SEC climate disclosure rules push platform providers to embed audit trails and emissions tracking into core architectures. Microsoft Corporation competes through Azure IoT's developer ecosystem and enterprise software integration across Houston and Denver energy corridors.
China
Semiconductor fabs in Shanghai and Beijing-Tianjin-Hebei corridors absorb MIIT GB standards and data security law localization requirements that fragment multinational platform stacks. The dual carbon goals accelerate smart factory digitization programs. Domestic platform engineering roadmaps diverge from global architectures to satisfy data residency mandates for pharmaceutical packaging and electronics assembly lines.
India
Electronics manufacturers in Tamil Nadu and Karnataka leverage PLI scheme subsidies to build greenfield automation requiring integrated platform stacks. The Bureau of Indian Standards develops conformity frameworks for industrial IoT cybersecurity. Automotive component producers in Pune and Chennai clusters procure cloud-based deployments fastest where IT staffing scarcity favors outsourced operations.
Japan
Motion-intensive robotics cells in Toyota City and Nagoya automotive plants deploy edge nodes for deterministic control loop closure under 10 milliseconds. METI's Society 5.0 initiative funds smart manufacturing infrastructure upgrades. Machine tool factories in Osaka-Kobe corridors pilot time-sensitive networking converged with 5G private cellular for synchronized robotics coordination.
Industrial IoT Platform Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized edge analytics and sector-specific compliance modules. The vendor base concentrates around three strategic archetypes: automation hardware incumbents extending software layers, hyperscale cloud providers industrializing infrastructure services, and pure-play platform vendors building developer ecosystems. Siemens AG and Microsoft Corporation anchor opposing integration philosophies. Competitive moves center on multi-cloud orchestration partnerships and conformity assessment pre-certification to accelerate European sales cycles.
Within the automation-heritage tier, Siemens AG and ABB Ltd. represent integrated hardware-software positioning, while Microsoft Corporation exemplifies cloud-native platform economics. IBM Corporation and Amazon Web Services, Inc. occupy enterprise IT and hyperscale infrastructure positions respectively. PTC Inc. and Rockwell Automation Inc. sit within the industrial software specialization segment. Cisco Systems Inc. anchors networking-centric platform architectures. General Electric Company represents asset-intensive industry verticalization. These archetypes reflect procurement fragmentation as buyers reject single-vendor dependency.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Siemens AG |
| PTC Inc. |
| Amazon Web Services, Inc. |
| Cisco Systems Inc |
| General Electric Company |
| Rockwell Automation Inc. |
| ABB Ltd. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up system integrators now dominate mid-market platform deployment, compressing vendor margins through volume aggregation while passing through semiconductor cost volatility into hybrid-architecture premiums.
Pricing Analysis
Input-cost pass-through from GPU accelerators and edge-gateway ASICs drives subscription-tier repricing, with cloud-native SaaS deployments absorbing tariff exposure more readily than on-premises hardware bundles. Price differentiation hinges on EU AI Act conformity documentation and NIS2 cybersecurity certification tiers, with German automotive buyers least sensitive and Indian PLI-scheme manufacturers most price-responsive. Cost compression in edge-computing hardware is intensifying because Taiwanese foundry allocation constraints persist. Margins are tightening for pure-play platform vendors lacking automation hardware anchoring.
Supply Chain Analysis
Certification gating through BSI, TÜV, and UL cybersecurity qualifications fragments qualified supplier pools, concentrating edge-gateway manufacturing in Taiwan, South Korea, and Germany. Component dependencies center on NVIDIA GPU accelerators, ARM-based edge processors, and time-sensitive networking chipsets. Single-source vulnerability in advanced-node semiconductor fabrication exposes platform hardware roadmaps to geopolitical disruption. Distribution runs through automation-heritage channel partners and hyperscale cloud marketplaces, with system integrators capturing implementation margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU AI Act compliance costs in Stuttgart and Wolfsburg run triple those in Tamil Nadu and Karnataka, creating divergent platform procurement economics.
For Market Incumbents: Anchor integrated edge-to-cloud offerings through backward integration into hazardous-area-certified hardware, defending against pure-play platform vendors encroaching from cloud-native positions. Prioritize NIS2 pre-certification investments to compress European sales cycles before regulatory deadlines harden. Capacity addition in Indian PLI corridors captures greenfield factory automation demand ahead of domestic platform engineering roadmaps maturing. For New Entrants and Emerging Players: System integrators represent the fastest path to revenue, offering immediate access to oil and gas operator procurement committees in the Permian Basin and North Sea clusters. Target cloud-based predictive maintenance modules for Indian electronics manufacturers, where IT staffing scarcity favors outsourced operations. White-space exists in physics-based digital twin convergence for process industries, underserved by incumbent automation hardware vendors. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking software layer capabilities to complement hardware heritage. Five-to-ten-year viability hinges on multi-jurisdiction certification parallelism capabilities, with EU AI Act explainability modules and China MIIT localization engineering as durable moats. The signal to watch is consolidation velocity among mid-cap system integrators, indicating channel control tipping toward implementation specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure IoT and Siemens MindSphere convergence addresses German automotive AI Act compliance requirements. |
| Acquisition of Specialist Firm | Edge analytics boutiques with sub-10ms latency expertise command premium valuations from oil and gas operators. |
| Strategic Partnership | Time-sensitive networking alliances with 5G private cellular vendors unlock Japanese automotive robotics coordination. |
| Geographic Expansion | India PLI corridor presence captures electronics and automotive component greenfield automation demand. |
| Product Launch | EU AI Act-native explainability interfaces accelerate procurement evaluations from French aerospace manufacturers. |
Study Parameters
Bottom-up manufacturing deployment modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core, combining primary interviews with plant engineers, OT-IT integration specialists, platform procurement officers, and system integrator principals against secondary validation through SEC filings, MIIT GB standard disclosures, EU AI Act implementation guidance, and hyperscaler capex reports.
Input-output matrix framing connects edge-gateway unit economics to cloud-services revenue recognition across deployment topology, application criticality, and operational technology maturity dimensions. CAGRs derive from segment-level adoption curves weighted by regulatory compliance deadlines and factory digitization program timelines. Forecast inputs include semiconductor allocation volatility indices and EU NIS2 vendor qualification velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan Strait geopolitical disruption, EU AI Act enforcement intensity, and China data localization mandate expansion. A model refresh is warranted upon material change in edge-computing chip supply allocation or EU conformity assessment harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
IoT Application Enablement Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
Global IoT Engineering Services Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
Cellular IoT Module Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
Smart Tracker Market