
 Ireland Data Center Power Market | 2026-2036
Ireland Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Data Center Power Market Insights
Hyperscale cloud operators are redrawing procurement priorities in Ireland's data center power landscape. Schneider Electric SE leverages its integrated EcoStruxure platform to anchor large-scale deployments across the island. Eaton Corporation plc competes through advanced power distribution units designed for high-density workloads. Vertiv Group Corp. specializes in thermal management systems that sustain uptime under Ireland's temperate but variable climate conditions.
Ireland Data Center Power encompasses the generation, conditioning, distribution, and backup systems that ensure continuous electrical supply to server facilities, typically operating at voltages from 400V to 33kV with redundancy tiers from N to 2N+1. The primary purpose is eliminating downtime for digital infrastructure serving European and transatlantic data traffic. Diesel generators still dominate the backup power segment though renewable energy integration is accelerating fastest as hyperscale operators face Scope 3 pressure. Liquid cooling is displacing legacy air systems in new builds as rack densities exceed 50kW per cabinet, concentrating margin pools with specialized infrastructure providers.
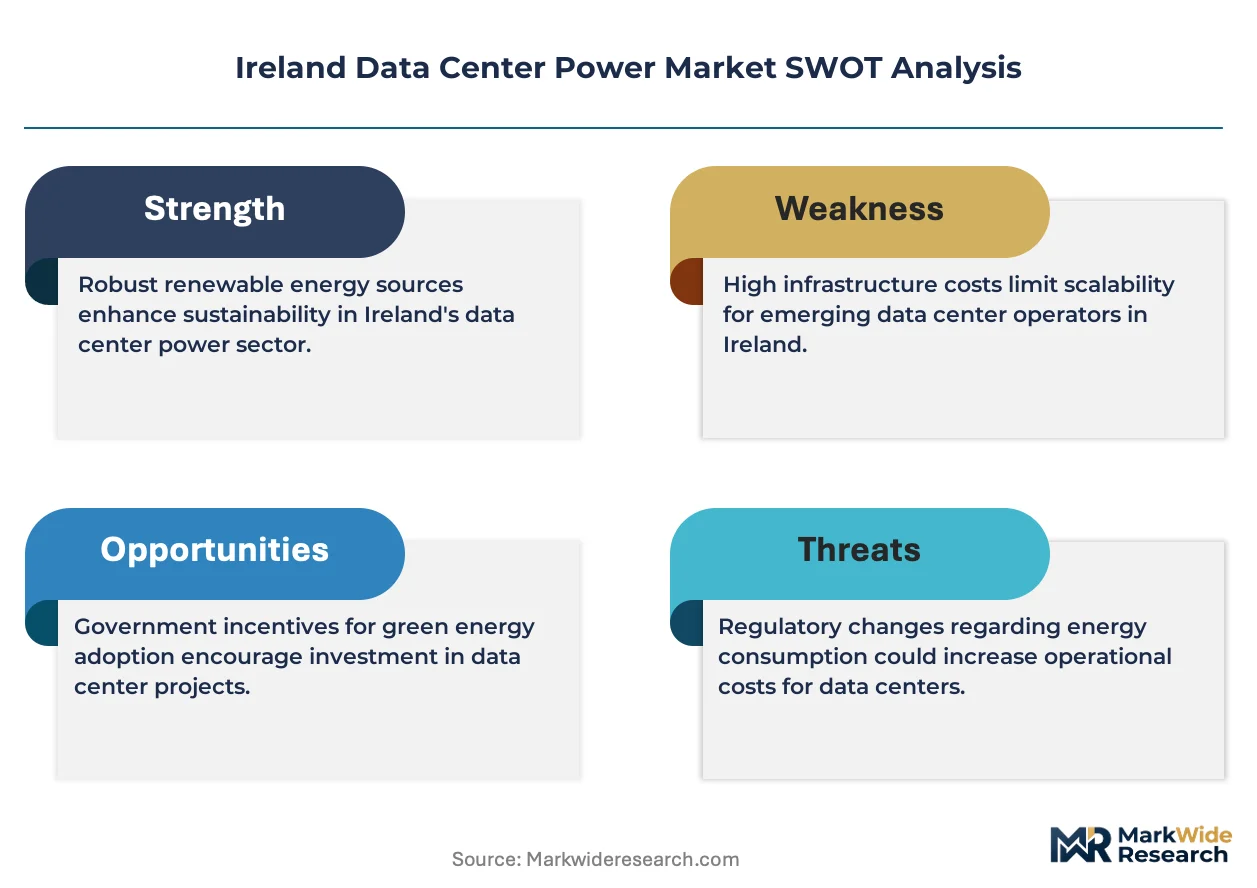
EirGrid governs grid connection standards while the EPA enforces emissions limits on backup generation, collectively pushing operators toward battery storage and green power purchase agreements. The Commission for Regulation of Utilities shapes tariff structures that influence where capacity clusters develop. Stakeholders must monitor how Ireland's planning permissions interact with national renewable targets and grid reinforcement timelines.
Market Dynamics
EirGrid connection queue congestion is compressing project timelines while hyperscale operators compete for limited substation capacity across the Greater Dublin Area. This grid-access bottleneck is restructuring how power infrastructure gets financed, built, and commissioned.
Growth Catalysts
- EPA emissions standards:Tightening limits on diesel backup generation are accelerating battery storage and renewable power purchase agreement adoption among facility operators.
- Liquid cooling systems:Rack densities exceeding 50kW per cabinet are pulling demand for advanced thermal management solutions that sustain uptime under variable Irish climate conditions.
- Greater Dublin Area:Fiber and power infrastructure intersection is concentrating hyperscale investment in this corridor, creating clustering effects that attract secondary suppliers.
Market Restraints
- Grid connection delays:EirGrid queue backlogs are extending project timelines by 18-36 months for new facilities seeking 33kV supply.
- Transformer supply concentration:European specialist manufacturers control high-capacity unit production, creating vulnerability for Irish projects requiring 10MVA+ substations.
- Copper price volatility:Busbar and cable costs fluctuate with commodity markets, compressing margins on fixed-price EPC contracts.
Strategic Opportunities
- Cork and Limerick:Secondary cities outside Dublin offer available grid capacity and planning permissions with shorter approval cycles.
- Behind-the-meter solar:On-site photovoltaic integration pairs with battery storage to reduce grid dependency and Scope 2 emissions exposure.
- Commission for Regulation of Utilities tariff reform:Proposed demand-response incentives would reward flexible load operators for grid stabilization services.
Industry Challenges
- High-voltage commissioning expertise:Qualified 33kV switchgear specialists are scarce, extending handover timelines and inflating contractor rates.
- Legacy air-cooling retrofit complexity:Existing facilities face disruptive infrastructure overhauls to accommodate liquid cooling manifolds and heat rejection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Data Center Power Market |
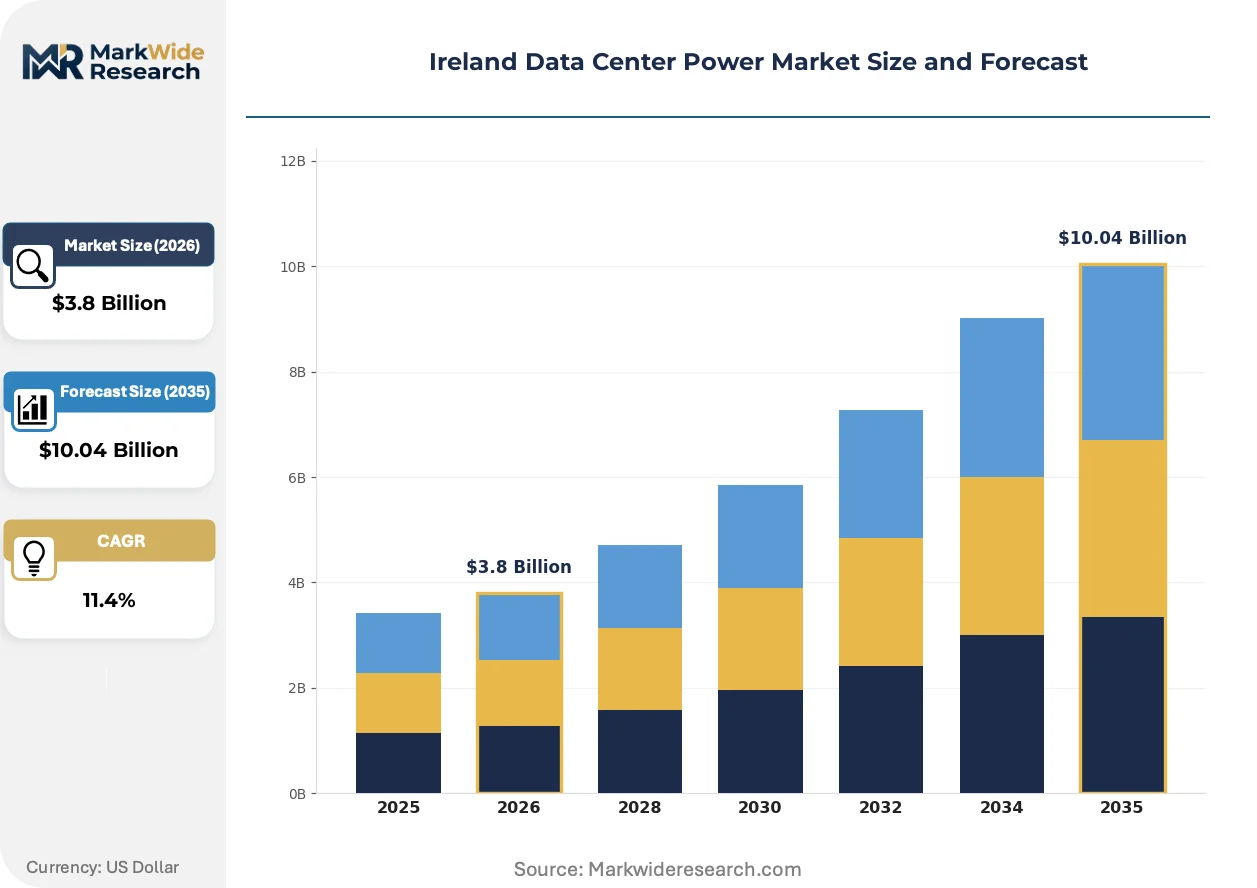
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Grid Supply, Diesel Generators, Uninterruptible Power Supply Facility Type: Hyperscale Data Centers, Colocation Facilities, Edge Data Centers, Enterprise Data Centers Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Immersion Cooling End User: Cloud Service Providers, IT Companies, Telecommunications, Financial Services |
| Companies Covered | ABB Ltd., Eaton Corporation plc, Schneider Electric SE, Vertiv Group Corp., Caterpillar Inc., Cummins Inc., Delta Electronics Inc., Rolls-Royce Power Systems, Legrand Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Data Center Power Market Trends and Innovations
Power infrastructure architecture is diverging from standardized designs as workload-specific requirements fragment procurement patterns. Operators now specify modular, scalable systems that adapt to uncertain density trajectories.
Liquid cooling manifolds and immersion tanks are fragmenting the thermal management landscape. Hyperscale operators are specifying direct-to-chip and single-phase immersion systems for AI training clusters. This technology divergence is compressing margins for air-cooling specialists while opening niche positions for fluid chemistry and heat exchanger vendors.
The Commission for Regulation of Utilities is revising connection charging methodologies to reflect locational network constraints. This policy shift will penalize Dublin-clustered projects while rewarding dispersed development. Facility planners are responding by accelerating site screening in Cork, Limerick, and regional towns with available transmission capacity.
Power purchase agreement structures are evolving from fixed-price renewables contracts to 24/7 carbon-free energy matching. Hyperscale buyers now require hourly generation-consumption alignment rather than annualized certificates. This behavioral shift is most visible among cloud operators with European sustainability commitments, who are contracting directly with offshore wind developers for firm supply.
Ireland Data Center Power Market Segmentation
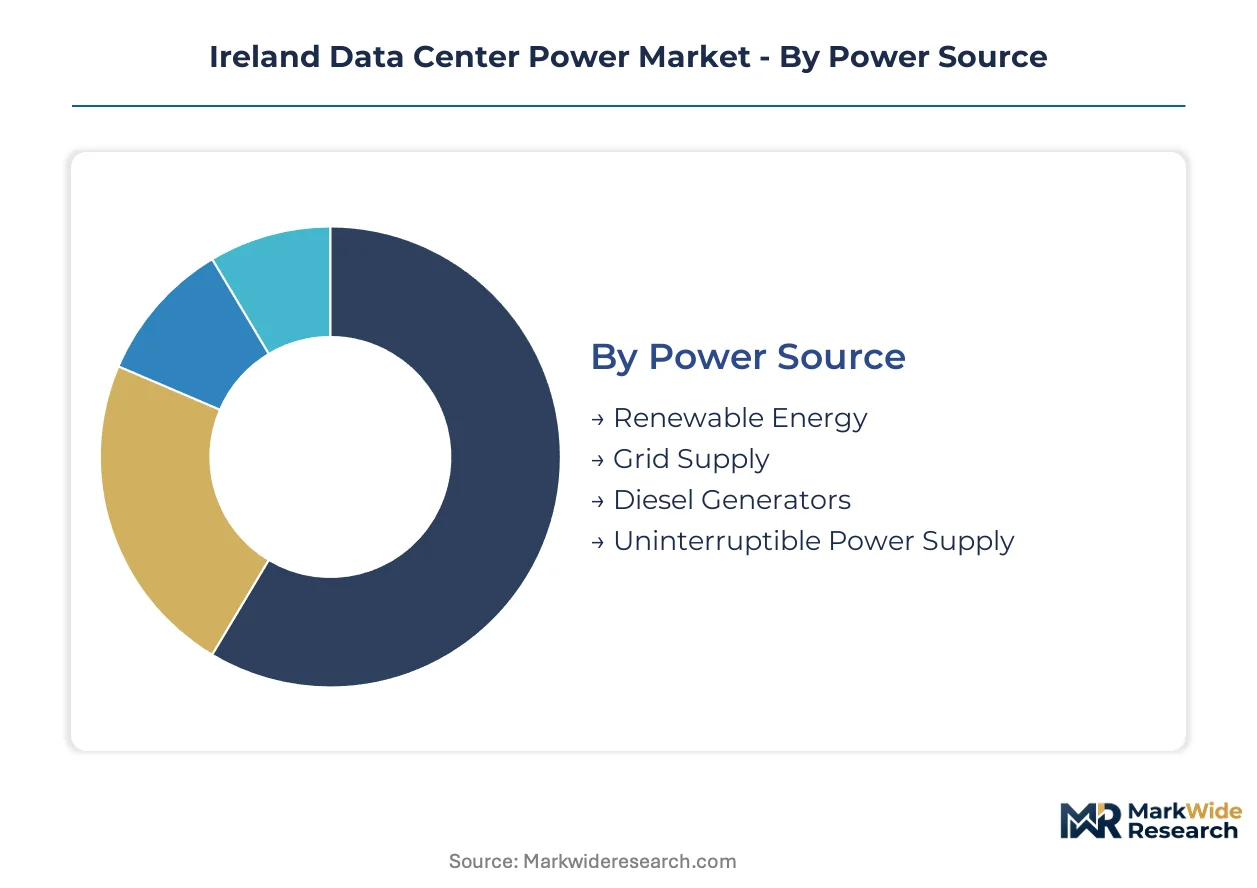
Segmentation in Ireland's data center power market reveals where capital allocation concentrates as grid constraints and density requirements reshape procurement priorities. Understanding these divisions exposes which infrastructure configurations capture hyperscale investment versus legacy upgrade cycles.
Power Source:
Grid Supply faces the most acute substitution pressure as EirGrid queue delays push operators toward behind-the-meter alternatives and battery storage configurations.
- Renewable Energy:Power purchase agreements with offshore wind developers and on-site solar photovoltaic arrays deliver hourly carbon-free energy matching for Scope 2 compliance. Hyperscale operators in the Greater Dublin Area contract directly with developers to bypass grid interconnection bottlenecks.
- Grid Supply:EirGrid-managed transmission at 33kV to 110kV serves as primary baseload for established facilities. Connection queue congestion extending 18-36 months is forcing new entrants toward secondary locations in Cork and Limerick where substation capacity remains available.
- Diesel Generators:Legacy backup systems dominate existing facilities but face tightening EPA emissions limits.
- Uninterruptible Power Supply:Battery energy storage systems displace rotating machinery for short-duration ride-through.
Grid Supply retains volume leadership; Renewable Energy holds the steepest expansion curve.
Facility Type:
Cost tier stratification separates hyperscale deployments with dedicated substations from multi-tenant facilities sharing infrastructure.
- Hyperscale Data Centers:Single-tenant facilities exceeding 50MW demand dedicated 33kV connections and custom switchgear configurations. Microsoft, Amazon, and Google anchor development in the Greater Dublin Area despite grid constraints.
- Colocation Facilities:Multi-tenant environments aggregate demand across enterprise clients with standardized power densities. Operators in Cork and Limerick attract secondary market entrants seeking faster commissioning timelines.
- Edge Data Centers:Distributed sub-10MW facilities target latency-sensitive workloads outside Dublin.
- Enterprise Data Centers:Captive facilities serving single organizations face legacy air-cooling retrofit complexity.
Hyperscale Data Centers command the capital deployment; Edge Data Centers are expanding most quickly outside the capital region.
Cooling Technology:
Application-specific thermal requirements fragment procurement as AI training clusters diverge from general compute densities.
- Liquid Cooling:Direct-to-chip and single-phase immersion systems sustain rack densities exceeding 50kW per cabinet for AI workloads. Hyperscale operators specify manifolds and heat rejection systems that adapt to Ireland's temperate but variable climate.
- Air Cooling:Legacy raised-floor configurations with computer room air handlers serve sub-30kW densities. Existing facilities in the Greater Dublin Area face disruptive infrastructure overhauls to accommodate liquid cooling manifolds.
- Evaporative Cooling:Adiabatic systems leverage Ireland's moderate wet-bulb temperatures for free cooling cycles.
- Immersion Cooling:Two-phase systems for extreme density deployments remain niche but attract specialized fluid chemistry vendors.
Air Cooling retains installed base dominance; Liquid Cooling gains share fastest as rack densities climb.
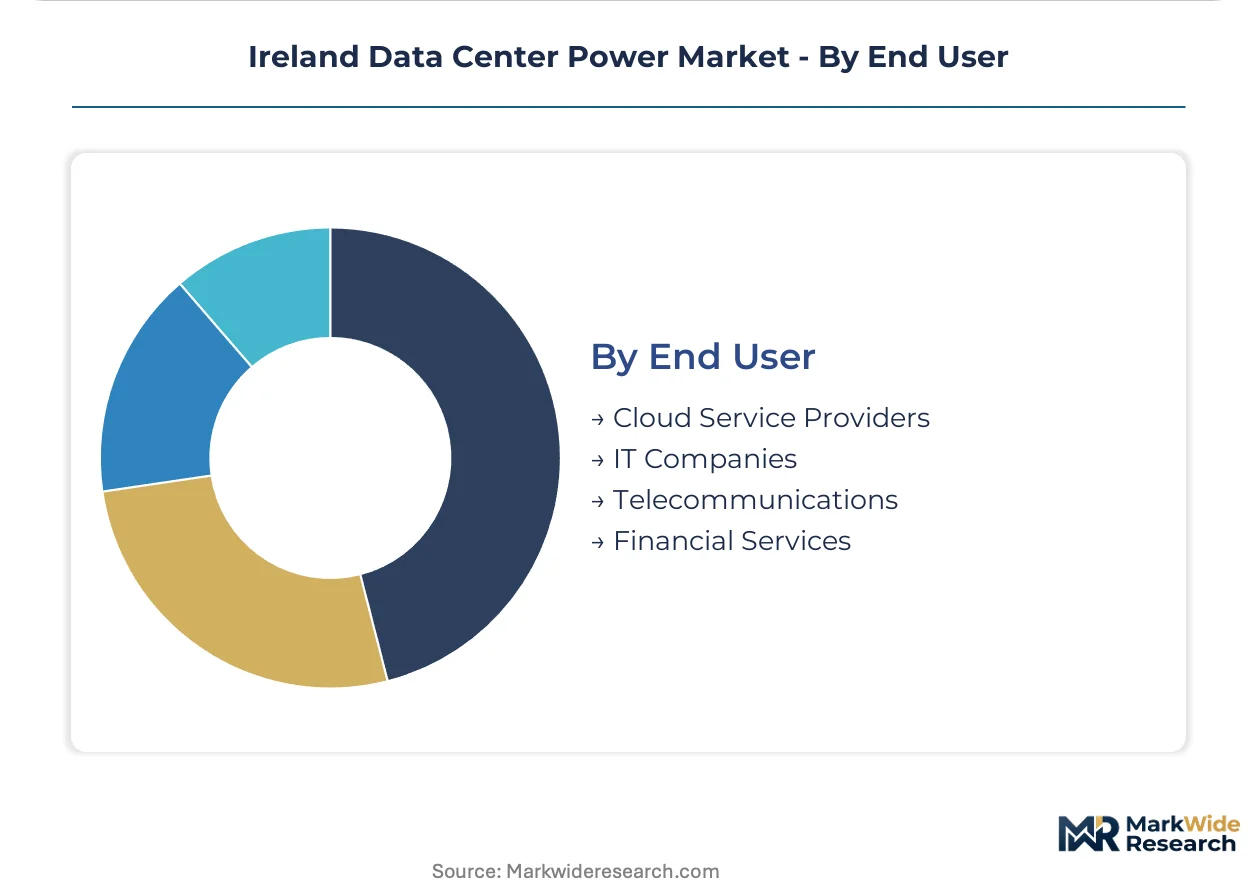
End User:
Customer type determines redundancy tier requirements and renewable energy procurement sophistication.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform drive 2N+1 redundancy standards and 24/7 carbon-free energy matching. Their European sustainability commitments reshape power purchase agreement structures across the island.
- IT Companies:SaaS providers and technology vendors operate N+1 configurations with annualized renewable energy certificates rather than hourly matching.
- Telecommunications:Carrier-neutral facilities prioritize uptime over density with traditional diesel backup architectures.
- Financial Services:Dublin-based banks and payment processors demand Tier III certification with regulatory scrutiny of operational resilience.
Cloud Service Providers anchor procurement volume; Financial Services demonstrate the steepest sustainability compliance trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ireland exports data center capacity to European cloud users and transatlantic traffic corridors. Dublin's fiber-rich infrastructure draws hyperscale investment despite grid constraints. Secondary cities compete on available substation capacity and faster planning permissions.
Greater Dublin Area
Hyperscale operators from Microsoft, Amazon, and Google cluster here for transatlantic cable landing points. EirGrid connection queue delays now extend 18-36 months for new 33kV supply requests. Tallaght and Clonee host the densest power infrastructure concentrations as operators retrofit legacy facilities for liquid cooling.
Cork
Available grid capacity at 110kV substations attracts secondary market entrants seeking faster commissioning. The Commission for Regulation of Utilities tariff structures favor this southwestern location for demand-response incentives. Little Island and Cork Docklands emerge as alternative data center corridors with shorter planning cycles than Dublin.
Limerick
Shannon Free Zone offers enterprise-grade fiber and redundant power pathways for edge deployments. The EPA emissions standards apply with equal force here, pushing battery storage adoption over diesel backup. Raheen Business Park anchors the region's data center power demand as pharmaceutical and technology firms co-locate.
Galway
Medtech and financial services firms drive smaller-scale facility requirements across redundant N+1 configurations. The city's university research computing clusters pull specialized high-performance power infrastructure. Parkmore Industrial Estate concentrates the region's limited data center development as operators test secondary market viability.
Border Region
Cross-border fiber routes and all-island grid interconnectivity position Dundalk and Drogheda for UK-facing latency-sensitive workloads. Northern Ireland planning permissions sometimes accelerate project timelines for Republic-registered operators. This corridor remains speculative as EirGrid reinforcement timelines for the East-West interconnector face regulatory uncertainty.
Ireland Data Center Power Market Competitive Landscape
Player mix skews toward integrated electrical infrastructure specialists with full-stack power and thermal capabilities. Market structure concentrates around three global conglomerates with Irish operational presence, supported by specialized backup power and cooling component suppliers. Two strategic archetypes dominate: full-system integrators delivering turnkey substation-to-rack solutions, and component specialists winning on density-optimized subsystems. Competitive moves center on grid-connection partnership structures with EirGrid and liquid cooling technology licensing arrangements.
Within the integrated infrastructure tier, Schneider Electric SE and Eaton Corporation plc exemplify the full-stack archetype through their EcoStruxure and power distribution platforms. Vertiv Group Corp. occupies a specialized position in thermal management systems adapted to Irish climate variability. These three anchors demonstrate how global electrical infrastructure conglomerates structure Irish market presence around grid interconnection expertise and high-density cooling capabilities.
| Leading Market Players |
|---|
| ABB Ltd. |
| Eaton Corporation plc |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Caterpillar Inc. |
| Cummins Inc. |
| Delta Electronics Inc. |
| Rolls-Royce Power Systems |
| Legrand Group |
| Others |
Pricing and Supply Chain Analysis
EirGrid connection certification gates both supplier qualification and price differentiation simultaneously, as only vendors with demonstrated 33kV switchgear commissioning records can bid on hyperscale substation projects. EPA emissions compliance tiers further stratify procurement, with Tier 4 final backup generators commanding premiums over legacy diesel configurations. This dual-gating mechanism concentrates margin pools with integrated infrastructure providers while compressing returns for component specialists lacking certification depth.
Pricing Analysis
Next-generation liquid cooling infrastructure commands substantial premiums over legacy air-cooled systems and transitional hybrid configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from hyperscale operators. Cost compression in standard-tier power distribution units is intensifying because European transformer manufacturers face copper price volatility and extended lead times. Cloud service providers demonstrate the least price sensitivity, prioritizing 2N+1 redundancy and hourly carbon-free energy matching over unit economics.
Supply Chain Analysis
Strait of Malacca transit vulnerability for transformer core steel and rare-earth magnet shipments underwrites supply security premiums in Irish procurement contracts. High-capacity power transformer manufacturing concentrates in Germany, Switzerland, and Japan, with busbar copper drawing from Chilean and Zambian mining operations. Single-source vulnerability in 10MVA+ substation equipment creates exposure for Dublin-clustered projects facing EirGrid queue delays. Distribution runs through EPC contractor networks with turnkey commissioning capabilities, locking out pure component vendors from hyperscale direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ireland's data center power market sits in early-cycle expansion, with liquid cooling penetration still below critical mass despite rack density acceleration from AI training workloads.
For Market Incumbents: Shield margin pools in the Greater Dublin Area by deepening backward integration into battery energy storage system assembly, countering emerging competition from Asian power electronics specialists. Prioritize certification investment for 33kV switchgear commissioning to maintain EirGrid partnership exclusivity as queue congestion intensifies vendor selection pressure. For New Entrants and Emerging Players: Anchor in Cork and Limerick secondary markets where available 110kV substation capacity and shorter planning permissions create faster path to revenue. Target colocation facility operators seeking standardized N+1 configurations with modular, scalable power distribution architectures that adapt to uncertain density trajectories. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid cooling infrastructure as direct-to-chip and immersion systems displace legacy air handlers. Long-term viability centers on full-stack electrical infrastructure specialists with demonstrated EirGrid interconnection expertise. Monitor offshore wind power purchase agreement execution timelines as the critical signal for hyperscale demand sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| EirGrid Partnership Structuring | Grid interconnection exclusivity secures multi-year hyperscale procurement pipelines ahead of queue reforms. |
| Liquid Cooling Technology Licensing | Direct-to-chip manifold patents capture margin pools as AI training clusters exceed 50kW per cabinet. |
| Offshore Wind PPA Execution | Hourly carbon-free energy matching contracts with developers satisfy Scope 2 compliance for cloud operators. |
| Battery Storage Integration | Behind-the-meter lithium-ion systems displace diesel backup under tightening EPA emissions limits. |
| Secondary Market Geographic Expansion | Cork and Limerick site development captures demand displaced by Dublin grid connection delays. |
Research Methodology
The analysis maps power source configurations, cooling technology tiers, and facility type segments, each validated through hyperscale procurement directors, EPC contractor project managers, EirGrid interconnection planners, and EPA compliance officers. Primary interview findings triangulate against EirGrid connection queue databases, EPA emissions filing records, Commission for Regulation of Utilities tariff documentation, and hyperscaler capital expenditure disclosures. Bottom-up project pipeline aggregation cross-checks with top-down market sizing across the modeling period.
Consistency checks validate volume and value outputs against external benchmarks including utility-scale data center development tracking, electrical infrastructure trade flow data, and renewable energy certificate market registries. The analytical framework models segmentation across power source, facility type, cooling technology, and end user dimensions. CAGRs derive from installed base evolution and replacement cycle acceleration. Forecast inputs incorporate EirGrid reinforcement timelines and offshore wind capacity addition schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained hyperscale investment and stable EirGrid queue management; material deviation in grid access policy or renewable energy cost trajectories would warrant model refresh. Practitioners should keep alternative scenarios live as EPA emissions standards and Commission for Regulation of Utilities tariff reforms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Hong Kong Data Center Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
US Data Center Rack Market