
 India Data Center Power Market | 2026-2036
India Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Power Market Insights
BIS certification for electrical and electronic equipment is rotating vendor eligibility in the India data center power landscape, forcing suppliers to demonstrate indigenous testing compliance before securing large-scale contracts. Schneider Electric SE leverages its local manufacturing footprint to pre-certify switchgear and UPS systems ahead of tender cycles. Vertiv Holdings Co anchors its position through dedicated R&D facilities in Bengaluru that adapt global designs to Indian voltage and thermal conditions. Cummins Inc. competes on generator set localization, sustaining cost advantages against fully imported alternatives.
India data center power encompasses the generation, conditioning, distribution, and backup infrastructure that maintains continuous electrical supply for server facilities operating at voltages typically between 11 kV incoming and 415 V three-phase distribution with redundancy targets of N+1 or 2N. The primary purpose is to eliminate downtime for digital services ranging from financial transactions to streaming platforms. Diesel power sources retain dominant installed capacity despite sustainability pressures, while battery backup systems represent the fastest-expanding segment as lithium-ion chemistry displaces lead-acid in new builds. Liquid cooling is gaining structural importance as rack densities exceed 30 kW in hyperscale facilities, creating margin pools for specialized thermal management vendors.
CEA guidelines on power quality and reliability standards shape interconnection agreements for data centers drawing from state grids, while the PLI scheme for advanced chemistry cell manufacturing redirects battery procurement toward domestic suppliers. BIS compulsory registration requirements for IT and telecom equipment extend to power distribution units, filtering out uncertified imports. Stakeholders must monitor how state-level data center policies in Maharashtra and Karnataka evolve their power subsidy structures against tightening national renewable purchase obligations.
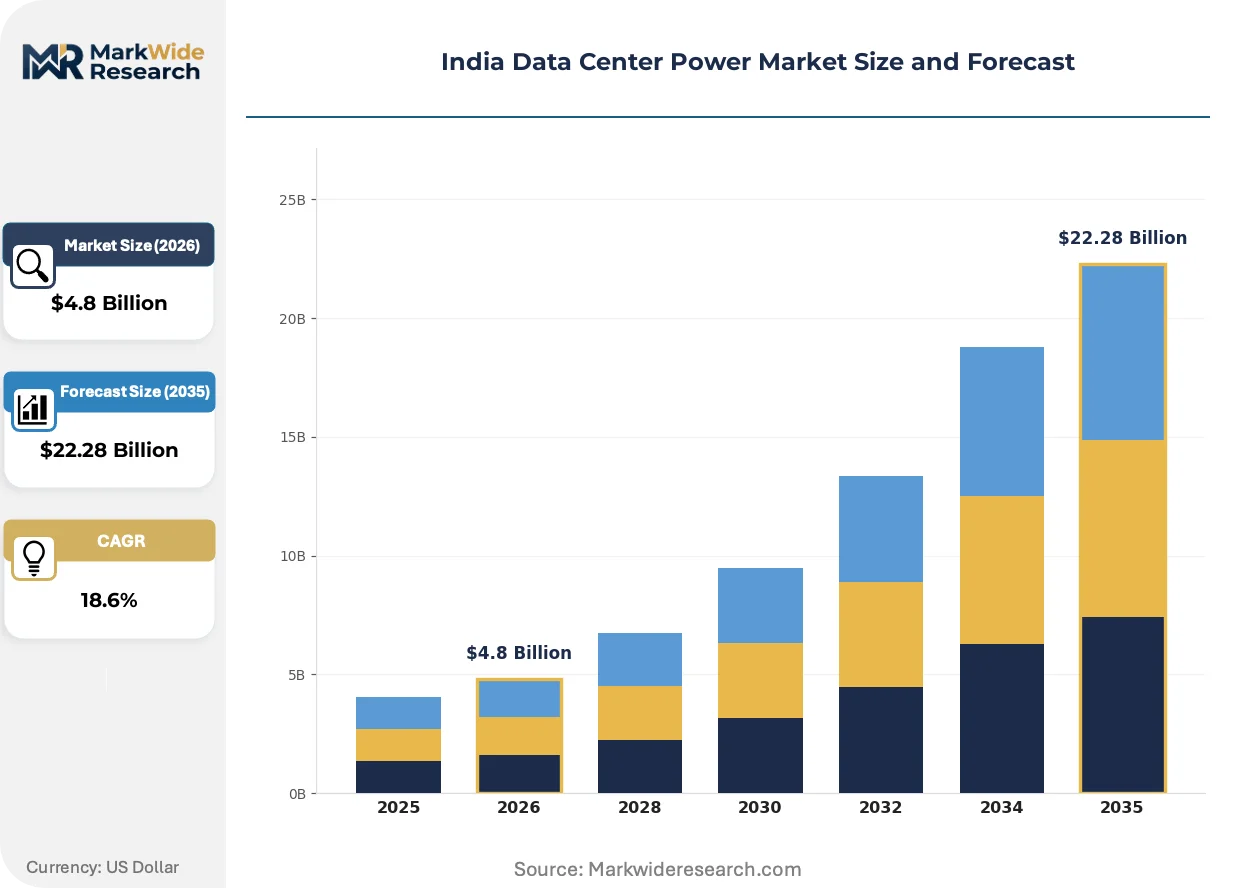
Market Dynamics
Hyperscale cloud operators are compressing deployment timelines for data center power infrastructure across Maharashtra, Karnataka, and Telangana, forcing suppliers to pre-position certified equipment ahead of tender releases. This demand acceleration is restructuring vendor qualification protocols and localization requirements.
Growth Catalysts
- CEA Grid Interconnection Standards:The Central Electricity Authority's reliability mandates for power quality are compelling data center operators to upgrade conditioning infrastructure, expanding the addressable market for advanced UPS and switchgear systems.
- Lithium-ion Battery Chemistry:PLI scheme incentives for advanced chemistry cell manufacturing are redirecting procurement toward domestic battery suppliers, reducing import dependency for backup power systems.
- State Data Center Policies:Dedicated policies in Telangana offering power subsidies and single-window clearances are attracting co-location investments that cascade into power equipment contracts.
Market Restraints
- Copper and Rare Earth Input Volatility:Price swings in copper busbars and neodymium for generator magnets are compressing margins for switchgear and genset manufacturers operating on fixed-price tenders.
- Import Concentration in Power Semiconductors:IGBT modules and silicon carbide devices remain concentrated among East Asian suppliers, exposing Indian power equipment makers to supply disruption risks.
- Diesel Generator Carbon Intensity:Sustainability commitments from hyperscale tenants are creating friction against diesel backup dominance, though battery alternatives face duration limitations beyond four-hour ratings.
Strategic Opportunities
- Underpenetrated Tier-II Cities:Bhubaneswar, Jaipur, and Kochi are emerging as satellite data center locations where state governments are drafting dedicated policies, creating first-mover advantages for power infrastructure suppliers establishing local service networks.
- Liquid Cooling Convergence:Integration of direct-to-chip cooling with power distribution units is opening margin pools for vendors combining thermal and electrical expertise in high-density rack deployments.
- BIS Certification as Channel Filter:Compulsory registration schemes for power distribution units are disqualifying uncertified imports, creating protected market space for compliant domestic and localized multinational suppliers.
Industry Challenges
- Specialized Commissioning Talent Scarcity:Shortages of technicians qualified in 11 kV switchgear commissioning and UPS synchronization are extending project handover timelines and inflating service costs.
- Legacy Lead-Acid Infrastructure Stranding:Existing battery rooms designed for vented lead-acid systems require costly retrofitting for lithium-ion thermal management and fire suppression, complicating upgrade economics for brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Power Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable, Diesel, Grid Power, Battery Backup Cooling System: Air Cooling, Liquid Cooling, Immersion Cooling, Hybrid Cooling End User: Telecom, E-commerce, Cloud Service Providers, Financial Institutions Facility Type: Colocation, Enterprise, Wholesale, Edge |
| Companies Covered | Schneider Electric SE, Vertiv Holdings Co, Eaton Corporation plc, ABB Ltd., Cummins Inc., Caterpillar Inc., Legrand SA, Rolls-Royce Holdings plc, Delta Electronics Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Power Market Trends and Innovations
Power infrastructure architecture is pivoting from centralized backup halls to distributed rack-level energy storage, driven by rack density inflation and sustainability mandates. This reconfiguration is redrawing equipment specifications and vendor competitive boundaries.
Lithium-ion battery systems with nickel-manganese-cobalt chemistry are displacing vented lead-acid configurations in new data center builds. Hyperscale operators in Mumbai and Bengaluru are specifying 10-15 minute discharge ratings at 30 kW per rack. This chemistry shift is compressing floor space requirements for energy storage by approximately two-thirds while demanding integrated battery management systems.
BIS compulsory registration schemes for IT and telecom power equipment are tightening import pathways. The quality enforcement framework now requires third-party testing at Indian laboratories before market entry. Foreign suppliers without local manufacturing partnerships face extended certification timelines that disadvantage them in fast-track hyperscale tenders.
Power purchase agreements with renewable generators are restructuring how data centers procure electricity. Large operators in Karnataka are contracting directly with solar-wind hybrid projects, bypassing state discom intermediaries. This procurement evolution is forcing power conditioning equipment to handle higher voltage fluctuation ranges from variable renewable injection.
India Data Center Power Market Segmentation
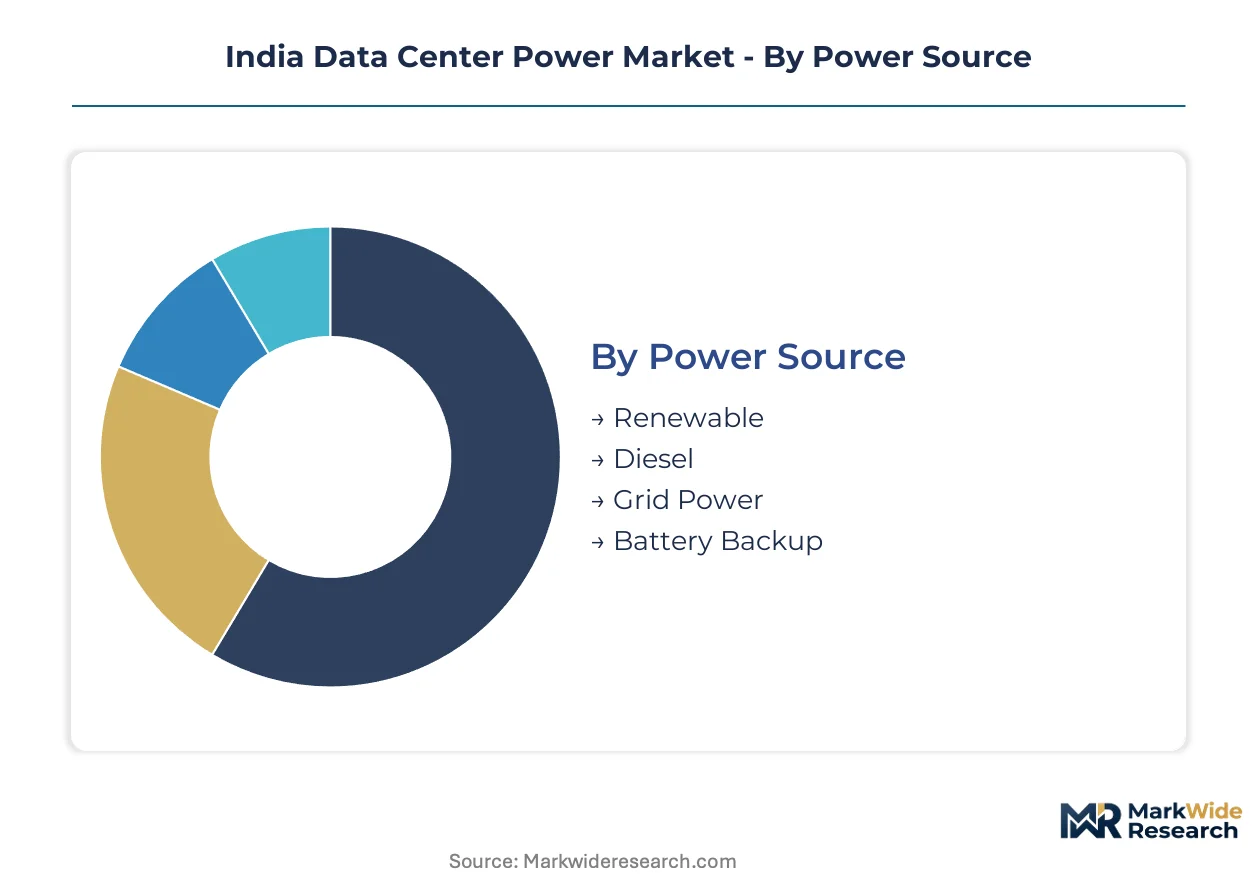
Segmentation in the India data center power market reveals how procurement channels diverge across power sources, cooling architectures, and facility types. Each dimension channels distinct margin structures and vendor qualification requirements.
Power Source:
Channel mix varies sharply by source type, with diesel flowing through traditional genset distributors while battery backup shifts toward direct manufacturer relationships.
- Diesel:Generator sets retain dominant installed capacity across Maharashtra and Karnataka facilities. Hyperscale operators in Mumbai face sustainability friction from tenant ESG mandates, though four-hour battery alternatives remain duration-limited for extended outages.
- Battery Backup:Lithium-ion chemistry with nickel-manganese-cobalt configurations is displacing vented lead-acid in new Bengaluru builds. PLI scheme incentives for advanced chemistry cell manufacturing redirect procurement toward domestic suppliers, compressing floor space requirements by approximately two-thirds.
- Renewable:Solar-wind hybrid projects in Karnataka enable direct power purchase agreements bypassing state discom intermediaries.
- Grid Power:CEA reliability mandates compel conditioning infrastructure upgrades for 11 kV incoming feeds.
Diesel dominates installed base. Battery backup is where expansion concentrates.
Cooling System:
Application intensity separates segments, with air cooling serving legacy densities while liquid cooling addresses rack power above 30 kW.
- Liquid Cooling:Direct-to-chip and cold plate configurations manage thermal loads exceeding 30 kW per rack in hyperscale Mumbai facilities. Integration with power distribution units opens margin pools for vendors combining thermal and electrical expertise.
- Air Cooling:Precision air handlers and computer room air conditioners serve legacy enterprise facilities in Telangana with rack densities below 15 kW. Established service networks and lower capital requirements sustain channel presence for retrofit projects.
- Immersion Cooling:Dielectric fluid submersion targets extreme density deployments in AI training clusters.
- Hybrid Cooling:Combined air-liquid architectures optimize capital allocation across mixed-density halls.
Air cooling holds the largest installed footprint. Liquid cooling is climbing the fastest.
End User:
Customer type dictates procurement sophistication, with cloud service providers driving standardization while financial institutions emphasize compliance layering.
- Cloud Service Providers:Hyperscale operators in Maharashtra and Karnataka compress deployment timelines, forcing suppliers to pre-position BIS-certified equipment ahead of tender releases. Standardized specifications across multi-megawatt campuses enable volume pricing leverage.
- Financial Institutions:RBI guidelines on business continuity and data localization drive 2N redundancy requirements for Mumbai-based banking facilities. Compliance layering extends procurement cycles but sustains premium pricing for certified switchgear and UPS systems.
- Telecom:TRAI infrastructure sharing mandates encourage multi-tenant power architectures.
- E-commerce:Seasonal demand spikes in fulfillment centers favor modular UPS scaling.
Cloud service providers anchor volume demand. Financial institutions concentrate premium margin capture.
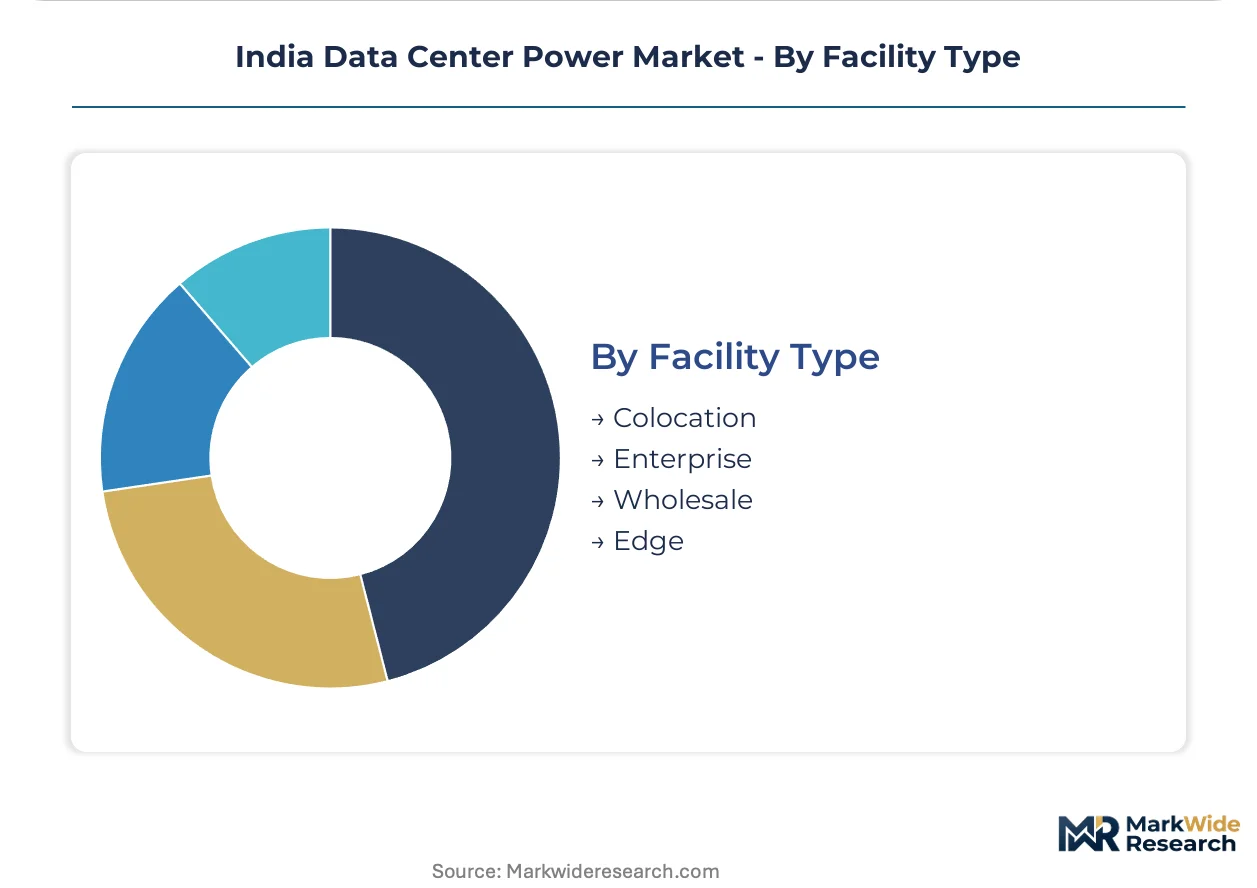
Facility Type:
Volume scale and margin structure diverge across facility types, with wholesale commanding single-source relationships and edge fragmenting across distributed service networks.
- Colocation:Multi-tenant facilities in Telangana leverage state power subsidies and single-window clearances to attract retail and wholesale tenants. Shared infrastructure economics demand standardized power distribution units with tenant-level metering.
- Wholesale:Dedicated hyperscale halls in Maharashtra specify custom 11 kV switchgear and containerized power modules. Single-source vendor relationships span design, commissioning, and long-term service agreements.
- Enterprise:Captive facilities in Karnataka retain legacy lead-acid battery rooms requiring costly lithium-ion retrofitting.
- Edge:Distributed nodes in Bhubaneswar and Jaipur demand compact, pre-integrated power skids for rapid deployment.
Colocation carries the broadest installed base. Edge deployments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level data center policies in Maharashtra, Karnataka, and Telangana are channeling power infrastructure investment toward designated clusters with subsidized electricity tariffs and streamlined clearances.
Maharashtra
Mumbai's financial district generates concentrated demand for 2N redundant UPS systems from banking and securities institutions. The state's dedicated data center policy offers power tariff subsidies and stamp duty exemptions for facilities in Navi Mumbai and Pune. MMRDA's planned data center parks in Navi Mumbai are attracting hyperscale operators requiring 11 kV switchgear and containerized power modules.
Karnataka
Bengaluru's hyperscale corridor commands lithium-ion battery systems with 10-15 minute discharge ratings at 30 kW per rack density. The state's electronics manufacturing cluster incentives support local assembly of power distribution units and battery management systems. Whitefield and Electronic City host the densest concentration of cloud service provider facilities with direct renewable power purchase agreements.
Telangana
Hyderabad's co-location market leverages single-window clearance mechanisms and dedicated power infrastructure zones. The state's data center policy extends capital subsidies and concessional electricity tariffs for facilities exceeding 10 MW capacity. Hardware Park and Genome Valley are emerging as satellite locations with pre-certified electrical equipment requirements.
Tamil Nadu
Chennai's enterprise data center base retains legacy lead-acid infrastructure requiring costly lithium-ion retrofitting for thermal management compliance. The state's Electronics Manufacturing Policy aligns with PLI scheme incentives for advanced chemistry cell manufacturing. Sriperumbudur and Oragadam industrial corridors are positioning for edge data center deployments with compact power skid specifications.
Delhi-NCR
Gurugram and Noida's financial services concentration drives RBI-mandated business continuity infrastructure with stringent power quality requirements. The National Capital Region's land scarcity pushes modular power architectures for vertical facility builds. Noida Special Economic Zone hosts telecommunications infrastructure with multi-tenant power metering systems.
India Data Center Power Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and localization depth, creating a tiered structure where multinational corporations anchor premium segments and domestic fabricators capture retrofit opportunities. Market concentration tilts toward integrated electrical infrastructure providers with BIS pre-certification capabilities and established service networks in Maharashtra and Karnataka. Two strategic archetypes dominate: full-stack power infrastructure vendors combining switchgear, UPS, and thermal management; and component specialists focusing on generator sets or battery systems with deep local manufacturing. Competitive moves center on R&D facility establishment for Indian voltage condition adaptation and backward integration into power semiconductor sourcing.
Within the full-stack infrastructure tier, Schneider Electric SE and Vertiv Holdings Co occupy positions representing integrated electrical-thermal capability. Schneider Electric SE exemplifies the archetype of multinational localization through pre-certified switchgear manufacturing ahead of tender cycles. Vertiv Holdings Co anchors the dedicated R&D facility model with Bengaluru-based design adaptation. Cummins Inc. sits within the power generation specialization archetype, representing generator set localization strategies against imported alternatives.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Holdings Co |
| Eaton Corporation plc |
| ABB Ltd. |
| Cummins Inc. |
| Caterpillar Inc. |
| Legrand SA |
| Rolls-Royce Holdings plc |
| Delta Electronics Inc. |
| Others |
Pricing and Supply Chain Analysis
BIS compulsory registration schemes for power distribution units and IT equipment gate both vendor qualification and price differentiation simultaneously, compressing margins for uncertified imports while enabling compliant domestic manufacturers to command premiums in hyperscale tenders across Maharashtra and Karnataka.
Pricing Analysis
Certification level (BIS/CE/UL-grade) creates the primary spread between premium and economy tiers in the India data center power market. Project-based contract pricing dominates, with hyperscale cloud service providers driving standardization for volume leverage while financial institutions absorb premium pricing for 2N redundant compliance. Cost compression in switchgear and UPS systems is intensifying because copper busbar volatility and fixed-price tender structures squeeze fabrication margins. Cloud service providers exhibit the highest price sensitivity due to standardized specifications and multi-vendor RFP processes, whereas banking facilities show lowest sensitivity given RBI-mandated business continuity requirements.
Supply Chain Analysis
Port congestion at JNPT and container availability constraints on the Asia-India trade lane elevate inbound logistics costs for power semiconductor modules and precision cooling components. Manufacturing concentration centers on China, South Korea, and Taiwan for IGBT modules and silicon carbide devices, while domestic assembly of switchgear and battery management systems expands in Bengaluru and Pune. The supply chain rests on neodymium magnet imports for generator sets and lithium carbonate sourcing for battery chemistry, exposing Indian power equipment makers to single-source vulnerability in advanced power electronics. Distribution runs through authorized distributor networks for genset and switchgear sales, with direct manufacturer relationships dominating lithium-ion battery procurement for hyperscale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India data center power market tracks a cyclical recovery anchored to hyperscale cloud capacity expansion waves, with demand inflection tied to state policy activation in Telangana and Karnataka subsidy windows.
For Market Incumbents: Fortify BIS pre-certification pipelines ahead of tender cycles to defend against emerging domestic fabricators capturing retrofit opportunities in legacy lead-acid facilities. Deepen backward integration into power semiconductor sourcing to mitigate East Asian supply disruption risks, while anchoring long-term service agreements with Maharashtra-based financial institutions to lock in premium pricing for 2N redundant installations. For New Entrants and Emerging Players: Post-sales commissioning talent scarcity in 11 kV switchgear and UPS synchronization opens white-space for specialized service providers targeting brownfield upgrade cycles in Chennai's enterprise base. Tier-II satellite markets including Bhubaneswar and Jaipur offer the most penetrable geography, where state governments are drafting dedicated data center policies without established incumbent service networks. Pursue partnership-based go-to-market models with EPC contractors to bypass direct hyperscale vendor qualification barriers. For Investors and Strategic Acquirers: PLI scheme activation for advanced chemistry cell manufacturing reshapes the acquisition landscape toward domestic battery assembly capabilities with BIS certification pathways. Long-term viability over the projection horizon favors vertically integrated power infrastructure platforms combining switchgear, UPS, and thermal management expertise. Monitor state-level renewable purchase obligation tightening as the signal to watch for demand inflection in grid-interconnection conditioning equipment.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Pre-Positioning | Pre-certified equipment stocks enable rapid response to compressed hyperscale tender timelines in Mumbai and Bengaluru. |
| Backward Integration into Power Semiconductors | In-house sourcing of IGBT modules reduces exposure to East Asian supply concentration and tariff volatility. |
| Liquid Cooling-Thermal Convergence | Combined electrical-thermal expertise captures margin pools in high-density rack deployments exceeding 30 kW. |
| Tier-II City Service Network Expansion | First-mover presence in Bhubaneswar and Jaipur secures positioning ahead of state policy finalization. |
| Renewable Power Purchase Agreement Structuring | Direct solar-wind hybrid contracting bypasses state discom intermediaries and conditions equipment for variable injection. |
Research Methodology
A spread of perspectives from data center facility engineers, electrical infrastructure procurement leads, state nodal agency officials, and EPC project managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against CEA grid interconnection guidelines, BIS compulsory registration schemes, state data center policy documents, and hyperscaler capital expenditure disclosures. The approach triangulated bottom-up equipment shipment estimates with top-down power capacity buildout projections.
Segmentation dimensions modeled span power source type, cooling architecture, end-user category, and facility scale across the projection horizon. The analytical framework derived CAGRs by correlating hyperscale deployment announcements with equipment procurement lead times and state subsidy activation schedules. Forecast inputs incorporated PLI scheme incentive trajectories for advanced chemistry cell manufacturing and evolving BIS certification timelines for imported power distribution units.
Underlying assumptions cover sustained hyperscale cloud expansion, stable state policy subsidy structures, and manageable copper and rare earth input volatility, with deviation risk concentrated in power semiconductor supply disruption and accelerated renewable purchase obligation enforcement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
Canada Data Center Power Market
Data Center Infrastructure
Japan Data Center Market