
 Global Server Management Software Market | 2026-2036
Global Server Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Server Management Software Market Foresight
Enterprise buyer concentration is restructuring as hyperscale cloud operators consolidate server management procurement while mid-market firms fragment across SaaS-native alternatives. Microsoft Corporation leverages its Azure ecosystem to embed server management within hybrid cloud subscriptions. IBM Corporation anchors its position through Red Hat OpenShift integration for containerized infrastructure. VMware competes via specialized virtualization management tools that bridge on-premises and multi-cloud environments.
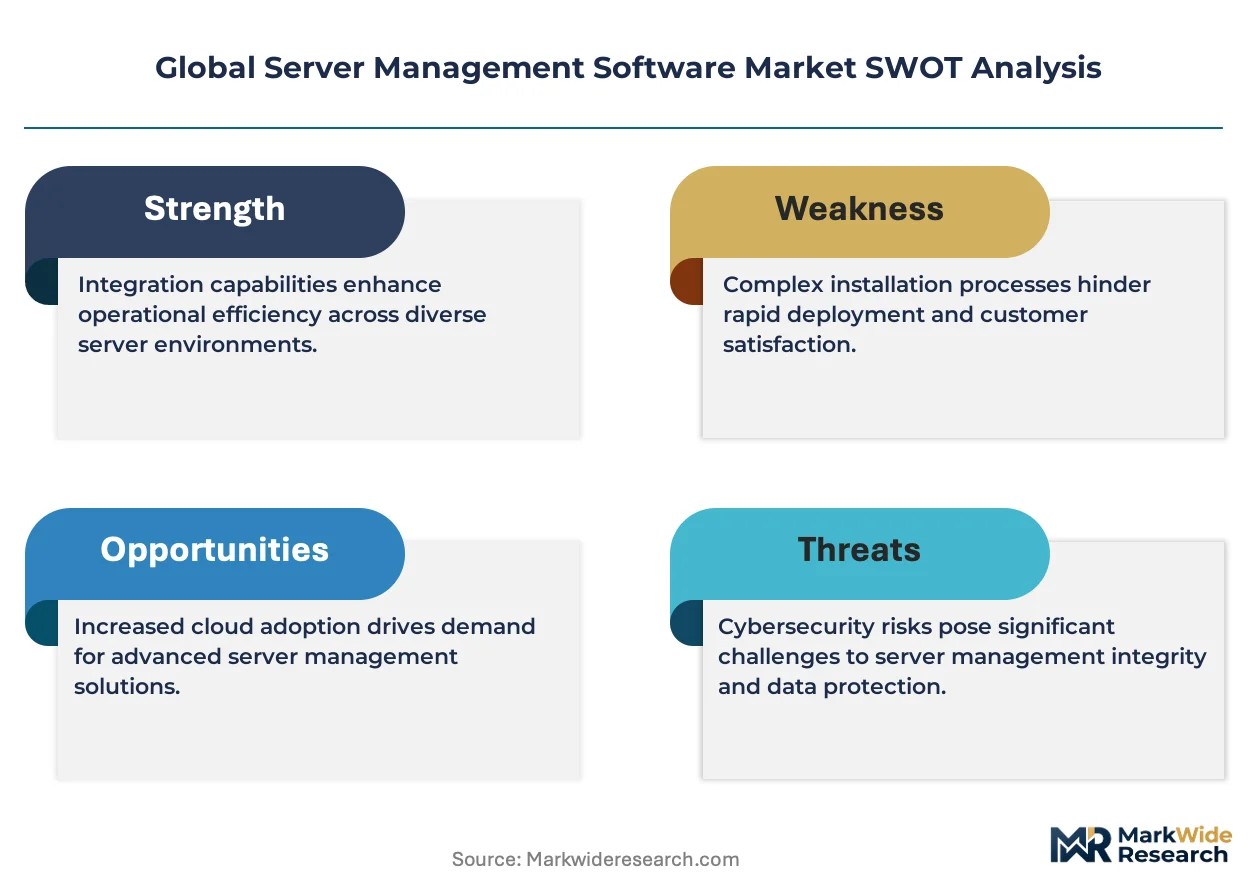
Server management software encompasses tools for monitoring, configuring, automating, and securing physical and virtual server infrastructure across distributed computing environments, typically integrating with SNMP, WMI, or REST APIs for real-time telemetry collection. The primary commercial purpose is to minimize downtime, optimize resource utilization, and enforce compliance policies across heterogeneous server fleets. Cloud-based deployment now leads solution type adoption as organizations retire legacy data center footprints, while AI-based analytics represents the fastest-growing technology integration segment as predictive failure detection replaces reactive ticketing workflows. Monitoring solutions retain the largest margin pool due to recurring telemetry ingestion fees and premium alerting tiers.
FCC guidelines on communications infrastructure reliability intersect with EU NIS2 Directive requirements for critical service provider operational resilience, compelling vendors to embed automated compliance reporting into server management stacks. ISO 27001 and SOC 2 Type II certifications have become baseline market access requirements for enterprise procurement. Stakeholders must monitor how sovereign data localization mandates in India, Germany, and Saudi Arabia fragment multi-cloud management architectures and reshape vendor certification roadmaps.
Market Dynamics
Hyperscale cloud operators are consolidating procurement power while sovereign data mandates in India, Germany, and Saudi Arabia fragment multi-cloud architectures, forcing vendors to rebuild certification roadmaps around jurisdictional boundaries rather than unified global platforms.
Growth Catalysts
- EU AI Act operational resilience mandates:Critical digital infrastructure operators must deploy automated compliance reporting, directly expanding demand for embedded server orchestration platforms with real-time telemetry.
- Edge computing deployment waves:Manufacturing and telecommunications sectors in India and Germany are scaling distributed server fleets that require unified management across thousands of remote nodes.
- Hyperscale data center expansion:Cloud service providers in the United States are standardizing on API-native management stacks to automate provisioning across heterogeneous hardware generations.
Market Restraints
- Specialized engineering talent scarcity:Kubernetes and OpenShift certification pipelines in India and Germany lag behind deployment timelines, inflating implementation costs for containerized infrastructure.
- Legacy virtualization lock-in:Enterprises with substantial VMware estates face technical friction migrating telemetry workflows to cloud-native alternatives without service disruption.
- Input cost volatility in semiconductor components:Memory and processor supply concentration in East Asian foundries creates procurement uncertainty for on-premises server refresh cycles.
Strategic Opportunities
- Sovereign cloud mandates in Saudi Arabia:Data localization requirements are creating demand for region-specific server management certifications and in-country support infrastructure.
- AI-based predictive analytics convergence:Machine learning failure detection is integrating with automated remediation workflows, opening premium service tiers for mission-critical workloads.
- Telecommunications edge densification:5G network rollouts in Germany and India require distributed server management at cell tower aggregation points, an underpenetrated application segment.
Industry Challenges
- Multi-framework compliance complexity:Simultaneous ISO 27001, SOC 2 Type II, and EU NIS2 Directive audits extend vendor certification timelines and inflate documentation overhead.
- Heterogeneous integration requirements:SNMP, WMI, and REST API telemetry standards coexist without unified abstraction layers, forcing custom connector development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Server Management Software Market |
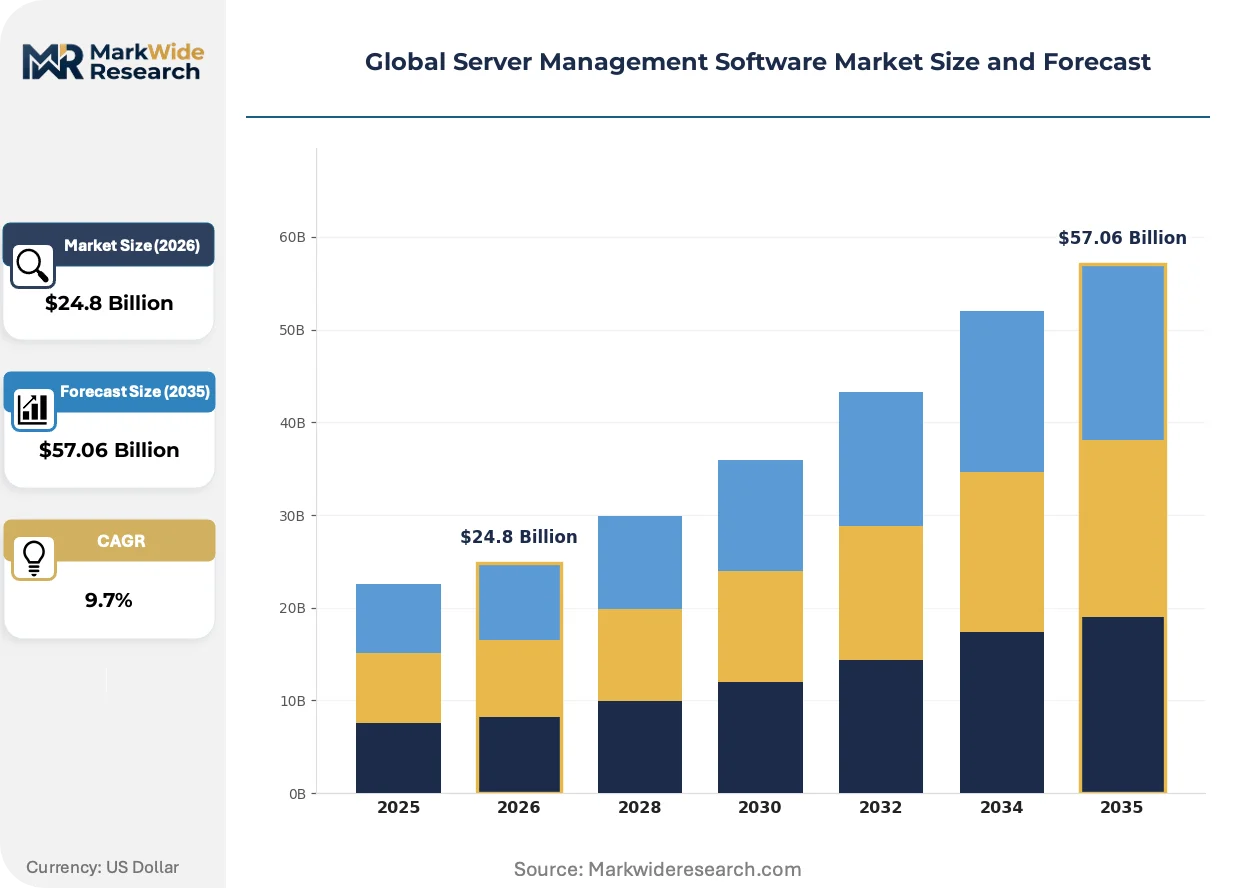
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $57.06 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution Type: Monitoring, Configuration, Automation, Security Management, Backup Management End User: IT Service Providers, Telecommunication Companies, Financial Institutions, Educational Institutes, Government Agencies Technology Integration: AI-Based Analytics, Virtualization Support, Container Management, Multi-Cloud Compatibility, API Integration |
| Companies Covered | Microsoft Corporation, IBM Corporation, VMware, Oracle Corporation, Cisco Systems, SolarWinds, Hewlett Packard Enterprise, ManageEngine, Datadog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Server Management Software Market Shifts & Advancements
Artificial intelligence is compressing incident response cycles from hours to minutes while regulatory fragmentation forces architectural specialization. Vendors must now engineer for jurisdictional compliance as a primary design constraint rather than retrofitting global platforms.
Predictive failure analytics is integrating telemetry ingestion, pattern recognition, and automated ticketing into continuous remediation loops. Hyperscale operators in the United States are deploying these capabilities across fleets exceeding one hundred thousand nodes, compressing mean time to resolution and reducing manual intervention. The structural consequence is a margin shift from reactive support contracts toward recurring AI-enabled premium tiers.
The EU NIS2 Directive is mandating operational resilience documentation and automated incident reporting for critical service providers. Vendors must embed compliance dashboards directly into server management stacks or risk disqualification from European enterprise procurement. Cloud service providers with existing EU operations are accelerating certification roadmaps, while new entrants face extended validation timelines.
Enterprise buyers are unbundling server management from broader infrastructure contracts and evaluating specialized vendors on API flexibility and multi-cloud abstraction. Mid-market firms in India and Germany are fragmenting across SaaS-native alternatives rather than defaulting to incumbent hypervisor ecosystems. This pattern is most visible in telecommunications and financial services verticals, where workload portability across cloud regions has become a procurement priority.
Global Server Management Software Market Segmentation
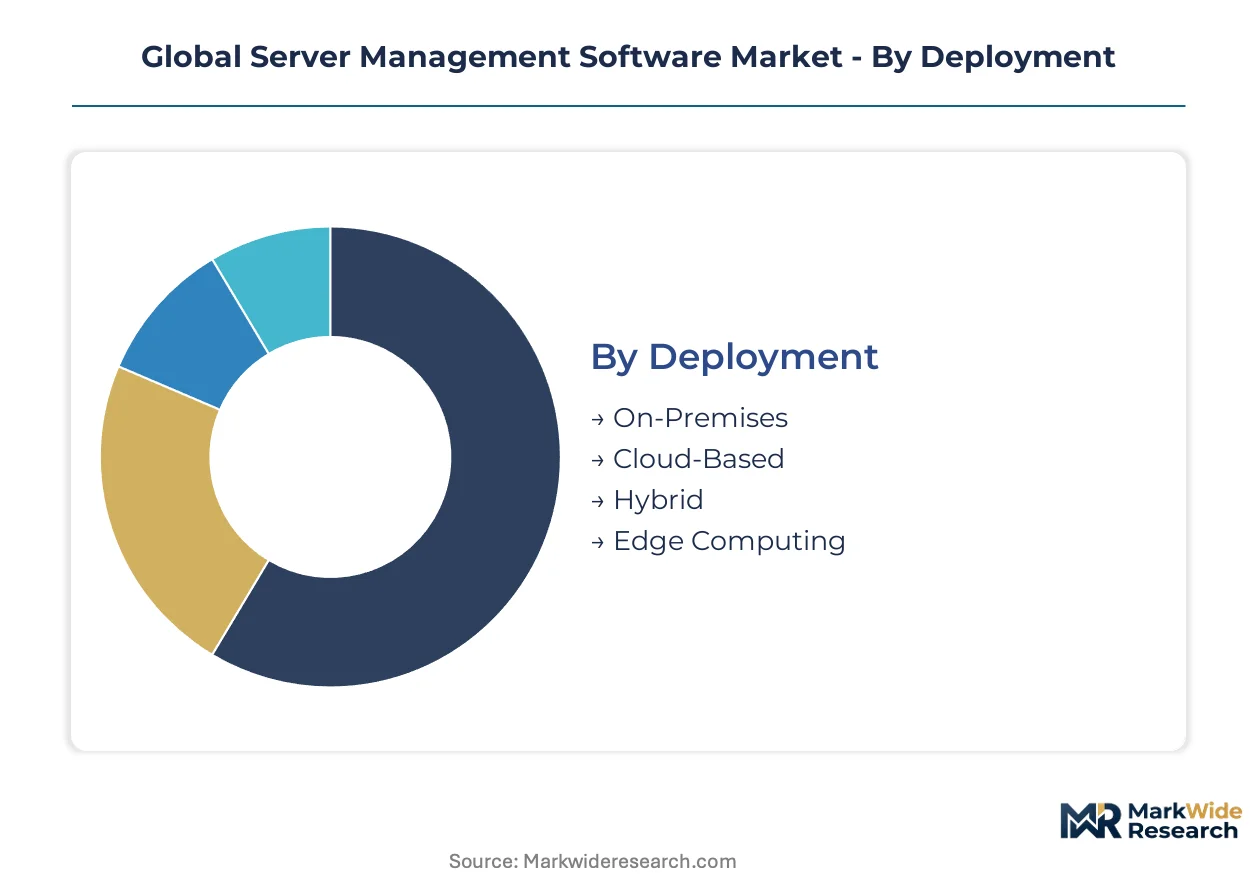
Server management software segments reflect divergent infrastructure maturity across buyer organizations. Procurement patterns split between legacy data center operators prioritizing control and cloud-native enterprises optimizing for API flexibility.
Deployment:
Buyers in this category differentiate by infrastructure ownership models and data sovereignty requirements.
- On-Premises:Deployed within customer-controlled data centers with direct hardware access. Financial institutions in Germany and government agencies in Saudi Arabia favor this model for compliance with data localization mandates.
- Cloud-Based:Delivered as SaaS with centralized orchestration planes and subscription billing. Mid-market firms in India are migrating here fastest to eliminate capital expenditure on physical infrastructure.
- Hybrid:Combines on-premises control with cloud burst capacity through unified management layers. Enterprises with VMware estates in the United States use this to bridge legacy and cloud-native workloads.
- Edge Computing:Distributed deployment at remote aggregation points with intermittent connectivity. Telecommunications operators in Germany and India require this for 5G cell tower infrastructure.
On-Premises leads volumes today; Cloud-Based is gaining share fastest.
Solution Type:
Commercial priority in this category tracks margin concentration and recurring revenue potential.
- Monitoring:Real-time telemetry ingestion across SNMP, WMI, and REST API endpoints with premium alerting tiers. This segment commands the largest margin pool due to continuous data stream monetization.
- Automation:Policy-driven orchestration for provisioning, patching, and remediation workflows. Hyperscale operators in the United States standardize on this to manage fleets exceeding one hundred thousand nodes.
- Configuration:Baseline drift detection and compliance enforcement across heterogeneous server fleets. Required for ISO 27001 and SOC 2 Type II audit documentation.
- Security Management:Vulnerability scanning, access control, and threat detection integration. Mandated by EU NIS2 Directive requirements for critical digital infrastructure operators.
- Backup Management:Snapshot orchestration and disaster recovery workflow automation. Financial institutions prioritize this for regulatory resilience mandates.
Monitoring dominates revenue today; Automation is expanding most quickly.
End User:
Vertical specialization in this category determines integration complexity and compliance burden.
- IT Service Providers:Multi-tenant management platforms supporting diverse client infrastructure stacks. These buyers demand API flexibility and white-label reporting capabilities.
- Telecommunication Companies:Distributed server management at cell tower aggregation points and core network facilities. 5G rollouts in Germany and India are accelerating procurement here.
- Financial Institutions:Mission-critical workload management with sub-second failover requirements. Subject to RBI regulations in India and BaFin oversight in Germany.
- Government Agencies:Sovereign cloud deployments with in-country support and certification requirements. Saudi Arabia and India impose strict data localization on these buyers.
- Educational Institutes:Cost-optimized solutions for research computing and campus IT infrastructure. Budget constraints favor open-source and SaaS-native alternatives.
IT Service Providers anchor volume today; Telecommunication Companies show the steepest expansion trajectory.
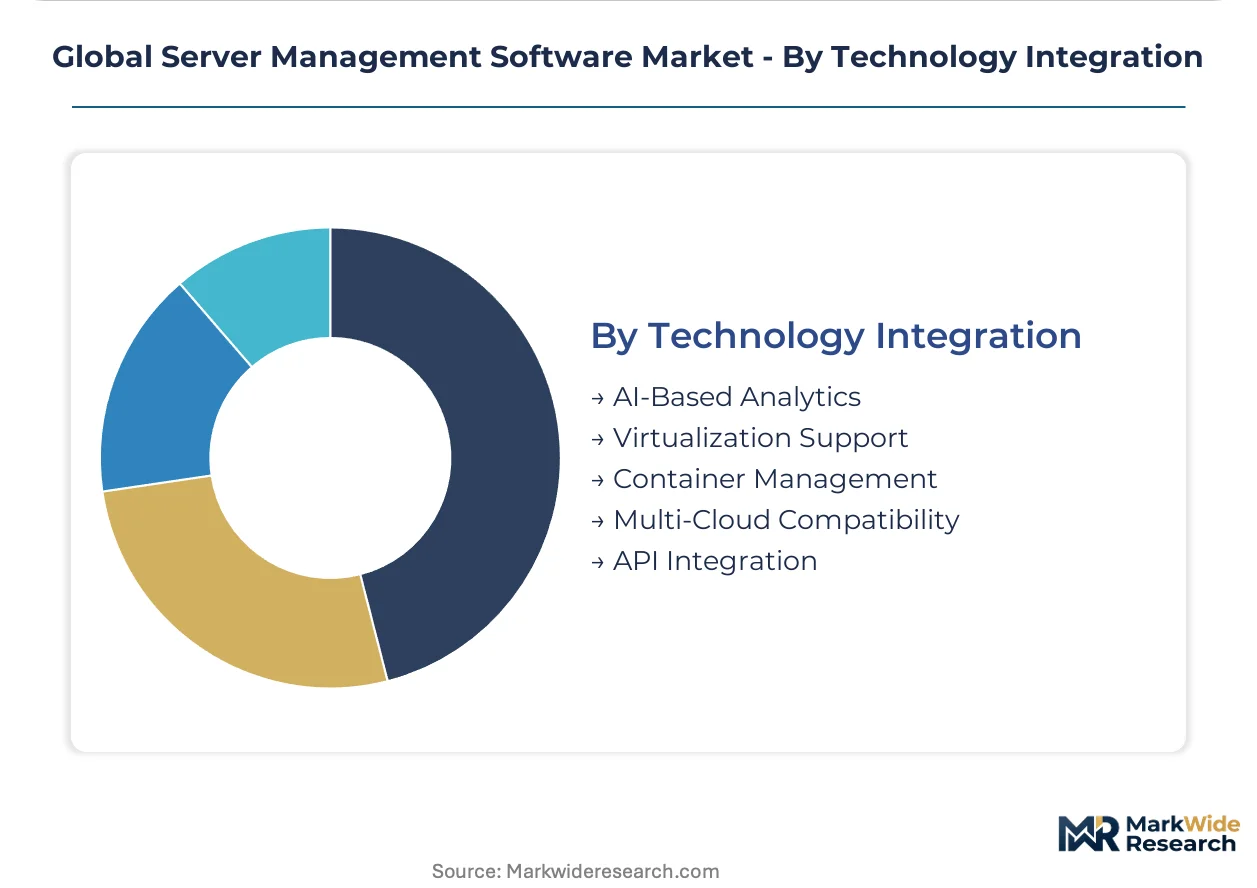
Technology Integration:
Competitive differentiation in this category hinges on abstraction layer completeness and AI-enabled automation depth.
- AI-Based Analytics:Machine learning models for predictive failure detection and automated remediation. Compresses incident response from hours to minutes across hyperscale deployments.
- Container Management:Kubernetes and OpenShift orchestration with pod-level telemetry and resource optimization. Engineering talent scarcity in India and Germany inflates implementation costs.
- Virtualization Support:VMware and Hyper-V integration bridging legacy hypervisor estates. Enterprises face technical friction migrating telemetry workflows without service disruption.
- Multi-Cloud Compatibility:Unified control planes across AWS, Azure, and GCP with workload portability. Sovereign data mandates fragment these architectures by jurisdiction.
- API Integration:RESTful endpoints for custom connector development and third-party tool chaining. Required where SNMP and WMI standards coexist without unified abstraction.
Virtualization Support leads adoption today; AI-Based Analytics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified Kubernetes and OpenShift engineers cluster disproportionately in the United States, Germany, and India, anchoring procurement concentration for automated server orchestration platforms.
United States
Hyperscale cloud operators in Northern Virginia and the Pacific Northwest are standardizing API-native management stacks across heterogeneous hardware generations. FCC guidelines on communications infrastructure reliability intersect with enterprise compliance requirements. The Dallas-Fort Worth metroplex hosts expanding data center clusters where automated provisioning demand concentrates.
Germany
Industrial manufacturers in Bavaria and Baden-Württemberg are scaling edge computing deployments requiring unified management across thousands of remote nodes. The EU NIS2 Directive mandates operational resilience documentation for critical digital infrastructure operators. Frankfurt's financial district drives mission-critical workload management procurement with sub-second failover requirements.
India
Telecommunications operators in Mumbai and Bangalore are deploying distributed server management at 5G cell tower aggregation points. RBI regulations impose strict data localization on financial institutions managing server infrastructure. Hyderabad's technology corridor attracts hyperscale cloud providers building region-specific certification roadmaps.
Saudi Arabia
Government agencies in Riyadh are procuring sovereign cloud deployments with in-country support infrastructure. Data localization requirements under national cybersecurity frameworks create demand for region-specific server management certifications. The King Abdullah Financial District anchors financial services procurement with regulatory resilience mandates.
Japan
Telecommunications carriers in Tokyo and Osaka require distributed server management for 5G network densification. METI guidelines encourage operational resilience investments in critical digital infrastructure. The Kansai region's manufacturing base drives edge computing deployment for industrial IoT telemetry collection.
Global Server Management Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base splits between platform-integrated suites and best-of-breed point solutions. Three archetypes dominate: hyperscale cloud ecosystem players, legacy infrastructure incumbents, and SaaS-native observability specialists. Competitive moves concentrate on strategic partnerships for API interoperability and geographic certification expansion to satisfy sovereign data mandates.
Within the ecosystem-integrated tier, Microsoft Corporation and IBM Corporation occupy positions defined by hybrid cloud subscription bundling and container orchestration platform integration. VMware exemplifies the virtualization-centric archetype bridging on-premises and multi-cloud environments. These three companies represent divergent strategic bets on infrastructure abstraction layers, with each anchoring a distinct buyer segment based on existing technology estate composition and cloud migration trajectory.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| VMware |
| Oracle Corporation |
| Cisco Systems |
| SolarWinds |
| Hewlett Packard Enterprise |
| ManageEngine |
| Datadog |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ISO 27001-compliant enterprise tiers and uncertified mid-market alternatives manifests in both subscription pricing and supply chain sourcing strategies, with sovereign data mandates in Germany and Saudi Arabia forcing regional pricing premiums alongside localized support infrastructure investments.
Pricing Analysis
Capacity additions in India's technology corridor are reshaping price floors for cloud-based server management subscriptions. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by AI-enabled predictive tiering and EU NIS2 Directive compliance bundling. Cost compression in the mid-market tier intensifies because SaaS-native entrants from Hyderabad undercut legacy virtualization incumbents. Government agencies in Saudi Arabia show least price sensitivity due to sovereign cloud mandates, while educational institutes in India face acute budget constraints.
Supply Chain Analysis
Semiconductor memory supply rests on South Korean and Taiwanese foundry concentration, with processor fabrication anchored in the United States and China. Cloud orchestration platforms draw from specialized API middleware components, container runtime engines, and telemetry ingestion infrastructure. Single-source vulnerability in East Asian memory supply creates procurement uncertainty for on-premises server refresh cycles. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels with region-specific certification overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where EU AI Act compliance costs in Germany diverge from India's lighter regulatory burden, enabling cost-optimized delivery models for price-sensitive mid-market buyers.
For Market Incumbents: Anchor hybrid cloud subscription bundles through backward integration into container orchestration platforms, defending against SaaS-native observability specialists encroaching on the mid-market. Prioritize certification investment for EU NIS2 Directive and Saudi data localization mandates to maintain procurement eligibility. Channel control through hyperscaler marketplace presence preserves margin position against direct competitors. For New Entrants and Emerging Players: Begin with telecommunications edge densification in Germany and India, where 5G cell tower infrastructure remains underpenetrated by unified server management platforms. Target IT service providers seeking white-label API flexibility as the most penetrable buyer archetype. Go-to-market leverage through Kubernetes-native deployment models bypasses legacy virtualization lock-in friction. For Investors and Strategic Acquirers: Consolidation pressure builds where container management talent scarcity in India and Germany inflates implementation timelines beyond customer tolerance. Long-term viability favors vendors with multi-cloud abstraction layers and jurisdictional certification roadmaps. Acquisition target archetype: SaaS-native observability platforms with existing API connector libraries. Signal to watch: hyperscale cloud provider capex deceleration indicating procurement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding server management within Azure and OpenShift ecosystems captures hybrid cloud subscription renewals. |
| Geographic Expansion | Building in-country support infrastructure in Riyadh satisfies Saudi data localization and cybersecurity framework requirements. |
| Strategic Partnership | API interoperability alliances with telecommunications vendors unlock 5G edge densification procurement channels. |
| Acquisition of Specialist Firm | Absorbing Kubernetes-native observability tools addresses engineering talent scarcity in Germany and India. |
| Product Launch | EU NIS2 Directive-compliant compliance dashboards prevent disqualification from European enterprise procurement. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie/Sensor Tower data, and enterprise software procurement databases. Triangulation across deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern segments ensures granular alignment.
Historical trendline analysis across server fleet telemetry ingestion rates, subscription renewal patterns, and certification adoption curves informs projection mechanics. Segmentation dimensions modeled include deployment architecture, solution type margin pool, end-user vertical, and technology integration depth. CAGRs derive from fitted growth curves calibrated against infrastructure investment cycles and regulatory implementation timelines. Forecast inputs incorporate EU AI Act operational resilience mandate compliance deadlines and sovereign cloud procurement waves.
Caveats apply where semiconductor supply disruptions, abrupt regulatory enforcement shifts, or hyperscale cloud provider strategy pivots could materially shift the outlook. Forecasts reflect documented assumptions about edge computing deployment velocity and container orchestration talent pipeline expansion. A small set of named triggers—East Asian foundry output volatility, EU NIS2 Directive audit stringency, and Indian data localization enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mindfulness Meditation Application Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
Global Voip Software Market
Software & Services
Global Document Control Software Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Open Stack Service Market
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
Global Workforce Management Software Market
Software & Services
Kennel Management Software Market
Software & Services
Video Converter Software Market
Software & Services
Plant Design Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Audio and Video Editing Software Market