
 Data Center Transfer Switches and Switchgears Market | 2026-2036
Data Center Transfer Switches and Switchgears Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Transfer Switches and Switchgears Market Intelligence
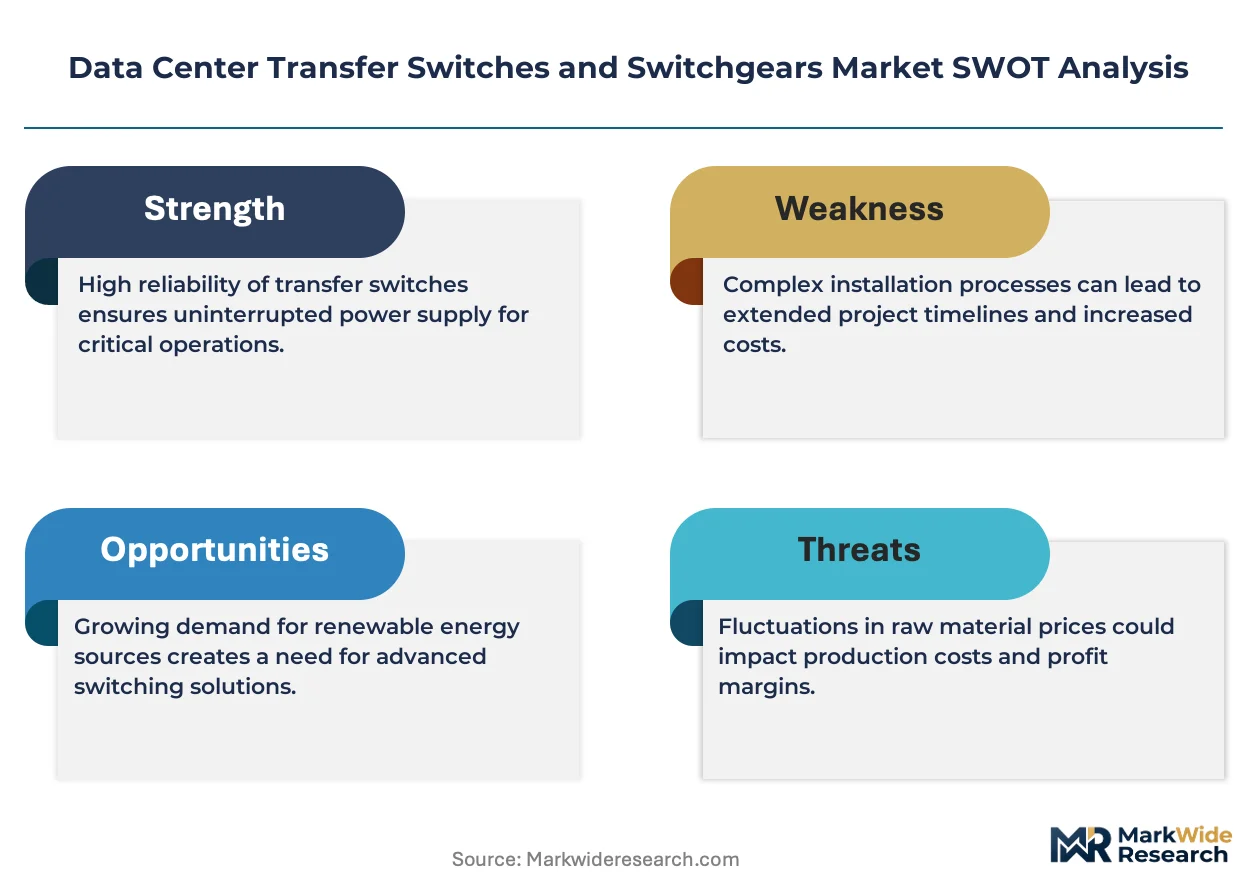
Aftermarket service revenue is reconfiguring margin capture across the Data Center Transfer Switches and Switchgears landscape. Schneider Electric leverages its global service footprint to lock in multi-year maintenance contracts for critical power infrastructure. ABB anchors its position through integrated digital monitoring platforms that reduce unplanned downtime for colocation operators. Eaton competes aggressively on modular switchgear architectures that accelerate deployment timelines for hyperscale facilities.
Data center transfer switches and switchgears comprise electromechanical and solid-state apparatus engineered to redirect electrical load between primary and secondary power sources within milliseconds, ensuring continuous operation of server infrastructure. These systems typically operate at voltages from 208V to 15kV and incorporate vacuum circuit breaker technology to extinguish arcs under fault conditions. Automatic transfer switches command the largest installed base due to non-negotiable uptime requirements in hyperscale computing environments, while smart switchgear with digital control architectures represents the fastest-expanding technology tier as operators pursue remote diagnostics and predictive maintenance capabilities. Medium voltage switchgear retains concentrated margin pools given specialized engineering requirements and limited qualified vendor bases.
The U.S. EPA and OSHA shape domestic product standards through efficiency mandates and electrical safety protocols that govern switchgear installation in occupied facilities. The EU Green Deal and F-Gas Regulation in Europe are accelerating phase-out of sulfur hexafluoride insulation in medium voltage switchgear, redirecting R&D investment toward vacuum and dry air alternatives. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs for dual-certified product lines reshape competitive economics for multinational suppliers.
Market Dynamics
The hyperscale computing sector's power density escalation is compressing deployment timelines for medium voltage switchgear, forcing procurement cycles to compress from 18 months to under 9 months in Northern Virginia and Frankfurt clusters. This structural acceleration is reconfiguring vendor qualification criteria and inventory strategies across the supply base.
Growth Catalysts
- EPA ENERGY STAR Certification:Tightening efficiency thresholds for data center equipment are mandating automatic transfer switch upgrades across U.S. colocation facilities, creating replacement demand cycles.
- Vacuum Circuit Breaker Technology:Arc extinction performance improvements are enabling 15kV-class switchgear to penetrate hyperscale facilities previously limited to air-insulated alternatives.
- Northern Virginia Power Density:Load requirements exceeding 50MW per campus are driving procurement of redundant automatic transfer switch configurations to sustain 99.999% uptime commitments.
Market Restraints
- Copper and Electrical Steel Volatility:Raw material input costs for switchgear enclosures and busbars fluctuate with commodity markets, compressing margin predictability for fixed-price contracts.
- SF6 Phase-Out Friction:The EU F-Gas Regulation's sulfur hexafluoride insulation restrictions are forcing R&D redirection toward dry air alternatives, extending product development cycles by 18-24 months.
- Qualified Vendor Concentration:Medium voltage switchgear engineering certification requirements limit approved suppliers to fewer than 12 globally accredited manufacturers, creating supply bottleneck risk.
Strategic Opportunities
- India Data Center Buildout:PLI scheme incentives for electronics manufacturing are attracting switchgear assembly investments to serve Mumbai and Chennai hyperscale corridors.
- Predictive Maintenance Convergence:Integration of IoT sensors with vacuum circuit breaker diagnostics is opening recurring revenue streams through condition-based service contracts.
- Modular Switchgear Architectures:Pre-engineered skid-mounted substations are compressing field installation from weeks to days for rapid-deploy hyperscale campuses.
Industry Challenges
- Medium Voltage Engineering Talent Scarcity:Specialized expertise in 5kV-15kV switchgear design and commissioning is concentrating among aging workforce cohorts in Germany and Japan.
- Dual-Certification Compliance Burden:Simultaneous UL and IEC testing requirements for multinational deployments extend product launch timelines and inflate qualification costs.
- Legacy Control System Integration:Digital switchgear retrofits must interface with decades-old SCADA protocols in existing data centers, complicating firmware compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Transfer Switches and Switchgears Market |
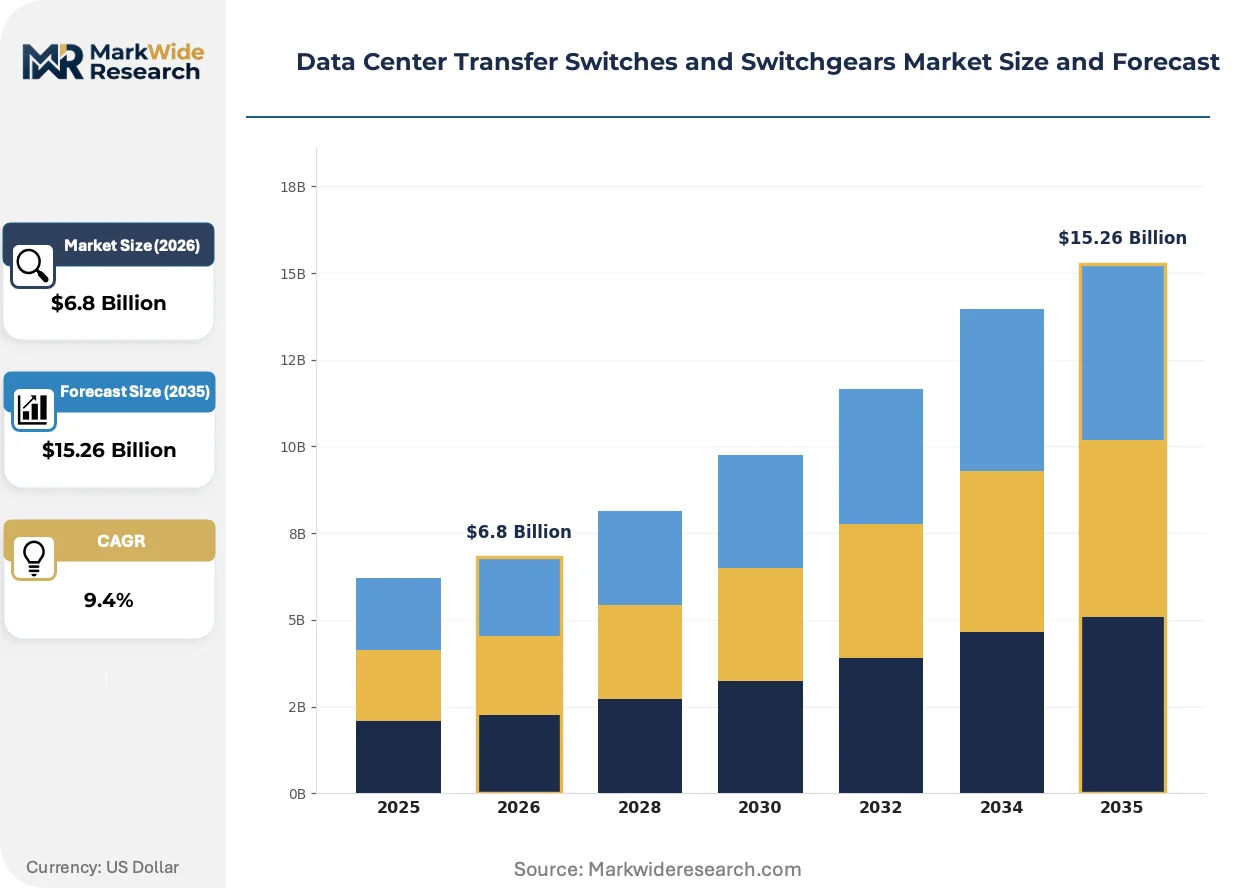
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Transfer Switch, Manual Transfer Switch, Modular Switchgear, Fixed Switchgear, Low Voltage Switchgear, Medium Voltage Switchgear Technology: Electromechanical, Solid State, Hybrid, Digital Control, Smart Switchgear, Vacuum Circuit Breaker Application: Data Centers, Server Farms, Telecommunications Facilities, Cloud Service Providers, Edge Computing Sites, Colocation Facilities End User: IT Infrastructure Providers, Managed Service Operators, Hyperscale Computing, Enterprise IT, Internet Service Providers, Data Network Operators |
| Companies Covered | ABB, Cummins, Eaton, Schneider Electric, Vertiv Group Corp., Caterpillar, Siemens, Legrand, ASCO Power Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Transfer Switches and Switchgears Market Strategic Shifts & Innovations
Electrification intensity in data centers is forcing equipment architecture toward higher voltage distribution, while environmental compliance deadlines are accelerating insulation technology transitions. These pressures are converging to reshape product roadmaps and procurement specifications simultaneously.
Solid-state transfer switch technology is migrating from niche military and healthcare applications into hyperscale computing environments. These silicon-controlled rectifier-based systems transfer loads in under 4 milliseconds versus 100+ milliseconds for electromechanical alternatives. Google and Microsoft procurement teams are piloting 480V-class solid-state units for AI training clusters where voltage sag tolerance approaches zero.
The EU F-Gas Regulation's 2030 sulfur hexafluoride reduction targets are compelling medium voltage switchgear redesigns across European manufacturing. Vacuum interrupter technology is displacing SF6-insulated gear in 12kV-24kV applications, though dielectric performance gaps persist above 36kV. ABB and Siemens are redirecting R&D investment toward dry air insulation for 72.5kV-class data center substations to maintain product line viability.
Hyperscale operators are consolidating switchgear procurement through direct vendor relationships, bypassing traditional electrical distributor channels. Amazon Web Services and Meta Platforms now issue multi-year framework agreements specifying custom switchgear configurations with embedded digital monitoring. This disintermediation concentrates volume with tier-one manufacturers while compressing margin pools for regional distributors in Northern Virginia and Frankfurt.
Data Center Transfer Switches and Switchgears Market Segmentation
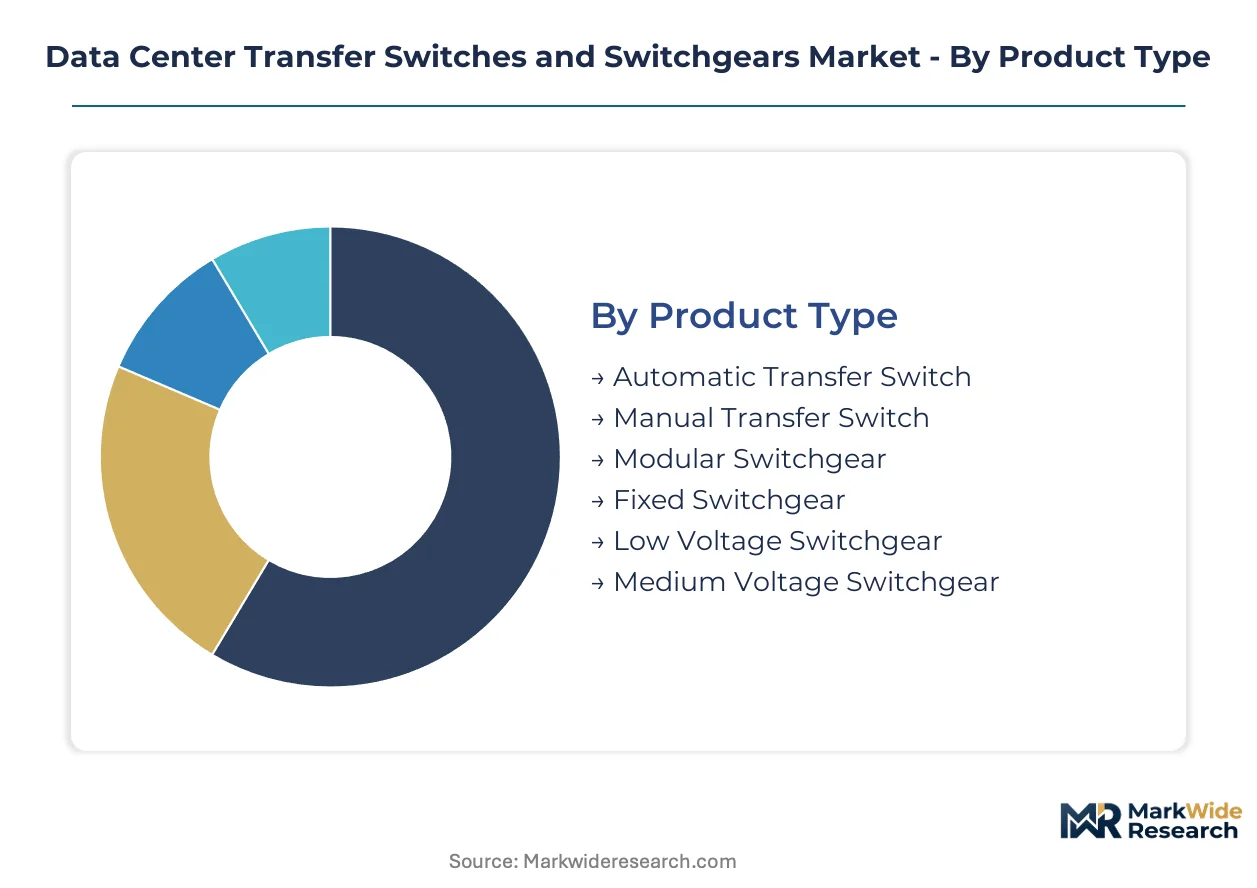
Segmentation in the Data Center Transfer Switches and Switchgears Market reveals distinct procurement patterns across voltage classes and deployment scales. Hyperscale operators prioritize automatic transfer capabilities while enterprise buyers balance capital constraints with redundancy requirements. Understanding these divides sharpens vendor positioning and R&D allocation.
Product Type:
Use cases span from mission-critical hyperscale campuses requiring sub-cycle transfer speeds to smaller colocation sites accepting manual intervention protocols.
- Automatic Transfer Switch:Electromechanical or solid-state apparatus engineered to redirect 208V-15kV loads within 4-100 milliseconds upon primary source failure. Amazon Web Services and Microsoft Azure procurement teams specify redundant ATS configurations for AI training clusters in Northern Virginia where 99.999% uptime is contractually mandated.
- Medium Voltage Switchgear:Vacuum circuit breaker-based systems operating at 5kV-15kV with specialized arc extinction engineering and limited qualified vendor bases. Frankfurt and Northern Virginia hyperscale corridors drive procurement as campus densities exceed 50MW, though SF6 phase-out requirements under the EU F-Gas Regulation extend European product development cycles.
- Manual Transfer Switch:Operator-actuated load transfer devices for secondary power paths in non-critical infrastructure zones.
- Modular Switchgear:Pre-engineered skid-mounted substations compressing field installation timelines from weeks to days.
- Fixed Switchgear:Permanently installed conventional architectures for stable, long-tenancy data center facilities.
- Low Voltage Switchgear:208V-600V distribution gear serving smaller edge computing sites and legacy facility retrofits.
The dominant share belongs to Automatic Transfer Switch, while Medium Voltage Switchgear is gaining share fastest amid power density escalation in hyperscale corridors.
Technology:
Cost tiers separate proven electromechanical platforms from premium solid-state and digitally integrated alternatives commanding service contract premiums.
- Vacuum Circuit Breaker:Arc extinction technology enabling 15kV-class switchgear penetration into hyperscale facilities previously limited to air-insulated alternatives. ABB and Siemens redirect R&D toward dry air insulation for 72.5kV-class substations to maintain European product viability under F-Gas Regulation deadlines.
- Smart Switchgear:Digital control architectures with embedded IoT sensors enabling remote diagnostics and predictive maintenance capabilities. Google and Microsoft pilot procurement for AI cluster applications where voltage sag tolerance approaches zero, opening recurring revenue streams through condition-based service contracts.
- Electromechanical:Conventional relay-based transfer mechanisms dominating installed base due to proven reliability and lower capital outlay.
- Solid State:Silicon-controlled rectifier systems transferring loads in under 4 milliseconds for zero-downtime computing environments.
- Hybrid:Combined electromechanical and solid-state architectures balancing cost with performance for mid-tier colocation operators.
- Digital Control:Microprocessor-based monitoring and switching logic enabling SCADA integration and firmware-upgradable protection schemes.
Vacuum Circuit Breaker holds the largest installed base, though Smart Switchgear is expanding most quickly as operators pursue predictive maintenance capabilities.
Application:
Volume concentrates in hyperscale computing environments while margin pools deepen in specialized telecommunications and edge deployments.
- Hyperscale Computing:Campus-scale facilities exceeding 50MW with non-negotiable uptime commitments driving redundant automatic transfer switch configurations. Procurement cycles compress from 18 months to under 9 months in Northern Virginia and Frankfurt clusters, forcing vendor inventory and qualification strategy adjustments.
- Edge Computing Sites:Distributed low-latency infrastructure requiring compact, rapidly deployable switchgear solutions. PLI scheme incentives in India attract assembly investments to serve Mumbai and Chennai corridor buildouts where power density requirements trail hyperscale averages but deployment velocity is accelerating.
- Data Centers:General-purpose enterprise facilities with standard redundancy requirements and longer procurement horizons.
- Server Farms:High-density compute-intensive installations prioritizing thermal management integration with power distribution.
- Telecommunications Facilities:Carrier-grade infrastructure with specialized grounding and lightning protection specifications.
- Cloud Service Providers:Multi-tenant platforms balancing standardization with tenant-specific power conditioning needs.
- Colocation Facilities:Third-party data centers serving mixed enterprise clients with tiered redundancy offerings.
Hyperscale Computing commands the dominant procurement volume, while Edge Computing Sites are climbing the fastest amid distributed infrastructure buildouts.
End User:
Customer type determines specification stringency, with IT Infrastructure Providers and Managed Service Operators representing contrasting procurement philosophies.
- Hyperscale Computing:Amazon Web Services, Meta Platforms, and similar operators issuing multi-year framework agreements with direct vendor relationships, bypassing electrical distributor channels. Custom switchgear configurations with embedded digital monitoring concentrate volume with tier-one manufacturers while compressing regional distributor margins in Northern Virginia and Frankfurt.
- Managed Service Operators:Colocation and hosting providers balancing capital efficiency with competitive SLA commitments. Schneider Electric leverages global service footprints to lock in multi-year maintenance contracts, while Eaton competes on modular architectures accelerating deployment timelines.
- IT Infrastructure Providers:Hardware-centric vendors integrating switchgear into bundled data center construction packages.
- Enterprise IT:Corporate-owned facilities with longer replacement cycles and greater price sensitivity than hyperscale counterparts.
- Internet Service Providers:Network operators prioritizing availability for DNS and routing infrastructure over compute density.
- Data Network Operators:Specialized carriers with unique grounding and electromagnetic compatibility requirements.
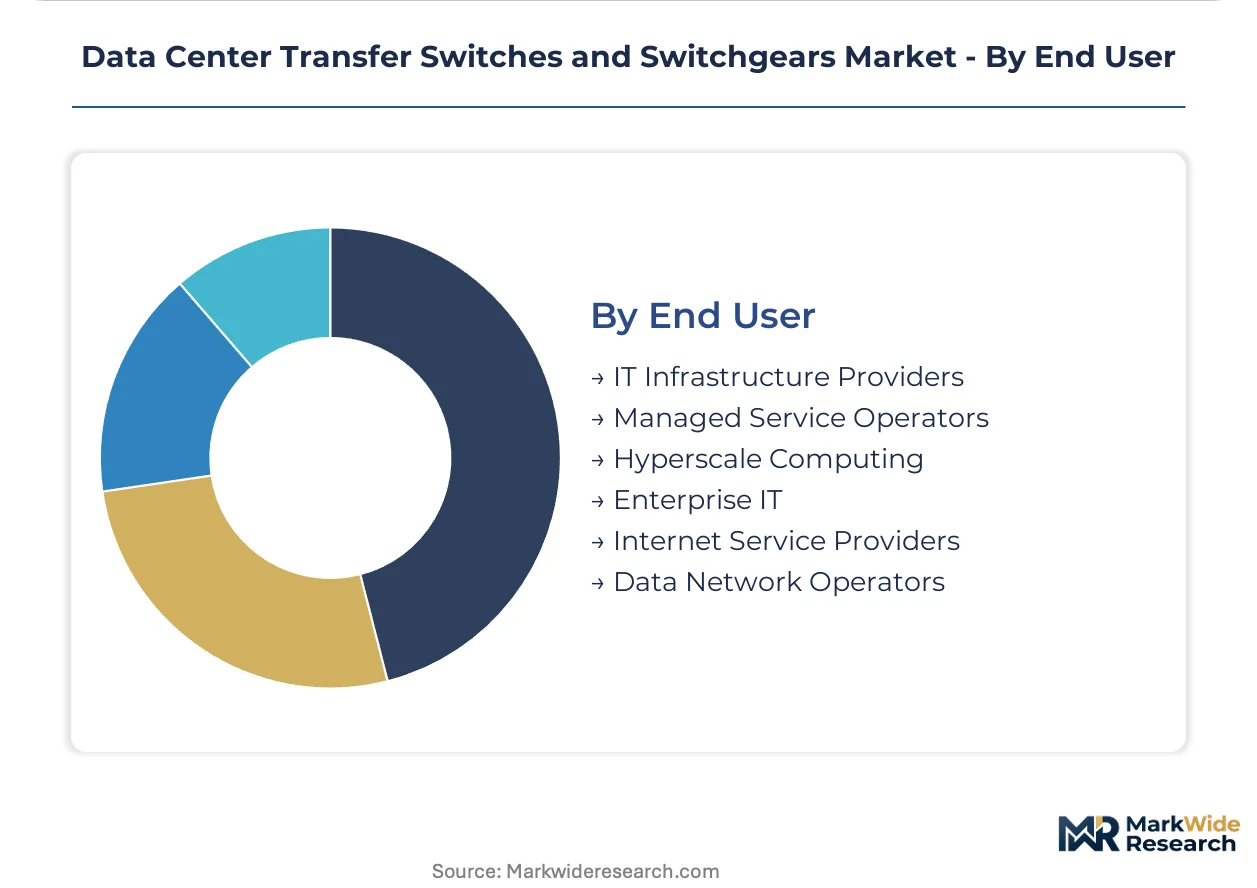
Hyperscale Computing dominates procurement value, though Managed Service Operators are closing the gap fastest as colocation capacity expands to serve enterprise cloud migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes automatic transfer switch redundancy for hyperscale uptime commitments. Europe accelerates SF6 phase-outs under F-Gas Regulation deadlines. India scales domestic assembly under PLI incentives.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth drive procurement of 15kV-class vacuum circuit breaker switchgear for 50MW-plus campuses. EPA ENERGY STAR certification tightens efficiency thresholds for data center equipment, forcing colocation facility upgrades. Ashburn's data center corridor compresses procurement cycles below nine months as power density requirements exceed national averages.
Germany
Frankfurt's hyperscale cluster demands medium voltage switchgear with dry air insulation alternatives to SF6. The EU F-Gas Regulation mandates sulfur hexafluoride reduction targets by 2030, extending product development cycles for domestic manufacturers. Bavaria and Hesse host engineering talent concentrations for 5kV-15kV switchgear design, though workforce aging threatens commissioning capacity.
India
Mumbai and Chennai hyperscale corridors attract switchgear assembly investments under the PLI scheme for electronics manufacturing. Central Electricity Authority standards govern medium voltage installations in occupied facilities. Telangana's Hyderabad cluster emerges as a rapid-deployment hub for modular switchgear serving domestic cloud operators.
China
Beijing-Tianjin-Hebei and Yangtze River Delta data center buildouts drive vacuum interrupter demand for 12kV-24kV applications. MIIT efficiency standards and dual carbon goals redirect procurement toward digitally monitored switchgear architectures. Shenzhen manufacturers accelerate solid-state transfer switch production for AI training clusters.
United Kingdom
London and Slough data center operators specify smart switchgear with embedded IoT diagnostics for predictive maintenance contracts. The UK government's net-zero commitments align with EU F-Gas Regulation phase-out timelines for SF6 insulation. Scotland's renewable energy integration drives demand for grid-interactive automatic transfer switches.
Data Center Transfer Switches and Switchgears Market Key Industry Players
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified electrical conglomerates. The vendor base compresses into fewer than twelve globally accredited manufacturers for medium voltage certification tiers. Three archetypes dominate: integrated power management platforms, modular architecture specialists, and predictive maintenance service bundlers. Competitive moves center on multi-year framework agreements with hyperscale operators and R&D redirection toward dry air insulation alternatives.
Among diversified electrical conglomerates, ABB, Schneider Electric, and Eaton exemplify distinct positioning vectors. ABB anchors the vacuum interrupter technology tier through its European manufacturing heritage. Schneider Electric occupies the service-contract bundling position with global maintenance footprints. Eaton represents the modular architecture specialization for rapid-deployment hyperscale campuses. These three entities collectively illustrate how vendor qualification criteria and inventory strategies reconfigure around compressed procurement timelines in Northern Virginia and Frankfurt.
| Leading Market Players |
|---|
| ABB |
| Cummins |
| Eaton |
| Schneider Electric |
| Vertiv Group Corp. |
| Caterpillar |
| Siemens |
| Legrand |
| ASCO Power Technologies |
| Others |
Cost & Logistics Intelligence
Overcapacity in Asian electrical steel production is compressing enclosure material costs while tightening margin discipline among European switchgear specialists. This utilization asymmetry rewards vertically integrated manufacturers with captive metal-forming capacity and pressures project-based pricing for modular substation providers serving Northern Virginia's compressed deployment timelines.
Pricing Analysis
Long-term framework agreements dominate hyperscale procurement, with Amazon Web Services and Meta Platforms locking in multi-year pricing for custom-configured automatic transfer switches with embedded digital monitoring. Price differentiation hinges on UL certification tier and after-sales service bundling, with Schneider Electric commanding premiums for global maintenance footprints. Cost compression in standard-grade electromechanical transfer switches is intensifying due to qualified vendor concentration below twelve accredited manufacturers. Enterprise colocation operators exhibit highest price sensitivity, while hyperscale computing buyers prioritize uptime guarantees over capital outlay.
Supply Chain Analysis
Copper cathode supply draws from Chile, Peru, and Indonesian smelters, with electrical steel production anchored in China, Japan, and South Korea. Vacuum interrupter manufacturing rests on specialized ceramic-to-metal sealing expertise concentrated in Germany and Switzerland. Single-source vulnerability persists for 72.5kV-class dry air insulation components as EU F-Gas Regulation deadlines accelerate SF6 phase-out timelines. Distribution runs through direct vendor relationships with hyperscale operators, bypassing traditional electrical distributor channels in Northern Virginia and Frankfurt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state transfer switch technology represents a high-growth disruption as Google and Microsoft pilot sub-4-millisecond load transfer for AI training clusters. The EU F-Gas Regulation's 2030 sulfur hexafluoride reduction targets compound this inflection by forcing R&D redirection toward vacuum and dry air alternatives.
For Market Incumbents: Pre-empt margin erosion in electromechanical transfer switches by accelerating solid-state product line development and securing multi-year service contracts for existing installed bases. Threat from silicon-controlled rectifier-based alternatives demands backward integration into power semiconductor sourcing. Certification investment in dual UL-IEC testing protocols protects European market access as regulatory divergence intensifies. For New Entrants and Emerging Players: Pursue modular switchgear assembly opportunities in India's PLI-subsidized corridors serving Mumbai and Chennai hyperscale buildouts. Edge computing sites in secondary Indian cities offer the most penetrable geography, with power density requirements trailing hyperscale averages but deployment velocity accelerating. A go-to-market angle anchored to rapid-deployment skid-mounted substations bypasses entrenched vendor relationships in saturated Northern Virginia. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive maintenance service bundlers with IoT-enabled vacuum circuit breaker diagnostics. Long-term viability over the next decade favors acquisition targets with proven dry air insulation engineering for 72.5kV-class substations. The signal to watch is hyperscale framework agreement renewal rates in Northern Virginia as procurement cycle compression stabilizes.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Insulation Transition | ABB and Siemens R&D redirection toward dry air alternatives maintains EU market access under F-Gas Regulation deadlines. |
| Solid-State Transfer Switch Scale-Up | Silicon-controlled rectifier production expansion captures Google and Microsoft procurement for AI cluster applications. |
| Modular Substation Deployment | Pre-engineered skid-mounted architectures compress field installation timelines for rapid-deploy hyperscale campuses. |
| Predictive Maintenance Platform Integration | IoT sensor convergence with vacuum circuit breaker diagnostics opens recurring revenue streams through condition-based contracts. |
| India Manufacturing Localization | PLI scheme incentives attract assembly investments to serve Mumbai and Chennai hyperscale corridor buildouts. |
Research Approach
Operator-level perspectives from data center infrastructure directors, electrical engineering procurement leads, and medium voltage switchgear commissioning specialists anchored the qualitative base. Primary interviews with hyperscale facility operators in Northern Virginia and Frankfurt supplemented secondary validation through EPA ENERGY STAR certification databases, EU F-Gas Regulation implementation tracking, and SEC filings from publicly traded electrical equipment manufacturers. Customs data on copper and electrical steel trade flows provided input cost calibration. Bottom-up facility deployment tracking and top-down equipment spend analysis enabled cross-triangulation.
Scenario-bracketing around regulatory implementation timelines and raw material cost volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include voltage class, transfer speed tier, insulation technology type, and regional regulatory cluster. CAGRs were derived from deployment velocity correlation with hyperscale capex disclosures and power density escalation curves. Vacuum interrupter technology penetration rates and solid-state transfer switch adoption thresholds served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in copper and electrical steel pricing, or in hyperscale data center construction lending rates, would shift the trajectory. Forecasts reflect assumptions on EU F-Gas Regulation enforcement consistency and EPA efficiency threshold evolution. Cross-checking against hyperscaler disclosed infrastructure spend and regional permitting data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Poland Data Center Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market