
 Data Center IT Asset Disposition Market | 2026-2036
Data Center IT Asset Disposition Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center IT Asset Disposition Market Analysis
Hyperscale operators is collapsing the traditional enterprise refresh cycle, forcing ITAD providers to rebuild logistics networks around bulk server flows rather than dispersed corporate pickups. Iron Mountain leverages its document-management footprint to anchor secure transport lanes for high-volume decommissions. Sims Lifecycle Services specializes in component-level recovery, competing on rare-earth yield rates from shredded storage arrays.
Data center IT asset disposition encompasses the secure retirement, data sanitization, and material recovery of enterprise computing hardware, typically involving NIST 800-88 compliant data destruction and R2 or e-Stewards certified recycling protocols to eliminate residual information exposure. The service model dimension shows hybrid engagements capturing margin pools as clients demand both onsite witnessing and offsite processing flexibility. Recycling dominates volume within disposition method while reselling generates disproportionate value recovery from recent-generation servers and networking equipment.
EPA hazardous waste rules, the EU WEEE Directive, and emerging SEC climate disclosure requirements collectively tighten documentation standards and downstream vendor accountability across the ITAD value chain. NIST 800-88 and ISO 27001 certifications now function as market-access prerequisites rather than competitive differentiators for enterprise contracts. Stakeholders must monitor regulatory divergence between jurisdictions where data localization laws complicate cross-border asset movement and certificate portability.
Market Dynamics
Hyperscale cloud operators compress server refresh cycles to 3-4 years, flooding ITAD channels with bulk decommissioning volumes that overwhelm traditional enterprise-focused logistics networks built for dispersed, low-density pickups.
Growth Catalysts
- EU WEEE Directive chain-of-custody mandates:The directive's tightened documentation requirements force enterprises to outsource asset retirement to certified ITAD specialists rather than handle disposition internally.
- Hyperscale decommissioning velocity:Cloud operators retire server fleets at triple the historical enterprise rate, creating concentrated demand spikes for secure transport and rapid processing capacity.
- NIST 800-88 data sanitization protocols:Federal contracting requirements in the United States mandate compliant destruction methods, pulling defense and healthcare sectors toward certified service providers.
Market Restraints
- Rare-earth recovery yield volatility:Neodymium and dysprosium extraction rates from shredded storage arrays fluctuate with ore spot prices, compressing margins for component-level recyclers.
- State-level e-waste mandate fragmentation:Inconsistent definitions of covered equipment across California, New York, and Texas force ITAD providers to maintain parallel compliance workflows.
- Cross-border data localization barriers:China's cybersecurity law restricts asset movement containing residual storage media, trapping hardware value in domestic recovery channels.
Strategic Opportunities
- India data center buildout wave:The country's PLI scheme for electronics manufacturing is spawning greenfield facilities that will generate first-generation retirement volumes by 2028.
- R2 and e-Stewards certification convergence:Dual-certified facilities can capture enterprise contracts requiring both standards, commanding premium positioning in the United States and Germany.
- Onsite witnessing service bundling:Hybrid engagements combining physical audit presence with offsite processing address financial sector liability concerns without sacrificing logistics efficiency.
Industry Challenges
- Certified data destruction technician scarcity:NIST 800-88 and R2 auditor training programs graduate insufficient personnel to match hyperscale decommissioning timelines.
- Legacy tape media sanitization complexity:Outdated backup systems in healthcare and government verticals require specialized degaussing equipment that most ITAD facilities have depreciated.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center IT Asset Disposition Market |
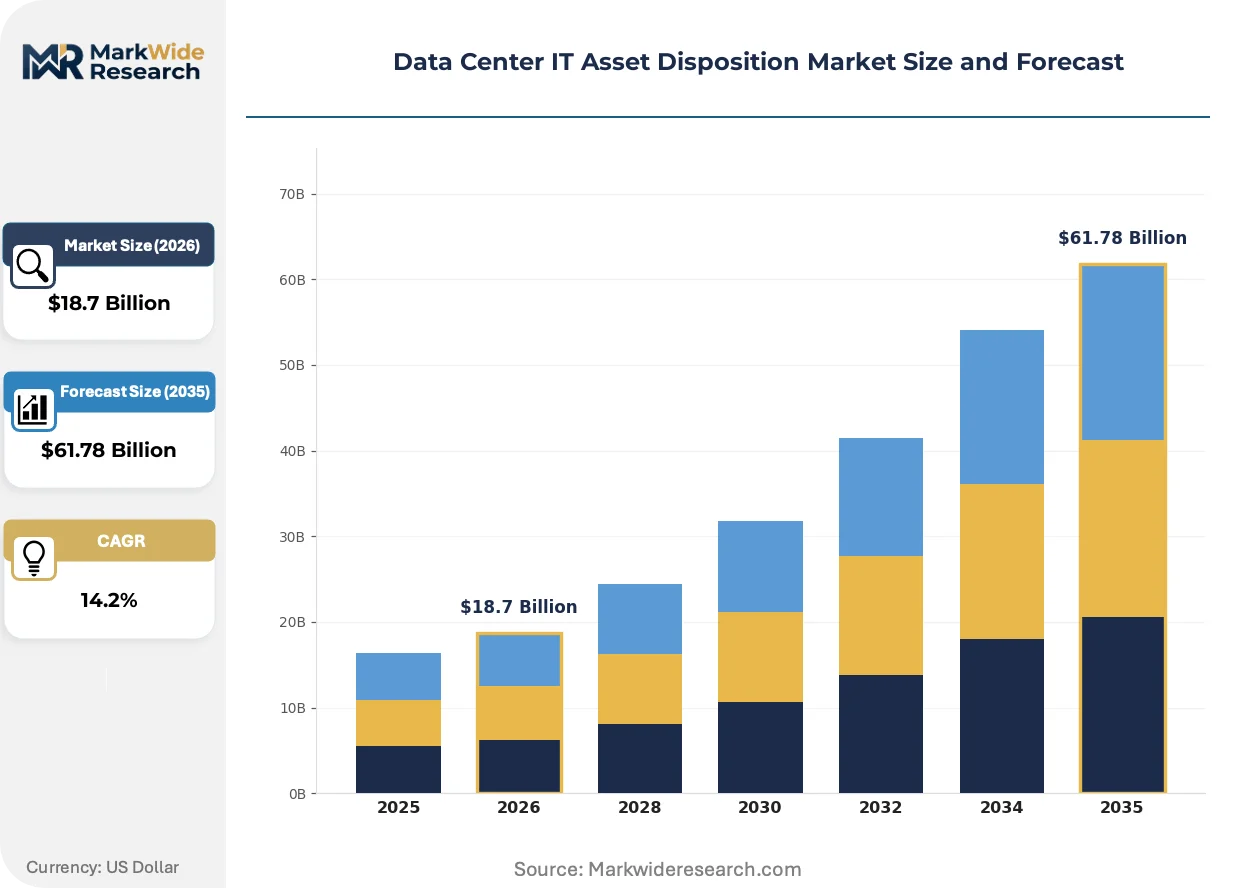
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
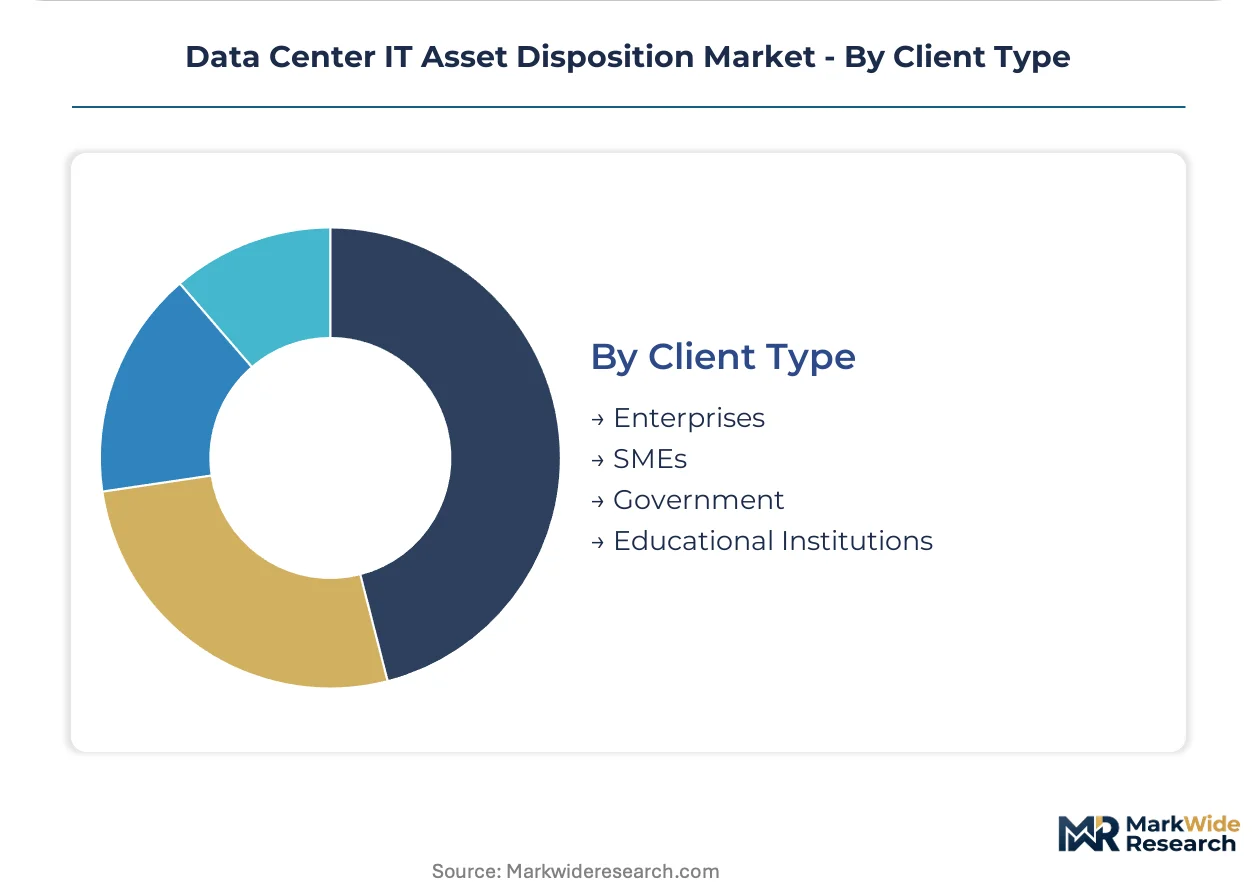
| Segmentation | Disposition Method: Recycling, Reselling, Donation, Landfill Asset Type: Servers, Storage Devices, Networking Equipment, Workstations Service Model: Onsite, Offsite, Hybrid, Managed Services Client Type: Enterprises, SMEs, Government, Educational Institutions |
| Companies Covered | Ingram Micro, DMD Systems Recovery, Iron Mountain, HOBI International, Securis, Dell, Sims Lifecycle Services, ERI, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center IT Asset Disposition Market Emerging Trajectories
Automation is penetrating asset triage and component grading, while regulatory disclosure requirements force traceability investments downstream into smelter networks previously opaque to ITAD providers.
Automated optical sorting systems equipped with AI-driven component recognition are displacing manual teardown labor in high-volume processing facilities. Hyperscale operators in the United States and Germany now mandate machine-graded resale certificates for servers under 24 months old. This compression of assessment cycles is displacing traditional refurbishment timelines and forcing smaller ITAD providers to outsource grading to regional hub facilities.
The SEC climate disclosure rules are extending scope-3 emissions tracking to retired asset downstream vendors. Financial services firms in the United States must now document smelter-level recovery rates for precious metals extracted from decommissioned storage arrays. This transparency mandate is driving ITAD providers to secure exclusive offtake agreements with RMI-certified refiners rather than commodity brokers.
Enterprise buyers now unbundle data destruction witnessing from physical logistics, selecting specialized auditors for certificate issuance while contracting transport separately. Financial and healthcare verticals in Germany and the United States drive this fragmentation, treating NIST 800-88 compliance as a distinct procurement category from chain-of-custody services. This bifurcation pressures full-service ITAD providers to defend margin pools through certification exclusivity rather than bundled convenience.
Data Center IT Asset Disposition Market Segmentation

ITAD providers configure service architectures around disposition velocity and security requirements. Segment boundaries determine logistics investments, certification stacking, and margin capture across hyperscale and enterprise workflows.
Disposition Method:
Channel economics vary sharply by method, with bulk flows favoring automated processing and premium recovery demanding witnessed handling.
- Recycling:Mechanical shredding and hydrometallurgical extraction handle storage arrays and obsolete networking gear. Rare-earth yield rates from shredded drives concentrate value recovery in Germany and China where smelter networks are densest.
- Reselling:Functional servers under 36 months undergo NIST 800-88 sanitization before secondary-market placement. Hyperscale operators in the United States now mandate machine-graded resale certificates for recent-generation hardware.
- Donation:Refurbished workstations flow to educational institutions through EPA-compliant channels with tax-documentation packages.
- Landfill:Residual fractions after materials recovery enter hazardous waste streams under EPA RCRASubtitle C protocols.
Recycling dominates installed base. Reselling is where expansion concentrates.
Asset Type:
Processing complexity and data sensitivity escalate from networking peripherals to core compute infrastructure.
- Servers:High-density blade and rack units from hyperscale decommissions drive volume concentration. Component-level recovery of CPUs and memory modules yields premium margins when processed through R2-certified facilities in the United States.
- Storage Devices:HDD and SSD arrays require specialized degaussing or cryptographic erasure before shredding. Healthcare and financial verticals in Germany demand witnessed destruction for HIPAA-equivalent compliance.
- Networking Equipment:Switches and routers carry lower residual data risk, enabling faster triage and resale velocity through enterprise secondary markets.
- Workstations:Desktop and laptop fleets from SME clients generate dispersed pickup logistics that favor regional hub consolidation before processing.
Servers dominate installed base. Storage devices is where expansion concentrates.
Service Model:
Client liability tolerance and audit requirements determine the physical custody chain from data center to final disposition.
- Onsite:Mobile shredding and degaussing units deploy to client facilities for witnessed destruction. Financial services firms in the United States contract dedicated teams for quarterly decommissioning windows.
- Offsite:Secure transport to centralized processing hubs achieves scale economies for bulk server flows. Iron Mountain leverages its document-management footprint to anchor high-volume lanes.
- Hybrid:Physical audit presence at decommissioning combines with offsite processing flexibility. This model captures margin pools as clients unbundle witnessing from logistics.
- Managed Services:End-to-end program management covers asset tracking, certificate issuance, and regulatory filing for multi-site enterprises.
Offsite dominates installed base. Hybrid is where expansion concentrates.
Client Type:
Procurement sophistication and compliance burden vary across organizational scale and sector.
- Enterprises:Multi-national corporations mandate dual R2 and e-Stewards certification with scope-3 emissions documentation. SEC climate disclosure rules extend accountability to downstream vendor networks.
- SMEs:Mid-market clients prioritize cost efficiency over witnessed handling, accepting serialized certificates without physical audit presence.
- Government:Federal and defense contracts require NIST 800-88 Rev. 1 compliance with documented chain-of-custody. State-level e-waste mandates in California and New York add parallel workflows.
- Educational Institutions:Universities and school districts leverage donation channels for workstation fleets, capturing tax benefits through EPA-compliant refurbishment programs.
Enterprises dominate installed base. Government is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based ITAD providers export decommissioned server components to German and Chinese smelter networks, creating a tripartite trade corridor that concentrates value recovery in jurisdictions with dense rare-earth processing infrastructure.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth compress server refresh cycles to 36 months, flooding channels with bulk decommissioning volumes. SEC climate disclosure rules extend scope-3 emissions tracking to retired asset downstream vendors, forcing documentation through RMI-certified refiners. Chicago and Phoenix anchor secure transport lanes for high-density server flows moving toward processing hubs.
Germany
Frankfurt and Berlin data center clusters generate concentrated retirement volumes as operators comply with EU WEEE Directive chain-of-custody mandates. The country's national environmental regulator enforces tightened documentation requirements that pull enterprise disposition toward certified specialists. Bavaria hosts dense smelter networks where rare-earth yield rates from shredded storage arrays achieve premium extraction economics.
China
Domestic cloud buildouts in Beijing and Shanghai generate first-generation retirement volumes as facilities reach initial end-of-life windows. The Ministry of Ecology and Environment restricts cross-border movement of assets containing residual storage media, trapping hardware value in domestic recovery channels. Guangdong Province concentrates component-level recycling capacity for neodymium and dysprosium extraction from decommissioned drives.
India
Maharashtra and Karnataka data center buildouts under the PLI scheme for electronics manufacturing will generate greenfield retirement volumes by 2028. The country's national electronics regulator enforces emerging e-waste frameworks that tighten producer responsibility obligations. Mumbai and Bangalore anchor early ITAD infrastructure investments targeting hyperscale operator contracts.
Japan
Tokyo and Osaka enterprise data centers drive steady decommissioning demand as operators refresh aging infrastructure under METI energy efficiency guidelines. The country's national industrial standards body certifies destruction protocols that align with NIST 800-88 equivalents for financial sector compliance. Kansai region facilities specialize in tape media degaussing for healthcare and government verticals.
Data Center IT Asset Disposition Market Vendor Landscape
Player mix skews toward diversified logistics conglomerates with adjacent secure transport capabilities, creating tiered competition between scale-driven processors and specialized component recovery operators. Market structure concentrates around providers with dual R2 and e-Stewards certification stacks that function as enterprise contract prerequisites. Three archetypes dominate: document-management incumbents repurposing secure transport networks, pure-play electronics recyclers competing on rare-earth yield rates, and OEM-affiliated service arms bundling disposition with refresh cycles. Competitive moves center on certification stacking for contract eligibility and exclusive offtake agreements with RMI-certified refiners to secure scope-3 documentation pathways.
Within the diversified logistics tier, Iron Mountain leverages its document-management footprint to anchor high-volume secure transport lanes for hyperscale decommissions. Sims Lifecycle Services exemplifies the specialized component recovery archetype, competing on rare-earth extraction economics from shredded storage arrays. Dell occupies a position bridging OEM-affiliated service provision with integrated refresh-cycle bundling for enterprise clients.
| Leading Market Players |
|---|
| Ingram Micro |
| DMD Systems Recovery |
| Iron Mountain |
| HOBI International |
| Securis |
| Dell |
| Sims Lifecycle Services |
| ERI |
| Hewlett Packard Enterprise |
| Others |
Supply Flow & Price Mechanics
Sixty-day inventory cycles for rare-earth-bearing storage arrays concentrate pricing power with German and Chinese smelter networks, while hyperscale decommissioning velocity compresses logistics lead times for ITAD providers managing bulk server flows from Northern Virginia to processing hubs.
Pricing Analysis
Current-generation servers under 24 months command resale premiums through machine-graded certificates, while prior-generation hardware faces accelerated depreciation as hyperscale operators force refresh cycles shorter. Three-tier pricing structure across premium R2-e-Stewards dual-certified, standard single-certified, and economy non-certified levels differentiates buyer segments. Cost compression in component recovery runs through rare-earth yield volatility as neodymium spot prices fluctuate. SMEs exhibit highest price sensitivity, accepting serialized certificates without witnessed handling, while financial services firms absorb premium pricing for onsite audit presence.
Supply Chain Analysis
Port congestion along Asia-Pacific trade lanes elevates inbound logistics costs for decommissioned storage arrays routed to Chinese rare-earth refiners. Supply concentrates in the United States for hyperscale decommissioning volume, Germany for EU WEEE-compliant processing, and China for component-level extraction. The ITAD value chain draws from specialized degaussing equipment, RMI-certified refiner capacity, and certified transport fleets. Single-source vulnerability in R2 auditor training programs constrains processing throughput. Distribution runs through secure transport lanes anchored by document-management incumbents before hub-and-spoke consolidation at regional processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center IT asset disposition functions as a platform-economics inflection where certification interoperability between R2 and e-Stewards standards creates network effects that consolidate contract eligibility around dual-certified providers.
For Market Incumbents: Consolidate processing capacity through exclusive offtake agreements with RMI-certified refiners to secure scope-3 documentation pathways for financial sector clients. Acquire regional hub facilities in India to capture greenfield decommissioning volumes from PLI scheme data center buildouts before certification requirements tighten. Defend margin pools against pure-play recyclers by embedding managed services contracts with enterprise clients. For New Entrants and Emerging Players: R2-e-Stewards dual certification fast-track opens contract eligibility with multinational enterprises mandating both standards for ESG compliance. Target India's emerging hyperscale market where first-generation retirement volumes lack established ITAD relationships. Pursue government sector contracts requiring NIST 800-88 Rev. 1 compliance, as certified technician scarcity creates procurement bottlenecks that favor agile specialists. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because SEC climate disclosure rules and EU WEEE Directive mandates embed recurring demand for documented chain-of-custody services. Acquisition targets should display dual certification stacks with established relationships with RMI-certified refiners. Watch for convergence between R2 and e-Stewards standards as the inflection signal that collapses certification premiums and accelerates provider consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | R2-e-Stewards stacking captures enterprise contracts requiring both standards in the United States and Germany. |
| RMI-Certified Refiner Partnership | Exclusive offtake agreements secure scope-3 emissions documentation pathways for financial sector clients. |
| India Hub Facility Buildout | Early infrastructure positioning captures hyperscale operator contracts from PLI scheme data center expansion. |
| Automated Optical Sorting Deployment | AI-driven component grading displaces manual teardown labor and accelerates resale certificate issuance. |
| Onsite Witnessing Service Launch | Hybrid engagement model addresses financial sector liability concerns without sacrificing logistics efficiency. |
Methodological Framework
The analysis maps disposition method segmentation, service model configurations, and asset type workflows, each validated through primary interviews with data center operations directors, IT procurement officers, certified destruction technicians, and R2 auditor training program administrators. Secondary validation draws from EPA hazardous waste filings, SEC climate disclosure rulemakings, EU WEEE Directive implementation guidance, and hyperscaler capex decommissioning disclosures. Bottom-up volume estimates triangulate against top-down market sizing across the analysis window.
Consistency checks validate volume and value outputs against external benchmarks including rare-earth extraction rate disclosures from German smelter networks and RMI-certified refiner throughput data. The analytical framework models disposition method, asset type, service model, and client type dimensions over the projection horizon. CAGRs derive from regression analysis of historical decommissioning velocity against regulatory mandate implementation timelines and hyperscale refresh cycle compression patterns.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale decommissioning velocity and stable rare-earth spot price bands; material deviation in either input would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Global Mega Data Center Market