
 Paris Data Center Market | 2026-2036
Paris Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Paris Data Center Market Insights
Financial services is realigning the Paris data center demand profile as banks and insurers migrate core systems off-premises. Amazon Web Services leverages its cloud sovereignty partnerships to capture regulated workloads from French institutions. DATA4 Group anchors its expansion strategy around the Paris-Saclay cluster, where land and power constraints favor purpose-built campuses. Equinix competes through dense interconnection fabrics linking financial exchanges and cloud on-ramps.
Paris data centers are mission-critical facilities housing compute, storage, and networking infrastructure within purpose-built structures requiring power densities exceeding 30 kilowatts per rack and precision cooling to maintain 18-27°C operating ranges. Colocation dominates current revenue as enterprises shed owned assets, while edge computing represents the fastest-growing technology segment as latency-sensitive applications proliferate across the Île-de-France region. Cloud services command premium pricing where hyperscalers offer localized instances meeting French data residency requirements.
France's national cybersecurity agency ANSSI mandates certification for operators of vital importance, directly shaping facility design and operational protocols. The EU CSRD and France's RE2020 environmental standards enforce granular energy disclosure and carbon intensity thresholds that filter market access toward efficient operators. Stakeholders must monitor evolving AI training cluster deployments, as power allocations and grid interconnection timelines will determine which facilities capture the next wave of capacity expansion.
Market Dynamics
France's RE2020 environmental standards and the EU Energy Efficiency Directive are compressing facility design timelines as operators race to deploy liquid-cooled infrastructure before carbon intensity thresholds harden. Financial services migration off-premises is accelerating rack density requirements beyond legacy air-cooled limits.
Growth Catalysts
- EU CSRD disclosure mandates:Granular energy reporting requirements are filtering market access toward efficient operators with certified measurement systems. Banks and insurers now require documented carbon intensity from colocation partners.
- Liquid cooling technology:Direct-to-chip and immersion systems are unlocking power densities above 30 kilowatts per rack in the Paris-Saclay corridor. Hyperscale deployments are concentrating where nuclear baseload power meets fiber density.
- Digital transaction volumes:French financial institutions are expanding colocation footprints to handle real-time payment infrastructure and algorithmic trading platforms. Core system off-premises migration is reshaping facility specifications.
Market Restraints
- Grid interconnection queues:Électricité de France transmission upgrade timelines are extending power allocation delays for facilities above 50 megawatts. New capacity commitments are slipping 18-24 months behind original schedules.
- Land scarcity in Paris-Saclay:Purpose-built campus development is competing with residential and research zone expansion for limited parcels with adequate fiber and substation proximity.
- Copper and aluminum price volatility:Busbar and cabling material costs are fluctuating 15-20% quarter-to-quarter, compressing margin visibility on fixed-price construction contracts.
Strategic Opportunities
- Edge computing nodes in Île-de-France suburbs:Latency-sensitive manufacturing and autonomous vehicle testing are creating demand for sub-10 millisecond facilities in Seine-et-Marne and Essonne departments.
- AI training cluster deployments:Large language model workloads are seeking 100+ megawatt allocations with direct liquid cooling. Facilities with pre-approved grid connections are capturing advance commitments.
- Cloud sovereignty partnerships:French data residency requirements under CNIL guidance are enabling localized instance offerings that command premium positioning against standard global regions.
Industry Challenges
- ANSSI certification timelines:Operators of vital importance designation requires 12-18 month security audit cycles that delay revenue recognition on contracted capacity.
- Liquid cooling technician scarcity:Specialized plumbing, dielectric fluid handling, and corrosion management skills are concentrated among fewer than 200 certified professionals across France.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paris Data Center Market |
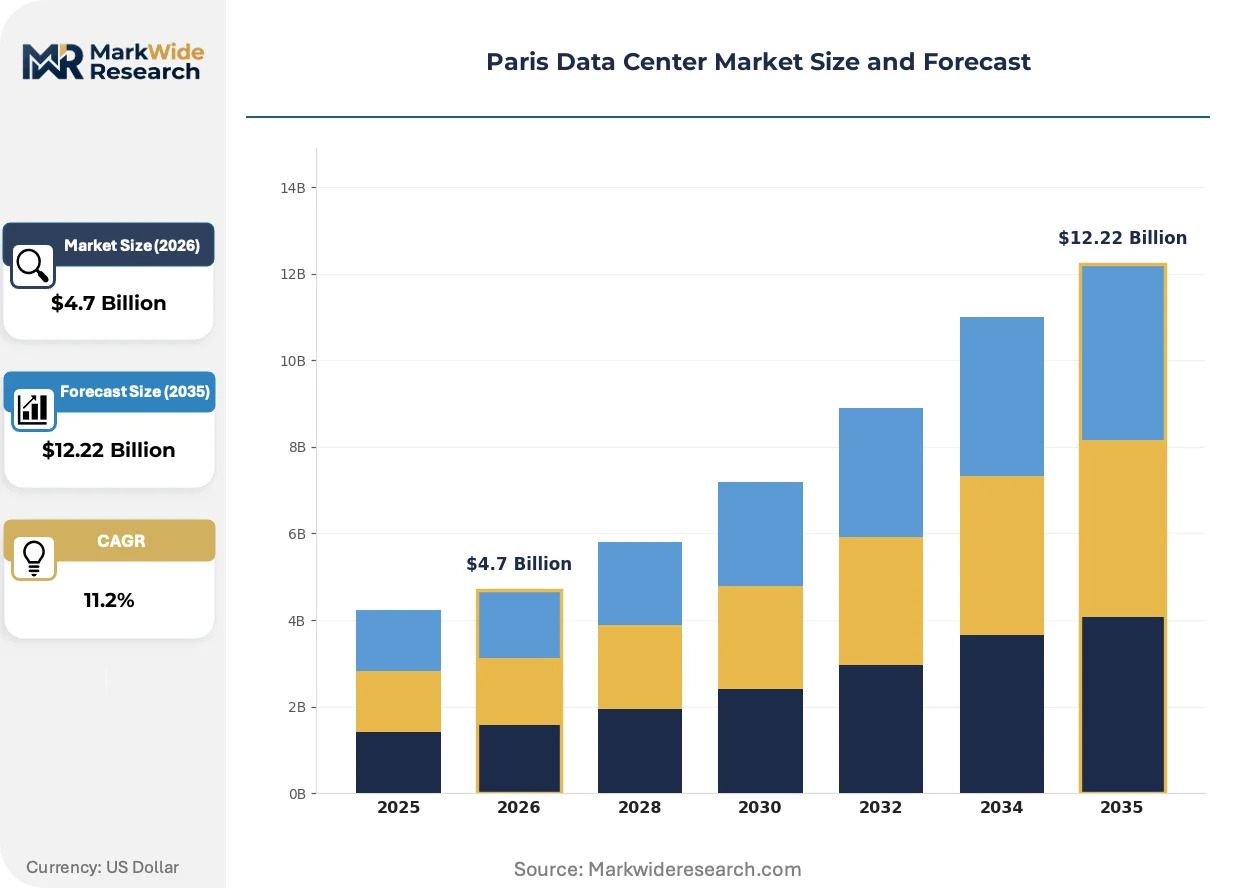
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.22 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Dedicated Hosting, Cloud Services Technology: Virtualization, Edge Computing, Network Security, Cooling Solutions End User: IT Services, Telecom, E-Commerce, Government Service Type: Installation, Maintenance, Support, Consulting |
| Companies Covered | Amazon Web Services, NTT, DATA4 Group, Global Switch, Telehouse, Digital Realty Trust, Microsoft, Colt Data Centre Services, Equinix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paris Data Center Market Trends and Innovations
Paris data center architecture is pivoting from air-cooled legacy designs to liquid-cooled, high-density configurations as AI workloads and environmental compliance converge. Facility operators are reengineering power distribution and cooling topology to capture this structural shift.
Immersion cooling systems using synthetic dielectric fluids are expanding into hyperscale and enterprise colocation facilities seeking power densities beyond 50 kilowatts per rack. French banks with algorithmic trading operations are adopting these systems fastest, driven by latency and thermal stability requirements. The technology is expanding into standard colocation offerings previously limited to 10-15 kilowatt air-cooled configurations.
France's RE2020 building standards now mandate operational carbon disclosure for new data center construction, with enforcement through the country's environmental regulator. Facility developers must submit lifecycle carbon assessments before permitting, extending pre-construction timelines. The Paris-Saclay cluster is responding with modular, factory-built designs that reduce on-site construction emissions and accelerate compliance documentation.
Financial services procurement teams are unbundling interconnection services from base colocation contracts, negotiating cloud on-ramp and exchange access as separate line items. This behavior is compressing traditional bundled pricing models and forcing operators to disclose cross-connect margins. The shift is most visible among Paris-based asset managers and insurance groups with multi-cloud strategies.
Paris Data Center Market Segmentation
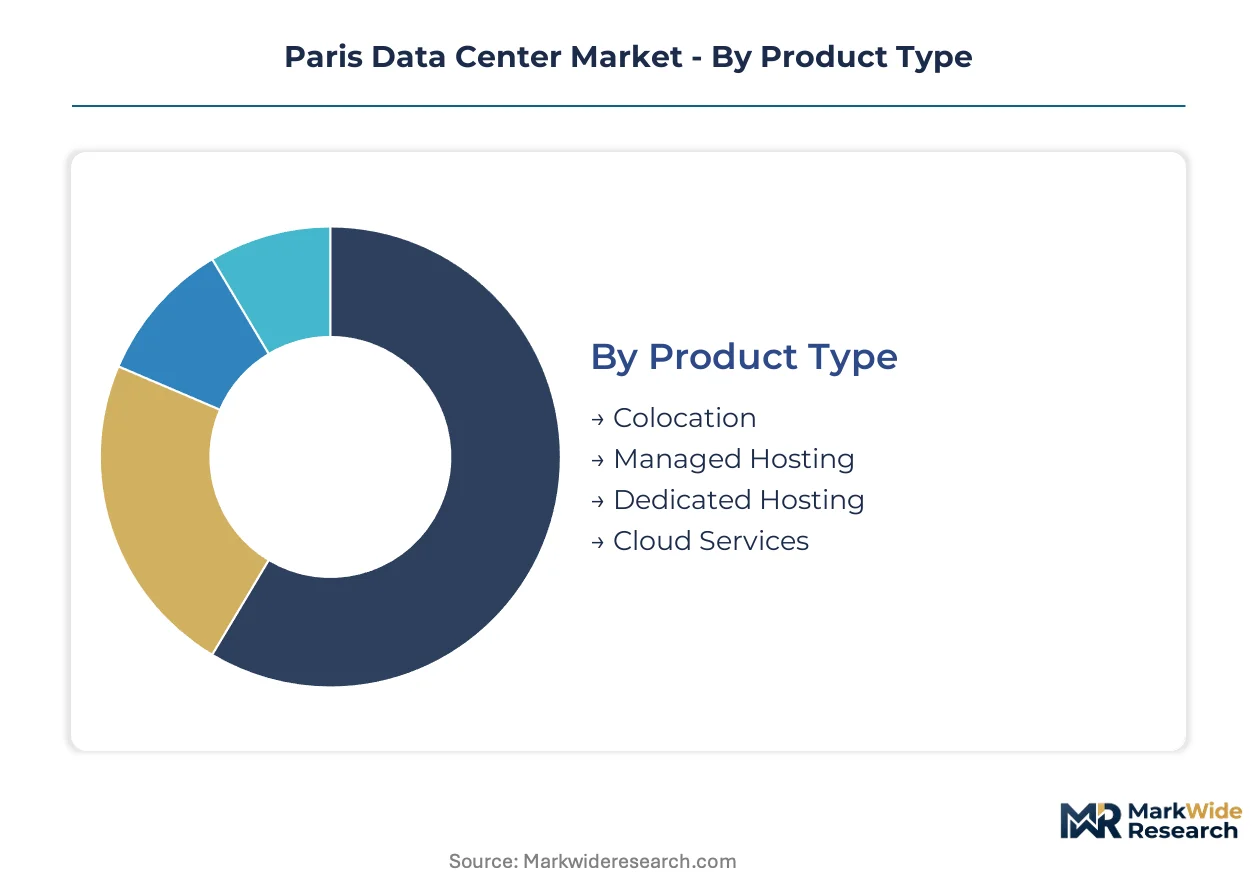
Segmentation in the Paris data center market reveals how capital allocation and operational complexity vary dramatically across service models and infrastructure layers. Understanding these divisions helps operators prioritize investments where regulatory compliance, power density, and customer retention intersect most profitably.
Product Type:
Capital intensity varies most sharply across product types, with physical infrastructure ownership demanding substantially higher upfront investment than service-layer offerings.
- Colocation:Operators construct and maintain facility shells, power distribution, and cooling systems while tenants supply their own servers. French financial institutions are migrating core systems into these facilities as ANSSI certification requirements harden facility specifications. RE2020 carbon disclosure mandates favor operators with pre-certified measurement infrastructure.
- Cloud Services:Hyperscalers deploy localized instances meeting CNIL data residency guidance, commanding premium positioning against standard global regions. AWS and competitors are expanding Paris-Saclay capacity where nuclear baseload power supports 100+ megawatt allocations.
- Managed Hosting:Providers own and operate server hardware on behalf of single-tenant customers, absorbing hardware refresh cycles and software patching obligations.
- Dedicated Hosting:Single-tenant physical or virtual server deployments offer isolation without full facility ownership, bridging colocation flexibility with managed service simplicity.
Colocation absorbs the bulk of installed capacity; cloud services are expanding most quickly as sovereign cloud partnerships capture regulated French workloads.
Technology:
Technology segments differentiate by operational risk profile, with thermal management and perimeter security carrying the highest failure-cost exposure.
- Cooling Solutions:Direct-to-chip and immersion systems unlock power densities above 50 kilowatts per rack in the Paris-Saclay corridor. Liquid cooling technician scarcity—fewer than 200 certified professionals nationwide—is constraining deployment velocity for hyperscale AI clusters.
- Network Security:ANSSI mandates certification for operators of vital importance, requiring 12-18 month security audit cycles that delay revenue recognition. French banks with algorithmic trading operations prioritize low-latency, certified secure interconnects.
- Virtualization:Software-defined compute and storage abstraction enables multi-tenant resource pooling and rapid workload migration.
- Edge Computing:Sub-10 millisecond facilities in Seine-et-Marne and Essonne departments serve latency-sensitive manufacturing and autonomous vehicle testing.
Cooling solutions command the highest capital allocation per square meter; edge computing is climbing the fastest as Île-de-France industrial zones digitize.
End User:
End user concentration tracks regulatory exposure and transaction volume intensity, with financial-adjacent sectors driving the most demanding facility specifications.
- IT Services:Systems integrators and managed service providers aggregate demand from mid-market enterprises, favoring modular colocation contracts with flexible power increments.
- Telecom:Mobile network operators and fiber carriers require dense interconnection fabrics linking cellular core networks to cloud on-ramps.
- E-Commerce:Peak-load volatility from promotional events drives demand for burst capacity and geographically distributed failover.
- Government:National and municipal entities procure through formal tender processes with extended security clearance requirements.
IT services anchor current revenue concentration; government procurement is gaining share fastest as digital sovereignty policies expand public sector cloud migration.
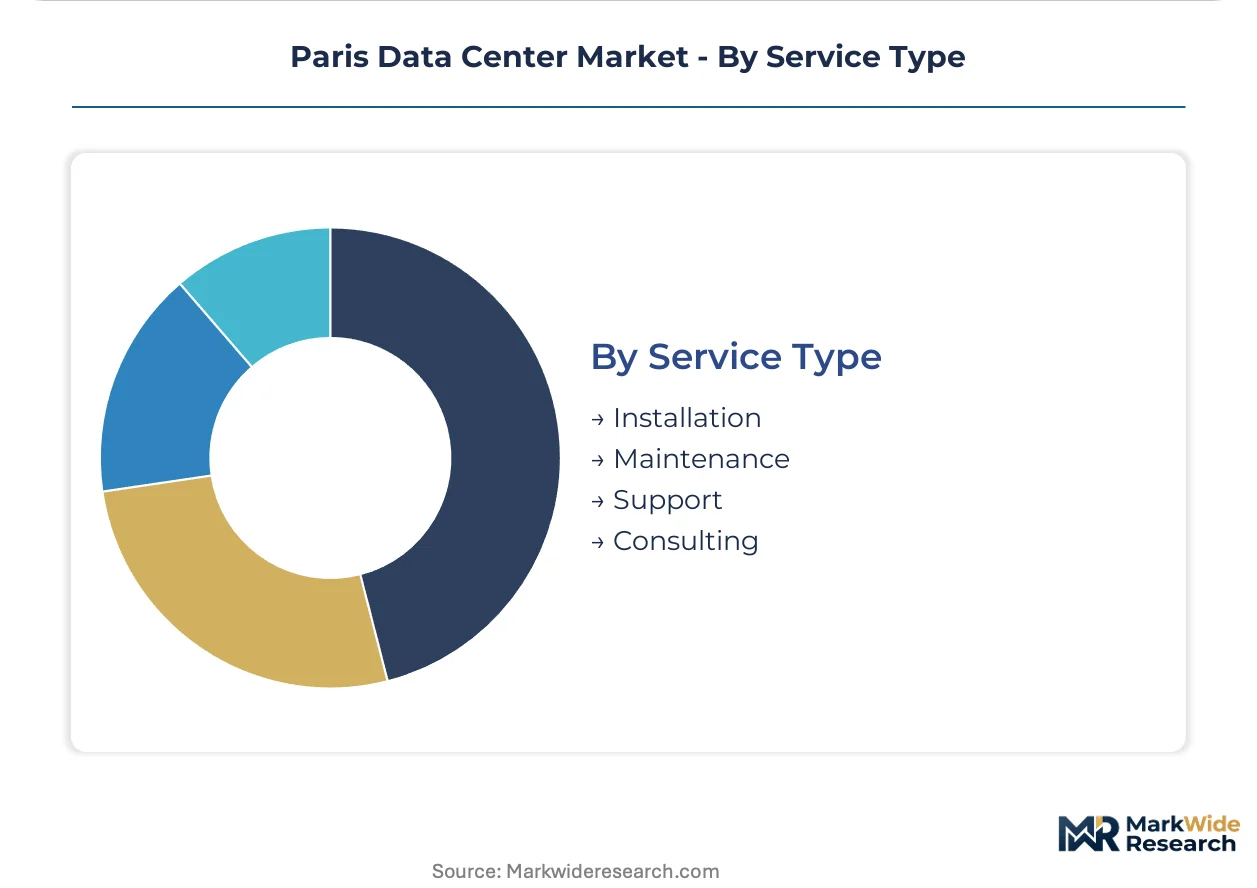
Service Type:
Service type margins correlate inversely with labor substitutability, with consulting and design services retaining premium pricing against commoditized maintenance.
- Installation:Mechanical and electrical fit-out, including busbar deployment and precision cooling commissioning, faces 15-20% quarter-to-quarter material cost volatility.
- Consulting:Facility design, energy efficiency optimization, and regulatory compliance planning extend pre-construction timelines under RE2020 lifecycle carbon assessment requirements.
- Maintenance:Scheduled preventive and corrective interventions on power and cooling infrastructure.
- Support:Remote monitoring, help desk, and incident response services with defined SLA tiers.
Installation absorbs the greatest capital equipment share; consulting is expanding most quickly as carbon disclosure and ANSSI certification complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paris-Saclay tax-advantaged zone concentrates hyperscale investment where nuclear baseload power and dense fiber infrastructure converge. This corridor anchors national capacity expansion as operators compete for land with adequate substation proximity and RE2020 environmental certification pathways.
Île-de-France
Financial institutions drive rack density requirements above 30 kilowatts as algorithmic trading and real-time payment infrastructure expand. ANSSI certification mandates shape facility security protocols with 12-18 month audit cycles. The Paris-Saclay cluster captures hyperscale deployments where Électricité de France transmission upgrades enable 100+ megawatt allocations.
Auvergne-Rhône-Alpes
Industrial digitization in Lyon and Grenoble creates demand for edge computing nodes serving manufacturing automation. The EU CSRD disclosure requirements filter procurement toward operators with certified carbon measurement systems. The Lyon metropolitan zone attracts sub-10 millisecond latency facilities for autonomous vehicle testing corridors.
Provence-Alpes-Côte d'Azur
Maritime logistics and aerospace supply chains generate colocation demand from systems integrators and managed service providers. France's RE2020 building standards extend pre-construction timelines through lifecycle carbon assessment mandates. The Sophia Antipolis technology park hosts modular data center deployments targeting Mediterranean connectivity routes.
Hauts-de-France
Cross-border financial services from Lille and proximity to Belgian and UK fiber routes position the region for disaster recovery and backup capacity. The EU Energy Efficiency Directive enforces granular energy reporting that advantages efficient operators. The Lille metropolitan area competes on land availability and lower construction costs versus Paris-Saclay constraints.
Nouvelle-Aquitaine
Agricultural technology and wine industry digitization create specialized edge computing demand for IoT sensor networks and supply chain traceability. CNIL data residency guidance under French data protection law shapes localized cloud procurement requirements. The Bordeaux technology cluster attracts smaller-scale colocation facilities serving regional enterprise mid-markets.
Paris Data Center Market Competitive Landscape
Top-tier vendors anchor hyperscale capacity deployment, while mid-tier specialists compete on interconnection density and regulatory certification speed. The market structures around three tiers: nuclear-powered campus developers, urban interconnection specialists, and cloud sovereignty partners. Strategic archetypes include land-and-power aggregators, financial exchange proximity players, and AI cluster specialists. Dominant competitive moves center on pre-approved grid connection capture and ANSSI certification pipeline investment.
Among hyperscale cloud operators, Amazon Web Services and Microsoft occupy positions defined by cloud sovereignty partnerships and localized instance offerings. DATA4 Group and Equinix exemplify contrasting infrastructure strategies, with the former anchoring purpose-built campus development and the latter representing dense interconnection fabric deployment. These four entities collectively illustrate how regulatory compliance, power access, and network topology differentiate competitive positioning in the Paris market.
| Leading Market Players |
|---|
| Amazon Web Services |
| NTT |
| DATA4 Group |
| Global Switch |
| Telehouse |
| Digital Realty Trust |
| Microsoft |
| Colt Data Centre Services |
| Equinix |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ANSSI-certified facilities and uncertified colocation space manifests in both pricing premiums and supply chain sourcing patterns. Premium-tier operators command sustained margin advantage through pre-approved grid connections and liquid-cooled infrastructure, while commodity providers face procurement constraints from copper busbar volatility and extended Électricité de France interconnection queues.
Pricing Analysis
Short lead-time availability commands substantial premiums in the Paris-Saclay corridor where Électricité de France transmission upgrades delay new capacity by 18-24 months. Three-tier pricing structure across premium, standard, and economy levels reflects ANSSI certification status, liquid cooling deployment, and nuclear power proximity. Cost compression in standard colocation is intensifying because hyperscalers pre-commit megawatt blocks at fixed rates. Asset managers and insurance groups with multi-cloud strategies exhibit highest price sensitivity through unbundled interconnection negotiations, while algorithmic trading operations show least sensitivity due to latency requirements.
Supply Chain Analysis
Regional distribution centers for precision cooling equipment and power distribution units concentrate in Germany, the Netherlands, and Belgium to serve Paris-Saclay deployment timelines. Critical inputs include synthetic dielectric fluids for immersion cooling, copper and aluminum busbar for power distribution, and factory-built modular data center components. Single-source vulnerability sits with French liquid cooling technician scarcity—fewer than 200 certified professionals nationwide. Distribution runs through direct manufacturer-to-operator channels for hyperscale projects, with systems integrators handling mid-market colocation fit-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as RE2020 carbon disclosure mandates and ANSSI certification timelines filter subscale operators from contract eligibility. Grid interconnection queue positioning and liquid cooling deployment capability will determine which facilities capture the next wave of AI cluster demand.
For Market Incumbents: Deepen vertical integration into liquid cooling system maintenance and dielectric fluid supply chains to offset technician scarcity constraints. Secure pre-approved grid connection allocations above 50 megawatts before Électricité de France transmission upgrade timelines extend further. Anchor expansion in the Paris-Saclay corridor where land and power constraints favor purpose-built campus scale. For New Entrants and Emerging Players: Launch via edge computing nodes in Seine-et-Marne and Essonne departments where sub-10 millisecond latency requirements from manufacturing automation remain underserved. Target the agricultural technology sector in Nouvelle-Aquitaine for specialized IoT sensor network hosting. Pursue cloud sovereignty partnerships with CNIL-compliant localized instance offerings as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with ANSSI-certified operators holding pre-approved grid connections given the structural supply-demand imbalance in Paris-Saclay power allocation. Long-term viability over the next decade hinges on liquid cooling deployment velocity and AI training cluster capture. Facilities with direct nuclear baseload power contracts represent the acquisition target archetype. Watch hyperscale advance commitment announcements as the signal for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Direct-to-chip and immersion systems unlock power densities above 50 kilowatts per rack for AI clusters. |
| Grid Connection Pre-Approval Capture | Électricité de France transmission queue positioning determines 18-24 month capacity delivery timelines. |
| ANSSI Certification Pipeline Investment | Security audit cycles lasting 12-18 months filter market access toward prepared operators. |
| Cloud Sovereignty Partnership Formation | CNIL-compliant localized instances command premium positioning against standard global regions. |
| Modular Factory-Built Design Adoption | RE2020 lifecycle carbon assessments accelerate compliance documentation and permitting speed. |
Research Methodology
Document review covered hyperscaler capex disclosures, Électricité de France transmission planning documents, and ANSSI certification registries, complemented by interviews with data center facility directors, cloud procurement officers at French financial institutions, liquid cooling system engineers, and commercial real estate developers specializing in tax-advantaged zones. Secondary validation drew from RE2020 environmental compliance filings, EU CSRD disclosure databases, and nuclear power generation records. Bottom-up capacity installation tracking and top-down market sizing triangulated volume estimates across the analysis window.
Cross-reference between historical deployment patterns and expert panel input shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, cooling technology tier, power density band, and end-user regulatory exposure. CAGRs were derived from capacity commitment pipelines and grid interconnection timelines. Forecast inputs incorporated AI training cluster power allocation announcements and hyperscale pre-leasing activity in the Paris-Saclay corridor.
Grid interconnection delays, liquid cooling technician availability, and RE2020 enforcement stringency are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on power density evolution and carbon intensity threshold progression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
South America Data Center Power Market