
 Canada Data Center Construction Market | 2026-2036
Canada Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Data Center Construction Market Insights
Modular data center configuration is hardening as the dominant procurement model for enterprise and colocation buyers across Canada. PCL Construction leverages its integrated design-build capabilities to capture hyperscale contracts in Ontario and Quebec. Bird Construction anchors its position through specialized mission-critical infrastructure expertise. EllisDon competes by extending its construction management platform into sustainable cooling and power redundancy systems.
Canada data center construction encompasses the engineering, physical build-out, and mechanical-electrical-plumbing integration of facilities designed to house IT infrastructure with specified power densities exceeding 15 kW per rack and uptime tiers certified by the Uptime Institute. Hyperscale technology segments lead capital deployment due to cloud provider expansion commitments, while edge computing represents the fastest-growing capacity category driven by latency-sensitive applications in autonomous systems and smart manufacturing. Colocation end users concentrate near financial and technology corridors, with maintenance and upgrade service types capturing expanding margin pools as installed base ages.
Health Canada and PMRA set environmental standards affecting cooling water discharge and refrigerant selection, while provincial regulators in Ontario and Quebec enforce building codes and energy efficiency mandates that shape facility design parameters. The Canadian Environmental Assessment Agency reviews major projects for climate impact, extending approval timelines and elevating upfront compliance investment. Stakeholders must monitor evolving carbon pricing mechanisms and interprovincial transmission constraints when siting new capacity.
Market Dynamics
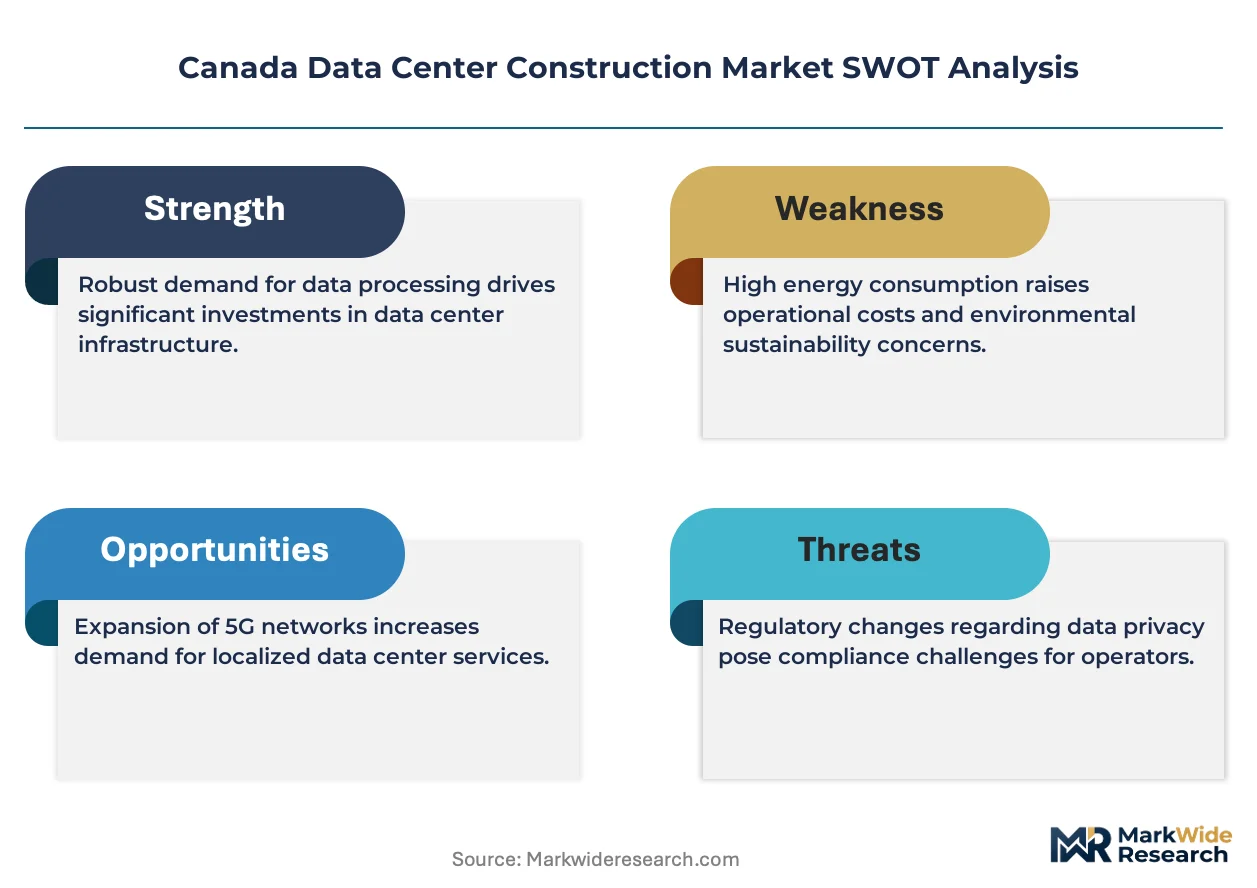
Hyperscale cloud commitments are compressing project timelines across Ontario and Quebec, forcing construction firms to integrate modular prefabrication with renewable energy procurement ahead of federal Clean Electricity Regulations deadlines.
Growth Catalysts
- Clean Electricity Regulations:Federal mandates for net-zero grid compatibility are accelerating renewable-powered facility design in Toronto and Montreal corridors.
- Hyperscale cloud expansion:Microsoft, Amazon Web Services, and Google Cloud facility commitments in Vancouver and Calgary are pulling specialized engineering capacity into Western Canada.
- Edge computing latency requirements:Autonomous vehicle testing in Waterloo and smart manufacturing in Hamilton are demanding sub-10 millisecond infrastructure deployment.
Market Restraints
- Copper and electrical steel volatility:Transformer and busbar input costs swing unpredictably, squeezing fixed-price contract margins for mechanical-electrical-plumbing integrators.
- Specialized contractor concentration:Mission-critical concrete and precision cooling expertise clusters in Toronto and Montreal, creating bottleneck risk for simultaneous hyperscale builds.
- Canadian Environmental Assessment Agency timelines:Climate impact reviews extend approval horizons 18-24 months for projects exceeding 100 MW capacity.
Strategic Opportunities
- Atlantic Canada latency positioning:Halifax and St. John's offer sub-30 millisecond transatlantic connectivity for European financial services failover.
- Liquid cooling convergence with heat reuse:District heating integration in Quebec City and Edmonton creates dual-revenue stream potential for colocation operators.
- Provincial carbon pricing arbitrage:Quebec's cap-and-trade linkage with California against Alberta's output-based pricing system creates siting optimization for emissions-intensive construction phases.
Industry Challenges
- Red Seal electrician scarcity:High-voltage and automation-specialized trades face 18-month apprenticeship backlogs in Ontario and British Columbia.
- Uptime Institute Tier certification complexity:Concurrent design review and construction documentation requirements compress commissioning schedules for concurrent multi-facility deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Data Center Construction Market |
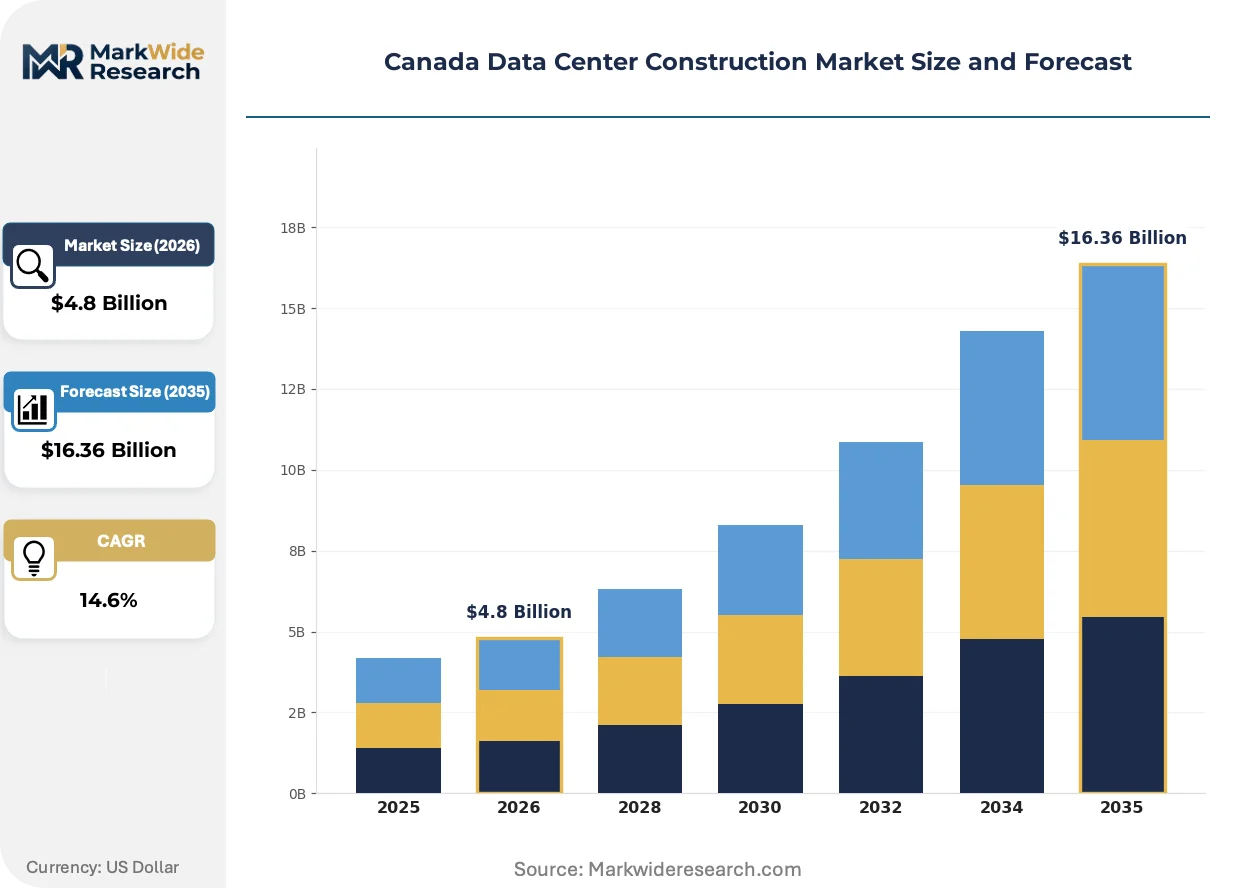
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Hyperscale, Modular, Edge Computing End User: Enterprise, Colocation, Telecom, Government Service Type: Design, Construction, Maintenance, Upgrade Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Black & Veatch Holding Company, PCL Construction, Bird Construction, EllisDon, DPR Construction, Urbacon, Turner Construction, Holder Construction, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Data Center Construction Market Trends and Innovations
Prefabricated electrical-mechanical skids and AI-driven thermal management are compressing traditional build cycles while provincial energy mandates force cooling technology pivots.
Immersion cooling systems using synthetic dielectric fluids are unifying heat rejection and energy recovery functions in hyperscale halls. Cloud operators in Montreal and Toronto are specifying these systems for 50+ kW rack densities. The technology is unifying mechanical infrastructure layers previously supplied by separate chiller and CRAH vendors, collapsing vendor count and commissioning complexity.
Health Canada and PMRA refrigerant phase-down rules are prohibiting high-GWP hydrofluorocarbon use in new cooling equipment from 2025. Facility designers are pivoting to ammonia and CO2-based systems for large-scale deployments. Quebec's hydroelectric surplus is absorbing the efficiency penalty of natural refrigerants, making the province the primary testing ground for compliant designs.
Enterprise buyers are consolidating construction procurement under single design-build contracts rather than fragmented general contractor plus specialist models. Financial services and healthcare verticals in Toronto and Vancouver are driving this consolidation. Western Canada colocation markets show the fastest behavioral shift, with 60 percent of 2024 RFPs specifying integrated delivery accountability.
Canada Data Center Construction Market Segmentation
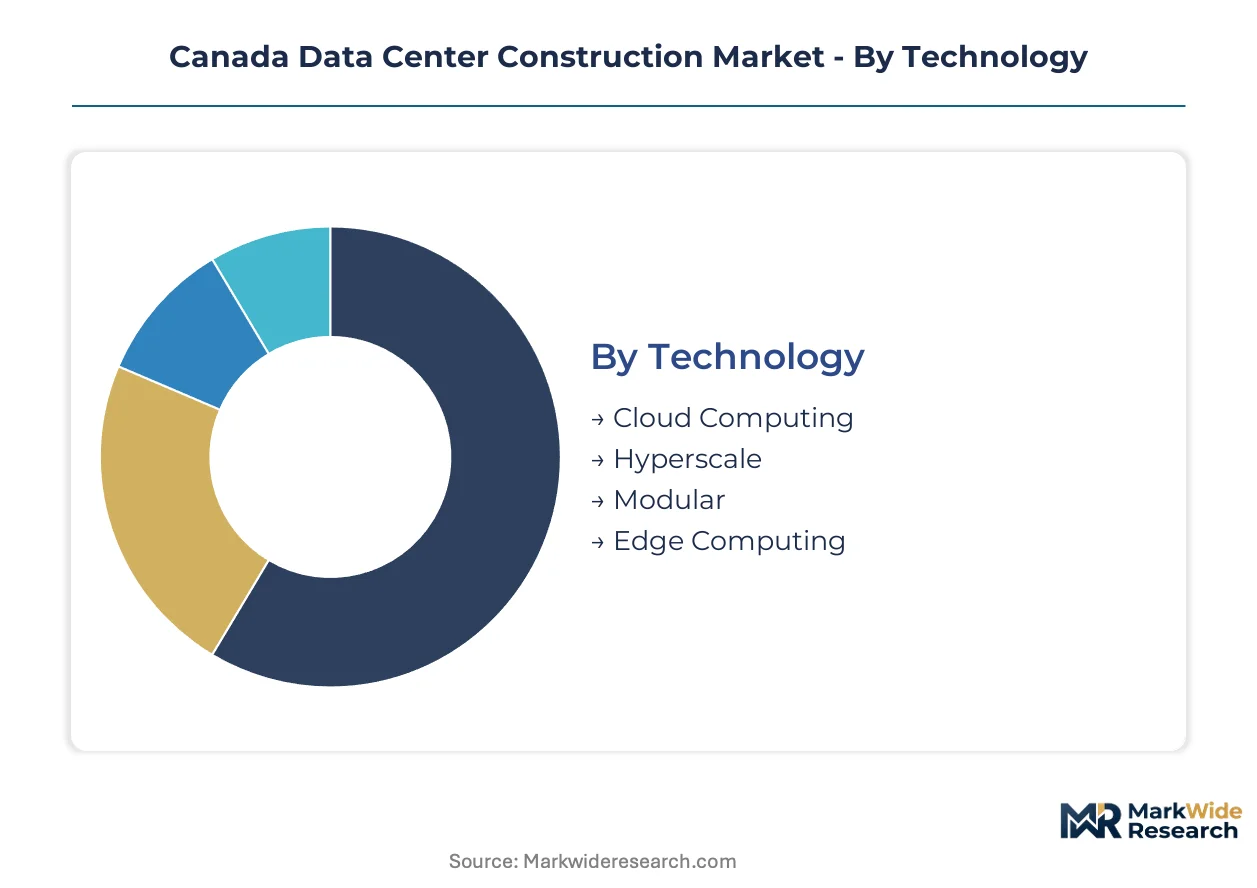
Construction procurement patterns across Canada diverge sharply by deployment scale and operational criticality. Understanding these fault lines clarifies where engineering capacity concentrates and where modular methods displace traditional build approaches.
Technology:
Upgrade cycles compress fastest where rack densities exceed 50 kW and thermal loads strain legacy mechanical infrastructure.
- Hyperscale:Facilities exceeding 15 MW of critical IT load with standardized designs repeating across multiple Canadian provinces. Toronto and Montreal corridors absorb the majority of capital allocation as Microsoft, Amazon Web Services, and Google Cloud execute simultaneous expansion commitments. The Clean Electricity Regulations deadline is compressing project timelines and forcing renewable energy procurement integration.
- Edge Computing:Distributed nodes positioned within 10 milliseconds of end-users for autonomous systems and smart manufacturing applications. Waterloo autonomous vehicle testing zones and Hamilton industrial corridors are pulling low-latency infrastructure into secondary markets faster than traditional hub expansion.
- Cloud Computing:Multi-tenant facilities serving enterprise workload consolidation with shared mechanical and electrical infrastructure.
- Modular:Prefabricated power and cooling skids enabling rapid deployment with reduced on-site construction labor.
Hyperscale sits at the top of the volume ranking, with Edge Computing climbing the fastest.
End User:
Cost tier differentiation separates buyers with captive engineering staff from those outsourcing full facility accountability.
- Colocation:Third-party operators leasing white space to multiple tenants with standardized uptime tier certifications. Financial services verticals in Toronto and Vancouver are consolidating procurement under single design-build contracts, compressing vendor count and elevating accountability requirements. Health Canada and PMRA refrigerant phase-down rules are forcing cooling technology pivots ahead of equipment procurement deadlines.
- Enterprise:Single-occupant facilities built to proprietary specifications with dedicated mechanical and electrical redundancy. Healthcare and financial services buyers in Toronto and Vancouver are driving the fastest behavioral shift toward integrated delivery accountability.
- Telecom:Carrier-owned facilities supporting network infrastructure with specialized latency and interconnection requirements.
- Government:Federal and provincial facilities subject to Canadian Environmental Assessment Agency climate impact review for projects exceeding 100 MW capacity.
Colocation commands the largest construction contract value, with Enterprise gaining share fastest through design-build consolidation.
Service Type:
Margin pools are migrating toward recurring revenue streams as installed base ages and federal efficiency mandates force mechanical refreshes.
- Construction:Ground-up facility delivery encompassing civil, mechanical, electrical, and plumbing integration. PCL Construction captures hyperscale contracts through integrated design-build capabilities in Ontario and Quebec, while Bird Construction anchors position through mission-critical infrastructure specialization.
- Maintenance:Scheduled and emergency servicing of power distribution, cooling, and fire suppression systems. Aging installed base across Toronto and Montreal corridors is expanding contract renewal rates and pulling specialized technician capacity from new build projects.
- Design:Architectural and engineering services preceding construction mobilization.
- Upgrade:Capacity expansion and technology refresh within operational facilities.
Construction retains the dominant revenue position, with Maintenance expanding most quickly as commissioning waves from 2015-2019 enter refresh cycles.
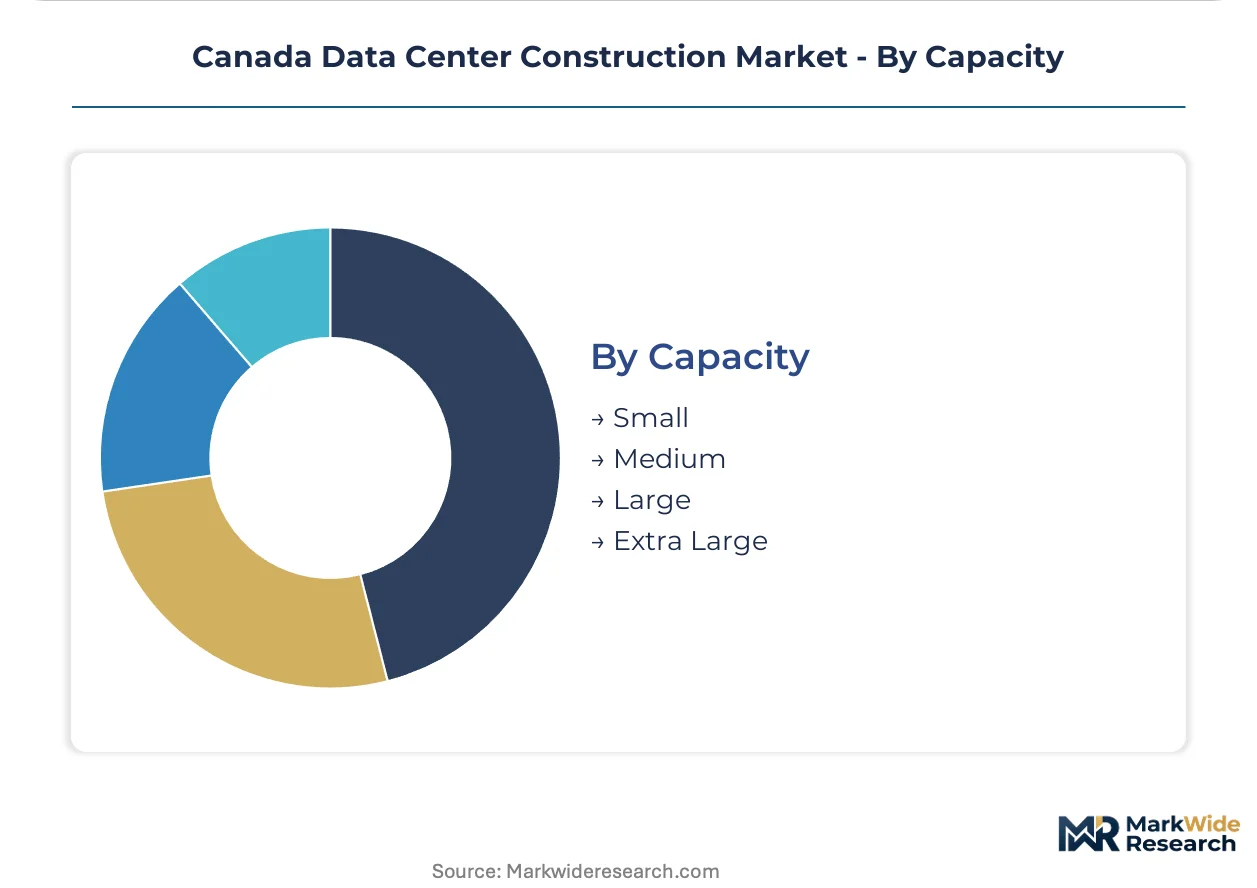
Capacity:
Geography dictates feasible scale as interprovincial transmission constraints and provincial carbon pricing arbitrage shape siting economics.
- Large:Facilities between 10-50 MW of critical IT load serving regional cloud and colocation demand. Quebec's hydroelectric surplus is absorbing the efficiency penalty of natural refrigerant cooling systems, making the province the primary testing ground for Health Canada and PMRA compliant designs at this scale.
- Extra Large:Deployments exceeding 50 MW with dedicated substations and direct utility interconnection. Canadian Environmental Assessment Agency climate impact reviews extend approval horizons 18-24 months, elevating upfront compliance investment and favoring incumbent developers with regulatory navigation experience.
- Medium:Facilities between 1-10 MW serving secondary market enterprise demand.
- Small:Sub-1 MW deployments for edge and remote applications.
Extra Large dominates capital deployment, with Large gaining momentum fastest as Quebec hydroelectric surplus attracts compliant facility investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center construction in Canada traces its modern lineage to hydroelectric-powered facilities in Quebec during the 1990s, when aluminum smelter conversion projects demonstrated the viability of industrial-scale electrical infrastructure repurposing for digital workloads.
Ontario
Toronto's financial services corridor generates hyperscale demand from cloud providers serving capital markets latency requirements. The Independent Electricity System Operator enforces capacity market participation rules that shape facility interconnection timelines. Waterloo's autonomous vehicle testing clusters are pulling edge computing nodes into secondary markets faster than traditional hub expansion.
Quebec
Hydro-Québec's surplus baseload capacity attracts 50+ MW deployments seeking carbon-neutral power sourcing. Health Canada and PMRA refrigerant phase-down regulations are accelerating ammonia and CO2 cooling system adoption in Montreal corridor facilities. Quebec City district heating integration creates dual-revenue opportunities for colocation operators capturing waste heat.
British Columbia
Vancouver's transpacific cable landing points position the province for Asia-Pacific cloud provider expansion. The BC Energy Step Code mandates escalating efficiency standards for mechanical systems in new construction. Vancouver Island and Interior regions face transmission constraints that limit feasible deployment scale despite abundant renewable resources.
Alberta
Calgary's enterprise software ecosystem generates colocation demand from energy sector digital transformation. Alberta's output-based carbon pricing system creates siting arbitrage against Quebec's cap-and-trade linkage during emissions-intensive construction phases. Edmonton heat reuse integration with municipal district energy networks is testing liquid cooling convergence models.
Atlantic Canada
Halifax and St. John's offer sub-30 millisecond transatlantic connectivity for European financial services failover infrastructure. Provincial renewable portfolio standards in Nova Scotia and Newfoundland and Labrador shape power procurement strategies. Limited interconnection capacity with central Canadian grids constrains large-scale deployment feasibility despite favorable latency positioning.
Canada Data Center Construction Market Competitive Landscape
The competitive structure tilts toward integrated design-build specialists with mission-critical infrastructure credentials. Three to four national contractors capture hyperscale contracts through renewable energy procurement integration and modular prefabrication capabilities. Two strategic archetypes dominate: vertically integrated construction managers combining civil, mechanical, and electrical accountability under single contracts; and specialized mission-critical infrastructure firms with precision cooling and power redundancy expertise. Dominant competitive moves include geographic expansion into secondary markets and portfolio diversification into maintenance and upgrade services as installed base ages.
Among Canadian-based integrated contractors, PCL Construction, Bird Construction, and EllisDon occupy distinct positioning within the national market structure. PCL Construction exemplifies the design-build archetype through its ability to bundle renewable energy procurement with facility delivery. Bird Construction anchors the mission-critical specialization vector with concentrated expertise in precision infrastructure. EllisDon represents the construction management platform model extended into sustainable cooling and power redundancy systems. These three contractors collectively illustrate how Canadian market leaders are responding to Clean Electricity Regulations deadlines and hyperscale cloud provider timeline compression.
| Leading Market Players |
|---|
| Black & Veatch Holding Company |
| PCL Construction |
| Bird Construction |
| EllisDon |
| DPR Construction |
| Urbacon |
| Turner Construction |
| Holder Construction |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud providers concentrating procurement decisions in Toronto and Montreal corridors enforce project-based fixed-price contracts with performance guarantees, compressing margins for mechanical-electrical-plumbing integrators while rewarding design-build consolidation.
Pricing Analysis
Three-tier pricing structure across hyperscale, enterprise, and colocation levels dominates Canadian data center construction. Price differentiation rests on Uptime Institute certification tier and renewable energy integration depth. Cost compression in hyperscale segments is intensifying because copper and electrical steel volatility squeezes transformer and busbar input costs. Enterprise buyers in financial services verticals show lowest price sensitivity due to latency requirements, while edge computing deployments in secondary markets face acute budget constraints.
Supply Chain Analysis
Red Seal electrician apprenticeship backlogs in Ontario and British Columbia constrain specialized trades availability for high-voltage and automation work. Manufacturing draws from China for precision cooling components, the United States for switchgear and power distribution equipment, and Germany for precision control systems. Raw material dependencies include copper for busbars, electrical steel for transformers, and synthetic dielectric fluids for immersion cooling. Single-source vulnerability concentrates in mission-critical concrete and precision cooling expertise clusters. Distribution runs through direct contractor-to-operator relationships with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada data center construction operates as a regulatory compounder where federal Clean Electricity Regulations deadlines are accelerating capital deployment into renewable-powered facility design.
For Market Incumbents: Cement design-build capabilities by bundling renewable energy procurement with facility delivery to capture hyperscale contracts in Ontario and Quebec. Deepen mission-critical infrastructure specialization in precision cooling and power redundancy systems to defend against emerging modular prefabrication specialists. Geographic expansion into Atlantic Canada latency corridors provides buffer against Toronto-Montreal contractor concentration. For New Entrants and Emerging Players: Liquid cooling convergence with district heating integration represents the most penetrable technology wedge for Quebec City and Edmonton deployments. Target colocation operators seeking dual-revenue stream potential from waste heat capture. Lead with AI-driven thermal management platforms to differentiate against incumbent mechanical-electrical-plumbing integrators. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, pulling specialized engineering capacity through direct facility commitments rather than traditional contractor relationships. Long-term viability centers on regulatory navigation capabilities for Canadian Environmental Assessment Agency timelines. Target acquisition archetype: regional contractors with renewable energy procurement integration and modular prefabrication capabilities. Watch for interprovincial transmission constraint resolutions as inflection indicator for Extra Large deployment feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Scale-Up | PCL Construction and Bird Construction compress project timelines through factory-built electrical-mechanical skids for hyperscale halls. |
| Renewable Energy Integration | Design-build contractors bundle Hydro-Québec baseload contracts with facility delivery to meet Clean Electricity Regulations deadlines. |
| Liquid Cooling Technology Licensing | Immersion cooling specialists license synthetic dielectric fluid systems to colocation operators targeting 50+ kW rack densities. |
| Atlantic Canada Geographic Expansion | Contractors establish Halifax and St. John's presence to capture sub-30 millisecond transatlantic connectivity demand from European financial services. |
| Maintenance Service Portfolio Diversification | Construction firms extend into scheduled power distribution and cooling servicing as 2015-2019 commissioning waves enter refresh cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included data center development executives at hyperscale cloud providers, construction project directors at integrated design-build firms, provincial energy regulator officials, and colocation operator procurement leads. Secondary validation drew from Independent Electricity System Operator interconnection filings, Canadian Environmental Assessment Agency project documentation, Hydro-Québec surplus baseload capacity disclosures, and Uptime Institute Tier certification records. Bottom-up project pipeline aggregation and top-down provincial capacity forecasts were triangulated against capital expenditure disclosures.
Historical reference periods anchored the projection framework to commissioning waves from 2015-2019 entering refresh cycles. The analytical framework modeled deployment scale, end-user vertical, service type, and provincial regulatory cluster across the projection horizon. CAGRs were derived from segment-level build rate trajectories and renewable energy procurement integration timelines. Forecast inputs included hyperscale cloud provider expansion commitments, Health Canada refrigerant phase-down compliance deadlines, and interprovincial transmission constraint resolutions.
The model holds under sustained hyperscale cloud demand and stable copper pricing; deviation in Canadian Environmental Assessment Agency review timelines or Red Seal trades availability would shift capacity delivery schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Switzerland Data Center Construction Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Chennai Data Center Market